
Bank Of America Corp 8-K, filed Apr 18, 2023
Bank Of America Corp (BAC)
8-K
2023-04-18
For: 2023-04-18
View Original
Added on
April 05, 2026
About this 8-K
Bank Of America Corp filed this 8-K on April 18, 2023.
Items reported
- Item 2.02: Financial results
- Item 7.01: Regulation FD disclosure
- Item 9.01: Financial statements and exhibits
As filed with the Securities and Exchange Commission on April 18, 2023
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
(Address of principal executive offices)
(704 ) 386-5681
(Registrant’s telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 1 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 2 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 4 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 5 | ||||||||
| November 28, 2031 of BofA Finance LLC (and the guarantee of the | ||||||||
| Registrant with respect thereto) | ||||||||
| Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR 230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR 240.12b-2). | |||||
| Emerging growth company | |||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ☐ | ||||
ITEM 2.02. RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
On April 18, 2023 , Bank of America Corporation (the “Corporation”) announced financial results for the first quarter ended March 31, 2023, reporting first quarter net income of $8.2 billion, or $0.94 per diluted share. A copy of the press release announcing the Corporation’s results for the first quarter ended March 31, 2023 (the “Press Release”) is attached hereto as Exhibit 99.1 and is incorporated by reference in this Item 2.02. The Press Release is available on the Corporation’s website.
The information provided in Item 2.02 of this report, including Exhibit 99.1, shall be deemed to be “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended.
ITEM 7.01. REGULATION FD DISCLOSURE.
On April 18, 2023 , the Corporation will hold an investor conference call and webcast to discuss financial results for the first quarter ended March 31, 2023, including the Press Release and other matters relating to the Corporation.
The Corporation has also made available on its website presentation materials containing certain historical and forward-looking information relating to the Corporation (the “Presentation Materials”) and materials that contain additional information about the Corporation’s financial results for the first quarter ended March 31, 2023 (the “Supplemental Information”). The Presentation Materials and the Supplemental Information are furnished herewith as Exhibit 99.2 and Exhibit 99.3, respectively, and are incorporated by reference in this Item 7.01. All information in Exhibits 99.2 and 99.3 is presented as of the particular date or dates referenced therein, and the Corporation does not undertake any obligation to, and disclaims any duty to, update any of the information provided.
The information provided in Item 7.01 of this report, including Exhibits 99.2 and 99.3, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall the information or Exhibits 99.2 or 99.3 be deemed incorporated by reference in any filings under the Securities Act of 1933, as amended.
ITEM 9.01. FINANCIAL STATEMENTS AND EXHIBITS.
(d) Exhibits.
Exhibit 99.1 is filed herewith. Exhibits 99.2 and 99.3 are furnished herewith.
| EXHIBIT NO. | DESCRIPTION OF EXHIBIT | |||||||
| 104 | Cover Page Interactive Data File (embedded in the cover page formatted in Inline XBRL) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the Corporation has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| BANK OF AMERICA CORPORATION | ||||||||
| By: | /s/ Rudolf A. Bless | |||||||
| Rudolf A. Bless | ||||||||
| Chief Accounting Officer | ||||||||
Dated: April 18, 2023
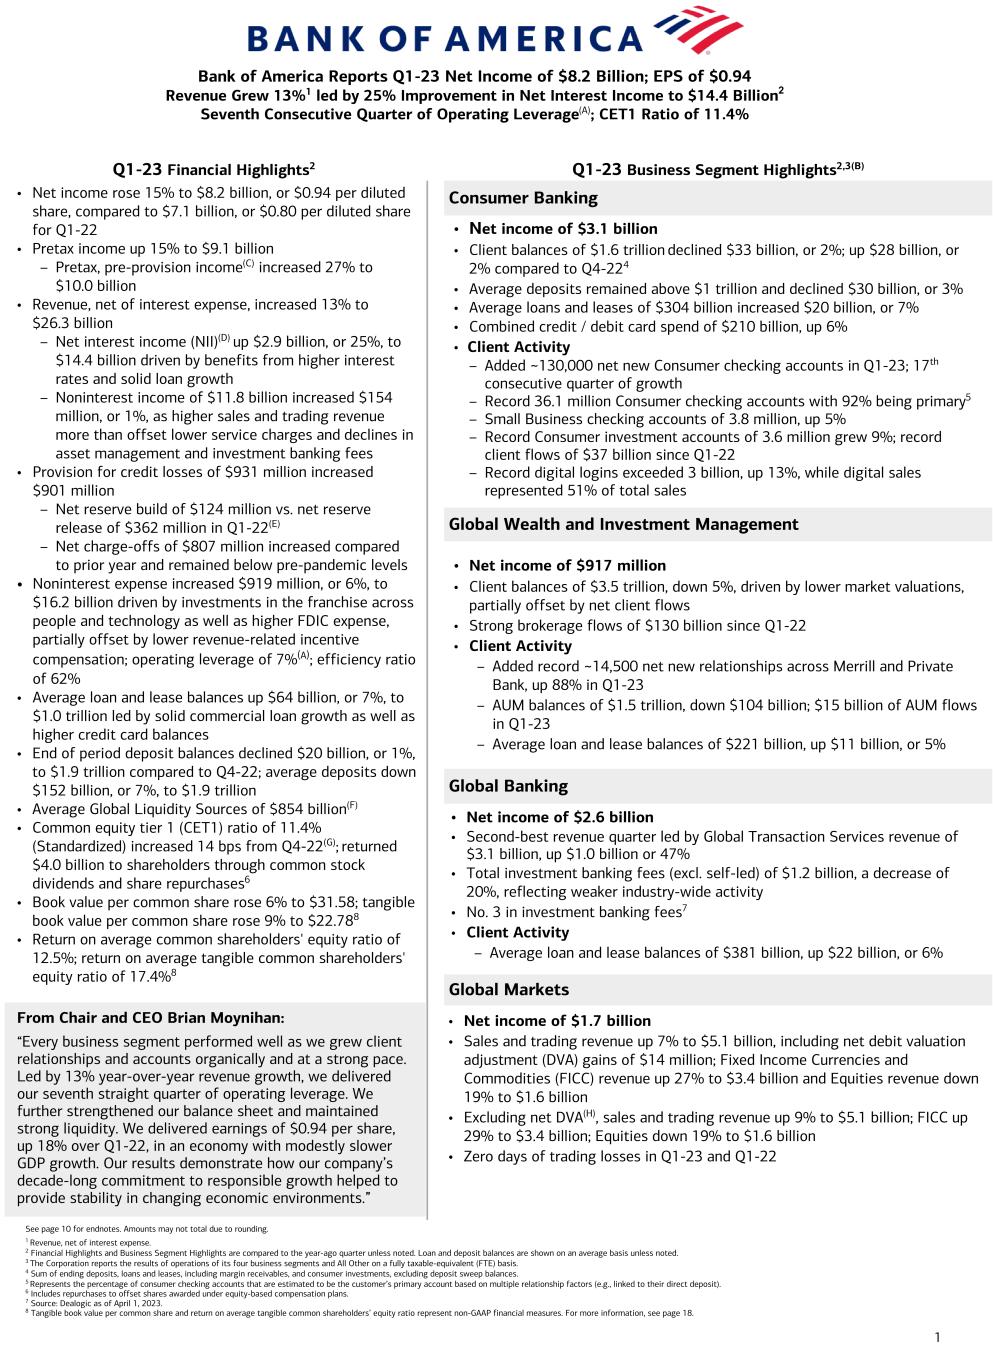
1 Q1-23 Financial Highlights2 Q1-23 Business Segment Highlights2,3(B) Consumer Banking Global Wealth and Investment Management Global Banking Global Markets See page 10 for endnotes. Amounts may not total due to rounding. 1 Revenue, net of interest expense. 2 Financial Highlights and Business Segment Highlights are compared to the year-ago quarter unless noted. Loan and deposit balances are shown on an average basis unless noted. 3 The Corporation reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis. 4 Sum of ending deposits, loans and leases, including margin receivables, and consumer investments, excluding deposit sweep balances. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 Includes repurchases to offset shares awarded under equity-based compensation plans. 7 Source: Dealogic as of April 1, 2023. 8 Tangible book value per common share and return on average tangible common shareholders’ equity ratio represent non-GAAP financial measures. For more information, see page 18. • Net income rose 15% to $8.2 billion, or $0.94 per diluted share, compared to $7.1 billion, or $0.80 per diluted share for Q1-22 • Pretax income up 15% to $9.1 billion – Pretax, pre-provision income(C) increased 27% to $10.0 billion • Revenue, net of interest expense, increased 13% to $26.3 billion – Net interest income (NII)(D) up $2.9 billion, or 25%, to $14.4 billion driven by benefits from higher interest rates and solid loan growth – Noninterest income of $11.8 billion increased $154 million, or 1%, as higher sales and trading revenue more than offset lower service charges and declines in asset management and investment banking fees • Provision for credit losses of $931 million increased $901 million – Net reserve build of $124 million vs. net reserve release of $362 million in Q1-22(E) – Net charge-offs of $807 million increased compared to prior year and remained below pre-pandemic levels • Noninterest expense increased $919 million, or 6%, to $16.2 billion driven by investments in the franchise across people and technology as well as higher FDIC expense, partially offset by lower revenue-related incentive compensation; operating leverage of 7%(A); efficiency ratio of 62% • Average loan and lease balances up $64 billion, or 7%, to $1.0 trillion led by solid commercial loan growth as well as higher credit card balances • End of period deposit balances declined $20 billion, or 1%, to $1.9 trillion compared to Q4-22; average deposits down $152 billion, or 7%, to $1.9 trillion • Average Global Liquidity Sources of $854 billion(F) • Common equity tier 1 (CET1) ratio of 11.4% (Standardized) increased 14 bps from Q4-22(G); returned $4.0 billion to shareholders through common stock dividends and share repurchases6 • Book value per common share rose 6% to $31.58; tangible book value per common share rose 9% to $22.788 • Return on average common shareholders' equity ratio of 12.5%; return on average tangible common shareholders' equity ratio of 17.4%8 • Net income of $1.7 billion • Sales and trading revenue up 7% to $5.1 billion, including net debit valuation adjustment (DVA) gains of $14 million; Fixed Income Currencies and Commodities (FICC) revenue up 27% to $3.4 billion and Equities revenue down 19% to $1.6 billion • Excluding net DVA(H), sales and trading revenue up 9% to $5.1 billion; FICC up 29% to $3.4 billion; Equities down 19% to $1.6 billion • Zero days of trading losses in Q1-23 and Q1-22 From Chair and CEO Brian Moynihan: “Every business segment performed well as we grew client relationships and accounts organically and at a strong pace. Led by 13% year-over-year revenue growth, we delivered our seventh straight quarter of operating leverage. We further strengthened our balance sheet and maintained strong liquidity. We delivered earnings of $0.94 per share, up 18% over Q1-22, in an economy with modestly slower GDP growth. Our results demonstrate how our company’s decade-long commitment to responsible growth helped to provide stability in changing economic environments.” • Net income of $917 million • Client balances of $3.5 trillion, down 5%, driven by lower market valuations, partially offset by net client flows • Strong brokerage flows of $130 billion since Q1-22 • Client Activity – Added record ~14,500 net new relationships across Merrill and Private Bank, up 88% in Q1-23 – AUM balances of $1.5 trillion, down $104 billion; $15 billion of AUM flows in Q1-23 – Average loan and lease balances of $221 billion, up $11 billion, or 5% • Net income of $2.6 billion • Second-best revenue quarter led by Global Transaction Services revenue of $3.1 billion, up $1.0 billion or 47% • Total investment banking fees (excl. self-led) of $1.2 billion, a decrease of 20%, reflecting weaker industry-wide activity • No. 3 in investment banking fees7 • Client Activity – Average loan and lease balances of $381 billion, up $22 billion, or 6% • Net income of $3.1 billion • Client balances of $1.6 trillion declined $33 billion, or 2%; up $28 billion, or 2% compared to Q4-224 • Average deposits remained above $1 trillion and declined $30 billion, or 3% • Average loans and leases of $304 billion increased $20 billion, or 7% • Combined credit / debit card spend of $210 billion, up 6% • Client Activity – Added ~130,000 net new Consumer checking accounts in Q1-23; 17th consecutive quarter of growth – Record 36.1 million Consumer checking accounts with 92% being primary5 – Small Business checking accounts of 3.8 million, up 5% – Record Consumer investment accounts of 3.6 million grew 9%; record client flows of $37 billion since Q1-22 – Record digital logins exceeded 3 billion, up 13%, while digital sales represented 51% of total sales Bank of America Reports Q1-23 Net Income of $8.2 Billion; EPS of $0.94 Revenue Grew 13%1 led by 25% Improvement in Net Interest Income to $14.4 Billion2 Seventh Consecutive Quarter of Operating Leverage(A); CET1 Ratio of 11.4%

2 Bank of America Financial Highlights Three Months Ended ($ in billions, except per share data) 3/31/2023 12/31/2022 3/31/2022 Total revenue, net of interest expense $26.3 $24.5 $23.2 Provision for credit losses 0.9 1.1 — Noninterest expense 16.2 15.5 15.3 Pretax income 9.1 7.9 7.9 Pretax, pre-provision income1(C) 10.0 9.0 7.9 Income tax expense 0.9 0.8 0.8 Net Income 8.2 7.1 7.1 Diluted earnings per share $0.94 $0.85 $0.80 1 Pretax, pre-provision income represents a non-GAAP financial measure. For more information, see page 18. From Chief Financial Officer Alastair Borthwick: “The value of responsible growth is evidenced again in our first quarter financial performance with 15% net income growth compared to Q1-22. Results were strong despite a challenging economic environment with market and banking sector volatility. Revenue growth reflected strong net interest income improvement coupled with one of our best quarters of sales and trading. Net interest income increased $2.9 billion, or 25%, versus the year-ago quarter driven by higher rates along with loan growth, supported by our longstanding, deepening relationships with our customers and clients. "Asset quality remained strong with net charge-offs, while normalizing, still below pre-pandemic levels. We maintained strong liquidity, ending the quarter with $904 billion of Global Liquidity Sources. Regulatory capital improved to $184 billion, and our CET1 ratio is nearly 100 basis points above our current minimum requirements. Capital strength allowed us to return $4 billion back to shareholders, and we continued to invest in our people and businesses.” Common Equity Tier 1 Capital $169.9 $171.8 $175.6 $180.1 $184.4 10.4% 10.5% 11.0% 11.2% 11.4% Common Equity Tier 1 capital Common Equity Tier 1 capital ratio Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Net Income $7.1 $6.2 $7.1 $7.1 $8.2 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Spotlight on Net Income and Common Equity Tier 1 Capital ($B) 1 Common equity tier 1 capital ratio under the Standardized approach. 1

3 Consumer Banking1,2 Financial Results Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Total revenue2 $10,706 $10,782 $8,813 Provision for credit losses 1,089 944 (52) Noninterest expense 5,473 5,100 4,921 Pretax income 4,144 4,738 3,944 Income tax expense 1,036 1,161 966 Net income $3,108 $3,577 $2,978 Business Highlights(B) Three months ended ($ in billions) 3/31/2023 12/31/2022 3/31/2022 Average deposits $1,026.2 $1,047.1 $1,056.1 Average loans and leases 303.8 300.4 284.1 Consumer investment assets (EOP)3 354.9 319.6 357.6 Active mobile banking users (MM) 36.3 35.5 33.6 Number of financial centers 3,892 3,913 4,056 Efficiency ratio 51 % 47 % 56 % Return on average allocated capital 30 35 30 Total Consumer Credit Card4 Average credit card outstanding balances $91.8 $89.6 $78.4 Total credit/debit spend 209.9 223.0 198.5 Risk-adjusted margin 8.7 % 9.9 % 10.4 % 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. 3 Consumer investment assets includes client brokerage assets, deposit sweep balances and AUM in Consumer Banking. 4 The Consumer credit card portfolio includes Consumer Banking and GWIM. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 As of February 2023. Includes clients in Consumer, Small Business and GWIM. 7 Household adoption represents households with consumer bank login activities in a 90-day period, as of February 2023. • Net income of $3.1 billion increased 4%, driven by strong revenue growth and continued investments in the business – Pretax income of $4.1 billion increased 5% – Pretax, pre-provision income(C) of $5.2 billion increased 34% – 8th consecutive quarter of operating leverage(A); efficiency ratio improved to 51% • Revenue of $10.7 billion improved 21%, due to increased NII driven by higher interest rates and loan balances, partially offset by the impact of reduced customer non-sufficient funds and overdraft fees • Provision for credit losses of $1.1 billion increased $1.1 billion vs. a benefit of $52 million – Net reserve build of $360 million(E), driven primarily by higher-than-expected credit card balances – Net charge-offs of $729 million increased $313 million driven primarily by credit card • Noninterest expense of $5.5 billion increased 11%, driven primarily by continued investments in people and technology Business Highlights1,4(B) • Average deposits remained above $1 trillion, and decreased $30 billion, or 3% – 57% of deposits in checking accounts; 92% primary accounts5 • Average loans and leases of $304 billion increased $20 billion, or 7% • Combined credit / debit card spend up $11 billion, or 6%, with both credit and debit up 6% • Consumer investment assets3 of $355 billion declined $3 billion, or 1%, driven by lower market valuations, partially offset by a record $37 billion of client flows from new and existing clients – Record 3.6 million consumer investment accounts, up 9% • 10.3 million Total clients6 enrolled in Preferred Rewards, up 8%, with 99% annualized retention rate Digital Usage Continued to Grow1 • Record 73% of overall households7 actively using digital platforms • Record 45 million active digital banking users, up 6% or ~2.7 million • ~1.8 million digital sales, up 4% • Record 3.1 billion digital logins, up 13% • 19.6 million active Zelle® users sent and received 275 million transfers worth $84 billion, both up 29% YoY • Clients booked ~892,000 digital appointments Continued Business Leadership • No. 1 in estimated U.S. Retail Deposits(a) • No. 1 Online Banking and Mobile Banking Functionality(b) • No. 1 Small Business Lender(c) • Best Bank in the U.S.(d) • Best Consumer Digital Bank in the U.S.(e) • Best Bank in the U.S. for Small and Medium Enterprises(f) • Certified by J.D. Power for Outstanding Client satisfaction with Customer Financial Health Support – Banking & Payments(g) See page 11 for Business Leadership sources.
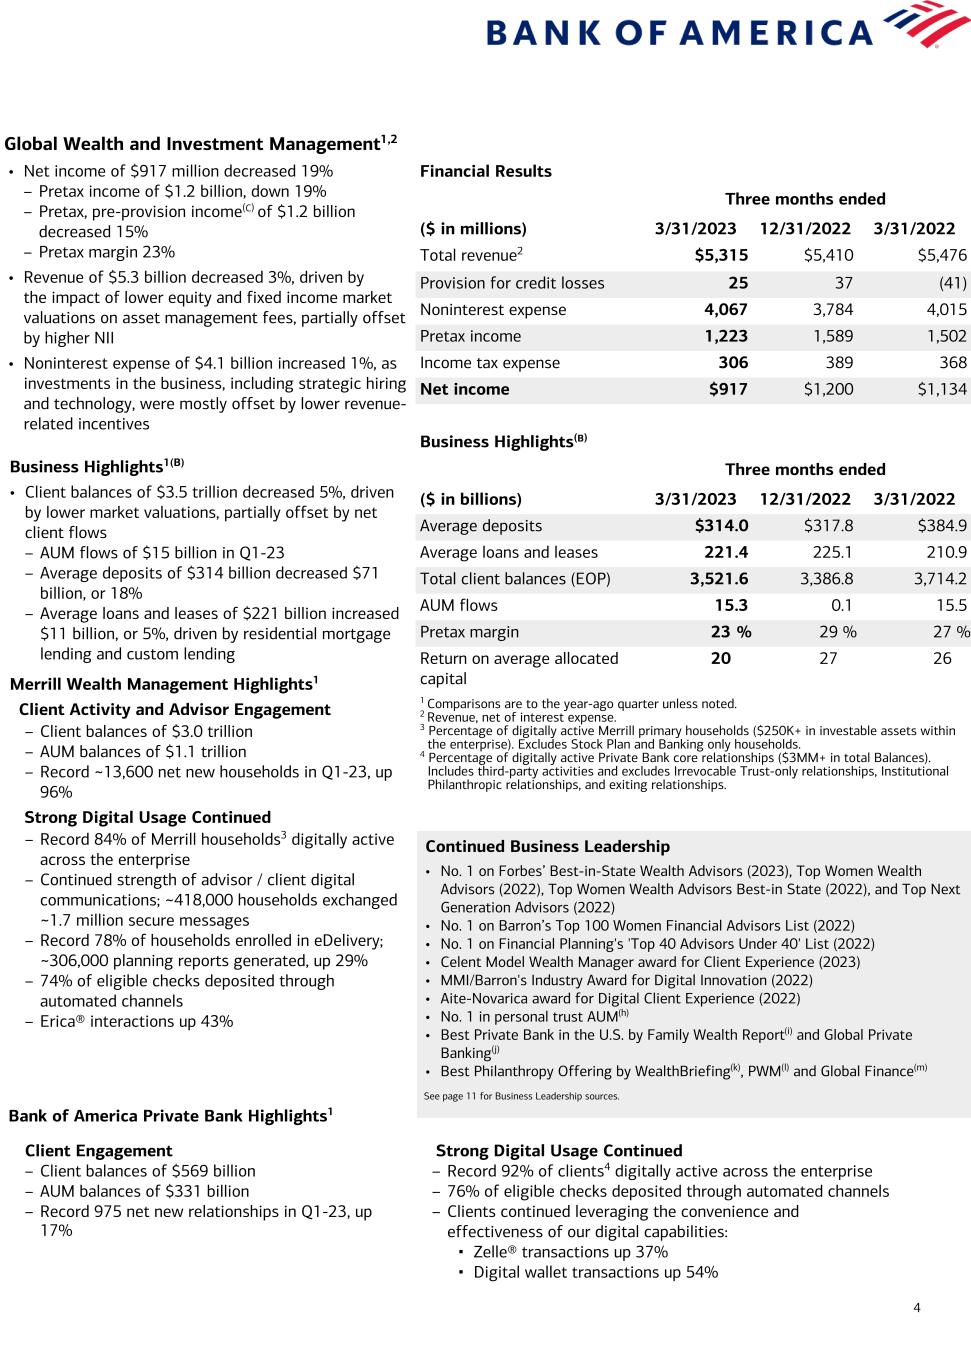
4 Global Wealth and Investment Management1,2 Financial Results Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Total revenue2 $5,315 $5,410 $5,476 Provision for credit losses 25 37 (41) Noninterest expense 4,067 3,784 4,015 Pretax income 1,223 1,589 1,502 Income tax expense 306 389 368 Net income $917 $1,200 $1,134 Business Highlights(B) Three months ended ($ in billions) 3/31/2023 12/31/2022 3/31/2022 Average deposits $314.0 $317.8 $384.9 Average loans and leases 221.4 225.1 210.9 Total client balances (EOP) 3,521.6 3,386.8 3,714.2 AUM flows 15.3 0.1 15.5 Pretax margin 23 % 29 % 27 % Return on average allocated capital 20 27 26 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. 3 Percentage of digitally active Merrill primary households ($250K+ in investable assets within the enterprise). Excludes Stock Plan and Banking only households. 4 Percentage of digitally active Private Bank core relationships ($3MM+ in total Balances). Includes third-party activities and excludes Irrevocable Trust-only relationships, Institutional Philanthropic relationships, and exiting relationships. Continued Business Leadership • No. 1 on Forbes’ Best-in-State Wealth Advisors (2023), Top Women Wealth Advisors (2022), Top Women Wealth Advisors Best-in State (2022), and Top Next Generation Advisors (2022) • No. 1 on Barron’s Top 100 Women Financial Advisors List (2022) • No. 1 on Financial Planning's 'Top 40 Advisors Under 40' List (2022) • Celent Model Wealth Manager award for Client Experience (2023) • MMI/Barron's Industry Award for Digital Innovation (2022) • Aite-Novarica award for Digital Client Experience (2022) • No. 1 in personal trust AUM(h) • Best Private Bank in the U.S. by Family Wealth Report(i) and Global Private Banking(j) • Best Philanthropy Offering by WealthBriefing(k), PWM(l) and Global Finance(m) See page 11 for Business Leadership sources. • Net income of $917 million decreased 19% – Pretax income of $1.2 billion, down 19% – Pretax, pre-provision income(C) of $1.2 billion decreased 15% – Pretax margin 23% • Revenue of $5.3 billion decreased 3%, driven by the impact of lower equity and fixed income market valuations on asset management fees, partially offset by higher NII • Noninterest expense of $4.1 billion increased 1%, as investments in the business, including strategic hiring and technology, were mostly offset by lower revenue- related incentives Business Highlights1(B) • Client balances of $3.5 trillion decreased 5%, driven by lower market valuations, partially offset by net client flows – AUM flows of $15 billion in Q1-23 – Average deposits of $314 billion decreased $71 billion, or 18% – Average loans and leases of $221 billion increased $11 billion, or 5%, driven by residential mortgage lending and custom lending Merrill Wealth Management Highlights1 Client Activity and Advisor Engagement – Client balances of $3.0 trillion – AUM balances of $1.1 trillion – Record ~13,600 net new households in Q1-23, up 96% Strong Digital Usage Continued – Record 84% of Merrill households3 digitally active across the enterprise – Continued strength of advisor / client digital communications; ~418,000 households exchanged ~1.7 million secure messages – Record 78% of households enrolled in eDelivery; ~306,000 planning reports generated, up 29% – 74% of eligible checks deposited through automated channels – Erica® interactions up 43% Client Engagement – Client balances of $569 billion – AUM balances of $331 billion – Record 975 net new relationships in Q1-23, up 17% Bank of America Private Bank Highlights1 Strong Digital Usage Continued – Record 92% of clients4 digitally active across the enterprise – 76% of eligible checks deposited through automated channels – Clients continued leveraging the convenience and effectiveness of our digital capabilities: ▪ Zelle® transactions up 37% ▪ Digital wallet transactions up 54%

5 Global Banking1,2,3 Financial Results Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Total revenue2,3 $6,203 $6,438 $5,194 Provision for credit losses (237) 149 165 Noninterest expense 2,940 2,833 2,683 Pretax income 3,500 3,456 2,346 Income tax expense 945 916 622 Net income $2,555 $2,540 $1,724 Business Highlights2(B) Three months ended ($ in billions) 3/31/2023 12/31/2022 3/31/2022 Average deposits $492.6 $503.5 $539.9 Average loans and leases 381.0 380.4 358.8 Total Corp. IB fees (excl. self- led)2 1.2 1.1 1.5 Global Banking IB fees2 0.7 0.7 0.9 Business Lending revenue 2.3 2.7 2.1 Global Transaction Services revenue 3.1 3.1 2.1 Efficiency ratio 47 % 44 % 52 % Return on average allocated capital 21 23 16 1 Comparisons are to the year-ago quarter unless noted. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Revenue, net of interest expense. • Net income of $2.6 billion increased 48% – Pretax income of $3.5 billion, up 49% – Pretax, pre-provision income(C) of $3.3 billion increased 30% • Revenue of $6.2 billion increased 19%, driven primarily by higher NII from the benefit of higher interest rates, partially offset by lower investment banking fees, lower treasury service charges due to higher earnings credit rates, and lower revenue from environmental, social and governance (ESG) investment activities • Provision for credit losses reflected a benefit of $237 million, driven primarily by an improved macroeconomic outlook, and decreased $402 million from Q1-22 as the prior year was impacted by reserve builds(E) • Noninterest expense of $2.9 billion increased 10%, primarily reflecting continued investments in the business, including strategic hiring in 2022 Continued Business Leadership • Global Most Innovative Financial Institution – 2022(m) • World's Best Bank, North America’s Best Bank for Small to Medium-sized Enterprises, and Best Bank in the US(n) • Best Bank for Payment & Collections in North America(o) • Model Bank award for Product Innovation in Cash Management – 2023, for CashPro Mobile, CashPro Forecasting, and CashPro API(p) • World’s Best Bank for Payments and Treasury and North America’s Best Bank for Transaction Services(n) • 2022 Quality, Share and Excellence Awards for U.S. Large Corporate Banking and Cash Management(q) • Relationships with 73% of the Global Fortune 500; 95% of the U.S. Fortune 1,000 (2022) See page 11 for Business Leadership sources. Strong Digital Usage Continued1 • 76% digitally active clients across commercial, corporate, and business banking clients (CashPro and BA360 platforms) (as of February 2023) • Record quarterly CashPro App active users increased 23% and record sign-ins increased 52% • Quarterly CashPro App Payment Approvals value was $179 billion, increased 31% • Quarterly percentage of eligible credit monitoring documents uploaded digitally at 42%, increased 758 bps (as of February 2023) Business Highlights1,2(B) • Total investment banking fees (excl. self-led) of $1.2 billion decreased $294 million, or 20% • Average deposits of $493 billion decreased $47 billion, or 9% • Average loans and leases of $381 billion increased $22 billion, or 6%

6 Global Markets1,2,3,6 Financial Results Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Total revenue2,3 $5,626 $3,861 $5,292 Net DVA4 14 (193) 69 Total revenue (excl. net DVA)2,3,4 $5,612 $4,054 $5,223 Provision for credit losses (53) 4 5 Noninterest expense 3,351 3,171 3,117 Pretax income 2,328 686 2,170 Income tax expense 640 182 575 Net income $1,688 $504 $1,595 Net income (excl. net DVA)4 $1,677 $650 $1,543 Business Highlights2(B) Three months ended ($ in billions) 3/31/2023 12/31/2022 3/31/2022 Average total assets $870.0 $857.3 $858.7 Average trading-related assets 626.0 608.5 596.2 Average loans and leases 125.0 123.0 108.6 Sales and trading revenue2 5.1 3.5 4.7 Sales and trading revenue (excl. net DVA)2,4(H) 5.1 3.7 4.7 Global Markets IB fees2 0.5 0.3 0.6 Efficiency ratio 60 % 82 % 59 % Return on average allocated capital 15 5 15 1 Comparisons are to the year-ago quarter unless noted. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Revenue, net of interest expense. 4 Revenue and net income, excluding net DVA, are non-GAAP financial measures. See endnote H on page 10 for more information. 5 VaR model uses a historical simulation approach based on three years of historical data and an expected shortfall methodology equivalent to a 99% confidence level. Average VaR was $109MM, $117MM and $79MM for Q1-23, Q4-22 and Q1-22, respectively. 6 The explanations for current period-over-period changes for Global Markets are the same for amounts including and excluding net DVA. • Net income of $1.7 billion increased $93 million, or 6% – Excluding net DVA, net income of $1.7 billion increased 9%4 • Revenue of $5.6 billion increased 6%, driven primarily by higher sales and trading revenue, partially offset by lower investment banking fees • Noninterest expense of $3.4 billion increased 8%, driven by investments in the business, including people and technology • Average VaR of $109 million5 Business Highlights1,2,6(B) • Sales and trading revenue of $5.1 billion increased 7% – FICC revenue increased 27% to $3.4 billion, driven primarily by improved performance across mortgage, credit and municipal products, and increased secured financing activity for clients – Equities revenue decreased 19% to $1.6 billion, driven by weaker trading performance and lower client activity in derivatives and cash • Excluding net DVA, sales and trading revenue increased 9% to $5.1 billion(H) – FICC revenue of $3.4 billion increased 29% – Equities revenue of $1.6 billion decreased 19% Additional Highlights • 700+ research analysts covering nearly 3,600 companies, 1,200+ corporate bond issuers across 55+ economies and 25 industries Continued Business Leadership • Americas Derivatives House of the Year and Americas House of the Year for Equity Derivatives, FX Derivatives, Interest Rate Derivatives, and Commodities Derivatives(r) • Commodity Derivatives House and Americas ESG Financing House(s) • Interest Rate Derivatives House of the Year(t) • Global Leader for Sustainable Project Finance(m) • Most Sustainable Banks in North America(u) • Most Impressive Corporate Bond House in Dollars(r) • No. 1 All-America Sales Team in Equities Idea Generation(v) • No. 1 Municipal Bonds Underwriter(w) • No. 2 Global Research Firm(v) See page 11 for Business Leadership sources.

7 All Other1,2 Financial Results Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Total revenue2 $(1,458) $(1,836) $(1,441) Provision for credit losses 107 (42) (47) Noninterest expense 407 655 583 Pretax loss (1,972) (2,449) (1,977) Income tax expense (benefit) (1,865) (1,760) (1,613) Net income (loss) $(107) $(689) $(364) 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. Note: All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments. • Net loss of $107 million included a $220 million pretax loss on sale of available-for-sale (AFS) debt securities • Total corporate effective tax rate (ETR) for the quarter was 10%, which included certain discrete tax benefits – Excluding these discrete tax benefits and recurring ESG tax credit benefits, the ETR would have been approximately 26%

8 Credit Quality1 Highlights Three months ended ($ in millions) 3/31/2023 12/31/2022 3/31/2022 Provision for credit losses $931 $1,092 $30 Net charge-offs 807 689 392 Net charge-off ratio2 0.32 % 0.26 % 0.16 % At period-end Nonperforming loans and leases $3,918 $3,808 $4,625 Nonperforming loans and leases ratio 0.38 % 0.37 % 0.47 % Allowance for loan and lease losses $12,514 $12,682 $12,104 Allowance for loan and lease losses ratio3 1.20 % 1.22 % 1.23 % 1 Comparisons are to the year-ago quarter unless noted. 2 Net charge-off ratio is calculated as annualized net charge-offs divided by average outstanding loans and leases during the period. 3 Allowance for loan and lease losses ratio is calculated as allowance for loan and lease losses divided by loans and leases outstanding at the end of the period. Note: Ratios do not include loans accounted for under the fair value option. Charge-offs • Total net charge-offs of $807 million increased $118 million, or 17%, from Q4-22 – Consumer net charge-offs of $653 million increased $122 million from Q4-22, driven primarily by higher credit card losses – Credit card loss rate of 2.21% in Q1-23 vs. 1.71% in Q4-22, and, pre-pandemic, 3.03% in Q4-19 – Commercial net charge-offs of $154 million decreased $4 million from Q4-22 • Net charge-off ratio2 of 0.32% increased 0.06% from Q4-22 and remained below pre-pandemic levels Provision for credit losses • Provision for credit losses of $931 million – Net reserve build of $124 million in Q1-23(E), driven primarily by Consumer due to higher-than- expected credit card balances, partially offset by an improved macroeconomic outlook that primarily benefited our Commercial portfolio Allowance for credit losses • Allowance for loan and lease losses of $12.5 billion decreased $168 million from Q4-22 and represented 1.20% of total loans and leases3 – Total allowance of $14.0 billion included $1.4 billion for unfunded commitments and decreased $271 million from Q4-22 • Includes a January 1, 2023 $243 million reduction for the accounting change to remove the recognition and measurement guidance on troubled debt restructurings • Nonperforming loans (NPL) increased $110 million from Q4-22 to $3.9 billion – 60% of Consumer NPLs are contractually current • Commercial reservable criticized utilized exposure of $19.8 billion increased $515 million from Q4-22

9 Balance Sheet, Liquidity and Capital Highlights ($ in billions except per share data, end of period, unless otherwise noted)(B) Three months ended 3/31/2023 12/31/2022 3/31/2022 Ending Balance Sheet Total assets $3,194.7 $3,051.4 $3,238.2 Total loans and leases 1,046.4 1,045.7 993.1 Total loans and leases in business segments (excluding All Other) 1,036.6 1,035.5 978.1 Total deposits 1,910.4 1,930.3 2,072.4 Average Balance Sheet Average total assets $3,096.1 $3,074.3 $3,207.7 Average loans and leases 1,041.4 1,039.2 977.8 Average deposits 1,893.6 1,925.5 2,045.8 Funding and Liquidity Long-term debt $283.9 $276.0 $278.7 Global Liquidity Sources, average(F) 854 868 1,109 Equity Common shareholders’ equity $251.8 $244.8 $239.5 Common equity ratio 7.9 % 8.0 % 7.4 % Tangible common shareholders’ equity1 $181.6 $174.6 $169.3 Tangible common equity ratio1 5.8 % 5.9 % 5.3 % Per Share Data Common shares outstanding (in billions) 7.97 8.00 8.06 Book value per common share $31.58 $30.61 $29.70 Tangible book value per common share1 22.78 21.83 20.99 Regulatory Capital(G) CET1 capital $184.4 $180.1 $169.9 Standardized approach Risk-weighted assets $1,623 $1,605 $1,639 CET1 ratio 11.4 % 11.2 % 10.4 % Advanced approaches Risk-weighted assets $1,429 $1,411 $1,416 CET1 ratio 12.9 % 12.8 % 12.0 % Supplementary leverage Supplementary leverage ratio (SLR) 6.0 % 5.9 % 5.4 % 1 Represents a non-GAAP financial measure. For reconciliation, see page 18.

10 Endnotes Three months ended (Dollars in millions) 3/31/2023 12/31/2022 3/31/2022 Sales and trading revenue Fixed-income, currencies and commodities $ 3,440 $ 2,157 $ 2,708 Equities 1,627 1,368 2,011 Total sales and trading revenue $ 5,067 $ 3,525 $ 4,719 Sales and trading revenue, excluding net debit valuation adjustment1 Fixed-income, currencies and commodities $ 3,429 $ 2,343 $ 2,648 Equities 1,624 1,375 2,002 Total sales and trading revenue, excluding net debit valuation adjustment $ 5,053 $ 3,718 $ 4,650 A Operating leverage is calculated as the year-over-year percentage change in revenue, net of interest expense, less the percentage change in noninterest expense. B We present certain key financial and nonfinancial performance indicators (KPIs) that management uses when assessing consolidated and/or segment results. We believe this information is useful because it provides management and investors with information about underlying operational performance and trends. KPIs are presented in Balance Sheet, Liquidity and Capital Highlights and on the Segment pages for each segment. C Pretax, pre-provision income (PTPI) at the consolidated level, as well as at the segment level, is a non-GAAP financial measure calculated by adjusting the respective entity’s pretax income to add back provision for credit losses. Management believes that PTPI (both at the consolidated and segment level) is a useful financial measure as it enables an assessment of the Company’s ability to generate earnings to cover credit losses through a credit cycle and provides an additional basis for comparing the Company's results of operations between periods by isolating the impact of provision for credit losses, which can vary significantly between periods. For Reconciliations to GAAP financial measures, see page 18 for Total company and below for segments. 1 For the three months ended March 31, 2023, December 31, 2022 and March 31, 2022, net DVA gains (losses) were $14 million, $(193) million and $69 million, FICC net DVA gains (losses) were $11 million, $(186) million and $60 million, and Equities net DVA gains (losses) were $3 million, $(7) million and $9 million, respectively. (Dollars in millions) First Quarter 2023 Consumer Banking GWIM Global Banking Pretax income $ 4,144 $ 1,223 $ 3,500 Provision for credit losses 1,089 25 (237) Pretax, pre-provision income $ 5,233 $ 1,248 $ 3,263 Fourth Quarter 2022 Consumer Banking GWIM Global Banking Pretax income $ 4,738 $ 1,589 $ 3,456 Provision for credit losses 944 37 149 Pretax, pre-provision income $ 5,682 $ 1,626 $ 3,605 First Quarter 2022 Consumer Banking GWIM Global Banking Pretax income $ 3,944 $ 1,502 $ 2,346 Provision for credit losses (52) (41) 165 Pretax, pre-provision income $ 3,892 $ 1,461 $ 2,511 D We also measure NII on an FTE basis, which is a non-GAAP financial measure. FTE basis is a performance measure used in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. We believe that this presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practice. NII on an FTE basis was $14.6 billion, $14.8 billion and $11.7 billion for the three months ended March 31, 2023, December 31, 2022 and March 31, 2022, respectively. The FTE adjustment was $134 million, $123 million and $106 million for the three months ended March 31, 2023, December 31, 2022 and March 31, 2022, respectively. E Reserve Build (or Release) is calculated by subtracting net charge-offs for the period from the provision for credit losses recognized in that period. The period-end allowance, or reserve, for credit losses reflects the beginning of the period allowance adjusted for net charge-offs recorded in that period plus the provision for credit losses and other valuation accounts recognized in that period. F Global Liquidity Sources (GLS) include cash and high-quality, liquid, unencumbered securities, inclusive of U.S. government securities, U.S. agency securities, U.S. agency mortgage-backed securities, and a select group of non-U.S. government and supranational securities, and other investment-grade securities, and are readily available to meet funding requirements as they arise. It does not include Federal Reserve Discount Window or Federal Home Loan Bank borrowing capacity. Transfers of liquidity among legal entities may be subject to certain regulatory and other restrictions. GRegulatR Regulatory capital ratios at March 31, 2023 are preliminary. The Corporation reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was the Common equity tier 1 ratio under the Standardized approach for all periods presented. H The below table includes Global Markets sales and trading revenue, excluding net DVA, which is a non-GAAP financial measure. We believe that the presentation of measures that exclude this item is useful because such measures provide additional information to assess the underlying operational performance and trends of our businesses and to allow better comparison of period-to-period operating performance.

11 (a) Estimated U.S. retail deposits based on June 30, 2022 FDIC deposit data. (b) Javelin 2022 Online and Mobile Banking Scorecards. (c) FDIC, 4Q22. (d) Global Finance, May 2022. (e) Global Finance, August 2022. (f) Global Finance, December 2022. (g) J.D. Power 2023 Financial Health Support CertificationSM is based on exceeding customer experience benchmarks using client surveys and a best practices verification. For more information, visit jdpower.com/awards. (h) Industry Q4-22 FDIC call reports. (i) Family Wealth Report, 2022. (j) Global Private Banking, The Digital Banker, 2022. (k) WealthBriefing, 2022. (l) PWM, 2022. (m) Global Finance, 2022. (n) Euromoney, 2022. (o) Global Finance Treasury & Cash Management Awards, 2023. (p) Celent, 2023. (q) Greenwich, 2023. (r) GlobalCapital, 2022. (s) IFR, 2022. (t) Risk.net, 2022. (u) Capital Monitor, 2022. (v) Institutional Investor, 2022. (w) Refinitiv, 2023 YTD. Business Leadership Sources

12 Contact Information and Investor Conference Call Invitation Investor Call Information Chief Executive Officer Brian Moynihan and Chief Financial Officer Alastair Borthwick will discuss first-quarter 2023 financial results in a conference call at 8:30 a.m. ET today. The presentation and supporting materials can be accessed on the Bank of America Investor Relations website at https://investor.bankofamerica.com. For a listen-only connection to the conference call, dial 1.877.200.4456 (U.S.) or 1.785.424.1732 (international). The conference ID is 79795. Please dial in 10 minutes prior to the start of the call. Investors can access replays of the conference call by visiting the Investor Relations website or by calling 1.800.934.4850 (U.S.) or 1.402.220.1178 (international) from noon April 18 through 11:59 p.m. ET on April 28. Investors May Contact: Lee McEntire, Bank of America Phone: 1.980.388.6780 lee.mcentire@bofa.com Jonathan G. Blum, Bank of America (Fixed Income) Phone: 1.212.449.3112 jonathan.blum@bofa.com Bank of America Bank of America is one of the world’s leading financial institutions, serving individual consumers, small and middle-market businesses and large corporations with a full range of banking, investing, asset management and other financial and risk management products and services. The company provides unmatched convenience in the United States, serving approximately 68 million consumer and small business clients with approximately 3,900 retail financial centers, approximately 15,000 ATMs and award-winning digital banking with approximately 56 million verified digital users. Bank of America is a global leader in wealth management, corporate and investment banking and trading across a broad range of asset classes, serving corporations, governments, institutions and individuals around the world. Bank of America offers industry-leading support to approximately 3 million small business households through a suite of innovative, easy-to-use online products and services. The company serves clients through operations across the United States, its territories and more than 35 countries. Bank of America Corporation stock (NYSE: BAC) is listed on the New York Stock Exchange. Forward-Looking Statements Bank of America Corporation (the Corporation) and its management may make certain statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “intends,” “plans,” “goals,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements represent the Corporation’s current expectations, plans or forecasts of its future results, revenues, liquidity, provision for credit losses, expenses, efficiency ratio, capital measures, strategy, deposits, assets, and future business and economic conditions more generally, and other future matters. These statements are not guarantees of future results or performance and involve certain known and unknown risks, uncertainties and assumptions that are difficult to predict and are often beyond the Corporation’s control. Actual outcomes and results may differ materially from those expressed in, or implied by, any of these forward-looking statements. Reporters May Contact: Bill Halldin, Bank of America Phone: 1.916.724.0093 william.halldin@bofa.com Christopher Feeney, Bank of America Phone: 1.980.386.6794 christopher.feeney@bofa.com

13 You should not place undue reliance on any forward-looking statement and should consider the following uncertainties and risks, as well as the risks and uncertainties more fully discussed under Item 1A. Risk Factors of the Corporation’s 2022 Annual Report on Form 10-K and in any of the Corporation’s subsequent Securities and Exchange Commission filings: the Corporation’s potential judgments, orders, settlements, penalties, fines and reputational damage resulting from pending or future litigation and regulatory investigations, proceedings and enforcement actions, including as a result of our participation in and execution of government programs related to the Coronavirus Disease 2019 (COVID-19) pandemic, such as the processing of unemployment benefits for California and certain other states; the possibility that the Corporation's future liabilities may be in excess of its recorded liability and estimated range of possible loss for litigation, and regulatory and government actions; the possibility that the Corporation could face increased claims from one or more parties involved in mortgage securitizations; the Corporation’s ability to resolve representations and warranties repurchase and related claims; the risks related to the discontinuation of the London Interbank Offered Rate and other reference rates, including increased expenses and litigation and the effectiveness of hedging strategies; uncertainties about the financial stability and growth rates of non-U.S. jurisdictions, the risk that those jurisdictions may face difficulties servicing their sovereign debt, and related stresses on financial markets, currencies and trade, and the Corporation’s exposures to such risks, including direct, indirect and operational; the impact of U.S. and global interest rates, inflation, currency exchange rates, economic conditions, trade policies and tensions, including tariffs, and potential geopolitical instability; the impact of the interest rate, inflationary, macroeconomic, banking and regulatory environment on the Corporation’s assets, business, financial condition and results of operations; the impact of adverse developments affecting the U.S. or global banking industry, including bank failures and liquidity concerns, which could cause continued or worsening economic and market volatility, and regulatory responses thereto; the possibility that future credit losses may be higher than currently expected due to changes in economic assumptions, customer behavior, adverse developments with respect to U.S. or global economic conditions and other uncertainties, including the impact of supply chain disruptions, inflationary pressures and labor shortages on economic conditions and our business; potential losses related to the Corporation’s concentration of credit risk; the Corporation's ability to achieve its expense targets and expectations regarding revenue, net interest income, provision for credit losses, net charge-offs, effective tax rate, loan growth or other projections; adverse changes to the Corporation’s credit ratings from the major credit rating agencies; an inability to access capital markets or maintain deposits or borrowing costs; estimates of the fair value and other accounting values, subject to impairment assessments, of certain of the Corporation’s assets and liabilities; the estimated or actual impact of changes in accounting standards or assumptions in applying those standards; uncertainty regarding the content, timing and impact of regulatory capital and liquidity requirements; the impact of adverse changes to total loss-absorbing capacity requirements, stress capital buffer requirements and/or global systemically important bank surcharges; the potential impact of actions of the Board of Governors of the Federal Reserve System on the Corporation’s capital plans; the effect of changes in or interpretations of income tax laws and regulations; the impact of implementation and compliance with U.S. and international laws, regulations and regulatory interpretations, including, but not limited to, recovery and resolution planning requirements, Federal Deposit Insurance Corporation assessments, the Volcker Rule, fiduciary standards, derivatives regulations and the Coronavirus Aid, Relief, and Economic Security Act and any similar or related rules and regulations; a failure or disruption in or breach of the Corporation’s operational or security systems or infrastructure, or those of third parties, including as a result of cyber-attacks or campaigns; the risks related to the transition and physical impacts of climate change; our ability to achieve environmental, social and governance goals and commitments or the impact of any changes in the Corporation's sustainability strategy or commitments generally; the impact of any future federal government shutdown and uncertainty regarding the federal government’s debt limit or changes in fiscal, monetary or regulatory policy; the emergence or continuation of widespread health emergencies or pandemics, including the magnitude and duration of the COVID-19 pandemic and its impact on U.S. and/or global financial market conditions and our business, results of operations, financial condition and prospects; the impact of natural disasters, extreme weather events, military conflict (including the Russia/Ukraine conflict, the possible expansion of such conflict and potential geopolitical consequences), terrorism or other geopolitical events; and other matters. Forward-looking statements speak only as of the date they are made, and the Corporation undertakes no obligation to update any forward- looking statement to reflect the impact of circumstances or events that arise after the date the forward-looking statement was made. “Bank of America” and “BofA Securities” are the marketing names used by the Global Banking and Global Markets divisions of Bank of America Corporation. Lending, other commercial banking activities, and trading in certain financial instruments are performed globally by banking affiliates of Bank of America Corporation, including Bank of America, N.A., Member FDIC. Trading in securities and financial instruments, and strategic advisory, and other investment banking activities, are performed globally by investment banking affiliates of Bank of America Corporation (“Investment Banking Affiliates”) or other affiliates, including, in the United States, BofA Securities, Inc., Merrill Lynch Professional Clearing Corp. and Merrill Lynch, Pierce, Fenner & Smith Incorporated, each of which are registered broker-dealers and Members of SIPC, and, in other jurisdictions, by locally registered entities. BofA Securities, Inc. and Merrill Lynch Professional Clearing Corp. are registered as futures commission merchants with the CFTC and are members of the NFA. Investment products offered by Investment Banking Affiliates: Are Not FDIC Insured · May Lose Value · Are Not Bank Guaranteed. Bank of America Corporation’s broker-dealers are not banks and are separate legal entities from their bank affiliates. The obligations of the broker-dealers are not obligations of their bank affiliates (unless explicitly stated otherwise), and these bank affiliates are not responsible for securities sold, offered, or recommended by the broker-dealers. The foregoing also applies to other non-bank affiliates. For more Bank of America news, including dividend announcements and other important information, visit the Bank of America newsroom at https://newsroom.bankofamerica.com. www.bankofamerica.com

Current-period information is preliminary and based on company data available at the time of the presentation. 14 Bank of America Corporation and Subsidiaries Selected Financial Data (In millions, except per share data) First Quarter 2023 Fourth Quarter 2022 First Quarter 2022Summary Income Statement Net interest income $ 14,448 $ 14,681 $ 11,572 Noninterest income 11,810 9,851 11,656 Total revenue, net of interest expense 26,258 24,532 23,228 Provision for credit losses 931 1,092 30 Noninterest expense 16,238 15,543 15,319 Income before income taxes 9,089 7,897 7,879 Income tax expense 928 765 812 Net income $ 8,161 $ 7,132 $ 7,067 Preferred stock dividends and other 505 228 467 Net income applicable to common shareholders $ 7,656 $ 6,904 $ 6,600 Average common shares issued and outstanding 8,065.9 8,088.3 8,136.8 Average diluted common shares issued and outstanding 8,182.3 8,155.7 8,202.1 Summary Average Balance Sheet Total debt securities $ 851,177 $ 869,084 $ 975,656 Total loans and leases 1,041,352 1,039,247 977,793 Total earning assets 2,671,426 2,647,712 2,779,844 Total assets 3,096,058 3,074,289 3,207,702 Total deposits 1,893,649 1,925,544 2,045,811 Common shareholders’ equity 248,855 243,647 242,865 Total shareholders’ equity 277,252 272,629 269,309 Performance Ratios Return on average assets 1.07 % 0.92 % 0.89 % Return on average common shareholders’ equity 12.48 11.24 11.02 Return on average tangible common shareholders’ equity (1) 17.38 15.79 15.51 Per Common Share Information Earnings $ 0.95 $ 0.85 $ 0.81 Diluted earnings 0.94 0.85 0.80 Dividends paid 0.22 0.22 0.21 Book value 31.58 30.61 29.70 Tangible book value (1) 22.78 21.83 20.99 Summary Period-End Balance Sheet March 31 2023 December 31 2022 March 31 2022 Total debt securities $ 797,005 $ 862,819 $ 969,880 Total loans and leases 1,046,406 1,045,747 993,145 Total earning assets 2,778,481 2,640,827 2,783,186 Total assets 3,194,657 3,051,375 3,238,223 Total deposits 1,910,402 1,930,341 2,072,409 Common shareholders’ equity 251,799 244,800 239,480 Total shareholders’ equity 280,196 273,197 266,617 Common shares issued and outstanding 7,972.4 7,996.8 8,062.1 First Quarter 2023 Fourth Quarter 2022 First Quarter 2022Credit Quality Total net charge-offs $ 807 $ 689 $ 392 Net charge-offs as a percentage of average loans and leases outstanding (2) 0.32 % 0.26 % 0.16 % Provision for credit losses $ 931 $ 1,092 $ 30 March 31 2023 December 31 2022 March 31 2022 Total nonperforming loans, leases and foreclosed properties (3) $ 4,083 $ 3,978 $ 4,778 Nonperforming loans, leases and foreclosed properties as a percentage of total loans, leases and foreclosed properties (3) 0.39 % 0.38 % 0.48 % Allowance for loan and lease losses $ 12,514 $ 12,682 $ 12,104 Allowance for loan and lease losses as a percentage of total loans and leases outstanding (2) 1.20 % 1.22 % 1.23 % For footnotes, see page 15.

Current-period information is preliminary and based on company data available at the time of the presentation. 15 Bank of America Corporation and Subsidiaries Selected Financial Data (continued) (Dollars in millions) Capital Management March 31 2023 December 31 2022 March 31 2022 Regulatory capital metrics (4): Common equity tier 1 capital $ 184,432 $ 180,060 $ 169,874 Common equity tier 1 capital ratio - Standardized approach 11.4 % 11.2 % 10.4 % Common equity tier 1 capital ratio - Advanced approaches 12.9 12.8 12.0 Tier 1 leverage ratio 7.1 7.0 6.3 Supplementary leverage ratio 6.0 5.9 5.4 Total ending equity to total ending assets ratio 8.8 9.0 8.2 Common equity ratio 7.9 8.0 7.4 Tangible equity ratio (5) 6.7 6.8 6.2 Tangible common equity ratio (5) 5.8 5.9 5.3 (1) Return on average tangible common shareholders’ equity and tangible book value per share of common stock are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. Tangible book value per share provides additional useful information about the level of tangible assets in relation to outstanding shares of common stock. See Reconciliations to GAAP Financial Measures on page 18. (2) Ratios do not include loans accounted for under the fair value option. Charge-off ratios are annualized for the quarterly presentation. (3) Balances do not include past due consumer credit card loans, consumer loans secured by real estate where repayments are insured by the Federal Housing Administration and individually insured long-term stand-by agreements (fully-insured home loans), and in general, other consumer and commercial loans not secured by real estate, and nonperforming loans held-for-sale or accounted for under the fair value option. (4) Regulatory capital ratios at March 31, 2023 are preliminary. Bank of America Corporation reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was the Common equity tier 1 ratio under the Standardized approach for all periods presented. (5) Tangible equity ratio equals period-end tangible shareholders’ equity divided by period-end tangible assets. Tangible common equity ratio equals period-end tangible common shareholders’ equity divided by period-end tangible assets. Tangible shareholders’ equity and tangible assets are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. See Reconciliations to GAAP Financial Measures on page 18.

Current-period information is preliminary and based on company data available at the time of the presentation. 16 Bank of America Corporation and Subsidiaries Quarterly Results by Business Segment and All Other (Dollars in millions) First Quarter 2023 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 10,706 $ 5,315 $ 6,203 $ 5,626 $ (1,458) Provision for credit losses 1,089 25 (237) (53) 107 Noninterest expense 5,473 4,067 2,940 3,351 407 Net income (loss) 3,108 917 2,555 1,688 (107) Return on average allocated capital (1) 30 % 20 % 21 % 15 % n/m Balance Sheet Average Total loans and leases $ 303,772 $ 221,448 $ 381,009 $ 125,046 $ 10,077 Total deposits 1,026,242 314,019 492,577 36,109 24,702 Allocated capital (1) 42,000 18,500 49,250 45,500 n/m Quarter end Total loans and leases $ 304,480 $ 217,804 $ 383,491 $ 130,804 $ 9,827 Total deposits 1,044,768 301,471 495,949 33,624 34,590 Fourth Quarter 2022 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 10,782 $ 5,410 $ 6,438 $ 3,861 $ (1,836) Provision for credit losses 944 37 149 4 (42) Noninterest expense 5,100 3,784 2,833 3,171 655 Net income (loss) 3,577 1,200 2,540 504 (689) Return on average allocated capital (1) 35 % 27 % 23 % 5 % n/m Balance Sheet Average Total loans and leases $ 300,360 $ 225,094 $ 380,385 $ 123,022 $ 10,386 Total deposits 1,047,058 317,849 503,472 37,219 19,946 Allocated capital (1) 40,000 17,500 44,500 42,500 n/m Quarter end Total loans and leases $ 304,761 $ 223,910 $ 379,107 $ 127,735 $ 10,234 Total deposits 1,048,799 323,899 498,661 39,077 19,905 First Quarter 2022 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 8,813 $ 5,476 $ 5,194 $ 5,292 $ (1,441) Provision for credit losses (52) (41) 165 5 (47) Noninterest expense 4,921 4,015 2,683 3,117 583 Net income 2,978 1,134 1,724 1,595 (364) Return on average allocated capital (1) 30 % 26 % 16 % 15 % n/m Balance Sheet Average Total loans and leases $ 284,068 $ 210,937 $ 358,807 $ 108,576 $ 15,405 Total deposits 1,056,100 384,902 539,912 44,393 20,504 Allocated capital (1) 40,000 17,500 44,500 42,500 n/m Quarter end Total loans and leases $ 286,322 $ 214,273 $ 367,423 $ 110,037 $ 15,090 Total deposits 1,088,940 385,288 533,820 43,371 20,990 (1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently. n/m = not meaningful The Company reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis.

Current-period information is preliminary and based on company data available at the time of the presentation. 17 Bank of America Corporation and Subsidiaries Supplemental Financial Data (Dollars in millions) First Quarter 2023 Fourth Quarter 2022 First Quarter 2022FTE basis data (1) Net interest income $ 14,582 $ 14,804 $ 11,678 Total revenue, net of interest expense 26,391 24,655 23,334 Net interest yield 2.20 % 2.22 % 1.69 % Efficiency ratio 61.53 63.05 65.65 Other Data March 31 2023 December 31 2022 March 31 2022 Number of financial centers - U.S. 3,892 3,913 4,056 Number of branded ATMs - U.S. 15,407 15,528 15,959 Headcount 217,059 216,823 208,139 (1) FTE basis is a non-GAAP financial measure. FTE basis is a performance measure used by management in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that this presentation allows for comparison of amounts from both taxable and tax- exempt sources and is consistent with industry practices. Net interest income includes FTE adjustments of $134 million, $123 million and $106 million for the first quarter of 2023 and the fourth and first quarters of 2022, respectively.

Current-period information is preliminary and based on company data available at the time of the presentation. 18 The Corporation evaluates its business based on the following ratios that utilize tangible equity, a non-GAAP financial measure. Tangible equity represents shareholders’ equity or common shareholders’ equity reduced by goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities (“adjusted” shareholders’ equity or common shareholders’ equity). Return on average tangible common shareholders’ equity measures the Corporation’s net income applicable to common shareholders as a percentage of adjusted average common shareholders’ equity. The tangible common equity ratio represents adjusted ending common shareholders’ equity divided by total tangible assets (total assets less goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities). Return on average tangible shareholders’ equity measures the Corporation’s net income as a percentage of adjusted average total shareholders’ equity. The tangible equity ratio represents adjusted ending shareholders’ equity divided by total tangible assets. Tangible book value per common share represents adjusted ending common shareholders’ equity divided by ending common shares outstanding. These measures are used to evaluate the Corporation’s use of equity. In addition, profitability, relationship and investment models all use return on average tangible shareholders’ equity as key measures to support our overall growth goals. See the tables below for reconciliations of these non-GAAP financial measures to the most closely related financial measures defined by GAAP for the three months ended March 31, 2023, December 31, 2022 and March 31, 2022. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. Other companies may define or calculate supplemental financial data differently. Bank of America Corporation and Subsidiaries Reconciliations to GAAP Financial Measures (Dollars in millions, except per share information) First Quarter 2023 Fourth Quarter 2022 First Quarter 2022 Reconciliation of income before income taxes to pretax, pre-provision income Income before income taxes $ 9,089 $ 7,897 $ 7,879 Provision for credit losses 931 1,092 30 Pretax, pre-provision income $ 10,020 $ 8,989 $ 7,909 Reconciliation of average shareholders’ equity to average tangible shareholders’ equity and average tangible common shareholders’ equity Shareholders’ equity $ 277,252 $ 272,629 $ 269,309 Goodwill (69,022) (69,022) (69,022) Intangible assets (excluding mortgage servicing rights) (2,068) (2,088) (2,146) Related deferred tax liabilities 899 914 929 Tangible shareholders’ equity $ 207,061 $ 202,433 $ 199,070 Preferred stock (28,397) (28,982) (26,444) Tangible common shareholders’ equity $ 178,664 $ 173,451 $ 172,626 Reconciliation of period-end shareholders’ equity to period-end tangible shareholders’ equity and period-end tangible common shareholders’ equity Shareholders’ equity $ 280,196 $ 273,197 $ 266,617 Goodwill (69,022) (69,022) (69,022) Intangible assets (excluding mortgage servicing rights) (2,055) (2,075) (2,133) Related deferred tax liabilities 895 899 926 Tangible shareholders’ equity $ 210,014 $ 202,999 $ 196,388 Preferred stock (28,397) (28,397) (27,137) Tangible common shareholders’ equity $ 181,617 $ 174,602 $ 169,251 Reconciliation of period-end assets to period-end tangible assets Assets $ 3,194,657 $ 3,051,375 $ 3,238,223 Goodwill (69,022) (69,022) (69,022) Intangible assets (excluding mortgage servicing rights) (2,055) (2,075) (2,133) Related deferred tax liabilities 895 899 926 Tangible assets $ 3,124,475 $ 2,981,177 $ 3,167,994 Book value per share of common stock Common shareholders’ equity $ 251,799 $ 244,800 $ 239,480 Ending common shares issued and outstanding 7,972.4 7,996.8 8,062.1 Book value per share of common stock $ 31.58 $ 30.61 $ 29.70 Tangible book value per share of common stock Tangible common shareholders’ equity $ 181,617 $ 174,602 $ 169,251 Ending common shares issued and outstanding 7,972.4 7,996.8 8,062.1 Tangible book value per share of common stock $ 22.78 $ 21.83 $ 20.99

Bank of America 1Q23 Financial Results April 18, 2023

1Q23 Results Highlights 2 Generated strong earnings Grew clients and accounts organically Seventh consecutive quarter of operating leverage2 Strengthened balance sheet Maintained strong liquidity Delivered good returns Diluted EPS $0.94 +18% YoY CET14 capital $184B GLS5,6 $904B ROTCE7,8 17.4% ROE7 12.5% Cash5 $376B ~130K net new Consumer checking accounts ~14.5K net new GWIM2 relation- ships 1 Revenue, net of interest expense. 2 GWIM stands for Global Wealth and Investment Management. 3 Operating leverage is calculated as the year-over-year percentage change in revenue, net of interest expense, less the percentage change in noninterest expense. 4 CET1 stands for common equity tier 1. 5 End of period. 6 GLS stands for Global Liquidity Sources. See note A on slide 35 for definition of Global Liquidity Sources. 7 ROE stands for return on average common shareholders’ equity. ROTCE stands for return on average tangible common shareholders’ equity. ROA stands for return on average assets. 8 Represents a non-GAAP financial measure. For important presentation information, see slide 38. Revenue1 $26.3B +13% YoY Deposits5 $1.9T ROA7 1.07%

1Q23 Highlights (Comparisons to 1Q22, unless otherwise noted) • Net income of $8.2B; diluted earnings per share of $0.94; ROE 12.5%, ROTCE 17.4%1 • Revenue, net of interest expense, of $26.3B increased $3.0B, or 13% – Net interest income (NII) of $14.4B ($14.6B FTE1) increased $2.9B, or 25%, driven primarily by benefits from higher interest rates and solid loan growth – Noninterest income of $11.8B increased $154MM, or 1%, as higher sales and trading revenue more than offset lower service charges and declines in asset management and investment banking fees • Provision for credit losses of $931MM – Net reserve build of $124MM vs. net reserve release of $362MM in 1Q22; build of $403MM in 4Q222 – Net charge-offs (NCOs) of $807MM increased compared to 1Q22 and 4Q22 and remained below pre-pandemic levels – Net charge-off ratio of 32 bps increased 16 bps vs. 1Q22 and 6 bps vs. 4Q22 • Noninterest expense of $16.2B increased $0.9B, or 6%, vs. 1Q22 – Generated operating leverage3 for the seventh consecutive quarter (705 bps in 1Q23) • Balance sheet remained strong – Average loans and leases grew $2B from 4Q22 – Average deposits decreased $32B from 4Q22 – Common Equity Tier 1 ratio of 11.4% increased 14 bps from 4Q22 – Average Global Liquidity Sources of $854B; ending Global Liquidity Sources of $904B4 – Paid $1.8B in common dividends and repurchased $2.2B of common stock, including repurchases to offset shares awarded under equity-based compensation plans 3 Note: FTE stands for fully taxable-equivalent basis. 1 Represent non-GAAP financial measures. For important presentation information about these measures, see slide 38. 2 For more information on reserve build (release), see note B on slide 35. Net charge-offs exclude loans measured at fair value. 3 Operating leverage is calculated as the year-over-year percentage change in revenue, net of interest expense, less the percentage change in noninterest expense. 4 See note A on slide 35 for definition of Global Liquidity Sources.

Note: Amounts may not total due to rounding. N/M stands for not meaningful. 1 Represent non-GAAP financial measures. For more information on pretax, pre-provision income and a reconciliation to GAAP, see note C on slide 35. For important presentation information about these measures, see slide 38. Summary Income Statement ($B, except per share data) 1Q23 4Q22 Inc / (Dec) 1Q22 Inc / (Dec) Total Revenue, net of interest expense $26.3 $24.5 $1.7 7 % $23.2 $3.0 13 % Provision for credit losses 0.9 1.1 (0.2) (15) — 0.9 N/M Net charge-offs 0.8 0.7 0.1 17 0.4 0.4 106 Reserve build (release) 0.1 0.4 (0.3) (69) (0.4) 0.5 134 Noninterest expense 16.2 15.5 0.7 4 15.3 0.9 6 Pretax income 9.1 7.9 1.2 15 7.9 1.2 15 Pretax, pre-provision income1 10.0 9.0 1.0 11 7.9 2.1 27 Income tax expense 0.9 0.8 0.2 21 0.8 0.1 14 Net income $8.2 $7.1 $1.0 14 $7.1 $1.1 15 Diluted earnings per share $0.94 $0.85 $0.09 11 $0.80 $0.14 18 Average diluted common shares (in millions) 8,182 8,156 27 — 8,202 (20) — Return Metrics and Efficiency Ratio Return on average assets 1.07 % 0.92 % 0.89 % Return on average common shareholders' equity 12.5 11.2 11.0 Return on average tangible common shareholders' equity1 17.4 15.8 15.5 Efficiency ratio 62 63 66 1Q23 Financial Results 4

Balance Sheet Metrics 1Q23 4Q22 1Q22 Basel 3 Capital ($B)4 1Q23 4Q22 1Q22 Assets ($B) Common equity tier 1 capital $184 $180 $170 Total assets $3,195 $3,051 $3,238 Standardized approach Total loans and leases 1,046 1,046 993 Risk-weighted assets (RWA) $1,623 $1,605 $1,639 Cash and cash equivalents 376 230 274 CET1 ratio 11.4 % 11.2 % 10.4 % Total debt securities 797 863 970 Advanced approaches Risk-weighted assets $1,429 $1,411 $1,416 Funding & Liquidity ($B) CET1 ratio 12.9 % 12.8 % 12.0 % Total deposits $1,910 $1,930 $2,072 Supplementary leverage Long-term debt 284 276 279 Supplementary Leverage Ratio 6.0 % 5.9 % 5.4 % Global Liquidity Sources (average)2 854 868 1,109 Equity ($B) Common shareholders' equity $252 $245 $239 Common equity ratio 7.9 % 8.0 % 7.4 % Tangible common shareholders' equity3 $182 $175 $169 Tangible common equity ratio3 5.8 % 5.9 % 5.3 % Per Share Data Book value per common share $31.58 $30.61 $29.70 Tangible book value per common share3 22.78 21.83 20.99 Common shares outstanding (in billions) 7.97 8.00 8.06 1 EOP stands for end of period. 2 See note A on slide 35 for definition of Global Liquidity Sources. 3 Represent non-GAAP financial measures. For important presentation information, see slide 38. 4 Regulatory capital ratios at March 31, 2023 are preliminary. Bank of America Corporation (“the Corporation”) reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was CET1 ratio under the Standardized approach as of March 31, 2023, December 31, 2022 and March 31, 2022. 5 OCI stands for other comprehensive income; AFS stands for available-for-sale. Balance Sheet, Liquidity and Capital (EOP1 basis unless noted) 5 • CET1 ratio of 11.4% increased 14 bps vs. 4Q224 – CET1 capital of $184B rose $4B from 4Q22, driven by net income and OCI on AFS debt securities,5 partially offset by capital distributions to common shareholders – Standardized RWA of $1,623B increased $19B from 4Q22 • Book value per share of $31.58 improved 3% from 4Q22 • Average Global Liquidity Sources2 of $854B decreased $14B, or 2%, from 4Q22 – Ending Global Liquidity Sources2 of $904B
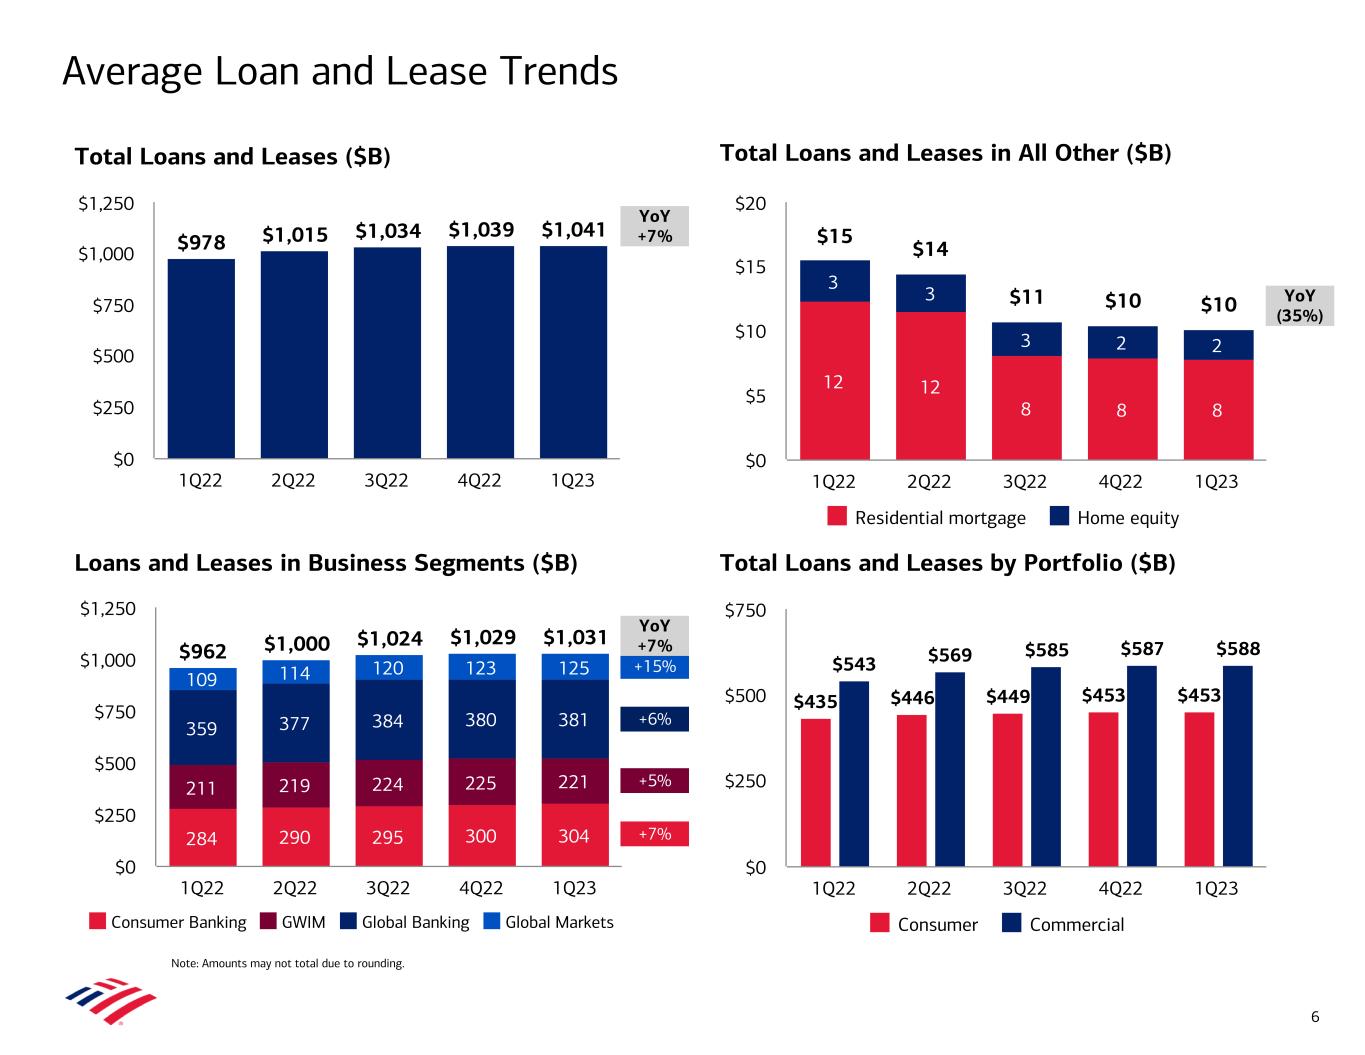
$962 $1,000 $1,024 $1,029 $1,031 284 290 295 300 304 211 219 224 225 221 359 377 384 380 381 109 114 120 123 125 Consumer Banking GWIM Global Banking Global Markets 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $250 $500 $750 $1,000 $1,250 $978 $1,015 $1,034 $1,039 $1,041 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $250 $500 $750 $1,000 $1,250 +7% +5% +6% +15% Average Loan and Lease Trends YoY +7% YoY +7% YoY (35%) Note: Amounts may not total due to rounding. Total Loans and Leases in All Other ($B) Loans and Leases in Business Segments ($B) Total Loans and Leases by Portfolio ($B) Total Loans and Leases ($B) $435 $446 $449 $453 $453 $543 $569 $585 $587 $588 Consumer Commercial 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $250 $500 $750 6 12 12 8 8 8 3 3 3 2 2 $15 $14 $11 $10 $10 Residential mortgage Home equity 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $5 $10 $15 $20

Consumer Banking ($B) GWIM ($B) Global Banking ($B) Total Corporation ($B) Average Deposit Trends Bank of America Ranked #1 in U.S. Retail Deposit Market Share1 Note: Amounts may not total due to rounding. Total Corporation also includes Global Markets and All Other. 1 Estimated U.S. retail deposits based on June 30, 2022 FDIC deposit data. 2 Includes Consumer and Small Business checking products and excludes Consumer Investments, which are included in non-checking. 3 Includes Preferred Deposits, other non-sweep Merrill Bank deposits, and Private Bank deposits. $256 $385 $364 $339 $318 $314 167 213 200 206 211 224 88 172 163 134 106 90 Bank deposits Sweep deposits 4Q19 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $100 $200 $300 $400 $1,410 $2,046 $2,012 $1,963 $1,926 $1,894 1,002 1,247 1,222 1,225 1,245 1,264 409 799 790 738 681 630 Interest-bearing Noninterest-bearing 4Q19 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $500 $1,000 $1,500 $2,000 $2,500 $379 $540 $509 $495 $503 $493 209 157 142 171 226 257 169 383 367 324 278 236 Interest-bearing Noninterest-bearing 4Q19 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $200 $400 $600 +6% (15%) +2% (7%) QoQ (2%) QoQ (1%) QoQ (2%) +14% (15%) (2%) QoQ (2%) 7 $720 $1,056 $1,078 $1,069 $1,047 $1,026 377 515 523 522 511 501 343 541 555 547 536 525 Non-checking Checking 4Q19 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $250 $500 $750 $1,000 $1,250 (2%) 2 +26% +54% vs. 4Q19 +34% +34% +2% vs. 4Q19 +23% +33% +53% vs. 4Q19 +43% +23% +39% vs. 4Q19 +30% 3
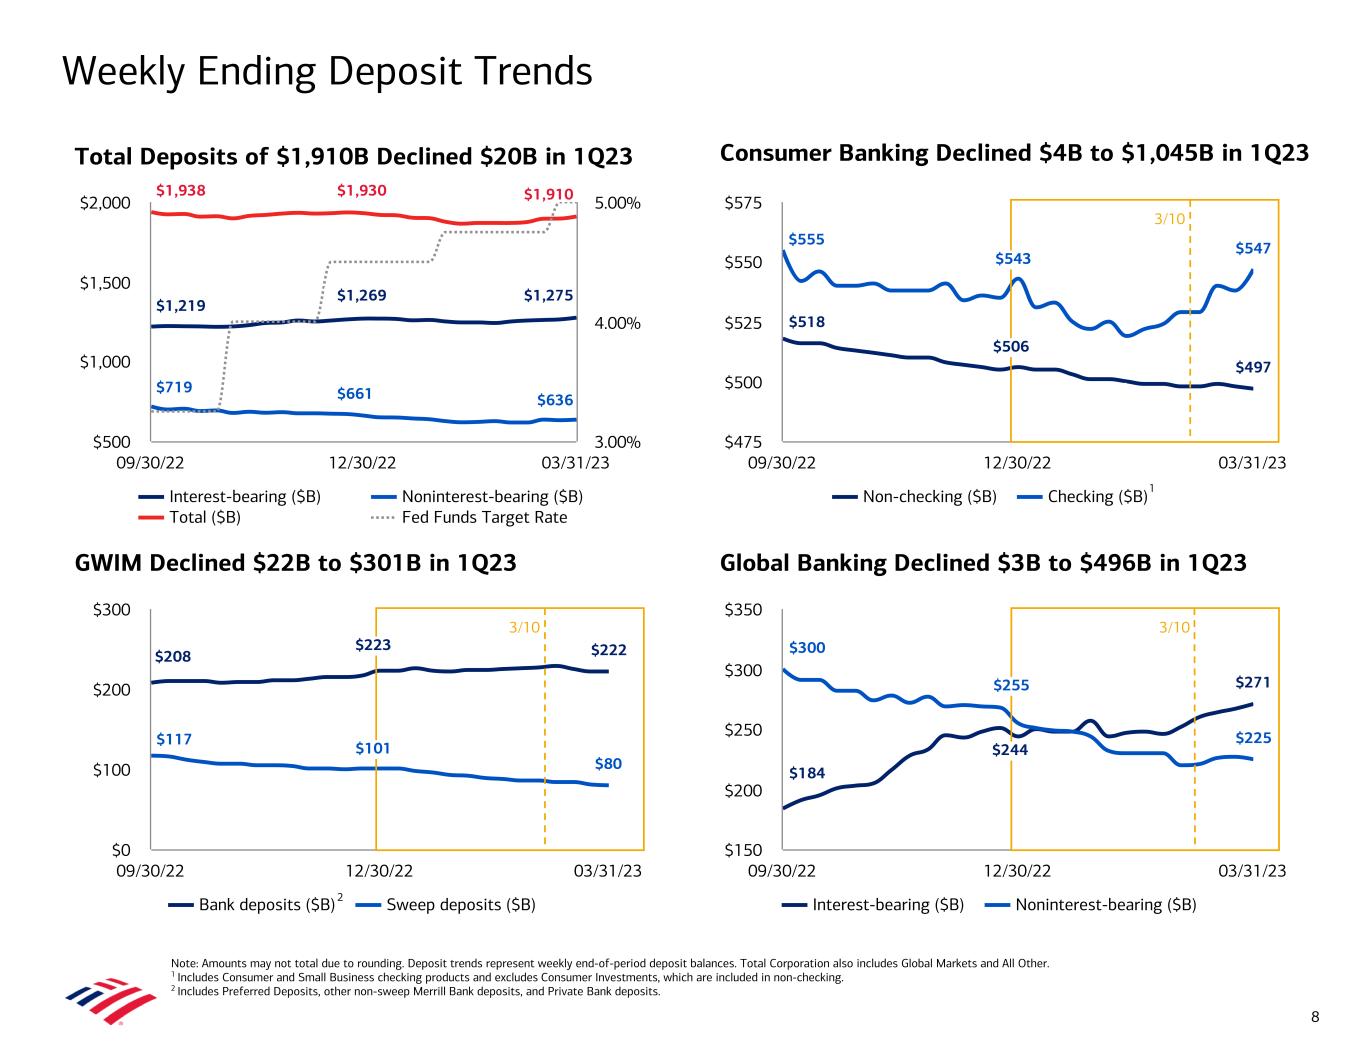
$497 $547 Non-checking ($B) Checking ($B) 09/30/22 12/30/22 03/31/23 $475 $500 $525 $550 $575 $271 $225 Interest-bearing ($B) Noninterest-bearing ($B) 09/30/22 12/30/22 03/31/23 $150 $200 $250 $300 $350 $222 $80 Bank deposits ($B) Sweep deposits ($B) 09/30/22 12/30/22 03/31/23 $0 $100 $200 $300 Interest-bearing ($B) Noninterest-bearing ($B) Total ($B) Fed Funds Target Rate 09/30/22 12/30/22 03/31/23 $500 $1,000 $1,500 $2,000 3.00% 4.00% 5.00% Consumer Banking Declined $4B to $1,045B in 1Q23 GWIM Declined $22B to $301B in 1Q23 Global Banking Declined $3B to $496B in 1Q23 Total Deposits of $1,910B Declined $20B in 1Q23 Weekly Ending Deposit Trends 8 $555 $184 $300 $518 Note: Amounts may not total due to rounding. Deposit trends represent weekly end-of-period deposit balances. Total Corporation also includes Global Markets and All Other. 1 Includes Consumer and Small Business checking products and excludes Consumer Investments, which are included in non-checking. 2 Includes Preferred Deposits, other non-sweep Merrill Bank deposits, and Private Bank deposits. $208 $117 $1,938 $1,219 $719 $1,910 $1,275 $636 3/10 3/103/10 1 $1,930 $1,269 $661 $543 $506 $244 $255 $223 $101 2
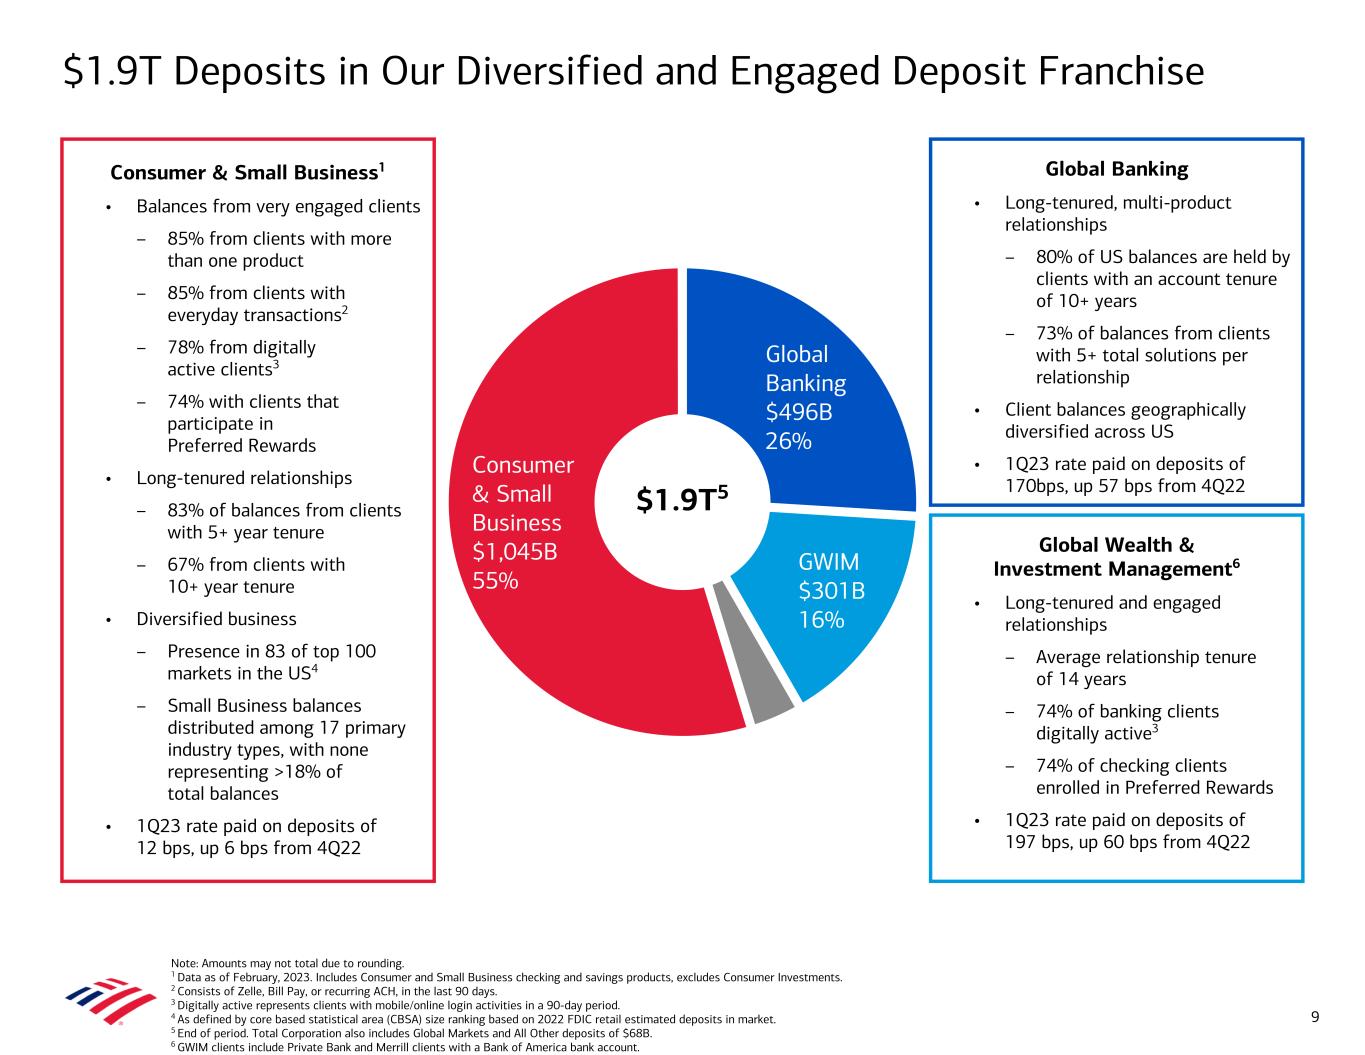
Global Banking $496B 26% GWIM $301B 16% Consumer & Small Business $1,045B 55% $1.9T Deposits in Our Diversified and Engaged Deposit Franchise 9 Note: Amounts may not total due to rounding. 1 Data as of February, 2023. Includes Consumer and Small Business checking and savings products, excludes Consumer Investments. 2 Consists of Zelle, Bill Pay, or recurring ACH, in the last 90 days. 3 Digitally active represents clients with mobile/online login activities in a 90-day period. 4 As defined by core based statistical area (CBSA) size ranking based on 2022 FDIC retail estimated deposits in market. 5 End of period. Total Corporation also includes Global Markets and All Other deposits of $68B. 6 GWIM clients include Private Bank and Merrill clients with a Bank of America bank account. Consumer & Small Business1 • Balances from very engaged clients – 85% from clients with more than one product – 85% from clients with everyday transactions2 – 78% from digitally active clients3 – 74% with clients that participate in Preferred Rewards • Long-tenured relationships – 83% of balances from clients with 5+ year tenure – 67% from clients with 10+ year tenure • Diversified business – Presence in 83 of top 100 markets in the US4 – Small Business balances distributed among 17 primary industry types, with none representing >18% of total balances • 1Q23 rate paid on deposits of 12 bps, up 6 bps from 4Q22 Global Wealth & Investment Management6 • Long-tenured and engaged relationships – Average relationship tenure of 14 years – 74% of banking clients digitally active3 – 74% of checking clients enrolled in Preferred Rewards • 1Q23 rate paid on deposits of 197 bps, up 60 bps from 4Q22 Global Banking • Long-tenured, multi-product relationships – 80% of US balances are held by clients with an account tenure of 10+ years – 73% of balances from clients with 5+ total solutions per relationship • Client balances geographically diversified across US • 1Q23 rate paid on deposits of 170bps, up 57 bps from 4Q22$1.9T5
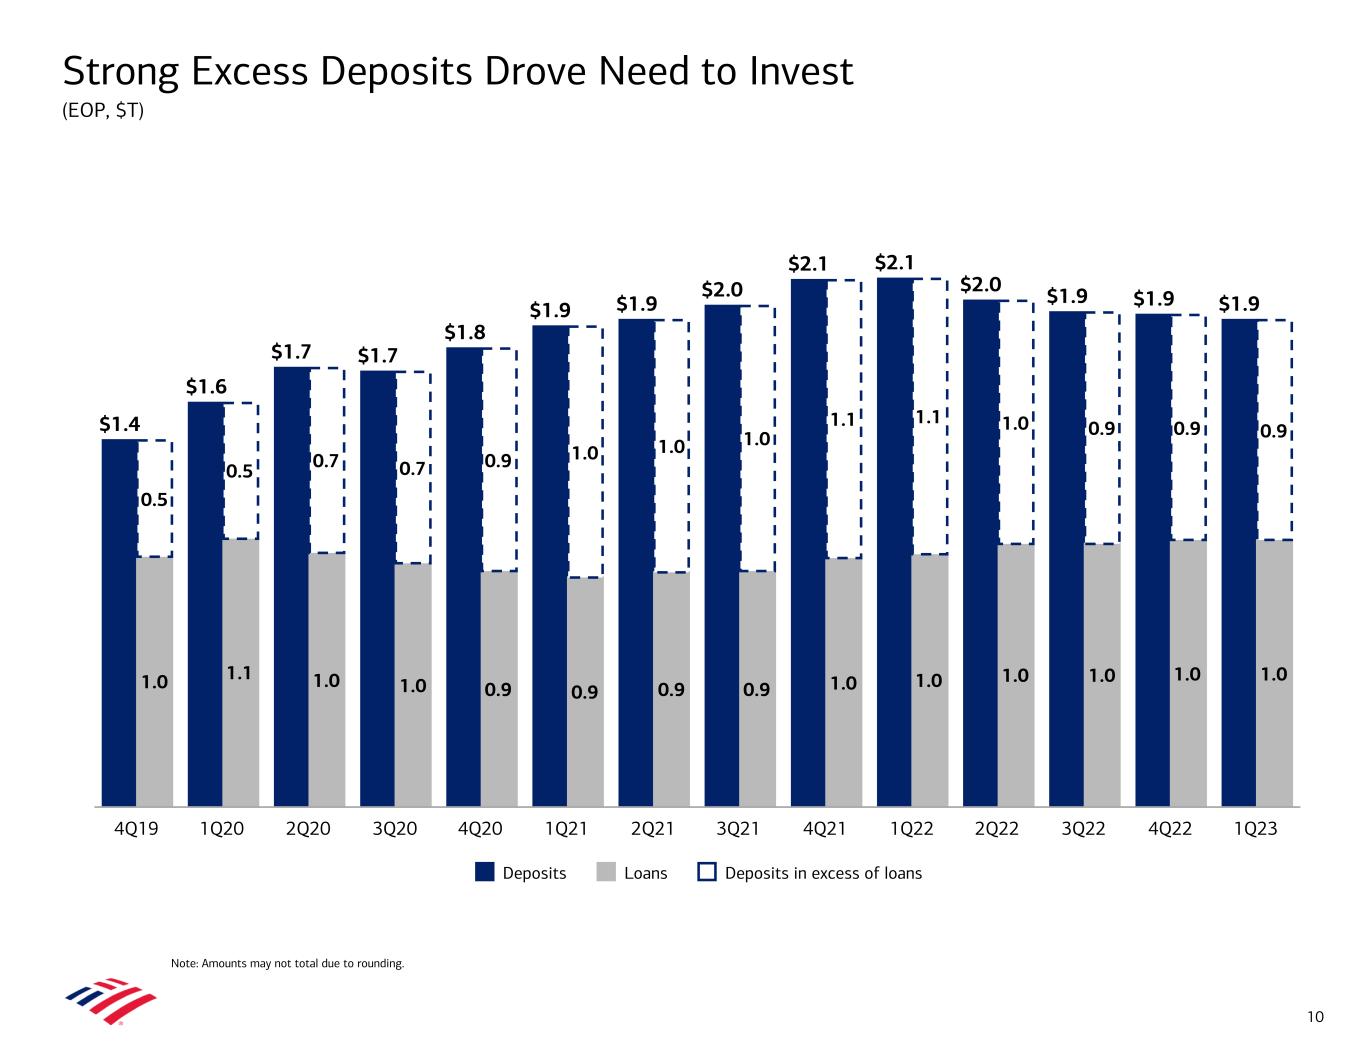
Strong Excess Deposits Drove Need to Invest (EOP, $T) 10 $1.4 $1.6 $1.7 $1.7 $1.8 $1.9 $1.9 $2.0 $2.1 $2.1 $2.0 $1.9 $1.9 $1.9 1.4 1.6 1.7 1.7 1.8 1.9 1.9 2.0 2.1 2.1 2.0 1.9 1.9 1.9 1.0 1.1 1.0 1.0 0.9 0.9 0.9 0.9 1.0 1.0 1.0 1.0 1.0 1.0 0.5 0.5 0.7 0.7 0.9 1.0 1.0 1.0 1.1 1.1 1.0 0.9 0.9 0.9 Deposits Loans Deposits in excess of loans 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 Note: Amounts may not total due to rounding.

Investments Made to Extract the Value of Deposits 11 $634 $726 $761 $885 $1,065 $1,183 $1,200 $1,248 $1,331 $1,244 $1,131 $1,085 $1,093 $1,173 162 380 348 230 376 256 247 308 230 173 216 438 675 633 624 Cash and cash equivalents ($B) AFS and other securities ($B) HTM securities ($B) 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $500 $1,000 $1,500 • Managed within various interest rate sensitivity, liquidity, and capital limits • Deposits in excess of loans grew from $0.5T in 4Q19 to $1.1T (4Q21-1Q22) and were $0.9T at March 31, 2023 – Stored excess deposits in cash and investment securities – Hedged AFS securities with floating rate swaps, beginning in 2020 – Stopped adding to HTM securities book as deposits appeared to be peaking; book has declined quarterly and is $59B below peak of $683B in 3Q21 – Weighted average life of HTM portfolio currently 8.5 years; AFS 5.5 years – NII excluding Global Markets trough of $9.1B in 3Q20 vs. $14.5B in 1Q233 • Reduced AFS securities and increased cash in 1Q23 Yield2 on: Cash 1.2% 0.8% 0.0% 0.0% 0.1% 0.0% 0.0% 0.1% 0.1% 0.1% 0.6% 1.8% 3.1% 4.0% Securities 2.5% 2.5% 2.1% 1.6% 1.5% 1.4% 1.3% 1.4% 1.5% 1.6% 1.7% 1.9% 2.3% 2.6% Blended 2.2% 2.1% 1.3% 1.1% 1.0% 1.1% 1.0% 1.1% 1.2% 1.3% 1.5% 1.9% 2.4% 2.9% Note: Amounts may not total due to rounding. 1 HTM stands for held-to-maturity. 2 Yields based on average balances. Yield on cash represents yield on interest-bearing deposits with the Federal Reserve, non-U.S. central banks and other banks. 3 Fully taxable-equivalent basis. Represents a non-GAAP financial measure. Reported NII was $10.1B and $14.4B in 3Q20 and 1Q23. FTE NII was $10.2B and $14.6B in 3Q20 and 1Q23. Global Markets NII was $1.1B and $0.1B in 3Q20 and 1Q23. For important presentation information, see slide 38. 1

Net Interest Income (FTE, $B)1 • Net interest income of $14.4B ($14.6B FTE1) increased $2.9B YoY, driven by benefits from higher interest rates and loan growth – Decreased $0.2B from 4Q22, as the benefit from higher interest rates was more than offset by lower deposit balances, two fewer interest accrual days, and lower NII related to GM activity – NII related to GM activity declined approximately $0.9B YoY, and $0.3B from 4Q22, and was offset in noninterest income – Premium amortization expense of $34MM in 1Q23, $210MM in 4Q22, and $905MM in 1Q22 • Net interest yield of 2.20% increased 51 bps YoY and decreased 2 bps from 4Q22 – Excluding GM, net interest yield of 2.85%;1 up 86 bps YoY • As of March 31, 2023, a +100 bps parallel shift in the interest rate yield curve is estimated to benefit net interest income by $3.3B over the next 12 months2 Net Interest Income Increased $2.9B, or 25% YoY Net Interest Yield (FTE)1 Note: FTE stands for fully taxable-equivalent basis. GM stands for Global Markets. 1 Represent non-GAAP financial measures. Net interest yield adjusted to exclude Global Markets NII of $0.1B, $0.4B, $0.7B, $1.0B, and $1.0B and average earning assets of $627.9B, $610.0B, $591.9B, $598.8B, and $610.9B for 1Q23, 4Q22, 3Q22, 2Q22, and 1Q22, respectively. The Corporation believes the presentation of NII and net interest yield excluding Global Markets provides investors with transparency of NII and net interest yield in core banking activities. For important presentation information, see slide 38. 2 NII asset sensitivity represents banking book positions. See note D on slide 35 for information on asset sensitivity assumptions. 1.69% 1.86% 2.06% 2.22% 2.20% 1.99% 2.20% 2.51% 2.81% 2.85% Reported net interest yield Net interest yield excl. GM 1Q22 2Q22 3Q22 4Q22 1Q23 1.00% 1.50% 2.00% 2.50% 3.00% $11.7 $12.5 $13.9 $14.8 $14.6 $11.6 $12.4 $13.8 $14.7 $14.4 Net interest income (GAAP) FTE Adjustment 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $5.0 $10.0 $15.0 12 Net Interest Income excl. GM (FTE, $B)1 $11.7 $12.5 $13.9 $14.8 $14.6 $10.7 $11.6 $13.1 $14.4 $14.5 NII excl. GM GM NII 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $5.0 $10.0 $15.0

$15.3 $15.3 $15.3 $15.5 $16.2 9.5 8.9 8.9 9.2 9.9 5.8 6.4 6.4 6.4 6.3 Compensation and benefits Other 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $10.0 $20.0 66% 67% 62% 63% 62% 1Q22 2Q22 3Q22 4Q22 1Q23 50% 60% 70% • Noninterest expense of $16.2B in 1Q23 increased $0.7B, or 4%, vs. 4Q22, driven primarily by seasonally higher payroll taxes, continued investments in people and technology, and higher FDIC expense from the 2022 increased assessment on banks • 1Q23 expense increased $0.9B, or 6%, vs. 1Q22, driven by investments in the franchise across people and technology as well as higher FDIC expense, partially offset by lower revenue-related incentive compensation Total Noninterest Expense ($B) Efficiency Ratio Expense and Efficiency Note: Amounts may not total due to rounding. 13

• Total net charge-offs of $807MM1 increased $118MM from 4Q22 – Consumer net charge-offs of $653MM increased $122MM, driven primarily by higher credit card losses ◦ Credit card loss rate of 2.21% in 1Q23, 1.71% in 4Q22, and 3.03% in 4Q19 – Commercial net charge-offs of $154MM decreased $4MM • Net charge-off ratio of 0.32% increased 6 bps from 4Q22 and remained below pre-pandemic levels • Provision for credit losses of $931MM – Net reserve build of $124MM in 1Q23, driven primarily by Consumer due to higher-than- expected credit card balances, partially offset by an improved macroeconomic outlook that primarily benefited the Commercial portfolio • Allowance for loan and lease losses of $12.5B represented 1.20% of total loans and leases1,2 – Total allowance of $14.0B included $1.4B for unfunded commitments – Includes a January 1, 2023 $243MM reduction for the accounting change to remove the recognition and measurement guidance on troubled debt restructurings • Nonperforming loans (NPLs) increased $0.1B from 4Q22 to $3.9B – 60% of Consumer NPLs are contractually current • Commercial reservable criticized utilized exposure of $19.8B increased $0.5B from 4Q22 Asset Quality 1 Excludes loans measured at fair value. 2 Allowance for loan and lease losses ratio is calculated as allowance for loan and lease losses divided by loans and leases outstanding at the end of the period. Provision for Credit Losses ($MM) Net Charge-offs ($MM)1 $30 $523 $898 $1,092 $931 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $500 $1,000 $1,500 $392 $571 $520 $689 $807 0.16% 0.23% 0.20% 0.26% 0.32% Net charge-offs Net charge-off ratio 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $200 $400 $600 $800 $1,000 0.00% 0.10% 0.20% 0.30% 0.40% 0.50% 14
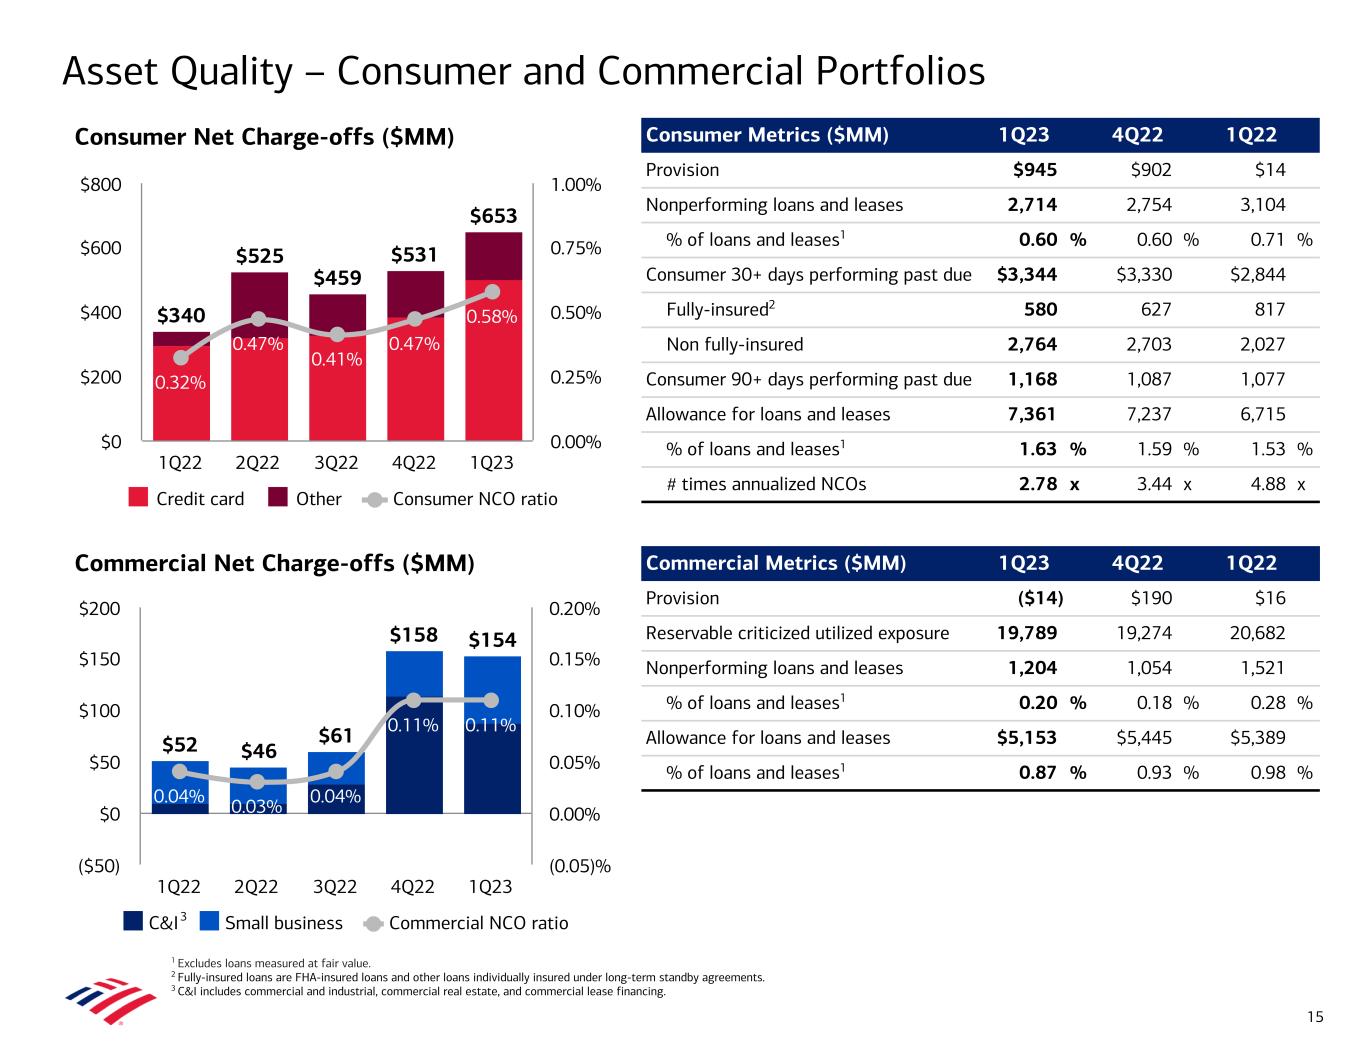
Commercial Net Charge-offs ($MM) Consumer Net Charge-offs ($MM) Asset Quality – Consumer and Commercial Portfolios 1 Excludes loans measured at fair value. 2 Fully-insured loans are FHA-insured loans and other loans individually insured under long-term standby agreements. 3 C&I includes commercial and industrial, commercial real estate, and commercial lease financing. $52 $46 $61 $158 $154 0.04% 0.03% 0.04% 0.11% 0.11% C&I Small business Commercial NCO ratio 1Q22 2Q22 3Q22 4Q22 1Q23 ($50) $0 $50 $100 $150 $200 (0.05)% 0.00% 0.05% 0.10% 0.15% 0.20% $340 $525 $459 $531 $653 0.32% 0.47% 0.41% 0.47% 0.58% Credit card Other Consumer NCO ratio 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $200 $400 $600 $800 0.00% 0.25% 0.50% 0.75% 1.00% Commercial Metrics ($MM) 1Q23 4Q22 1Q22 Provision ($14) $190 $16 Reservable criticized utilized exposure 19,789 19,274 20,682 Nonperforming loans and leases 1,204 1,054 1,521 % of loans and leases1 0.20 % 0.18 % 0.28 % Allowance for loans and leases $5,153 $5,445 $5,389 % of loans and leases1 0.87 % 0.93 % 0.98 % Consumer Metrics ($MM) 1Q23 4Q22 1Q22 Provision $945 $902 $14 Nonperforming loans and leases 2,714 2,754 3,104 % of loans and leases1 0.60 % 0.60 % 0.71 % Consumer 30+ days performing past due $3,344 $3,330 $2,844 Fully-insured2 580 627 817 Non fully-insured 2,764 2,703 2,027 Consumer 90+ days performing past due 1,168 1,087 1,077 Allowance for loans and leases 7,361 7,237 6,715 % of loans and leases1 1.63 % 1.59 % 1.53 % # times annualized NCOs 2.78 x 3.44 x 4.88 x 15 3

Added record ~14,500 net new relationships across Merrill and Private Bank $80 billion total net client flows since 1Q22 Opened record ~35,000 bank accounts, up 18% YoY Sent ~40,000 referrals to other lines of business Continued Organic Growth in 1Q23 16 Consumer Banking Global Wealth & Investment Management Global Banking Global Markets Added ~130,000 net new checking accounts; 17th consecutive quarter of growth Added 1.3 million credit card accounts1 Record 3.6 million consumer investment accounts, with $37 billion net client flows since 1Q22 Grew digital sales 4% YoY to 1.8 million; digital sales represented 51% of total sales Grew average loans and leases 6% YoY to $381 billion Second best revenue quarter at $6.2 billion, up 19% YoY $3.1 billion Global Transaction Services revenue, up 47% YoY #3 in investment banking fees2 Grew sales and trading revenue to $5.1 billion Second highest quarterly sales and trading revenue in a decade Highest quarterly FICC3 revenue in a decade, up 27% YoY Average loans of $125 billion, up 15% YoY 1 Includes credit cards across Consumer Banking, Small Business, and Global Wealth & Investment Management. 2 Source: Dealogic as of April 1, 2023. 3 FICC stands for Fixed Income, Currencies, and Commodities.

3Q19-2Q21 Break in operating leverage streak Revenue (7%) (5%) (2%) 1% (3%) 1% 3% 2% 7% 7% 1% 7% 4% (1%) 4% 6% —% 2% 12% 10% 2% 6% 8% 11% 13% Expense (29%) (25%) (31%) (2%) (10%) (2%) (1%) (4%) (1%) 1% (3%) (1%) (1%) (5%) (2%) (1%) (4%) —% —% 6% (1%) 2% 6% 6% 6% Extended Quarterly Operating Leverage1 Streak 17 Note: Amounts may not total due to rounding. Operating leverage is calculated as the year-over-year percentage change in revenue, net of interest expense, less the percentage change in noninterest expense. 1 Operating leverage calculated after adjusting 4Q17 revenue for the impact of the Tax Cuts and Jobs Act is a non-GAAP financial measure. Reported revenue growth and operating leverage were 11% and 12% for 4Q18, and 2% and 3% for 4Q17. Reported revenue was $22.7B, $20.4B, and $20.0B for 4Q18, 4Q17, and 4Q16, respectively. Excluding a $0.9B noninterest income charge from enactment of the Tax Act, 4Q17 revenue was $21.4B. For important presentation information, see slide 38.
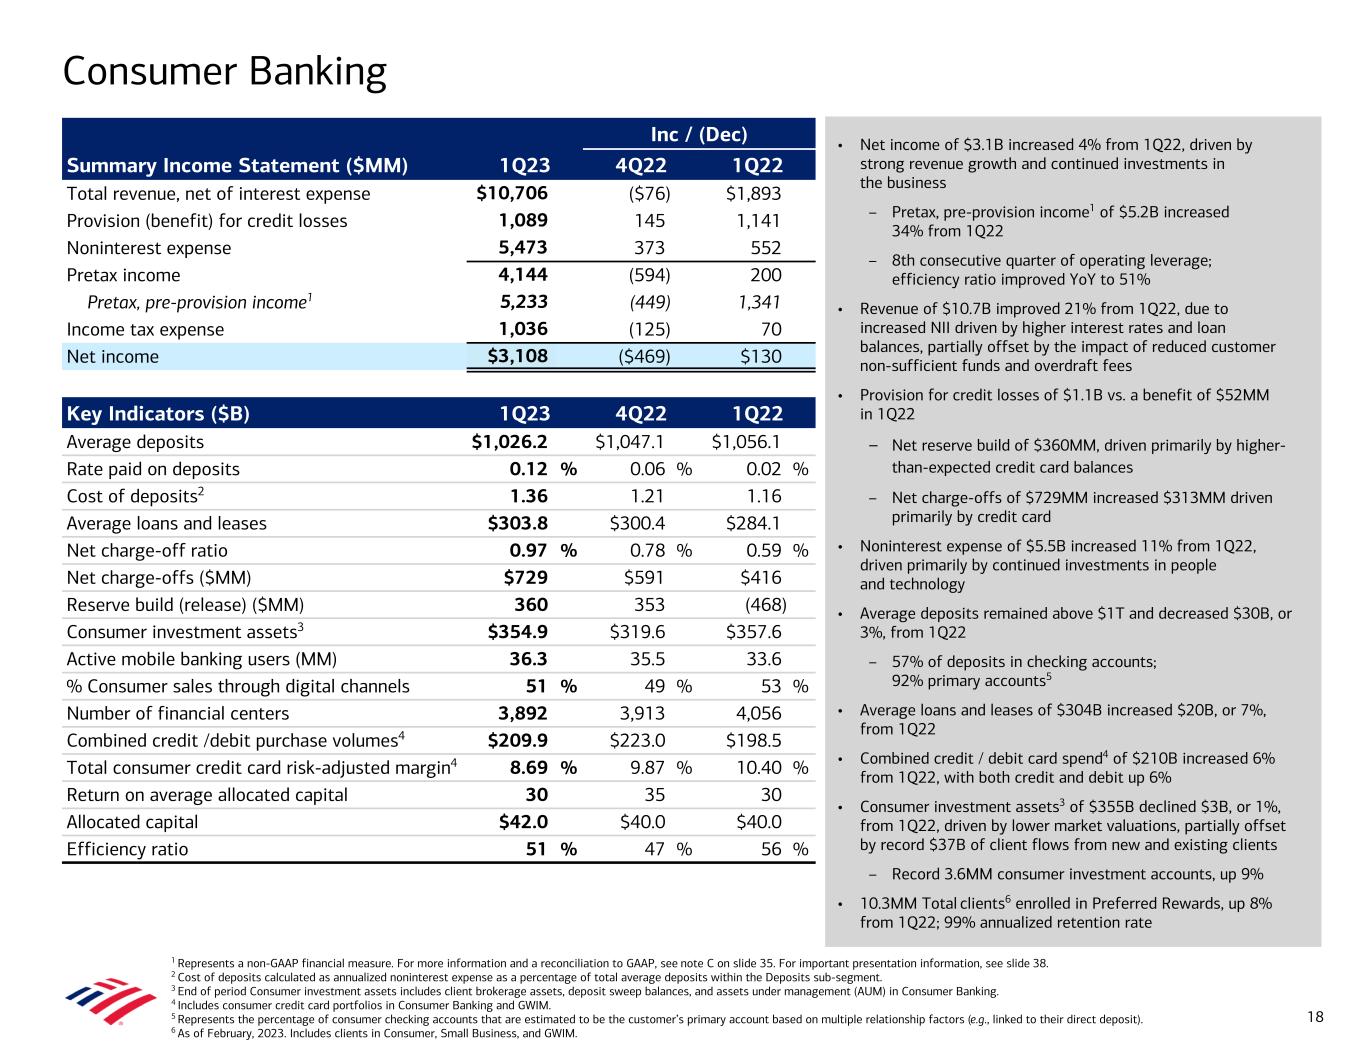
• Net income of $3.1B increased 4% from 1Q22, driven by strong revenue growth and continued investments in the business – Pretax, pre-provision income1 of $5.2B increased 34% from 1Q22 – 8th consecutive quarter of operating leverage; efficiency ratio improved YoY to 51% • Revenue of $10.7B improved 21% from 1Q22, due to increased NII driven by higher interest rates and loan balances, partially offset by the impact of reduced customer non-sufficient funds and overdraft fees • Provision for credit losses of $1.1B vs. a benefit of $52MM in 1Q22 – Net reserve build of $360MM, driven primarily by higher- than-expected credit card balances – Net charge-offs of $729MM increased $313MM driven primarily by credit card • Noninterest expense of $5.5B increased 11% from 1Q22, driven primarily by continued investments in people and technology • Average deposits remained above $1T and decreased $30B, or 3%, from 1Q22 – 57% of deposits in checking accounts; 92% primary accounts5 • Average loans and leases of $304B increased $20B, or 7%, from 1Q22 • Combined credit / debit card spend4 of $210B increased 6% from 1Q22, with both credit and debit up 6% • Consumer investment assets3 of $355B declined $3B, or 1%, from 1Q22, driven by lower market valuations, partially offset by record $37B of client flows from new and existing clients – Record 3.6MM consumer investment accounts, up 9% • 10.3MM Total clients6 enrolled in Preferred Rewards, up 8% from 1Q22; 99% annualized retention rate Consumer Banking 1 Represents a non-GAAP financial measure. For more information and a reconciliation to GAAP, see note C on slide 35. For important presentation information, see slide 38. 2 Cost of deposits calculated as annualized noninterest expense as a percentage of total average deposits within the Deposits sub-segment. 3 End of period Consumer investment assets includes client brokerage assets, deposit sweep balances, and assets under management (AUM) in Consumer Banking. 4 Includes consumer credit card portfolios in Consumer Banking and GWIM. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 As of February, 2023. Includes clients in Consumer, Small Business, and GWIM. Inc / (Dec) Summary Income Statement ($MM) 1Q23 4Q22 1Q22 Total revenue, net of interest expense $10,706 ($76) $1,893 Provision (benefit) for credit losses 1,089 145 1,141 Noninterest expense 5,473 373 552 Pretax income 4,144 (594) 200 Pretax, pre-provision income1 5,233 (449) 1,341 Income tax expense 1,036 (125) 70 Net income $3,108 ($469) $130 Key Indicators ($B) 1Q23 4Q22 1Q22 Average deposits $1,026.2 $1,047.1 $1,056.1 Rate paid on deposits 0.12 % 0.06 % 0.02 % Cost of deposits2 1.36 1.21 1.16 Average loans and leases $303.8 $300.4 $284.1 Net charge-off ratio 0.97 % 0.78 % 0.59 % Net charge-offs ($MM) $729 $591 $416 Reserve build (release) ($MM) 360 353 (468) Consumer investment assets3 $354.9 $319.6 $357.6 Active mobile banking users (MM) 36.3 35.5 33.6 % Consumer sales through digital channels 51 % 49 % 53 % Number of financial centers 3,892 3,913 4,056 Combined credit /debit purchase volumes4 $209.9 $223.0 $198.5 Total consumer credit card risk-adjusted margin4 8.69 % 9.87 % 10.40 % Return on average allocated capital 30 35 30 Allocated capital $42.0 $40.0 $40.0 Efficiency ratio 51 % 47 % 56 % 18
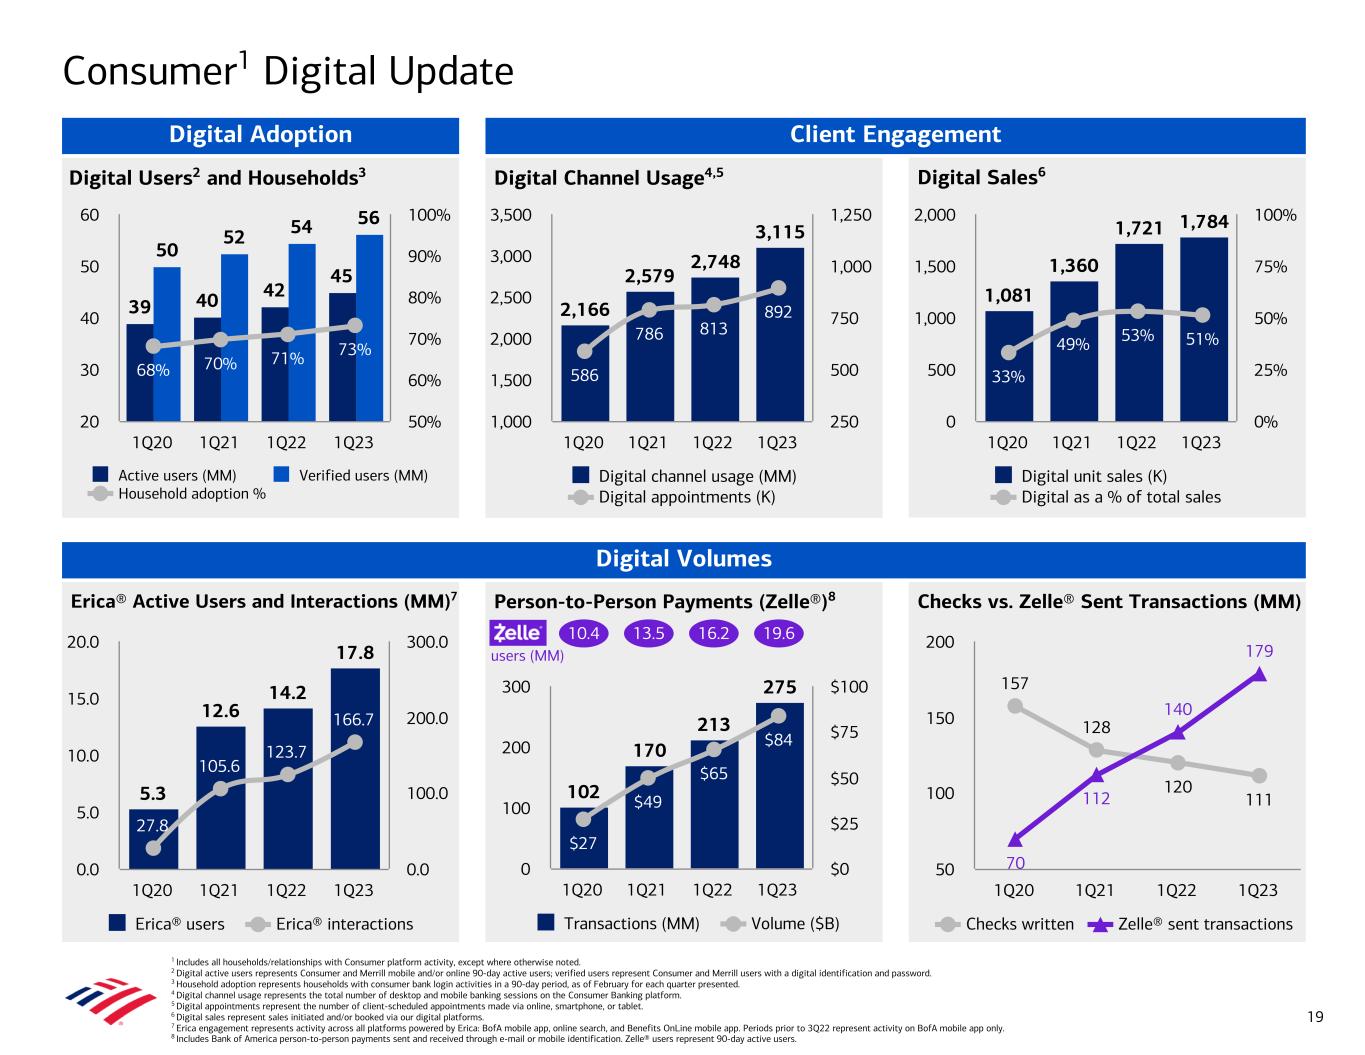
Erica® Active Users and Interactions (MM)7 Checks vs. Zelle® Sent Transactions (MM) Digital Sales6Digital Users2 and Households3 Digital Channel Usage4,5 1,081 1,360 1,721 1,784 33% 49% 53% 51% Digital unit sales (K) Digital as a % of total sales 1Q20 1Q21 1Q22 1Q23 0 500 1,000 1,500 2,000 0% 25% 50% 75% 100% 2,166 2,579 2,748 3,115 586 786 813 892 Digital channel usage (MM) Digital appointments (K) 1Q20 1Q21 1Q22 1Q23 1,000 1,500 2,000 2,500 3,000 3,500 250 500 750 1,000 1,250 39 40 42 45 50 52 54 56 68% 70% 71% 73% Active users (MM) Verified users (MM) Household adoption % 1Q20 1Q21 1Q22 1Q23 20 30 40 50 60 50% 60% 70% 80% 90% 100% Client Engagement Person-to-Person Payments (Zelle®)8 Digital Volumes 102 170 213 275 $27 $49 $65 $84 Transactions (MM) Volume ($B) 1Q20 1Q21 1Q22 1Q23 0 100 200 300 $0 $25 $50 $75 $100 Consumer1 Digital Update 1 Includes all households/relationships with Consumer platform activity, except where otherwise noted. 2 Digital active users represents Consumer and Merrill mobile and/or online 90-day active users; verified users represent Consumer and Merrill users with a digital identification and password. 3 Household adoption represents households with consumer bank login activities in a 90-day period, as of February for each quarter presented. 4 Digital channel usage represents the total number of desktop and mobile banking sessions on the Consumer Banking platform. 5 Digital appointments represent the number of client-scheduled appointments made via online, smartphone, or tablet. 6 Digital sales represent sales initiated and/or booked via our digital platforms. 7 Erica engagement represents activity across all platforms powered by Erica: BofA mobile app, online search, and Benefits OnLine mobile app. Periods prior to 3Q22 represent activity on BofA mobile app only. 8 Includes Bank of America person-to-person payments sent and received through e-mail or mobile identification. Zelle® users represent 90-day active users. 10.4 13.5 16.2 19.6 users (MM) 19 Digital Adoption 5.3 12.6 14.2 17.8 27.8 105.6 123.7 166.7 Erica® users Erica® interactions 1Q20 1Q21 1Q22 1Q23 0.0 5.0 10.0 15.0 20.0 0.0 100.0 200.0 300.0 157 128 120 111 70 112 140 179 Checks written Zelle® sent transactions 1Q20 1Q21 1Q22 1Q23 50 100 150 200
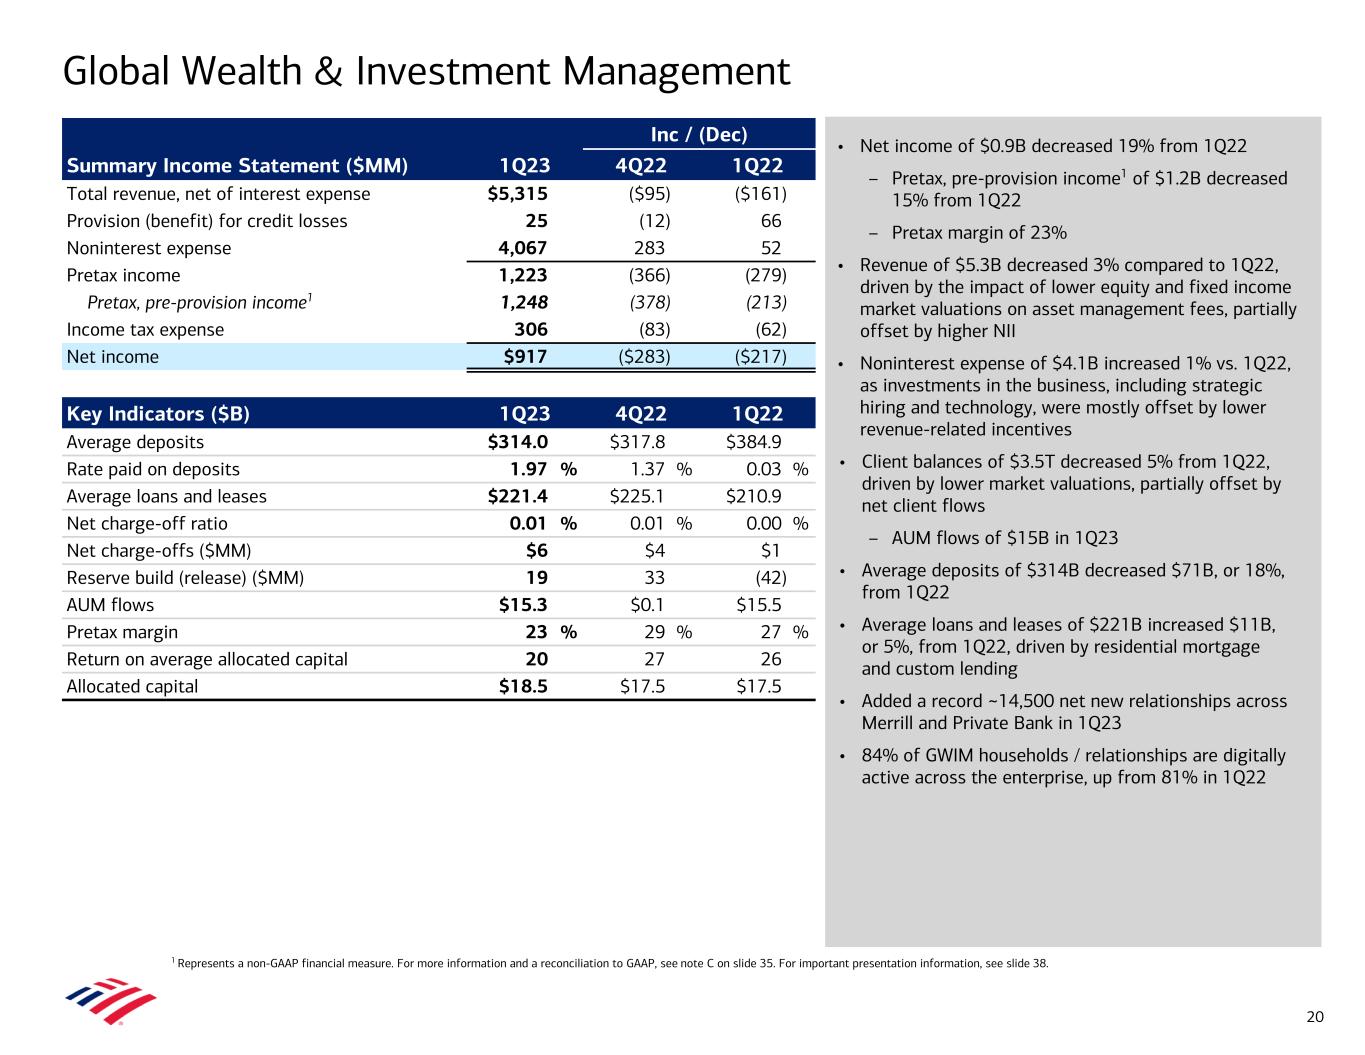
• Net income of $0.9B decreased 19% from 1Q22 – Pretax, pre-provision income1 of $1.2B decreased 15% from 1Q22 – Pretax margin of 23% • Revenue of $5.3B decreased 3% compared to 1Q22, driven by the impact of lower equity and fixed income market valuations on asset management fees, partially offset by higher NII • Noninterest expense of $4.1B increased 1% vs. 1Q22, as investments in the business, including strategic hiring and technology, were mostly offset by lower revenue-related incentives • Client balances of $3.5T decreased 5% from 1Q22, driven by lower market valuations, partially offset by net client flows – AUM flows of $15B in 1Q23 • Average deposits of $314B decreased $71B, or 18%, from 1Q22 • Average loans and leases of $221B increased $11B, or 5%, from 1Q22, driven by residential mortgage and custom lending • Added a record ~14,500 net new relationships across Merrill and Private Bank in 1Q23 • 84% of GWIM households / relationships are digitally active across the enterprise, up from 81% in 1Q22 Global Wealth & Investment Management 1 Represents a non-GAAP financial measure. For more information and a reconciliation to GAAP, see note C on slide 35. For important presentation information, see slide 38. Inc / (Dec) Summary Income Statement ($MM) 1Q23 4Q22 1Q22 Total revenue, net of interest expense $5,315 ($95) ($161) Provision (benefit) for credit losses 25 (12) 66 Noninterest expense 4,067 283 52 Pretax income 1,223 (366) (279) Pretax, pre-provision income1 1,248 (378) (213) Income tax expense 306 (83) (62) Net income $917 ($283) ($217) Key Indicators ($B) 1Q23 4Q22 1Q22 Average deposits $314.0 $317.8 $384.9 Rate paid on deposits 1.97 % 1.37 % 0.03 % Average loans and leases $221.4 $225.1 $210.9 Net charge-off ratio 0.01 % 0.01 % 0.00 % Net charge-offs ($MM) $6 $4 $1 Reserve build (release) ($MM) 19 33 (42) AUM flows $15.3 $0.1 $15.5 Pretax margin 23 % 29 % 27 % Return on average allocated capital 20 27 26 Allocated capital $18.5 $17.5 $17.5 20
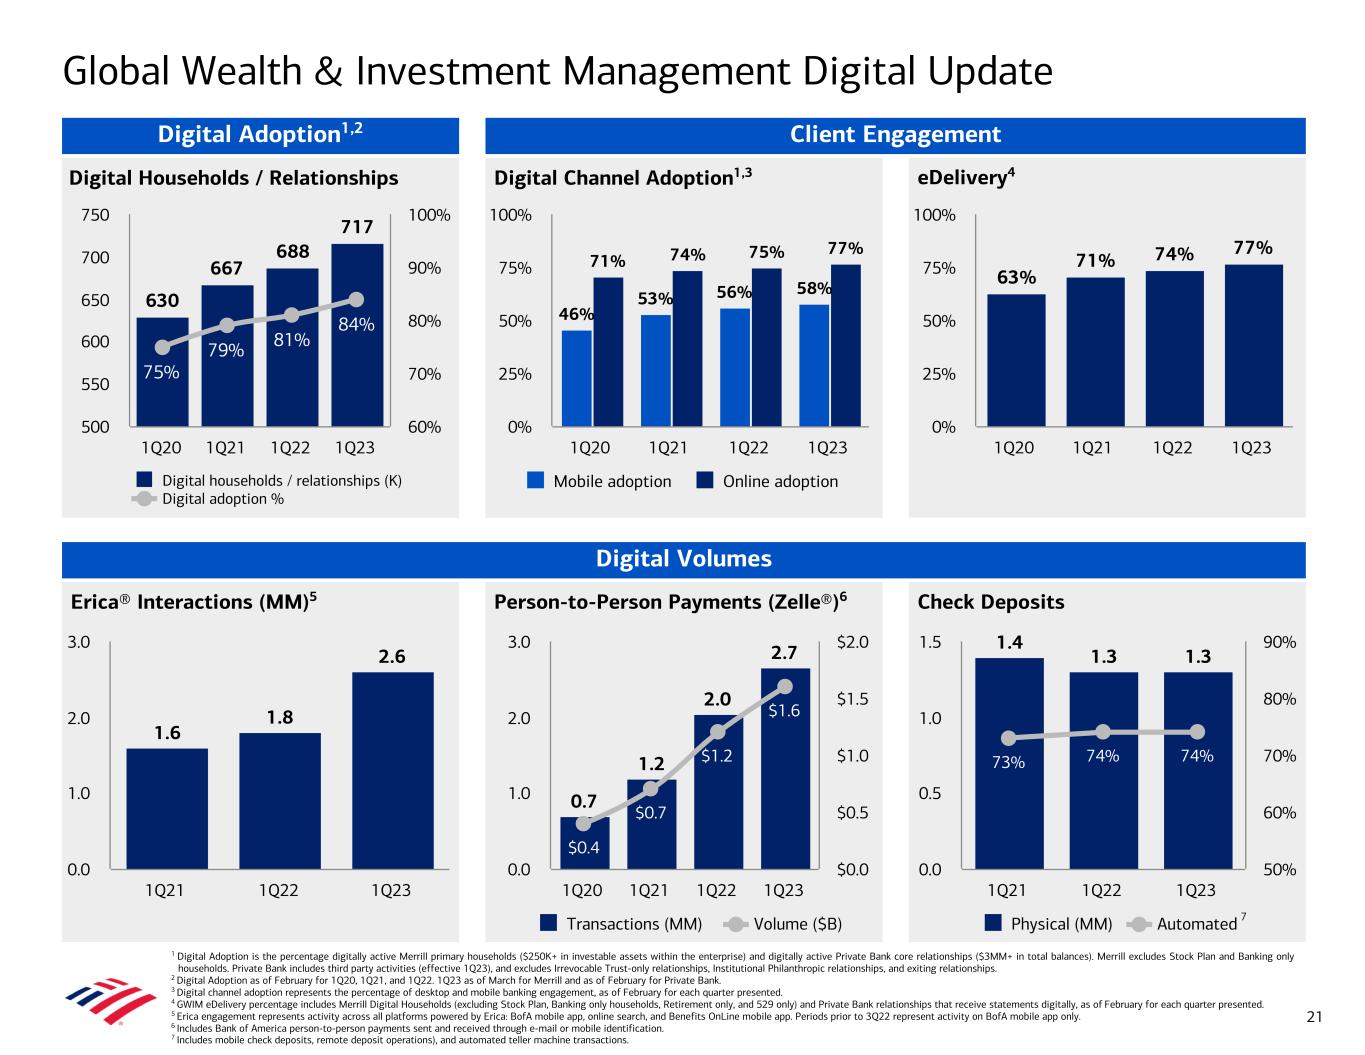
Erica® Interactions (MM)5 1.6 1.8 2.6 1Q21 1Q22 1Q23 0.0 1.0 2.0 3.0 Person-to-Person Payments (Zelle®)6 Check Deposits eDelivery4Digital Households / Relationships Digital Channel Adoption1,3 63% 71% 74% 77% 1Q20 1Q21 1Q22 1Q23 0% 25% 50% 75% 100% 46% 53% 56% 58% 71% 74% 75% 77% Mobile adoption Online adoption 1Q20 1Q21 1Q22 1Q23 0% 25% 50% 75% 100% 630 667 688 717 75% 79% 81% 84% Digital households / relationships (K) Digital adoption % 1Q20 1Q21 1Q22 1Q23 500 550 600 650 700 750 60% 70% 80% 90% 100% Client Engagement Digital Volumes Global Wealth & Investment Management Digital Update 1 Digital Adoption is the percentage digitally active Merrill primary households ($250K+ in investable assets within the enterprise) and digitally active Private Bank core relationships ($3MM+ in total balances). Merrill excludes Stock Plan and Banking only households. Private Bank includes third party activities (effective 1Q23), and excludes Irrevocable Trust-only relationships, Institutional Philanthropic relationships, and exiting relationships. 2 Digital Adoption as of February for 1Q20, 1Q21, and 1Q22. 1Q23 as of March for Merrill and as of February for Private Bank. 3 Digital channel adoption represents the percentage of desktop and mobile banking engagement, as of February for each quarter presented. 4 GWIM eDelivery percentage includes Merrill Digital Households (excluding Stock Plan, Banking only households, Retirement only, and 529 only) and Private Bank relationships that receive statements digitally, as of February for each quarter presented. 5 Erica engagement represents activity across all platforms powered by Erica: BofA mobile app, online search, and Benefits OnLine mobile app. Periods prior to 3Q22 represent activity on BofA mobile app only. 6 Includes Bank of America person-to-person payments sent and received through e-mail or mobile identification. 7 Includes mobile check deposits, remote deposit operations), and automated teller machine transactions. 21 Digital Adoption1,2 0.7 1.2 2.0 2.7 $0.4 $0.7 $1.2 $1.6 Transactions (MM) Volume ($B) 1Q20 1Q21 1Q22 1Q23 0.0 1.0 2.0 3.0 $0.0 $0.5 $1.0 $1.5 $2.0 1.4 1.3 1.3 73% 74% 74% Physical (MM) Automated 1Q21 1Q22 1Q23 0.0 0.5 1.0 1.5 50% 60% 70% 80% 90% 7
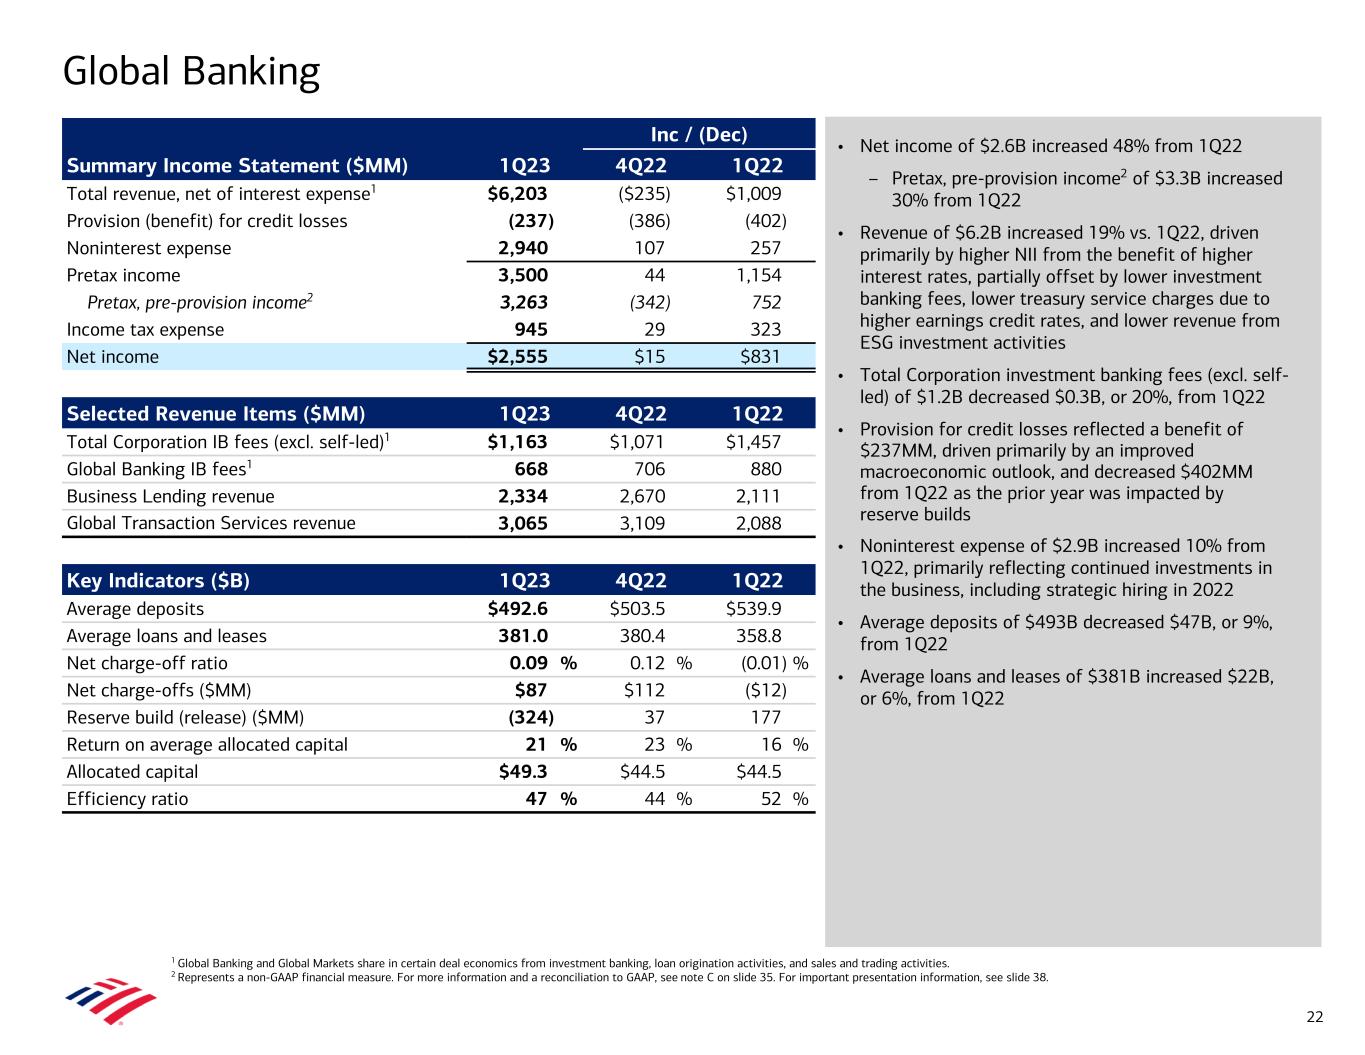
• Net income of $2.6B increased 48% from 1Q22 – Pretax, pre-provision income2 of $3.3B increased 30% from 1Q22 • Revenue of $6.2B increased 19% vs. 1Q22, driven primarily by higher NII from the benefit of higher interest rates, partially offset by lower investment banking fees, lower treasury service charges due to higher earnings credit rates, and lower revenue from ESG investment activities • Total Corporation investment banking fees (excl. self- led) of $1.2B decreased $0.3B, or 20%, from 1Q22 • Provision for credit losses reflected a benefit of $237MM, driven primarily by an improved macroeconomic outlook, and decreased $402MM from 1Q22 as the prior year was impacted by reserve builds • Noninterest expense of $2.9B increased 10% from 1Q22, primarily reflecting continued investments in the business, including strategic hiring in 2022 • Average deposits of $493B decreased $47B, or 9%, from 1Q22 • Average loans and leases of $381B increased $22B, or 6%, from 1Q22 Global Banking 1 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to GAAP, see note C on slide 35. For important presentation information, see slide 38. Inc / (Dec) Summary Income Statement ($MM) 1Q23 4Q22 1Q22 Total revenue, net of interest expense1 $6,203 ($235) $1,009 Provision (benefit) for credit losses (237) (386) (402) Noninterest expense 2,940 107 257 Pretax income 3,500 44 1,154 Pretax, pre-provision income2 3,263 (342) 752 Income tax expense 945 29 323 Net income $2,555 $15 $831 Selected Revenue Items ($MM) 1Q23 4Q22 1Q22 Total Corporation IB fees (excl. self-led)1 $1,163 $1,071 $1,457 Global Banking IB fees1 668 706 880 Business Lending revenue 2,334 2,670 2,111 Global Transaction Services revenue 3,065 3,109 2,088 Key Indicators ($B) 1Q23 4Q22 1Q22 Average deposits $492.6 $503.5 $539.9 Average loans and leases 381.0 380.4 358.8 Net charge-off ratio 0.09 % 0.12 % (0.01) % Net charge-offs ($MM) $87 $112 ($12) Reserve build (release) ($MM) (324) 37 177 Return on average allocated capital 21 % 23 % 16 % Allocated capital $49.3 $44.5 $44.5 Efficiency ratio 47 % 44 % 52 % 22
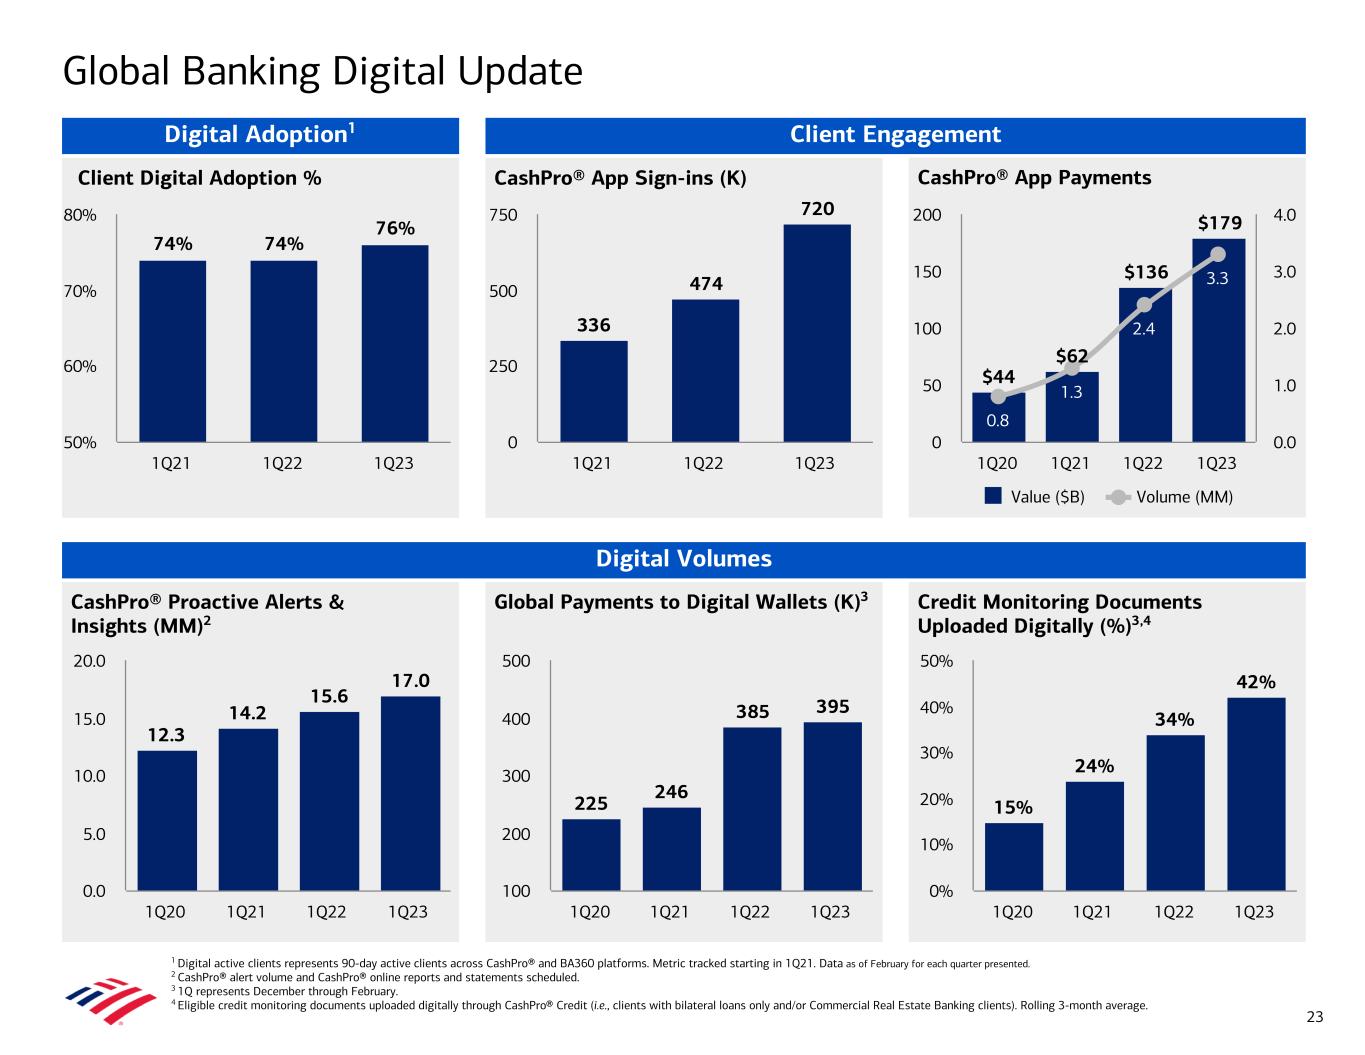
Credit Monitoring Documents Uploaded Digitally (%)3,4 CashPro® Proactive Alerts & Insights (MM)2 Global Payments to Digital Wallets (K)3 15% 24% 34% 42% 1Q20 1Q21 1Q22 1Q23 0% 10% 20% 30% 40% 50% 225 246 385 395 1Q20 1Q21 1Q22 1Q23 100 200 300 400 500 12.3 14.2 15.6 17.0 1Q20 1Q21 1Q22 1Q23 0.0 5.0 10.0 15.0 20.0 CashPro® App PaymentsClient Digital Adoption % CashPro® App Sign-ins (K) $44 $62 $136 $179 0.8 1.3 2.4 3.3 Value ($B) Volume (MM) 1Q20 1Q21 1Q22 1Q23 0 50 100 150 200 0.0 1.0 2.0 3.0 4.0 336 474 720 1Q21 1Q22 1Q23 0 250 500 750 74% 74% 76% 1Q21 1Q22 1Q23 50% 60% 70% 80% Client Engagement Digital Volumes Global Banking Digital Update 23 Digital Adoption1 1 Digital active clients represents 90-day active clients across CashPro® and BA360 platforms. Metric tracked starting in 1Q21. Data as of February for each quarter presented. 2 CashPro® alert volume and CashPro® online reports and statements scheduled. 3 1Q represents December through February. 4 Eligible credit monitoring documents uploaded digitally through CashPro® Credit (i.e., clients with bilateral loans only and/or Commercial Real Estate Banking clients). Rolling 3-month average.
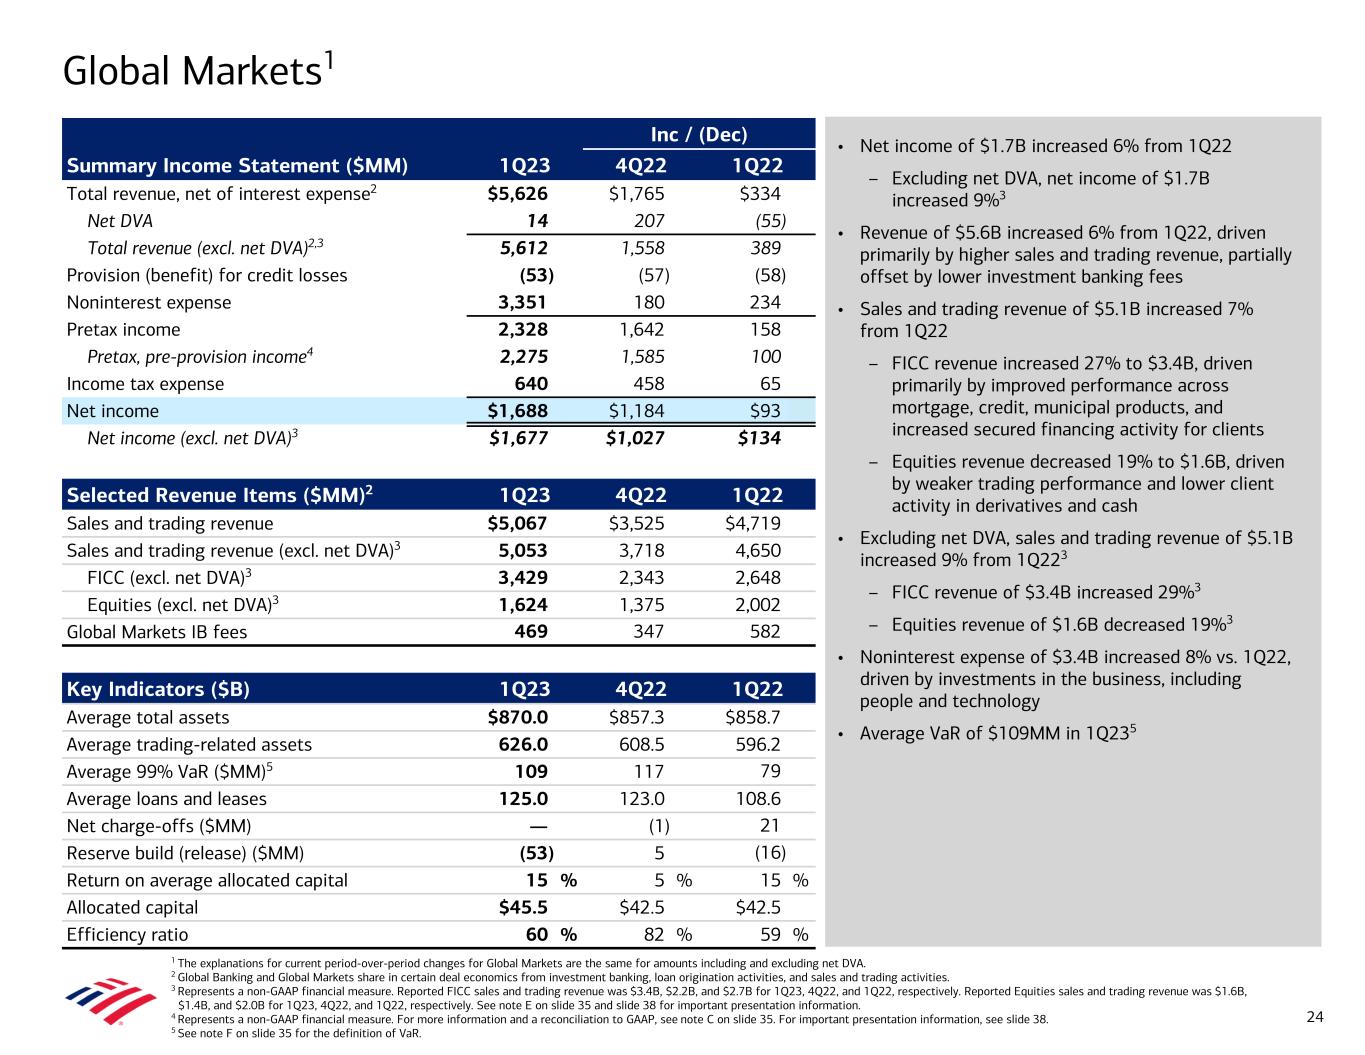
Global Markets1 • Net income of $1.7B increased 6% from 1Q22 – Excluding net DVA, net income of $1.7B increased 9%3 • Revenue of $5.6B increased 6% from 1Q22, driven primarily by higher sales and trading revenue, partially offset by lower investment banking fees • Sales and trading revenue of $5.1B increased 7% from 1Q22 – FICC revenue increased 27% to $3.4B, driven primarily by improved performance across mortgage, credit, municipal products, and increased secured financing activity for clients – Equities revenue decreased 19% to $1.6B, driven by weaker trading performance and lower client activity in derivatives and cash • Excluding net DVA, sales and trading revenue of $5.1B increased 9% from 1Q223 – FICC revenue of $3.4B increased 29%3 – Equities revenue of $1.6B decreased 19%3 • Noninterest expense of $3.4B increased 8% vs. 1Q22, driven by investments in the business, including people and technology • Average VaR of $109MM in 1Q235 1 The explanations for current period-over-period changes for Global Markets are the same for amounts including and excluding net DVA. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Represents a non-GAAP financial measure. Reported FICC sales and trading revenue was $3.4B, $2.2B, and $2.7B for 1Q23, 4Q22, and 1Q22, respectively. Reported Equities sales and trading revenue was $1.6B, $1.4B, and $2.0B for 1Q23, 4Q22, and 1Q22, respectively. See note E on slide 35 and slide 38 for important presentation information. 4 Represents a non-GAAP financial measure. For more information and a reconciliation to GAAP, see note C on slide 35. For important presentation information, see slide 38. 5 See note F on slide 35 for the definition of VaR. Inc / (Dec) Summary Income Statement ($MM) 1Q23 4Q22 1Q22 Total revenue, net of interest expense2 $5,626 $1,765 $334 Net DVA 14 207 (55) Total revenue (excl. net DVA)2,3 5,612 1,558 389 Provision (benefit) for credit losses (53) (57) (58) Noninterest expense 3,351 180 234 Pretax income 2,328 1,642 158 Pretax, pre-provision income4 2,275 1,585 100 Income tax expense 640 458 65 Net income $1,688 $1,184 $93 Net income (excl. net DVA)3 $1,677 $1,027 $134 Selected Revenue Items ($MM)2 1Q23 4Q22 1Q22 Sales and trading revenue $5,067 $3,525 $4,719 Sales and trading revenue (excl. net DVA)3 5,053 3,718 4,650 FICC (excl. net DVA)3 3,429 2,343 2,648 Equities (excl. net DVA)3 1,624 1,375 2,002 Global Markets IB fees 469 347 582 Key Indicators ($B) 1Q23 4Q22 1Q22 Average total assets $870.0 $857.3 $858.7 Average trading-related assets 626.0 608.5 596.2 Average 99% VaR ($MM)5 109 117 79 Average loans and leases 125.0 123.0 108.6 Net charge-offs ($MM) — (1) 21 Reserve build (release) ($MM) (53) 5 (16) Return on average allocated capital 15 % 5 % 15 % Allocated capital $45.5 $42.5 $42.5 Efficiency ratio 60 % 82 % 59 % 24
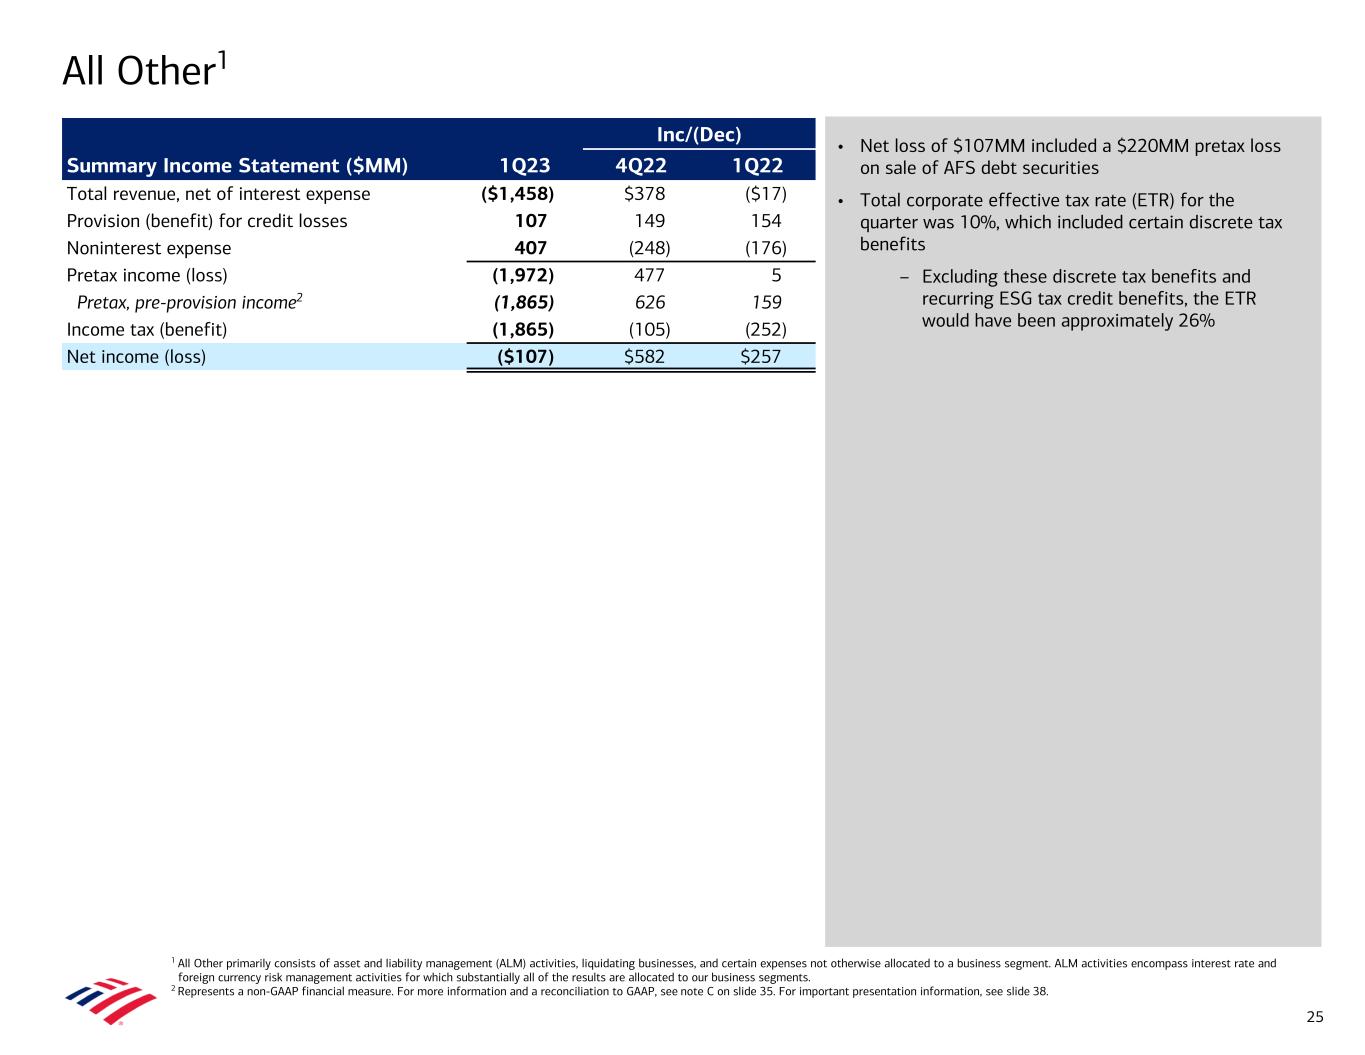
All Other1 • Net loss of $107MM included a $220MM pretax loss on sale of AFS debt securities • Total corporate effective tax rate (ETR) for the quarter was 10%, which included certain discrete tax benefits – Excluding these discrete tax benefits and recurring ESG tax credit benefits, the ETR would have been approximately 26% 1 All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses, and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to GAAP, see note C on slide 35. For important presentation information, see slide 38. Inc/(Dec) Summary Income Statement ($MM) 1Q23 4Q22 1Q22 Total revenue, net of interest expense ($1,458) $378 ($17) Provision (benefit) for credit losses 107 149 154 Noninterest expense 407 (248) (176) Pretax income (loss) (1,972) 477 5 Pretax, pre-provision income2 (1,865) 626 159 Income tax (benefit) (1,865) (105) (252) Net income (loss) ($107) $582 $257 25
Supplemental Business Segment Trends
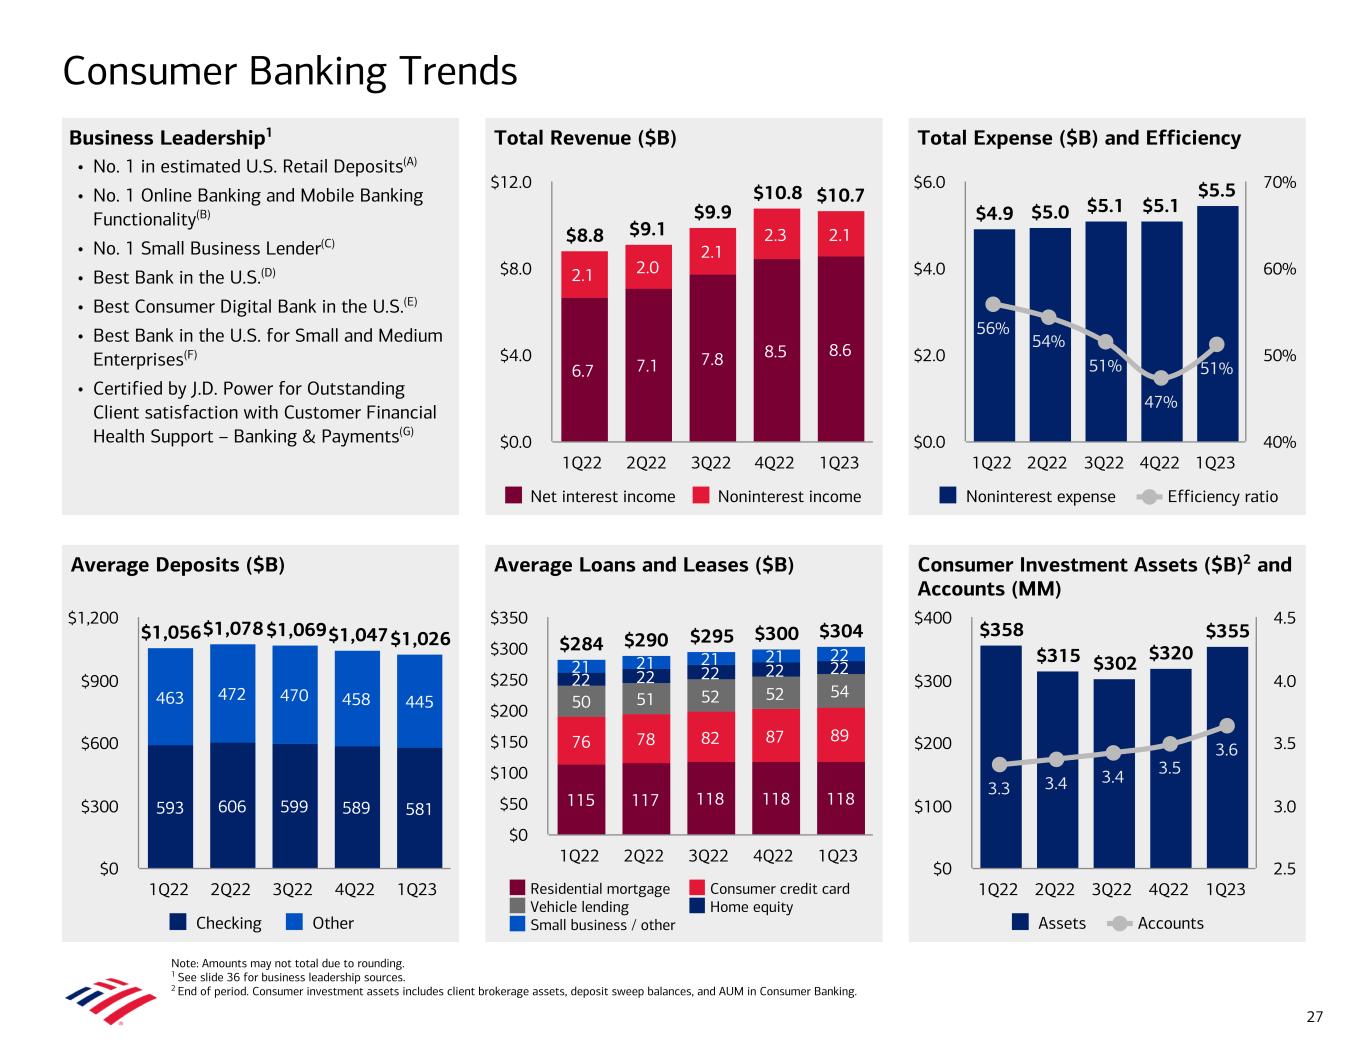
Total Expense ($B) and Efficiency Business Leadership1 • No. 1 in estimated U.S. Retail Deposits(A) • No. 1 Online Banking and Mobile Banking Functionality(B) • No. 1 Small Business Lender(C) • Best Bank in the U.S.(D) • Best Consumer Digital Bank in the U.S.(E) • Best Bank in the U.S. for Small and Medium Enterprises(F) • Certified by J.D. Power for Outstanding Client satisfaction with Customer Financial Health Support – Banking & Payments(G) Total Revenue ($B) Average Deposits ($B) Consumer Investment Assets ($B)2 and Accounts (MM) Average Loans and Leases ($B) Consumer Banking Trends Note: Amounts may not total due to rounding. 1 See slide 36 for business leadership sources. 2 End of period. Consumer investment assets includes client brokerage assets, deposit sweep balances, and AUM in Consumer Banking. $8.8 $9.1 $9.9 $10.8 $10.7 6.7 7.1 7.8 8.5 8.6 2.1 2.0 2.1 2.3 2.1 Net interest income Noninterest income 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $4.0 $8.0 $12.0 $4.9 $5.0 $5.1 $5.1 $5.5 56% 54% 51% 47% 51% Noninterest expense Efficiency ratio 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $2.0 $4.0 $6.0 40% 50% 60% 70% $1,056$1,078$1,069$1,047$1,026 593 606 599 589 581 463 472 470 458 445 Checking Other 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $300 $600 $900 $1,200 $284 $290 $295 $300 $304 115 117 118 118 118 76 78 82 87 89 50 51 52 52 54 22 22 22 22 2221 21 21 21 22 Residential mortgage Consumer credit card Vehicle lending Home equity Small business / other 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $50 $100 $150 $200 $250 $300 $350 27 $358 $315 $302 $320 $355 3.3 3.4 3.4 3.5 3.6 Assets Accounts 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $100 $200 $300 $400 2.5 3.0 3.5 4.0 4.5
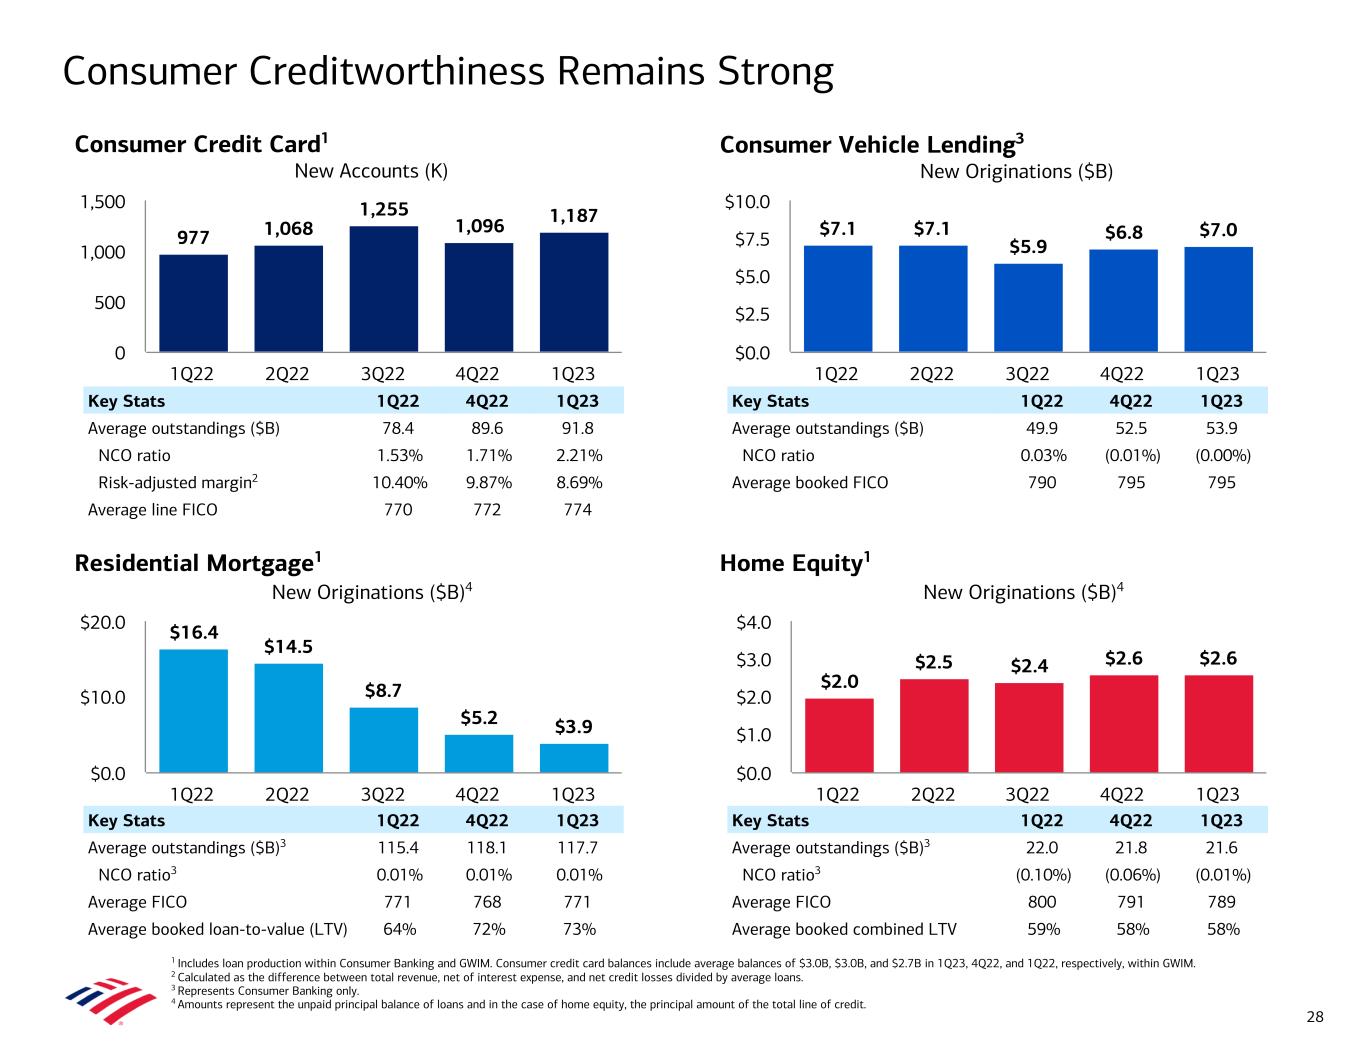
977 1,068 1,255 1,096 1,187 1Q22 2Q22 3Q22 4Q22 1Q23 0 500 1,000 1,500 Home Equity1 New Originations ($B)4 Consumer Creditworthiness Remains Strong 1 Includes loan production within Consumer Banking and GWIM. Consumer credit card balances include average balances of $3.0B, $3.0B, and $2.7B in 1Q23, 4Q22, and 1Q22, respectively, within GWIM. 2 Calculated as the difference between total revenue, net of interest expense, and net credit losses divided by average loans. 3 Represents Consumer Banking only. 4 Amounts represent the unpaid principal balance of loans and in the case of home equity, the principal amount of the total line of credit. Consumer Vehicle Lending3 New Originations ($B) Consumer Credit Card1 New Accounts (K) 28 Residential Mortgage1 New Originations ($B)4 Key Stats 1Q22 4Q22 1Q23 Average outstandings ($B) 78.4 89.6 91.8 NCO ratio 1.53% 1.71% 2.21% Risk-adjusted margin2 10.40% 9.87% 8.69% Average line FICO 770 772 774 $7.1 $7.1 $5.9 $6.8 $7.0 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $2.5 $5.0 $7.5 $10.0 Key Stats 1Q22 4Q22 1Q23 Average outstandings ($B) 49.9 52.5 53.9 NCO ratio 0.03% (0.01%) (0.00%) Average booked FICO 790 795 795 $16.4 $14.5 $8.7 $5.2 $3.9 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $10.0 $20.0 Key Stats 1Q22 4Q22 1Q23 Average outstandings ($B)3 115.4 118.1 117.7 NCO ratio3 0.01% 0.01% 0.01% Average FICO 771 768 771 Average booked loan-to-value (LTV) 64% 72% 73% $2.0 $2.5 $2.4 $2.6 $2.6 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $1.0 $2.0 $3.0 $4.0 Key Stats 1Q22 4Q22 1Q23 Average outstandings ($B)3 22.0 21.8 21.6 NCO ratio3 (0.10%) (0.06%) (0.01%) Average FICO 800 791 789 Average booked combined LTV 59% 58% 58%
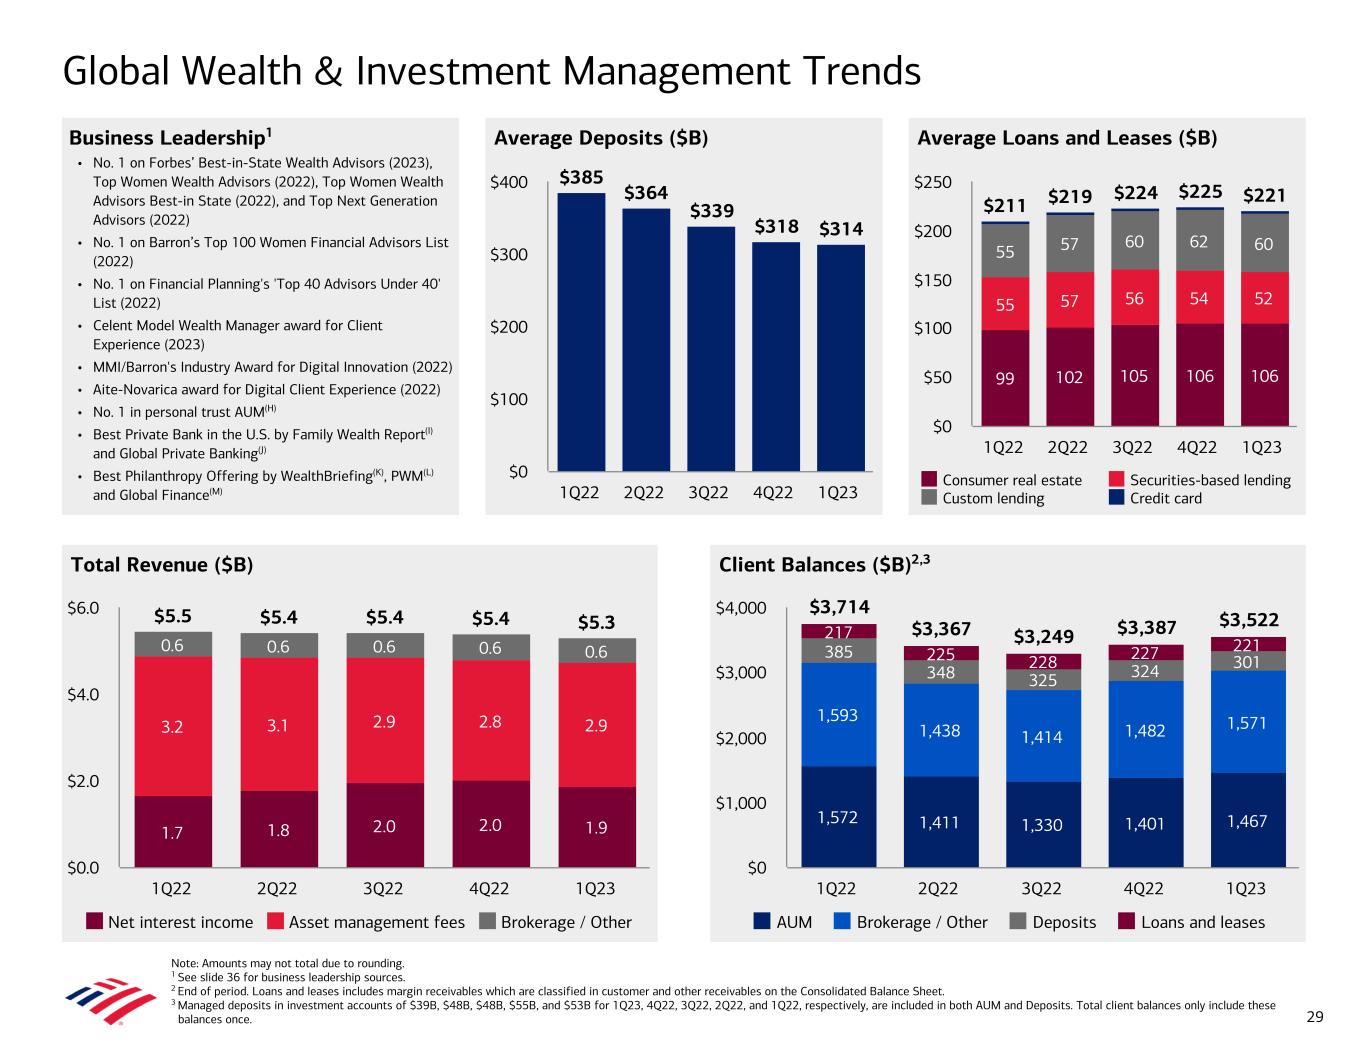
Average Deposits ($B) Global Wealth & Investment Management Trends Business Leadership1 • No. 1 on Forbes’ Best-in-State Wealth Advisors (2023), Top Women Wealth Advisors (2022), Top Women Wealth Advisors Best-in State (2022), and Top Next Generation Advisors (2022) • No. 1 on Barron’s Top 100 Women Financial Advisors List (2022) • No. 1 on Financial Planning's 'Top 40 Advisors Under 40' List (2022) • Celent Model Wealth Manager award for Client Experience (2023) • MMI/Barron's Industry Award for Digital Innovation (2022) • Aite-Novarica award for Digital Client Experience (2022) • No. 1 in personal trust AUM(H) • Best Private Bank in the U.S. by Family Wealth Report(I) and Global Private Banking(J) • Best Philanthropy Offering by WealthBriefing(K), PWM(L) and Global Finance(M) Note: Amounts may not total due to rounding. 1 See slide 36 for business leadership sources. 2 End of period. Loans and leases includes margin receivables which are classified in customer and other receivables on the Consolidated Balance Sheet. 3 Managed deposits in investment accounts of $39B, $48B, $48B, $55B, and $53B for 1Q23, 4Q22, 3Q22, 2Q22, and 1Q22, respectively, are included in both AUM and Deposits. Total client balances only include these balances once. Average Loans and Leases ($B) Total Revenue ($B) Client Balances ($B)2,3 $5.5 $5.4 $5.4 $5.4 $5.3 1.7 1.8 2.0 2.0 1.9 3.2 3.1 2.9 2.8 2.9 0.6 0.6 0.6 0.6 0.6 Net interest income Asset management fees Brokerage / Other 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $2.0 $4.0 $6.0 1,572 1,411 1,330 1,401 1,467 1,593 1,438 1,414 1,482 1,571 385 348 325 324 301 217 225 228 227 221 $3,714 $3,367 $3,249 $3,387 $3,522 AUM Brokerage / Other Deposits Loans and leases 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $1,000 $2,000 $3,000 $4,000 $211 $219 $224 $225 $221 99 102 105 106 106 55 57 56 54 52 55 57 60 62 60 Consumer real estate Securities-based lending Custom lending Credit card 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $50 $100 $150 $200 $250$385 $364 $339 $318 $314 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $100 $200 $300 $400 29
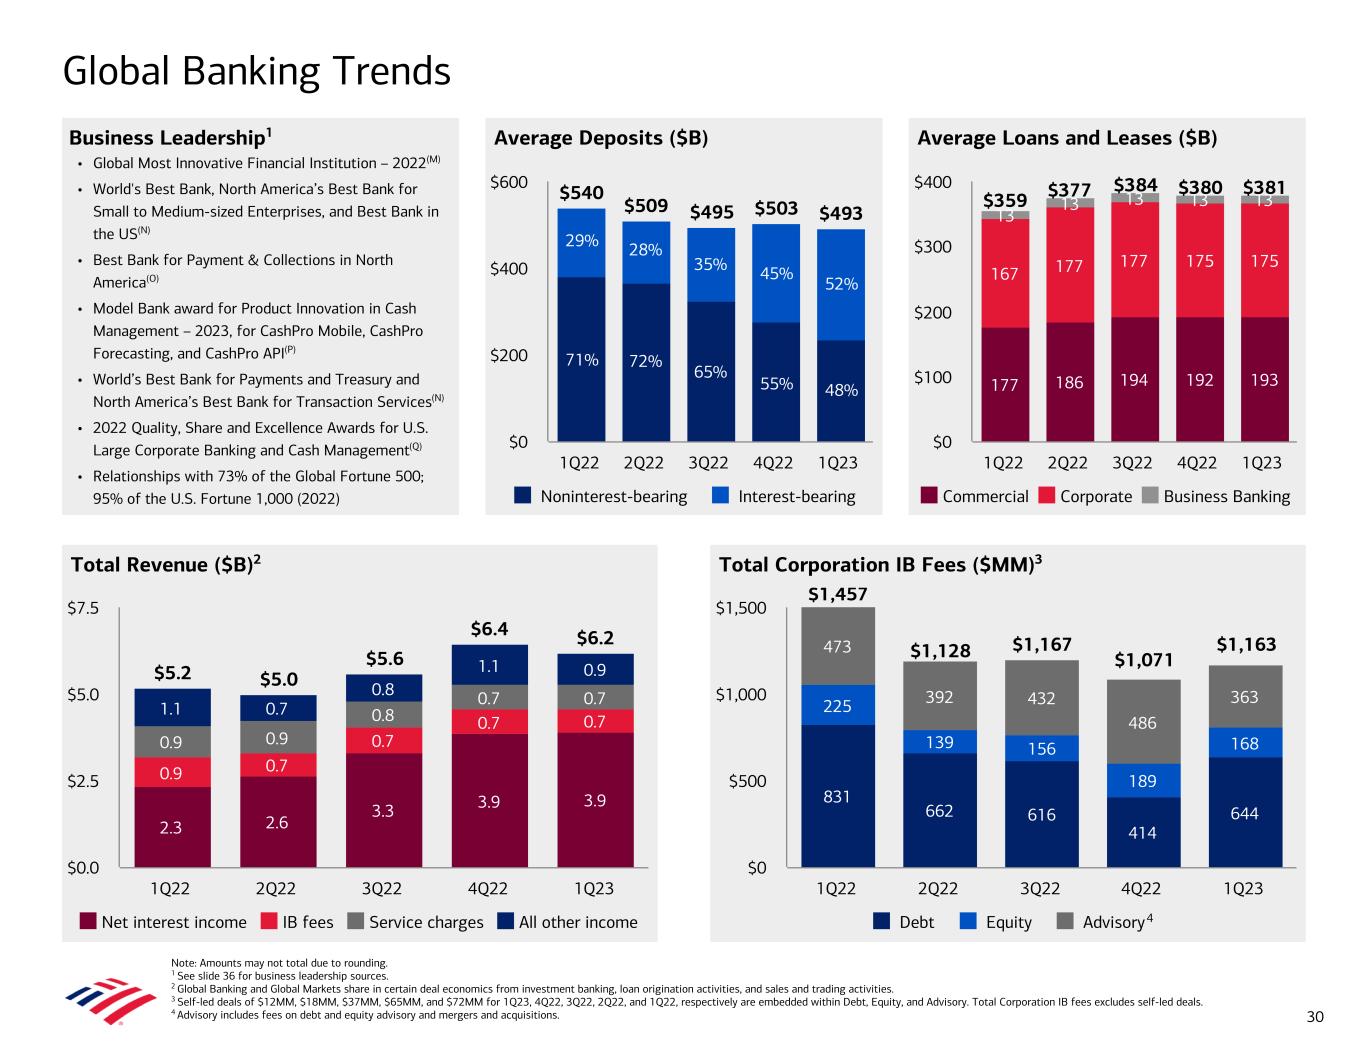
Global Banking Trends Note: Amounts may not total due to rounding. 1 See slide 36 for business leadership sources. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Self-led deals of $12MM, $18MM, $37MM, $65MM, and $72MM for 1Q23, 4Q22, 3Q22, 2Q22, and 1Q22, respectively are embedded within Debt, Equity, and Advisory. Total Corporation IB fees excludes self-led deals. 4 Advisory includes fees on debt and equity advisory and mergers and acquisitions. Average Deposits ($B)Business Leadership1 • Global Most Innovative Financial Institution – 2022(M) • World's Best Bank, North America’s Best Bank for Small to Medium-sized Enterprises, and Best Bank in the US(N) • Best Bank for Payment & Collections in North America(O) • Model Bank award for Product Innovation in Cash Management – 2023, for CashPro Mobile, CashPro Forecasting, and CashPro API(P) • World’s Best Bank for Payments and Treasury and North America’s Best Bank for Transaction Services(N) • 2022 Quality, Share and Excellence Awards for U.S. Large Corporate Banking and Cash Management(Q) • Relationships with 73% of the Global Fortune 500; 95% of the U.S. Fortune 1,000 (2022) Average Loans and Leases ($B) Total Revenue ($B)2 Total Corporation IB Fees ($MM)3 $5.2 $5.0 $5.6 $6.4 $6.2 2.3 2.6 3.3 3.9 3.9 0.9 0.7 0.7 0.7 0.7 0.9 0.9 0.8 0.7 0.7 1.1 0.7 0.8 1.1 0.9 Net interest income IB fees Service charges All other income 1Q22 2Q22 3Q22 4Q22 1Q23 $0.0 $2.5 $5.0 $7.5 831 662 616 414 644 225 139 156 189 168 473 392 432 486 363 $1,457 $1,128 $1,167 $1,071 $1,163 Debt Equity Advisory 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $500 $1,000 $1,500 177 186 194 192 193 167 177 177 175 175 13 13 13 13 13$359 $377 $384 $380 $381 Commercial Corporate Business Banking 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $100 $200 $300 $400 4 $540 $509 $495 $503 $493 Noninterest-bearing Interest-bearing 1Q22 2Q22 3Q22 4Q22 1Q23 $0 $200 $400 $600 30 71% 72% 65% 55% 48% 29% 28% 35% 45% 52%
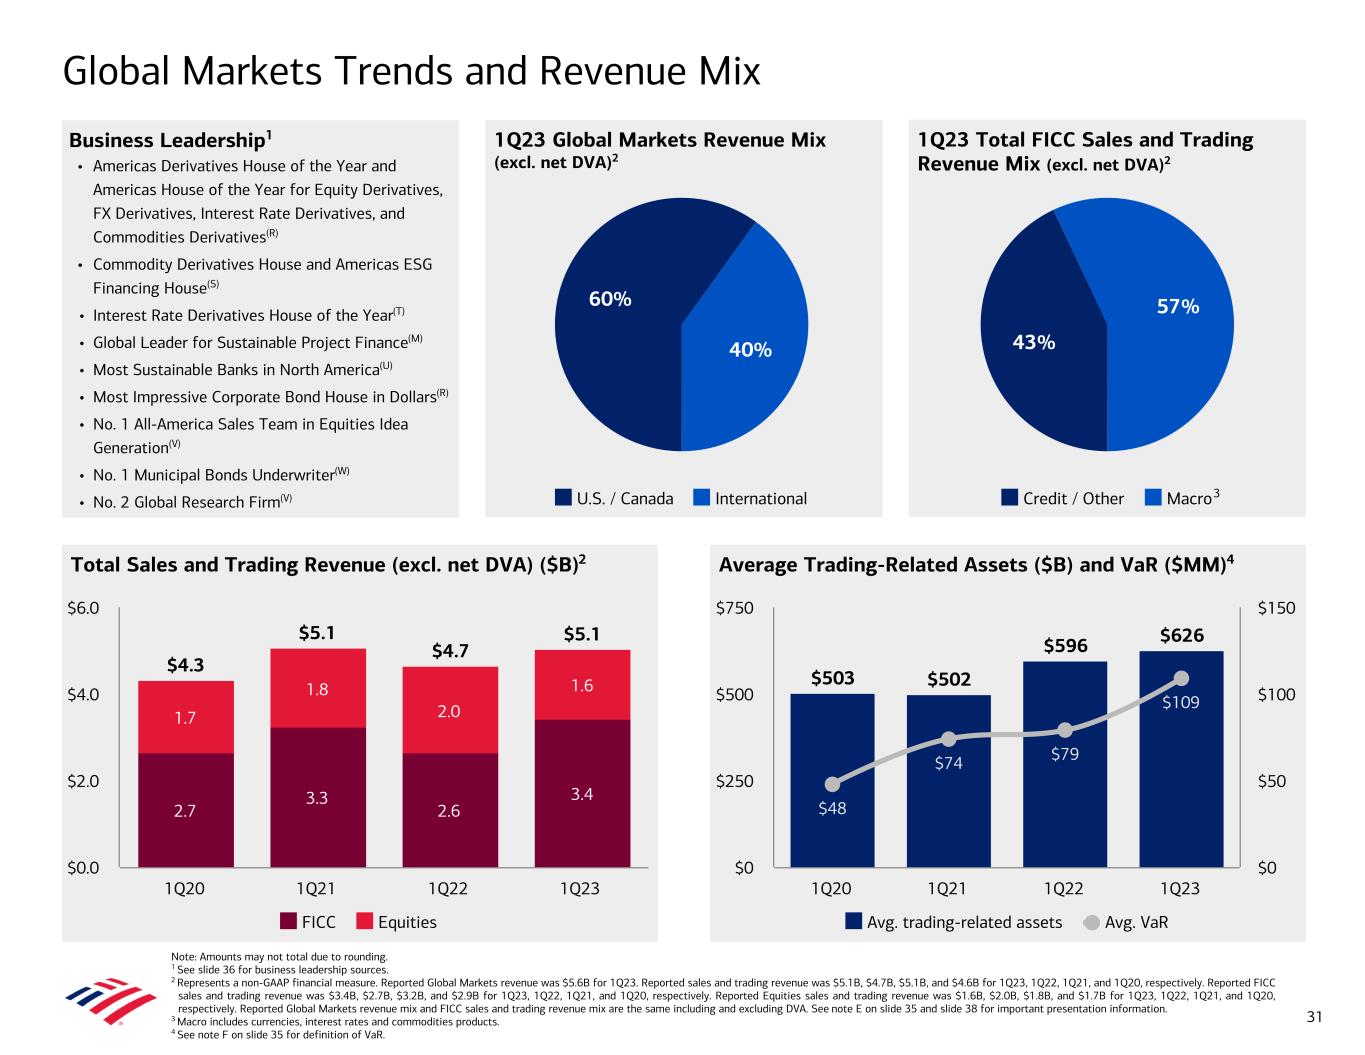
Global Markets Trends and Revenue Mix Note: Amounts may not total due to rounding. 1 See slide 36 for business leadership sources. 2 Represents a non-GAAP financial measure. Reported Global Markets revenue was $5.6B for 1Q23. Reported sales and trading revenue was $5.1B, $4.7B, $5.1B, and $4.6B for 1Q23, 1Q22, 1Q21, and 1Q20, respectively. Reported FICC sales and trading revenue was $3.4B, $2.7B, $3.2B, and $2.9B for 1Q23, 1Q22, 1Q21, and 1Q20, respectively. Reported Equities sales and trading revenue was $1.6B, $2.0B, $1.8B, and $1.7B for 1Q23, 1Q22, 1Q21, and 1Q20, respectively. Reported Global Markets revenue mix and FICC sales and trading revenue mix are the same including and excluding DVA. See note E on slide 35 and slide 38 for important presentation information. 3 Macro includes currencies, interest rates and commodities products. 4 See note F on slide 35 for definition of VaR. 1Q23 Global Markets Revenue Mix (excl. net DVA)2 Business Leadership1 • Americas Derivatives House of the Year and Americas House of the Year for Equity Derivatives, FX Derivatives, Interest Rate Derivatives, and Commodities Derivatives(R) • Commodity Derivatives House and Americas ESG Financing House(S) • Interest Rate Derivatives House of the Year(T) • Global Leader for Sustainable Project Finance(M) • Most Sustainable Banks in North America(U) • Most Impressive Corporate Bond House in Dollars(R) • No. 1 All-America Sales Team in Equities Idea Generation(V) • No. 1 Municipal Bonds Underwriter(W) • No. 2 Global Research Firm(V) 1Q23 Total FICC Sales and Trading Revenue Mix (excl. net DVA)2 Total Sales and Trading Revenue (excl. net DVA) ($B)2 Average Trading-Related Assets ($B) and VaR ($MM)4 $4.3 $5.1 $4.7 $5.1 2.7 3.3 2.6 3.4 1.7 1.8 2.0 1.6 FICC Equities 1Q20 1Q21 1Q22 1Q23 $0.0 $2.0 $4.0 $6.0 $503 $502 $596 $626 $48 $74 $79 $109 Avg. trading-related assets Avg. VaR 1Q20 1Q21 1Q22 1Q23 $0 $250 $500 $750 $0 $50 $100 $150 60% 40% U.S. / Canada International 43% 57% Credit / Other Macro3 31
Additional Presentation Information
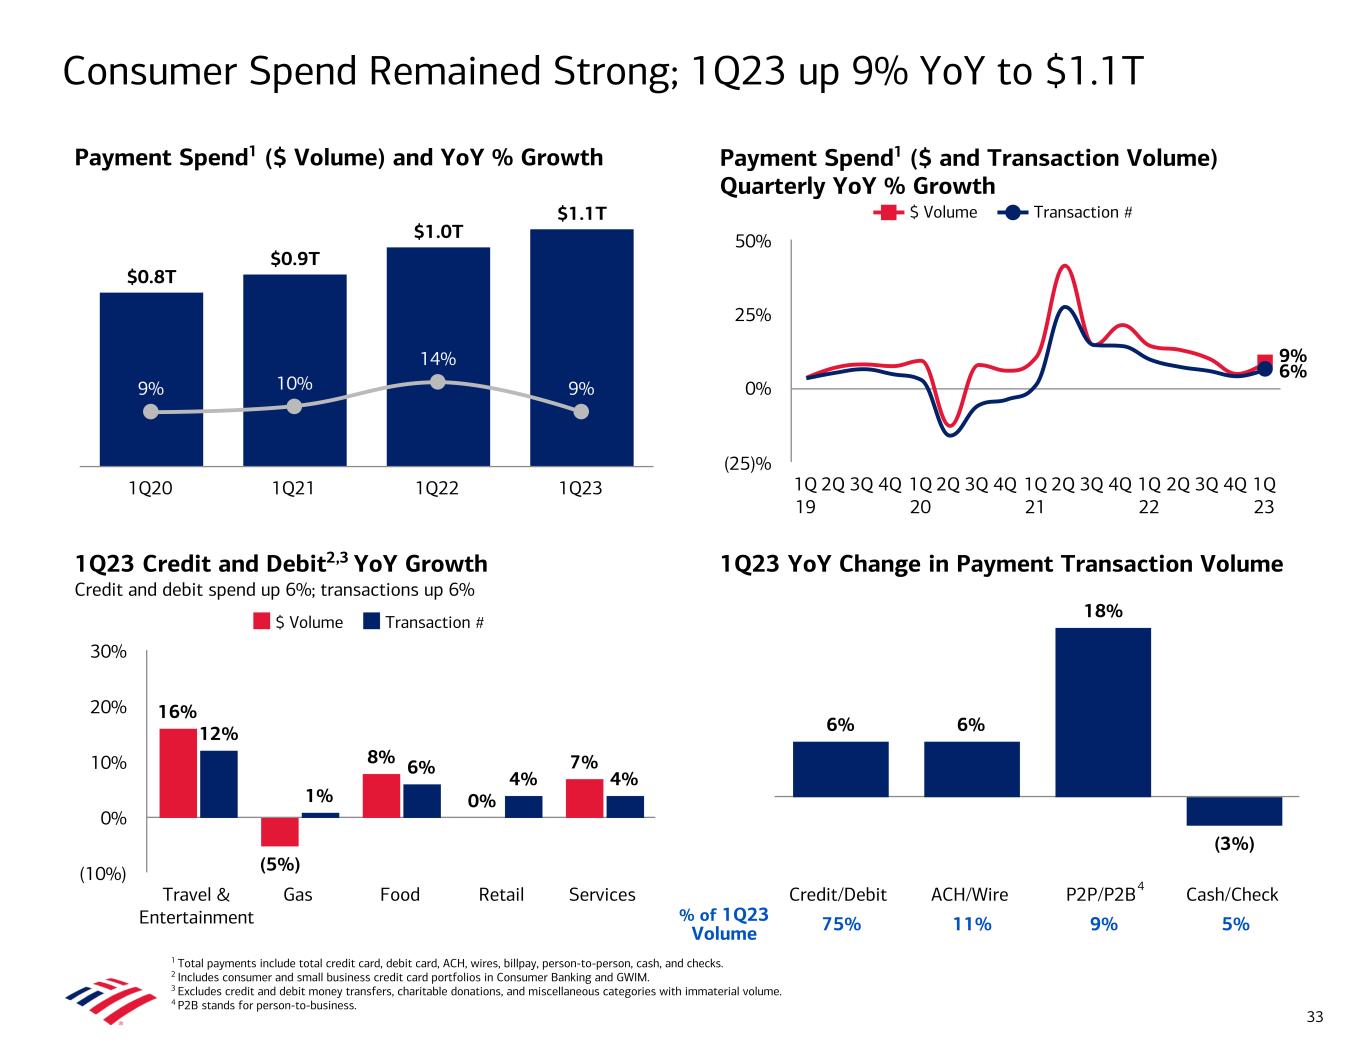
Consumer Spend Remained Strong; 1Q23 up 9% YoY to $1.1T 1 Total payments include total credit card, debit card, ACH, wires, billpay, person-to-person, cash, and checks. 2 Includes consumer and small business credit card portfolios in Consumer Banking and GWIM. 3 Excludes credit and debit money transfers, charitable donations, and miscellaneous categories with immaterial volume. 4 P2B stands for person-to-business. Payment Spend1 ($ and Transaction Volume) Quarterly YoY % Growth 33 1Q23 Credit and Debit2,3 YoY Growth Credit and debit spend up 6%; transactions up 6% $ Volume Transaction # 1Q 19 2Q 3Q 4Q 1Q 20 2Q 3Q 4Q 1Q 21 2Q 3Q 4Q 1Q 22 2Q 3Q 4Q 1Q 23 (25)% 0% 25% 50% 16% (5%) 8% 0% 7% 12% 1% 6% 4% 4% $ Volume Transaction # Travel & Entertainment Gas Food Retail Services (10%) 0% 10% 20% 30% Payment Spend1 ($ Volume) and YoY % Growth $0.8T $0.9T $1.0T $1.1T 9% 10% 14% 9% 1Q20 1Q21 1Q22 1Q23 9% 6% 1Q23 YoY Change in Payment Transaction Volume 6% 6% 18% (3%) Credit/Debit ACH/Wire P2P/P2B Cash/Check % of 1Q23 Volume 75% 11% 9% 5% 4
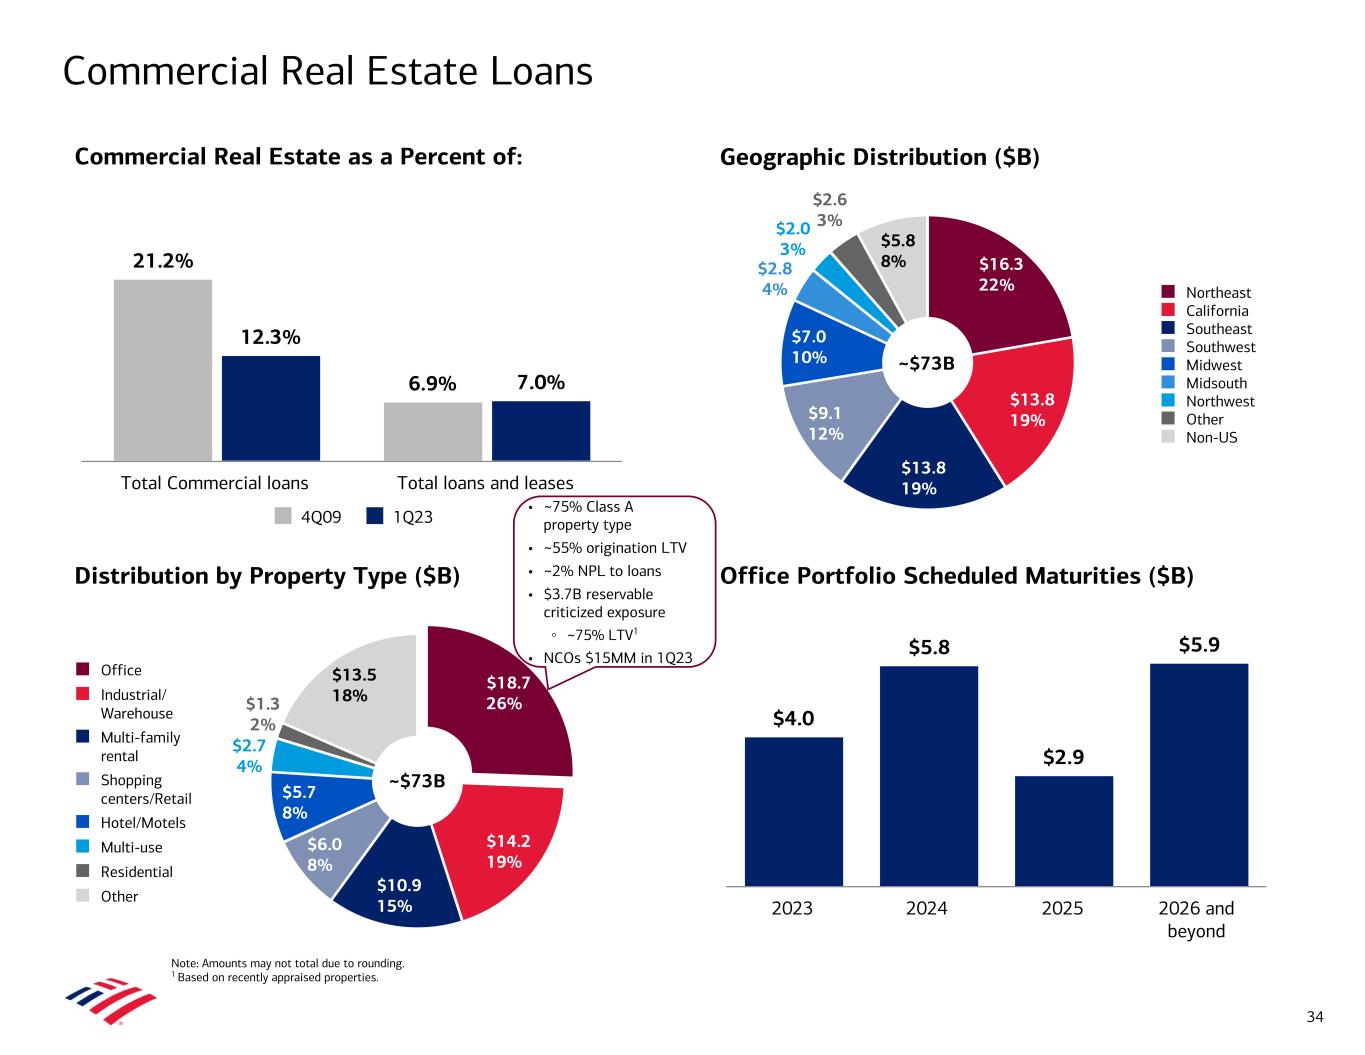
Commercial Real Estate Loans 34 21.2% 6.9% 12.3% 7.0% 4Q09 1Q23 Total Commercial loans Total loans and leases Commercial Real Estate as a Percent of: Geographic Distribution ($B) $16.3 22% $13.8 19% $13.8 19% $9.1 12% $7.0 10% $5.8 8% Northeast California Southeast Southwest Midwest Midsouth Northwest Other Non-US Office Portfolio Scheduled Maturities ($B) $18.7 26% $14.2 19% $10.9 15% $6.0 8% $5.7 8% $13.5 18% Office Industrial/ Warehouse Multi-family rental Shopping centers/Retail Hotel/Motels Multi-use Residential Other ~$73B Distribution by Property Type ($B) $2.6 3%$2.0 3% $2.8 4% $1.3 2% $2.7 4% $4.0 $5.8 $2.9 $5.9 2023 2024 2025 2026 and beyond • ~75% Class A property type • ~55% origination LTV • ~2% NPL to loans • $3.7B reservable criticized exposure ◦ ~75% LTV1 • NCOs $15MM in 1Q23 ~$73B Note: Amounts may not total due to rounding. 1 Based on recently appraised properties.
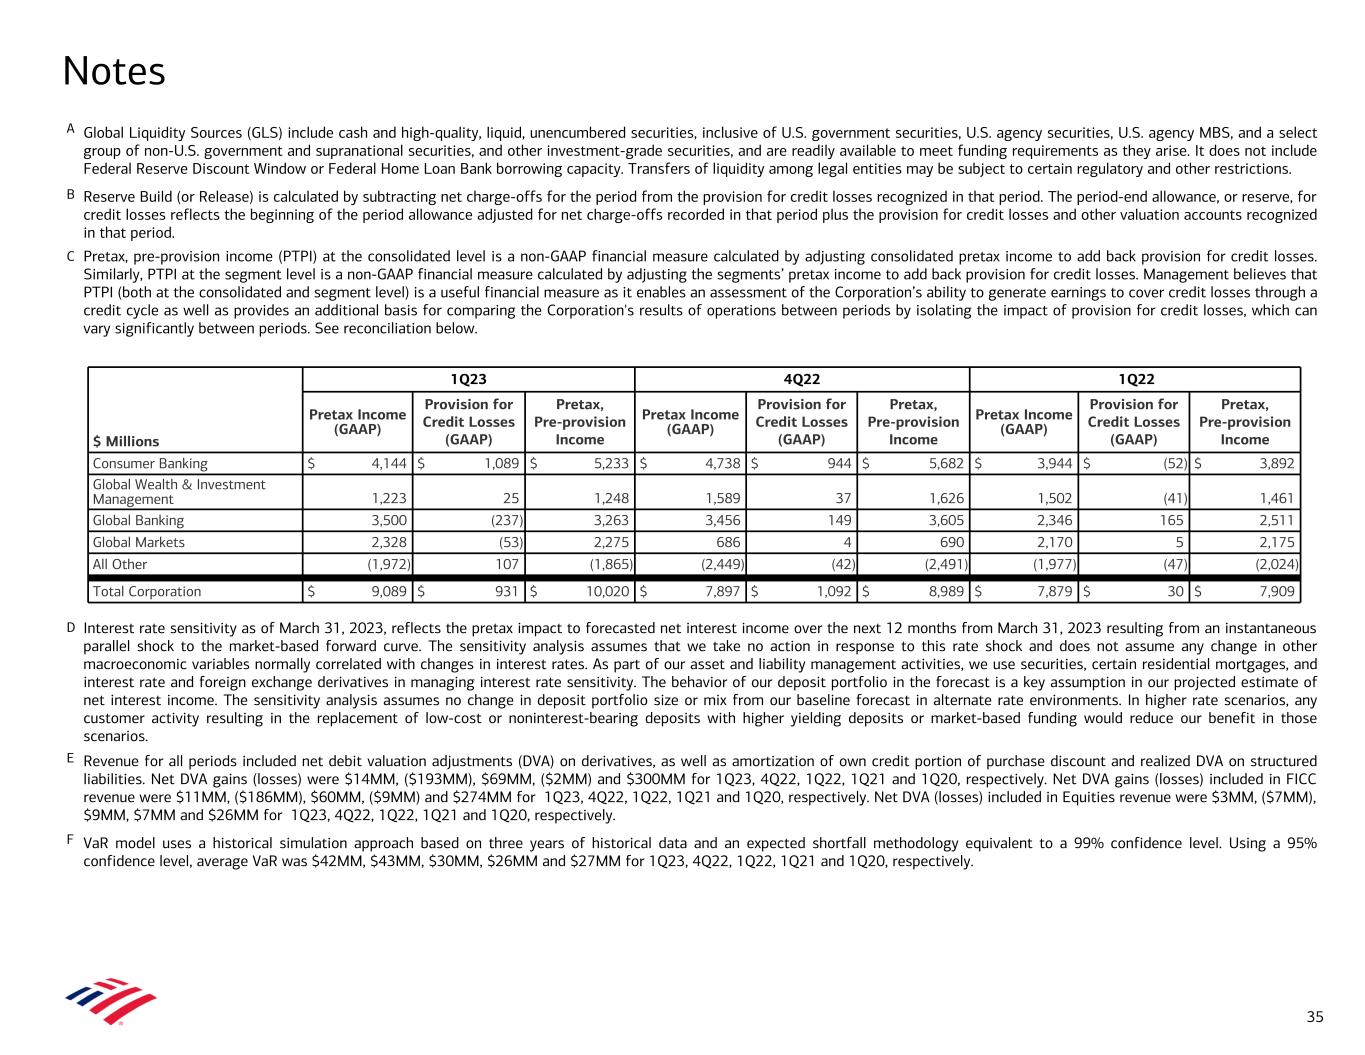
A Global Liquidity Sources (GLS) include cash and high-quality, liquid, unencumbered securities, inclusive of U.S. government securities, U.S. agency securities, U.S. agency MBS, and a select group of non-U.S. government and supranational securities, and other investment-grade securities, and are readily available to meet funding requirements as they arise. It does not include Federal Reserve Discount Window or Federal Home Loan Bank borrowing capacity. Transfers of liquidity among legal entities may be subject to certain regulatory and other restrictions. B Reserve Build (or Release) is calculated by subtracting net charge-offs for the period from the provision for credit losses recognized in that period. The period-end allowance, or reserve, for credit losses reflects the beginning of the period allowance adjusted for net charge-offs recorded in that period plus the provision for credit losses and other valuation accounts recognized in that period. C Pretax, pre-provision income (PTPI) at the consolidated level is a non-GAAP financial measure calculated by adjusting consolidated pretax income to add back provision for credit losses. Similarly, PTPI at the segment level is a non-GAAP financial measure calculated by adjusting the segments’ pretax income to add back provision for credit losses. Management believes that PTPI (both at the consolidated and segment level) is a useful financial measure as it enables an assessment of the Corporation’s ability to generate earnings to cover credit losses through a credit cycle as well as provides an additional basis for comparing the Corporation's results of operations between periods by isolating the impact of provision for credit losses, which can vary significantly between periods. See reconciliation below. D Interest rate sensitivity as of March 31, 2023, reflects the pretax impact to forecasted net interest income over the next 12 months from March 31, 2023 resulting from an instantaneous parallel shock to the market-based forward curve. The sensitivity analysis assumes that we take no action in response to this rate shock and does not assume any change in other macroeconomic variables normally correlated with changes in interest rates. As part of our asset and liability management activities, we use securities, certain residential mortgages, and interest rate and foreign exchange derivatives in managing interest rate sensitivity. The behavior of our deposit portfolio in the forecast is a key assumption in our projected estimate of net interest income. The sensitivity analysis assumes no change in deposit portfolio size or mix from our baseline forecast in alternate rate environments. In higher rate scenarios, any customer activity resulting in the replacement of low-cost or noninterest-bearing deposits with higher yielding deposits or market-based funding would reduce our benefit in those scenarios. E Revenue for all periods included net debit valuation adjustments (DVA) on derivatives, as well as amortization of own credit portion of purchase discount and realized DVA on structured liabilities. Net DVA gains (losses) were $14MM, ($193MM), $69MM, ($2MM) and $300MM for 1Q23, 4Q22, 1Q22, 1Q21 and 1Q20, respectively. Net DVA gains (losses) included in FICC revenue were $11MM, ($186MM), $60MM, ($9MM) and $274MM for 1Q23, 4Q22, 1Q22, 1Q21 and 1Q20, respectively. Net DVA (losses) included in Equities revenue were $3MM, ($7MM), $9MM, $7MM and $26MM for 1Q23, 4Q22, 1Q22, 1Q21 and 1Q20, respectively. F VaR model uses a historical simulation approach based on three years of historical data and an expected shortfall methodology equivalent to a 99% confidence level. Using a 95% confidence level, average VaR was $42MM, $43MM, $30MM, $26MM and $27MM for 1Q23, 4Q22, 1Q22, 1Q21 and 1Q20, respectively. Notes $ Millions 1Q23 4Q22 1Q22 Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Consumer Banking $ 4,144 $ 1,089 $ 5,233 $ 4,738 $ 944 $ 5,682 $ 3,944 $ (52) $ 3,892 Global Wealth & Investment Management 1,223 25 1,248 1,589 37 1,626 1,502 (41) 1,461 Global Banking 3,500 (237) 3,263 3,456 149 3,605 2,346 165 2,511 Global Markets 2,328 (53) 2,275 686 4 690 2,170 5 2,175 All Other (1,972) 107 (1,865) (2,449) (42) (2,491) (1,977) (47) (2,024) Total Corporation $ 9,089 $ 931 $ 10,020 $ 7,897 $ 1,092 $ 8,989 $ 7,879 $ 30 $ 7,909 35
Business Leadership Sources (A) Estimated U.S. retail deposits based on June 30, 2022 FDIC deposit data. (B) Javelin 2022 Online and Mobile Banking Scorecards. (C) FDIC, 4Q22. (D) Global Finance, May 2022. (E) Global Finance, August 2022. (F) Global Finance, December 2022. (G) J.D. Power 2023 Financial Health Support CertificationSM is based on exceeding customer experience benchmarks using client surveys and a best practices verification. For more information, visit jdpower.com/awards. (H) Industry Q4-22 FDIC call reports. (I) Family Wealth Report, 2022. (J) Global Private Banking, The Digital Banker, 2022. (K) WealthBriefing, 2022. (L) PWM, 2022. (M) Global Finance, 2022. (N) Euromoney, 2022. (O) Global Finance Treasury & Cash Management Awards, 2023. (P) Celent, 2023. (Q) Greenwich, 2023. (R) GlobalCapital, 2022. (S) IFR, 2022. (T) Risk.net, 2022. (U) Capital Monitor, 2022. (V) Institutional Investor, 2022. (W) Refinitiv, 2023 YTD. 36
Forward-Looking Statements Bank of America Corporation (the Corporation) and its management may make certain statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “intends,” “plans,” “goals,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements represent the Corporation’s current expectations, plans or forecasts of its future results, revenues, liquidity, provision for credit losses, expenses, efficiency ratio, capital measures, strategy, deposits, assets, and future business and economic conditions more generally, and other future matters. These statements are not guarantees of future results or performance and involve certain known and unknown risks, uncertainties and assumptions that are difficult to predict and are often beyond the Corporation’s control. Actual outcomes and results may differ materially from those expressed in, or implied by, any of these forward-looking statements. You should not place undue reliance on any forward-looking statement and should consider the following uncertainties and risks, as well as the risks and uncertainties more fully discussed under Item 1A. Risk Factors of the Corporation’s 2022 Annual Report on Form 10-K and in any of the Corporation’s subsequent Securities and Exchange Commission filings: the Corporation’s potential judgments, orders, settlements, penalties, fines and reputational damage resulting from pending or future litigation and regulatory investigations, proceedings and enforcement actions, including as a result of our participation in and execution of government programs related to the Coronavirus Disease 2019 (COVID-19) pandemic, such as the processing of unemployment benefits for California and certain other states; the possibility that the Corporation's future liabilities may be in excess of its recorded liability and estimated range of possible loss for litigation, and regulatory and government actions; the possibility that the Corporation could face increased claims from one or more parties involved in mortgage securitizations; the Corporation’s ability to resolve representations and warranties repurchase and related claims; the risks related to the discontinuation of the London Interbank Offered Rate and other reference rates, including increased expenses and litigation and the effectiveness of hedging strategies; uncertainties about the financial stability and growth rates of non-U.S. jurisdictions, the risk that those jurisdictions may face difficulties servicing their sovereign debt, and related stresses on financial markets, currencies and trade, and the Corporation’s exposures to such risks, including direct, indirect and operational; the impact of U.S. and global interest rates, inflation, currency exchange rates, economic conditions, trade policies and tensions, including tariffs, and potential geopolitical instability; the impact of the interest rate, inflationary, macroeconomic, banking and regulatory environment on the Corporation’s assets, business, financial condition and results of operations; the impact of adverse developments affecting the U.S. or global banking industry, including bank failures and liquidity concerns, which could cause continued or worsening economic and market volatility, and regulatory responses thereto; the possibility that future credit losses may be higher than currently expected due to changes in economic assumptions, customer behavior, adverse developments with respect to U.S. or global economic conditions and other uncertainties, including the impact of supply chain disruptions, inflationary pressures and labor shortages on economic conditions and our business; potential losses related to the Corporation’s concentration of credit risk; the Corporation's ability to achieve its expense targets and expectations regarding revenue, net interest income, provision for credit losses, net charge-offs, effective tax rate, loan growth or other projections; adverse changes to the Corporation’s credit ratings from the major credit rating agencies; an inability to access capital markets or maintain deposits or borrowing costs; estimates of the fair value and other accounting values, subject to impairment assessments, of certain of the Corporation’s assets and liabilities; the estimated or actual impact of changes in accounting standards or assumptions in applying those standards; uncertainty regarding the content, timing and impact of regulatory capital and liquidity requirements; the impact of adverse changes to total loss-absorbing capacity requirements, stress capital buffer requirements and/or global systemically important bank surcharges; the potential impact of actions of the Board of Governors of the Federal Reserve System on the Corporation’s capital plans; the effect of changes in or interpretations of income tax laws and regulations; the impact of implementation and compliance with U.S. and international laws, regulations and regulatory interpretations, including, but not limited to, recovery and resolution planning requirements, Federal Deposit Insurance Corporation assessments, the Volcker Rule, fiduciary standards, derivatives regulations and the Coronavirus Aid, Relief, and Economic Security Act and any similar or related rules and regulations; a failure or disruption in or breach of the Corporation’s operational or security systems or infrastructure, or those of third parties, including as a result of cyber- attacks or campaigns; the risks related to the transition and physical impacts of climate change; our ability to achieve environmental, social and governance goals and commitments or the impact of any changes in the Corporation's sustainability strategy or commitments generally; the impact of any future federal government shutdown and uncertainty regarding the federal government’s debt limit or changes in fiscal, monetary or regulatory policy; the emergence or continuation of widespread health emergencies or pandemics, including the magnitude and duration of the COVID-19 pandemic and its impact on U.S. and/or global financial market conditions and our business, results of operations, financial condition and prospects; the impact of natural disasters, extreme weather events, military conflict (including the Russia/Ukraine conflict, the possible expansion of such conflict and potential geopolitical consequences), terrorism or other geopolitical events; and other matters. Forward-looking statements speak only as of the date they are made, and the Corporation undertakes no obligation to update any forward-looking statement to reflect the impact of circumstances or events that arise after the date the forward-looking statement was made. 37
Important Presentation Information 38 • The information contained herein is preliminary and based on Corporation data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying slides. Bank of America does not undertake an obligation to, and disclaims any duty to, update any of the information provided. • The Corporation may present certain metrics and ratios, including year-over-year comparisons of revenue, noninterest expense and pretax income, excluding certain items (e.g., DVA) that are non-GAAP financial measures. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. For more information about the non-GAAP financial measures contained herein, please see the presentation of the most directly comparable financial measures calculated in accordance with GAAP and accompanying reconciliations in the earnings press release for the quarter ended March 31, 2023, and other earnings-related information available through the Bank of America Investor Relations website at: https://investor.bankofamerica.com/quarterly-earnings. • The Corporation presents certain key financial and nonfinancial performance indicators that management uses when assessing consolidated and/or segment results. The Corporation believes this information is useful because it provides management with information about underlying operational performance and trends. KPIs are presented in 1Q23 Financial Results on slide 4 and on the Summary Income Statement for each segment. • The Corporation also views net interest income and related ratios and analyses on a fully taxable-equivalent (FTE) basis, which when presented on a consolidated basis are non-GAAP financial measures. The Corporation believes managing the business with net interest income on an FTE basis provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that the presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practices. The FTE adjustment was $134MM, $123MM, $106MM, $103MM and $106MM for 1Q23, 4Q22, 3Q22, 2Q22 and 1Q22, respectively. • The Corporation allocates capital to its business segments using a methodology that considers the effect of regulatory capital requirements in addition to internal risk-based capital models. Allocated capital is reviewed periodically and refinements are made based on multiple considerations that include, but are not limited to, risk-weighted assets measured under Basel 3 Standardized and Advanced approaches, business segment exposures and risk profile, and strategic plans. As a result of this process, in the first quarter of 2023, the Corporation adjusted the amount of capital being allocated to its business segments.

Supplemental Information
First Quarter 2023
Current-period information is preliminary and based on company data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying pages. Bank of America Corporation (the Corporation) does not undertake an obligation to, and disclaims any duty to, update any of the information provided. Any forward-looking statements in this information are subject to the forward-looking language contained in the Corporation’s reports filed with the SEC pursuant to the Securities Exchange Act of 1934, which are available at the SEC’s website (www.sec.gov) or at the Corporation’s website (www.bankofamerica.com). The Corporation’s future financial performance is subject to risks and uncertainties as described in its SEC filings.
| Bank of America Corporation and Subsidiaries | |||||
| Table of Contents | Page | ||||
| Consumer Banking | |||||
| Global Wealth & Investment Management | |||||
| Global Banking | |||||
| Global Markets | |||||
| All Other | |||||
Key Performance Indicators | |||||
| The Corporation presents certain key financial and nonfinancial performance indicators that management uses when assessing consolidated and/or segment results. The Corporation believes this information is useful because it provides management with information about underlying operational performance and trends. Key performance indicators are presented in Consolidated Financial Highlights on page 2 and on the Key Indicators pages for each segment. | |||||
Business Segment Operations | |||||
The Corporation reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis. Additionally, the results for the total Corporation as presented on pages 11 - 12 are reported on an FTE basis. | |||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Consolidated Financial Highlights | ||||||||||||||||||||||||||||||||||||||||||||
| (In millions, except per share information) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Income statement | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,448 | $ | 14,681 | $ | 13,765 | $ | 12,444 | $ | 11,572 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 11,810 | 9,851 | 10,737 | 10,244 | 11,656 | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 26,258 | 24,532 | 24,502 | 22,688 | 23,228 | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 931 | 1,092 | 898 | 523 | 30 | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 16,238 | 15,543 | 15,303 | 15,273 | 15,319 | |||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 9,089 | 7,897 | 8,301 | 6,892 | 7,879 | |||||||||||||||||||||||||||||||||||||||
Pretax, pre-provision income (1) | 10,020 | 8,989 | 9,199 | 7,415 | 7,909 | |||||||||||||||||||||||||||||||||||||||
| Income tax expense | 928 | 765 | 1,219 | 645 | 812 | |||||||||||||||||||||||||||||||||||||||
| Net income | 8,161 | 7,132 | 7,082 | 6,247 | 7,067 | |||||||||||||||||||||||||||||||||||||||
| Preferred stock dividends and other | 505 | 228 | 503 | 315 | 467 | |||||||||||||||||||||||||||||||||||||||
| Net income applicable to common shareholders | 7,656 | 6,904 | 6,579 | 5,932 | 6,600 | |||||||||||||||||||||||||||||||||||||||
| Diluted earnings per common share | 0.94 | 0.85 | 0.81 | 0.73 | 0.80 | |||||||||||||||||||||||||||||||||||||||
| Average diluted common shares issued and outstanding | 8,182.3 | 8,155.7 | 8,160.8 | 8,163.1 | 8,202.1 | |||||||||||||||||||||||||||||||||||||||
| Dividends paid per common share | $ | 0.22 | $ | 0.22 | $ | 0.22 | $ | 0.21 | $ | 0.21 | ||||||||||||||||||||||||||||||||||
| Performance ratios | ||||||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 1.07 | % | 0.92 | % | 0.90 | % | 0.79 | % | 0.89 | % | ||||||||||||||||||||||||||||||||||
| Return on average common shareholders’ equity | 12.48 | 11.24 | 10.79 | 9.93 | 11.02 | |||||||||||||||||||||||||||||||||||||||
| Return on average shareholders’ equity | 11.94 | 10.38 | 10.37 | 9.34 | 10.64 | |||||||||||||||||||||||||||||||||||||||
Return on average tangible common shareholders’ equity (2) | 17.38 | 15.79 | 15.21 | 14.05 | 15.51 | |||||||||||||||||||||||||||||||||||||||
Return on average tangible shareholders’ equity (2) | 15.98 | 13.98 | 13.99 | 12.66 | 14.40 | |||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 61.84 | 63.36 | 62.45 | 67.32 | 65.95 | |||||||||||||||||||||||||||||||||||||||
| At period end | ||||||||||||||||||||||||||||||||||||||||||||
| Book value per share of common stock | $ | 31.58 | $ | 30.61 | $ | 29.96 | $ | 29.87 | $ | 29.70 | ||||||||||||||||||||||||||||||||||
Tangible book value per share of common stock (2) | 22.78 | 21.83 | 21.21 | 21.13 | 20.99 | |||||||||||||||||||||||||||||||||||||||
| Market capitalization | 228,012 | 264,853 | 242,338 | 250,136 | 332,320 | |||||||||||||||||||||||||||||||||||||||
| Number of financial centers - U.S. | 3,892 | 3,913 | 3,932 | 3,984 | 4,056 | |||||||||||||||||||||||||||||||||||||||
| Number of branded ATMs - U.S. | 15,407 | 15,528 | 15,572 | 15,730 | 15,959 | |||||||||||||||||||||||||||||||||||||||
| Headcount | 217,059 | 216,823 | 213,270 | 209,824 | 208,139 | |||||||||||||||||||||||||||||||||||||||
(1) Pretax, pre-provision income (PTPI) is a non-GAAP financial measure calculated by adjusting pretax income to add back provision for credit losses. Management believes that PTPI is a useful financial measure because it enables an assessment of the Corporation's ability to generate earnings to cover credit losses through a credit cycle. (See Exhibit A: Non-GAAP Reconciliations - Reconciliations to GAAP Financial Measures on page 30.)
(2) Tangible equity ratios and tangible book value per share of common stock are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. Tangible book value per share provides additional useful information about the level of tangible assets in relation to outstanding shares of common stock. (See Exhibit A: Non-GAAP Reconciliations - Reconciliations to GAAP Financial Measures on page 30.)
| Current-period information is preliminary and based on company data available at the time of the presentation. | 2 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||||||
| Consolidated Statement of Income | |||||||||||||||||||||||||||||||||||||||||||||||
| (In millions, except per share information) | |||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||||
| Net interest income | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 28,655 | $ | 25,075 | $ | 19,621 | $ | 14,975 | $ | 12,894 | |||||||||||||||||||||||||||||||||||||
| Interest expense | 14,207 | 10,394 | 5,856 | 2,531 | 1,322 | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | 14,448 | 14,681 | 13,765 | 12,444 | 11,572 | ||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||||||||
| Fees and commissions | 7,894 | 7,735 | 8,001 | 8,491 | 8,985 | ||||||||||||||||||||||||||||||||||||||||||
| Market making and similar activities | 4,712 | 3,052 | 3,068 | 2,717 | 3,238 | ||||||||||||||||||||||||||||||||||||||||||
| Other income (loss) | (796) | (936) | (332) | (964) | (567) | ||||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 11,810 | 9,851 | 10,737 | 10,244 | 11,656 | ||||||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 26,258 | 24,532 | 24,502 | 22,688 | 23,228 | ||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 931 | 1,092 | 898 | 523 | 30 | ||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits | 9,918 | 9,161 | 8,887 | 8,917 | 9,482 | ||||||||||||||||||||||||||||||||||||||||||
| Occupancy and equipment | 1,799 | 1,786 | 1,777 | 1,748 | 1,760 | ||||||||||||||||||||||||||||||||||||||||||
| Information processing and communications | 1,697 | 1,658 | 1,546 | 1,535 | 1,540 | ||||||||||||||||||||||||||||||||||||||||||
| Product delivery and transaction related | 890 | 904 | 892 | 924 | 933 | ||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 537 | 649 | 525 | 518 | 450 | ||||||||||||||||||||||||||||||||||||||||||
| Marketing | 458 | 460 | 505 | 463 | 397 | ||||||||||||||||||||||||||||||||||||||||||
| Other general operating | 939 | 925 | 1,171 | 1,168 | 757 | ||||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 16,238 | 15,543 | 15,303 | 15,273 | 15,319 | ||||||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 9,089 | 7,897 | 8,301 | 6,892 | 7,879 | ||||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 928 | 765 | 1,219 | 645 | 812 | ||||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 8,161 | $ | 7,132 | $ | 7,082 | $ | 6,247 | $ | 7,067 | |||||||||||||||||||||||||||||||||||||
| Preferred stock dividends and other | 505 | 228 | 503 | 315 | 467 | ||||||||||||||||||||||||||||||||||||||||||
| Net income applicable to common shareholders | $ | 7,656 | $ | 6,904 | $ | 6,579 | $ | 5,932 | $ | 6,600 | |||||||||||||||||||||||||||||||||||||
| Per common share information | |||||||||||||||||||||||||||||||||||||||||||||||
| Earnings | $ | 0.95 | $ | 0.85 | $ | 0.81 | $ | 0.73 | $ | 0.81 | |||||||||||||||||||||||||||||||||||||
| Diluted earnings | 0.94 | 0.85 | 0.81 | 0.73 | 0.80 | ||||||||||||||||||||||||||||||||||||||||||
| Average common shares issued and outstanding | 8,065.9 | 8,088.3 | 8,107.7 | 8,121.6 | 8,136.8 | ||||||||||||||||||||||||||||||||||||||||||
| Average diluted common shares issued and outstanding | 8,182.3 | 8,155.7 | 8,160.8 | 8,163.1 | 8,202.1 | ||||||||||||||||||||||||||||||||||||||||||
| Consolidated Statement of Comprehensive Income | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 8,161 | $ | 7,132 | $ | 7,082 | $ | 6,247 | $ | 7,067 | ||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss), net-of-tax: | ||||||||||||||||||||||||||||||||||||||||||||
| Net change in debt securities | 555 | 353 | (1,112) | (1,822) | (3,447) | |||||||||||||||||||||||||||||||||||||||
| Net change in debit valuation adjustments | 10 | (543) | 462 | 575 | 261 | |||||||||||||||||||||||||||||||||||||||
| Net change in derivatives | 2,042 | 835 | (3,703) | (2,008) | (5,179) | |||||||||||||||||||||||||||||||||||||||
| Employee benefit plan adjustments | 10 | (764) | 37 | 36 | 24 | |||||||||||||||||||||||||||||||||||||||
| Net change in foreign currency translation adjustments | 12 | (10) | (37) | (38) | 28 | |||||||||||||||||||||||||||||||||||||||
| Other comprehensive income (loss) | 2,629 | (129) | (4,353) | (3,257) | (8,313) | |||||||||||||||||||||||||||||||||||||||
| Comprehensive income (loss) | $ | 10,790 | $ | 7,003 | $ | 2,729 | $ | 2,990 | $ | (1,246) | ||||||||||||||||||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 3 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income and Noninterest Income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases | $ | 13,097 | $ | 12,114 | $ | 10,231 | $ | 8,222 | $ | 7,352 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities | 5,460 | 5,016 | 4,239 | 4,049 | 3,823 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 3,712 | 2,725 | 1,446 | 396 | (7) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account assets | 2,028 | 1,768 | 1,449 | 1,223 | 1,081 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other interest income | 4,358 | 3,452 | 2,256 | 1,085 | 645 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest income | 28,655 | 25,075 | 19,621 | 14,975 | 12,894 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 4,314 | 2,999 | 1,235 | 320 | 164 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 6,180 | 4,273 | 2,264 | 553 | (112) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account liabilities | 504 | 421 | 383 | 370 | 364 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 3,209 | 2,701 | 1,974 | 1,288 | 906 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest expense | 14,207 | 10,394 | 5,856 | 2,531 | 1,322 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,448 | $ | 14,681 | $ | 13,765 | $ | 12,444 | $ | 11,572 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Fees and commissions | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Card income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Interchange fees (1) | $ | 956 | $ | 1,029 | $ | 1,060 | $ | 1,072 | $ | 935 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other card income | 513 | 523 | 513 | 483 | 468 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total card income | 1,469 | 1,552 | 1,573 | 1,555 | 1,403 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Service charges | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposit-related fees | 1,097 | 1,081 | 1,162 | 1,417 | 1,530 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Lending-related fees | 313 | 308 | 304 | 300 | 303 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total service charges | 1,410 | 1,389 | 1,466 | 1,717 | 1,833 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment and brokerage services | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset management fees | 2,918 | 2,844 | 2,920 | 3,102 | 3,286 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Brokerage fees | 934 | 879 | 875 | 989 | 1,006 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment and brokerage services | 3,852 | 3,723 | 3,795 | 4,091 | 4,292 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Investment banking fees | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Underwriting income | 569 | 411 | 452 | 435 | 672 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Syndication fees | 231 | 174 | 283 | 301 | 312 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Financial advisory services | 363 | 486 | 432 | 392 | 473 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment banking fees | 1,163 | 1,071 | 1,167 | 1,128 | 1,457 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total fees and commissions | 7,894 | 7,735 | 8,001 | 8,491 | 8,985 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Market making and similar activities | 4,712 | 3,052 | 3,068 | 2,717 | 3,238 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other income (loss) | (796) | (936) | (332) | (964) | (567) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | $ | 11,810 | $ | 9,851 | $ | 10,737 | $ | 10,244 | $ | 11,656 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Gross interchange fees and merchant income were $3.2 billion, $3.3 billion, $3.3 billion, $3.3 billion and $2.9 billion and are presented net of $2.2 billion, $2.3 billion, $2.2 billion, $2.2 billion and $2.0 billion of expenses for rewards and partner payments as well as certain other card costs for the first quarter of 2023 and the fourth, third, second, and first quarters of 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 4 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||
| Consolidated Balance Sheet | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| March 31 2023 | December 31 2022 | March 31 2022 | ||||||||||||||||||
| Assets | ||||||||||||||||||||
| Cash and due from banks | $ | 29,327 | $ | 30,334 | $ | 29,769 | ||||||||||||||
| Interest-bearing deposits with the Federal Reserve, non-U.S. central banks and other banks | 346,891 | 199,869 | 244,165 | |||||||||||||||||
| Cash and cash equivalents | 376,218 | 230,203 | 273,934 | |||||||||||||||||
| Time deposits placed and other short-term investments | 11,637 | 7,259 | 5,645 | |||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 298,078 | 267,574 | 302,108 | |||||||||||||||||
| Trading account assets | 314,978 | 296,108 | 313,400 | |||||||||||||||||
| Derivative assets | 40,947 | 48,642 | 48,231 | |||||||||||||||||
| Debt securities: | ||||||||||||||||||||
| Carried at fair value | 172,510 | 229,994 | 297,700 | |||||||||||||||||
| Held-to-maturity, at cost | 624,495 | 632,825 | 672,180 | |||||||||||||||||
| Total debt securities | 797,005 | 862,819 | 969,880 | |||||||||||||||||
| Loans and leases | 1,046,406 | 1,045,747 | 993,145 | |||||||||||||||||
| Allowance for loan and lease losses | (12,514) | (12,682) | (12,104) | |||||||||||||||||
| Loans and leases, net of allowance | 1,033,892 | 1,033,065 | 981,041 | |||||||||||||||||
| Premises and equipment, net | 11,708 | 11,510 | 10,820 | |||||||||||||||||
| Goodwill | 69,022 | 69,022 | 69,022 | |||||||||||||||||
| Loans held-for-sale | 6,809 | 6,871 | 10,270 | |||||||||||||||||
| Customer and other receivables | 79,902 | 67,543 | 83,622 | |||||||||||||||||
| Other assets | 154,461 | 150,759 | 170,250 | |||||||||||||||||
| Total assets | $ | 3,194,657 | $ | 3,051,375 | $ | 3,238,223 | ||||||||||||||
| Liabilities | ||||||||||||||||||||
| Deposits in U.S. offices: | ||||||||||||||||||||
| Noninterest-bearing | $ | 617,922 | $ | 640,745 | $ | 787,045 | ||||||||||||||
| Interest-bearing | 1,183,106 | 1,182,590 | 1,178,451 | |||||||||||||||||
| Deposits in non-U.S. offices: | ||||||||||||||||||||
| Noninterest-bearing | 17,686 | 20,480 | 27,589 | |||||||||||||||||
| Interest-bearing | 91,688 | 86,526 | 79,324 | |||||||||||||||||
| Total deposits | 1,910,402 | 1,930,341 | 2,072,409 | |||||||||||||||||
| Federal funds purchased and securities loaned or sold under agreements to repurchase | 314,380 | 195,635 | 214,685 | |||||||||||||||||
| Trading account liabilities | 92,452 | 80,399 | 117,122 | |||||||||||||||||
| Derivative liabilities | 40,169 | 44,816 | 44,266 | |||||||||||||||||
| Short-term borrowings | 56,564 | 26,932 | 24,789 | |||||||||||||||||
| Accrued expenses and other liabilities | 216,621 | 224,073 | 219,625 | |||||||||||||||||
| Long-term debt | 283,873 | 275,982 | 278,710 | |||||||||||||||||
| Total liabilities | 2,914,461 | 2,778,178 | 2,971,606 | |||||||||||||||||
| Shareholders’ equity | ||||||||||||||||||||
Preferred stock, $0.01 par value; authorized – 100,000,000 shares; issued and outstanding – 4,088,099, 4,088,101 and 4,037,686 shares | 28,397 | 28,397 | 27,137 | |||||||||||||||||
Common stock and additional paid-in capital, $0.01 par value; authorized – 12,800,000,000 shares; issued and outstanding – 7,972,438,148, 7,996,777,943 and 8,062,102,236 shares | 57,264 | 58,953 | 59,968 | |||||||||||||||||
| Retained earnings | 213,062 | 207,003 | 192,929 | |||||||||||||||||
| Accumulated other comprehensive income (loss) | (18,527) | (21,156) | (13,417) | |||||||||||||||||
| Total shareholders’ equity | 280,196 | 273,197 | 266,617 | |||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 3,194,657 | $ | 3,051,375 | $ | 3,238,223 | ||||||||||||||
| Assets of consolidated variable interest entities included in total assets above (isolated to settle the liabilities of the variable interest entities) | ||||||||||||||||||||
| Trading account assets | $ | 4,276 | $ | 2,816 | $ | 2,160 | ||||||||||||||
| Loans and leases | 15,754 | 16,738 | 15,946 | |||||||||||||||||
| Allowance for loan and lease losses | (797) | (797) | (880) | |||||||||||||||||
| Loans and leases, net of allowance | 14,957 | 15,941 | 15,066 | |||||||||||||||||
| All other assets | 129 | 116 | 417 | |||||||||||||||||
| Total assets of consolidated variable interest entities | $ | 19,362 | $ | 18,873 | $ | 17,643 | ||||||||||||||
| Liabilities of consolidated variable interest entities included in total liabilities above | ||||||||||||||||||||
| Short-term borrowings | $ | 1,339 | $ | 42 | $ | 228 | ||||||||||||||
| Long-term debt | 4,883 | 4,581 | 3,557 | |||||||||||||||||
| All other liabilities | 7 | 13 | 6 | |||||||||||||||||
| Total liabilities of consolidated variable interest entities | $ | 6,229 | $ | 4,636 | $ | 3,791 | ||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 5 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Capital Management | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| March 31 2023 | December 31 2022 | March 31 2022 | |||||||||||||||||||||||||||
Risk-based capital metrics (1): | |||||||||||||||||||||||||||||
| Standardized Approach | |||||||||||||||||||||||||||||
| Common equity tier 1 capital | $ | 184,432 | $ | 180,060 | $ | 169,874 | |||||||||||||||||||||||
| Tier 1 capital | 212,825 | 208,446 | 197,007 | ||||||||||||||||||||||||||
| Total capital | 242,604 | 238,773 | 229,186 | ||||||||||||||||||||||||||
| Risk-weighted assets | 1,623,377 | 1,604,870 | 1,638,958 | ||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 11.4 | % | 11.2 | % | 10.4 | % | |||||||||||||||||||||||
| Tier 1 capital ratio | 13.1 | 13.0 | 12.0 | ||||||||||||||||||||||||||
| Total capital ratio | 14.9 | 14.9 | 14.0 | ||||||||||||||||||||||||||
| Advanced Approaches | |||||||||||||||||||||||||||||
| Common equity tier 1 capital | $ | 184,432 | $ | 180,060 | $ | 169,874 | |||||||||||||||||||||||
| Tier 1 capital | 212,825 | 208,446 | 197,007 | ||||||||||||||||||||||||||
| Total capital | 233,736 | 230,916 | 222,481 | ||||||||||||||||||||||||||
| Risk-weighted assets | 1,428,647 | 1,411,005 | 1,415,505 | ||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 12.9 | % | 12.8 | % | 12.0 | % | |||||||||||||||||||||||
| Tier 1 capital ratio | 14.9 | 14.8 | 13.9 | ||||||||||||||||||||||||||
| Total capital ratio | 16.4 | 16.4 | 15.7 | ||||||||||||||||||||||||||
Leverage-based metrics (1): | |||||||||||||||||||||||||||||
| Adjusted average assets | $ | 3,018,318 | $ | 2,997,118 | $ | 3,129,996 | |||||||||||||||||||||||
| Tier 1 leverage ratio | 7.1 | % | 7.0 | % | 6.3 | % | |||||||||||||||||||||||
| Supplementary leverage exposure | $ | 3,554,920 | $ | 3,523,484 | $ | 3,661,948 | |||||||||||||||||||||||
| Supplementary leverage ratio | 6.0 | % | 5.9 | % | 5.4 | % | |||||||||||||||||||||||
| Total ending equity to total ending assets ratio | 8.8 | 9.0 | 8.2 | ||||||||||||||||||||||||||
| Common equity ratio | 7.9 | 8.0 | 7.4 | ||||||||||||||||||||||||||
Tangible equity ratio (2) | 6.7 | 6.8 | 6.2 | ||||||||||||||||||||||||||
Tangible common equity ratio (2) | 5.8 | 5.9 | 5.3 | ||||||||||||||||||||||||||
(1)Regulatory capital ratios at March 31, 2023 are preliminary. We report regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation's binding ratio was the Common equity tier 1 ratio under the Standardized approach for all periods presented.
(2)Tangible equity ratio equals period-end tangible shareholders’ equity divided by period-end tangible assets. Tangible common equity ratio equals period-end tangible common shareholders’ equity divided by period-end tangible assets. Tangible shareholders’ equity and tangible assets are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. (See Exhibit A: Non-GAAP Reconciliations - Reconciliation to GAAP Financial Measures on page 30.)
| Current-period information is preliminary and based on company data available at the time of the presentation. | 6 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Capital Composition under Basel 3 | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| March 31 2023 | December 31 2022 | March 31 2022 | |||||||||||||||||||||||||||
| Total common shareholders' equity | $ | 251,799 | $ | 244,800 | $ | 239,480 | |||||||||||||||||||||||
CECL transitional amount (1) | 1,254 | 1,881 | 1,881 | ||||||||||||||||||||||||||
| Goodwill, net of related deferred tax liabilities | (68,644) | (68,644) | (68,641) | ||||||||||||||||||||||||||
| Deferred tax assets arising from net operating loss and tax credit carryforwards | (7,835) | (7,776) | (7,843) | ||||||||||||||||||||||||||
| Intangibles, other than mortgage servicing rights, net of related deferred tax liabilities | (1,538) | (1,554) | (1,589) | ||||||||||||||||||||||||||
| Defined benefit pension plan net assets, net-of-tax | (882) | (867) | (1,248) | ||||||||||||||||||||||||||
| Cumulative unrealized net (gain) loss related to changes in fair value of financial liabilities attributable to own creditworthiness, net-of-tax | 485 | 496 | 1,047 | ||||||||||||||||||||||||||
Accumulated net (gain) loss on certain cash flow hedges (2) | 9,886 | 11,925 | 7,049 | ||||||||||||||||||||||||||
| Other | (93) | (201) | (262) | ||||||||||||||||||||||||||
| Common equity tier 1 capital | 184,432 | 180,060 | 169,874 | ||||||||||||||||||||||||||
| Qualifying preferred stock, net of issuance cost | 28,396 | 28,396 | 27,136 | ||||||||||||||||||||||||||
| Other | (3) | (10) | (3) | ||||||||||||||||||||||||||
| Tier 1 capital | 212,825 | 208,446 | 197,007 | ||||||||||||||||||||||||||
| Tier 2 capital instruments | 17,840 | 18,751 | 21,737 | ||||||||||||||||||||||||||
Qualifying allowance for credit losses (3) | 12,315 | 11,739 | 11,000 | ||||||||||||||||||||||||||
| Other | (376) | (163) | (558) | ||||||||||||||||||||||||||
| Total capital under the Standardized approach | 242,604 | 238,773 | 229,186 | ||||||||||||||||||||||||||
Adjustment in qualifying allowance for credit losses under the Advanced approaches (3) | (8,868) | (7,857) | (6,705) | ||||||||||||||||||||||||||
| Total capital under the Advanced approaches | $ | 233,736 | $ | 230,916 | $ | 222,481 | |||||||||||||||||||||||
(1)March 31, 2022 and December 31, 2022 include 75 percent of the current expected credit losses (CECL) transition provision’s impact as of December 31, 2021. March 31, 2023 includes 50 percent of the transition provision’s impact as of December 31, 2021.
(2)Includes amounts in accumulated other comprehensive income related to the hedging of items that are not recognized at fair value on the Consolidated Balance Sheet.
(3)Includes the impact of transition provisions related to the CECL accounting standard.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 7 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarterly Average Balances and Interest Rates – Fully Taxable-equivalent Basis | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest Income/ Expense (1) | Yield/ Rate | Average Balance | Interest Income/ Expense (1) | Yield/ Rate | Average Balance | Interest Income/ Expense (1) | Yield/ Rate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Earning assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits with the Federal Reserve, non-U.S. central banks and other banks | $ | 202,700 | $ | 1,999 | 4.00 | % | $ | 175,595 | $ | 1,375 | 3.11 | % | $ | 244,971 | $ | 86 | 0.14 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits placed and other short-term investments | 10,581 | 108 | 4.16 | 9,558 | 74 | 3.07 | 9,253 | 12 | 0.52 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 287,532 | 3,712 | 5.24 | 289,321 | 2,725 | 3.74 | 299,404 | (7) | (0.01) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account assets | 183,657 | 2,040 | 4.50 | 169,003 | 1,784 | 4.19 | 151,969 | 1,096 | 2.92 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities | 851,177 | 5,485 | 2.58 | 869,084 | 5,043 | 2.30 | 975,656 | 3,838 | 1.58 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans and leases (2) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 229,275 | 1,684 | 2.94 | 229,364 | 1,663 | 2.90 | 223,979 | 1,525 | 2.73 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 26,513 | 317 | 4.84 | 26,983 | 275 | 4.05 | 27,784 | 220 | 3.21 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 91,775 | 2,426 | 10.72 | 89,575 | 2,327 | 10.31 | 78,409 | 1,940 | 10.03 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 105,657 | 1,186 | 4.55 | 106,598 | 1,119 | 4.16 | 104,632 | 579 | 2.25 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer | 453,220 | 5,613 | 5.00 | 452,520 | 5,384 | 4.73 | 434,804 | 4,264 | 3.96 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 376,852 | 4,471 | 4.81 | 378,850 | 4,172 | 4.37 | 346,510 | 2,127 | 2.49 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 127,003 | 1,778 | 5.68 | 125,983 | 1,474 | 4.64 | 118,767 | 504 | 1.72 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 70,591 | 1,144 | 6.57 | 68,764 | 994 | 5.74 | 63,065 | 387 | 2.49 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | 13,686 | 147 | 4.33 | 13,130 | 139 | 4.21 | 14,647 | 106 | 2.92 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 588,132 | 7,540 | 5.20 | 586,727 | 6,779 | 4.58 | 542,989 | 3,124 | 2.33 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 1,041,352 | 13,153 | 5.11 | 1,039,247 | 12,163 | 4.65 | 977,793 | 7,388 | 3.06 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other earning assets | 94,427 | 2,292 | 9.82 | 95,904 | 2,034 | 8.42 | 120,798 | 587 | 1.97 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total earning assets | 2,671,426 | 28,789 | 4.36 | 2,647,712 | 25,198 | 3.78 | 2,779,844 | 13,000 | 1.89 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 27,784 | 27,771 | 28,082 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets, less allowance for loan and lease losses | 396,848 | 398,806 | 399,776 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 3,096,058 | $ | 3,074,289 | $ | 3,207,702 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. interest-bearing deposits | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand and money market deposits | $ | 975,085 | $ | 2,790 | 1.16 | % | $ | 980,964 | $ | 2,044 | 0.83 | % | $ | 1,001,184 | $ | 80 | 0.03 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time and savings deposits | 196,984 | 919 | 1.89 | 180,684 | 543 | 1.19 | 163,981 | 40 | 0.10 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total U.S. interest-bearing deposits | 1,172,069 | 3,709 | 1.28 | 1,161,648 | 2,587 | 0.88 | 1,165,165 | 120 | 0.04 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. interest-bearing deposits | 91,603 | 605 | 2.68 | 83,073 | 412 | 1.97 | 81,879 | 44 | 0.22 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 1,263,672 | 4,314 | 1.38 | 1,244,721 | 2,999 | 0.96 | 1,247,044 | 164 | 0.05 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities loaned or sold under agreements to repurchase | 256,015 | 3,551 | 5.63 | 214,267 | 2,246 | 4.16 | 217,152 | 79 | 0.15 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings and other interest-bearing liabilities | 156,887 | 2,629 | 6.79 | 150,351 | 2,027 | 5.35 | 126,454 | (191) | (0.61) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account liabilities | 43,953 | 504 | 4.65 | 40,393 | 421 | 4.13 | 64,240 | 364 | 2.30 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 244,759 | 3,209 | 5.28 | 243,871 | 2,701 | 4.41 | 246,042 | 906 | 1.50 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 1,965,286 | 14,207 | 2.93 | 1,893,603 | 10,394 | 2.18 | 1,900,932 | 1,322 | 0.28 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing sources | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 629,977 | 680,823 | 798,767 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Other liabilities (3) | 223,543 | 227,234 | 238,694 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 277,252 | 272,629 | 269,309 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 3,096,058 | $ | 3,074,289 | $ | 3,207,702 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest spread | 1.43 | % | 1.60 | % | 1.61 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Impact of noninterest-bearing sources | 0.77 | 0.62 | 0.08 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net interest income/yield on earning assets (4) | $ | 14,582 | 2.20 | % | $ | 14,804 | 2.22 | % | $ | 11,678 | 1.69 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Includes the impact of interest rate risk management contracts.
(2)Nonperforming loans are included in the respective average loan balances. Income on these nonperforming loans is generally recognized on a cost recovery basis.
(3)Includes $37.3 billion, $31.9 billion and $30.2 billion of structured notes and liabilities for the first quarter of 2023 and the fourth and first quarters of 2022, respectively.
(4)Net interest income includes FTE adjustments of $134 million, $123 million and $106 million for the first quarter of 2023 and the fourth and first quarters of 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 8 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||
| Debt Securities | |||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||
| March 31, 2023 | |||||||||||||||||||||||
| Amortized Cost | Gross Unrealized Gains | Gross Unrealized Losses | Fair Value | ||||||||||||||||||||
| Available-for-sale debt securities | |||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||
| Agency | $ | 24,726 | $ | 5 | $ | (1,479) | $ | 23,252 | |||||||||||||||
| Agency-collateralized mortgage obligations | 2,235 | — | (200) | 2,035 | |||||||||||||||||||
| Commercial | 6,890 | 31 | (481) | 6,440 | |||||||||||||||||||
| Non-agency residential | 459 | 3 | (55) | 407 | |||||||||||||||||||
| Total mortgage-backed securities | 34,310 | 39 | (2,215) | 32,134 | |||||||||||||||||||
| U.S. Treasury and government agencies | 102,943 | 2 | (1,438) | 101,507 | |||||||||||||||||||
| Non-U.S. securities | 13,161 | 2 | (43) | 13,120 | |||||||||||||||||||
| Other taxable securities | 4,830 | 1 | (85) | 4,746 | |||||||||||||||||||
| Tax-exempt securities | 11,105 | 25 | (227) | 10,903 | |||||||||||||||||||
| Total available-for-sale debt securities | 166,349 | 69 | (4,008) | 162,410 | |||||||||||||||||||
Other debt securities carried at fair value (1) | 10,081 | 63 | (44) | 10,100 | |||||||||||||||||||
| Total debt securities carried at fair value | 176,430 | 132 | (4,052) | 172,510 | |||||||||||||||||||
| Held-to-maturity debt securities | |||||||||||||||||||||||
| Agency mortgage-backed securities | 494,998 | — | (80,664) | 414,334 | |||||||||||||||||||
| U.S. Treasury and government agencies | 121,609 | — | (17,511) | 104,098 | |||||||||||||||||||
| Other taxable securities | 7,921 | — | (901) | 7,020 | |||||||||||||||||||
| Total held-to-maturity debt securities | 624,528 | — | (99,076) | 525,452 | |||||||||||||||||||
| Total debt securities | $ | 800,958 | $ | 132 | $ | (103,128) | $ | 697,962 | |||||||||||||||
| December 31, 2022 | |||||||||||||||||||||||
| Available-for-sale debt securities | |||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||
| Agency | $ | 25,204 | $ | 5 | $ | (1,767) | $ | 23,442 | |||||||||||||||
| Agency-collateralized mortgage obligations | 2,452 | — | (231) | 2,221 | |||||||||||||||||||
| Commercial | 6,894 | 28 | (515) | 6,407 | |||||||||||||||||||
| Non-agency residential | 461 | 15 | (90) | 386 | |||||||||||||||||||
| Total mortgage-backed securities | 35,011 | 48 | (2,603) | 32,456 | |||||||||||||||||||
| U.S. Treasury and government agencies | 160,773 | 18 | (1,769) | 159,022 | |||||||||||||||||||
| Non-U.S. securities | 13,455 | 4 | (52) | 13,407 | |||||||||||||||||||
| Other taxable securities | 4,728 | 1 | (84) | 4,645 | |||||||||||||||||||
| Tax-exempt securities | 11,518 | 19 | (279) | 11,258 | |||||||||||||||||||
| Total available-for-sale debt securities | 225,485 | 90 | (4,787) | 220,788 | |||||||||||||||||||
Other debt securities carried at fair value (1) | 8,986 | 376 | (156) | 9,206 | |||||||||||||||||||
| Total debt securities carried at fair value | 234,471 | 466 | (4,943) | 229,994 | |||||||||||||||||||
| Held-to-maturity debt securities | |||||||||||||||||||||||
| Agency mortgage-backed securities | 503,233 | — | (87,319) | 415,914 | |||||||||||||||||||
| U.S. Treasury and government agencies | 121,597 | — | (20,259) | 101,338 | |||||||||||||||||||
| Other taxable securities | 8,033 | — | (1,018) | 7,015 | |||||||||||||||||||
| Total held-to-maturity debt securities | 632,863 | — | (108,596) | 524,267 | |||||||||||||||||||
| Total debt securities | $ | 867,334 | $ | 466 | $ | (113,539) | $ | 754,261 | |||||||||||||||
(1) Primarily includes non-U.S. securities used to satisfy certain international regulatory requirements.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 9 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Supplemental Financial Data | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
FTE basis data (1) | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,582 | $ | 14,804 | $ | 13,871 | $ | 12,547 | $ | 11,678 | ||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 26,391 | 24,655 | 24,608 | 22,791 | 23,334 | |||||||||||||||||||||||||||||||||||||||
| Net interest yield | 2.20 | % | 2.22 | % | 2.06 | % | 1.86 | % | 1.69 | % | ||||||||||||||||||||||||||||||||||
| Efficiency ratio | 61.53 | 63.05 | 62.18 | 67.01 | 65.65 | |||||||||||||||||||||||||||||||||||||||
(1)FTE basis is a non-GAAP financial measure. FTE basis is a performance measure used by management in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that this presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practices. Net interest income includes FTE adjustments of $134 million, $123 million, $106 million, $103 million and $106 million for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 10 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||
| Quarterly Results by Business Segment and All Other | |||||||||||||||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,582 | $ | 8,593 | $ | 1,876 | $ | 3,907 | $ | 109 | $ | 97 | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,469 | 1,274 | 12 | 190 | 16 | (23) | |||||||||||||||||||||||||||||||||||
| Service charges | 1,410 | 599 | 19 | 714 | 78 | — | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 3,852 | 74 | 3,238 | 9 | 533 | (2) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,163 | — | 39 | 668 | 469 | (13) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 7,894 | 1,947 | 3,308 | 1,581 | 1,096 | (38) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 4,712 | 5 | 34 | 45 | 4,398 | 230 | |||||||||||||||||||||||||||||||||||
Other income (loss) | (796) | 161 | 97 | 670 | 23 | (1,747) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 11,810 | 2,113 | 3,439 | 2,296 | 5,517 | (1,555) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 26,392 | 10,706 | 5,315 | 6,203 | 5,626 | (1,458) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 931 | 1,089 | 25 | (237) | (53) | 107 | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 16,238 | 5,473 | 4,067 | 2,940 | 3,351 | 407 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 9,223 | 4,144 | 1,223 | 3,500 | 2,328 | (1,972) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 1,062 | 1,036 | 306 | 945 | 640 | (1,865) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 8,161 | $ | 3,108 | $ | 917 | $ | 2,555 | $ | 1,688 | $ | (107) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,041,352 | $ | 303,772 | $ | 221,448 | $ | 381,009 | $ | 125,046 | $ | 10,077 | |||||||||||||||||||||||||||||
Total assets (1) | 3,096,058 | 1,105,245 | 359,164 | 588,886 | 870,038 | 172,725 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,893,649 | 1,026,242 | 314,019 | 492,577 | 36,109 | 24,702 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,046,406 | $ | 304,480 | $ | 217,804 | $ | 383,491 | $ | 130,804 | $ | 9,827 | |||||||||||||||||||||||||||||
Total assets (1) | 3,194,657 | 1,124,438 | 349,888 | 591,231 | 861,477 | 267,623 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,910,402 | 1,044,768 | 301,471 | 495,949 | 33,624 | 34,590 | |||||||||||||||||||||||||||||||||||
| Fourth Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,804 | $ | 8,494 | $ | 2,015 | $ | 3,880 | $ | 371 | $ | 44 | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,552 | 1,333 | 19 | 196 | 17 | (13) | |||||||||||||||||||||||||||||||||||
| Service charges | 1,389 | 586 | 17 | 703 | 79 | 4 | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 3,723 | 71 | 3,166 | 6 | 482 | (2) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,071 | — | 35 | 706 | 347 | (17) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 7,735 | 1,990 | 3,237 | 1,611 | 925 | (28) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 3,052 | 5 | 36 | 34 | 2,685 | 292 | |||||||||||||||||||||||||||||||||||
| Other income (loss) | (936) | 293 | 122 | 913 | (120) | (2,144) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 9,851 | 2,288 | 3,395 | 2,558 | 3,490 | (1,880) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 24,655 | 10,782 | 5,410 | 6,438 | 3,861 | (1,836) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,092 | 944 | 37 | 149 | 4 | (42) | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 15,543 | 5,100 | 3,784 | 2,833 | 3,171 | 655 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 8,020 | 4,738 | 1,589 | 3,456 | 686 | (2,449) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 888 | 1,161 | 389 | 916 | 182 | (1,760) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 7,132 | $ | 3,577 | $ | 1,200 | $ | 2,540 | $ | 504 | $ | (689) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,039,247 | $ | 300,360 | $ | 225,094 | $ | 380,385 | $ | 123,022 | $ | 10,386 | |||||||||||||||||||||||||||||
Total assets (1) | 3,074,289 | 1,123,813 | 361,592 | 595,525 | 857,319 | 136,040 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,925,544 | 1,047,058 | 317,849 | 503,472 | 37,219 | 19,946 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,045,747 | $ | 304,761 | $ | 223,910 | $ | 379,107 | $ | 127,735 | $ | 10,234 | |||||||||||||||||||||||||||||
Total assets (1) | 3,051,375 | 1,126,453 | 368,893 | 588,466 | 812,489 | 155,074 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,930,341 | 1,048,799 | 323,899 | 498,661 | 39,077 | 19,905 | |||||||||||||||||||||||||||||||||||
(1)Total assets include asset allocations to match liabilities (i.e., deposits).
| Current-period information is preliminary and based on company data available at the time of the presentation. | 11 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||
| Quarterly Results by Business Segment and All Other (continued) | |||||||||||||||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||
| First Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 11,678 | $ | 6,680 | $ | 1,668 | $ | 2,344 | $ | 993 | $ | (7) | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,403 | 1,185 | 18 | 176 | 14 | 10 | |||||||||||||||||||||||||||||||||||
| Service charges | 1,833 | 844 | 19 | 886 | 82 | 2 | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 4,292 | 83 | 3,654 | 12 | 545 | (2) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,457 | — | 66 | 880 | 582 | (71) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 8,985 | 2,112 | 3,757 | 1,954 | 1,223 | (61) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 3,238 | — | 13 | 49 | 3,190 | (14) | |||||||||||||||||||||||||||||||||||
| Other income (loss) | (567) | 21 | 38 | 847 | (114) | (1,359) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 11,656 | 2,133 | 3,808 | 2,850 | 4,299 | (1,434) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 23,334 | 8,813 | 5,476 | 5,194 | 5,292 | (1,441) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 30 | (52) | (41) | 165 | 5 | (47) | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 15,319 | 4,921 | 4,015 | 2,683 | 3,117 | 583 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 7,985 | 3,944 | 1,502 | 2,346 | 2,170 | (1,977) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 918 | 966 | 368 | 622 | 575 | (1,613) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 7,067 | $ | 2,978 | $ | 1,134 | $ | 1,724 | $ | 1,595 | $ | (364) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 977,793 | $ | 284,068 | $ | 210,937 | $ | 358,807 | $ | 108,576 | $ | 15,405 | |||||||||||||||||||||||||||||
Total assets (1) | 3,207,702 | 1,133,001 | 431,040 | 630,517 | 858,719 | 154,425 | |||||||||||||||||||||||||||||||||||
| Total deposits | 2,045,811 | 1,056,100 | 384,902 | 539,912 | 44,393 | 20,504 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 993,145 | $ | 286,322 | $ | 214,273 | $ | 367,423 | $ | 110,037 | $ | 15,090 | |||||||||||||||||||||||||||||
Total assets (1) | 3,238,223 | 1,166,443 | 433,122 | 623,168 | 883,304 | 132,186 | |||||||||||||||||||||||||||||||||||
| Total deposits | 2,072,409 | 1,088,940 | 385,288 | 533,820 | 43,371 | 20,990 | |||||||||||||||||||||||||||||||||||
(1)Total assets include asset allocations to match liabilities (i.e., deposits).
| Current-period information is preliminary and based on company data available at the time of the presentation. | 12 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking Segment Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 8,593 | $ | 8,494 | $ | 7,784 | $ | 7,087 | $ | 6,680 | ||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Card income | 1,274 | 1,333 | 1,331 | 1,320 | 1,185 | |||||||||||||||||||||||||||||||||||||||
| Service charges | 599 | 586 | 597 | 679 | 844 | |||||||||||||||||||||||||||||||||||||||
| All other income | 240 | 369 | 192 | 50 | 104 | |||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 2,113 | 2,288 | 2,120 | 2,049 | 2,133 | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 10,706 | 10,782 | 9,904 | 9,136 | 8,813 | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,089 | 944 | 738 | 350 | (52) | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 5,473 | 5,100 | 5,097 | 4,959 | 4,921 | |||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 4,144 | 4,738 | 4,069 | 3,827 | 3,944 | |||||||||||||||||||||||||||||||||||||||
| Income tax expense | 1,036 | 1,161 | 997 | 938 | 966 | |||||||||||||||||||||||||||||||||||||||
| Net income | $ | 3,108 | $ | 3,577 | $ | 3,072 | $ | 2,889 | $ | 2,978 | ||||||||||||||||||||||||||||||||||
| Net interest yield | 3.27 | % | 3.11 | % | 2.79 | % | 2.55 | % | 2.48 | % | ||||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 30 | 35 | 30 | 29 | 30 | |||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 51.12 | 47.29 | 51.47 | 54.28 | 55.84 | |||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 303,772 | $ | 300,360 | $ | 295,231 | $ | 289,595 | $ | 284,068 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,065,202 | 1,083,850 | 1,106,513 | 1,114,552 | 1,092,742 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,105,245 | 1,123,813 | 1,145,846 | 1,154,773 | 1,133,001 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,026,242 | 1,047,058 | 1,069,093 | 1,078,020 | 1,056,100 | |||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 42,000 | 40,000 | 40,000 | 40,000 | 40,000 | |||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 304,480 | $ | 304,761 | $ | 297,825 | $ | 294,570 | $ | 286,322 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,081,780 | 1,085,079 | 1,110,524 | 1,114,524 | 1,125,963 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,124,438 | 1,126,453 | 1,149,918 | 1,154,366 | 1,166,443 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,044,768 | 1,048,799 | 1,072,580 | 1,077,215 | 1,088,940 | |||||||||||||||||||||||||||||||||||||||
(1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2) Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 13 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking Key Indicators | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Average deposit balances | ||||||||||||||||||||||||||||||||||||||||||||
| Checking | $ | 580,910 | $ | 588,668 | $ | 599,099 | $ | 606,331 | $ | 593,428 | ||||||||||||||||||||||||||||||||||
| Savings | 68,327 | 69,790 | 71,933 | 73,295 | 72,413 | |||||||||||||||||||||||||||||||||||||||
| MMS | 339,823 | 356,015 | 365,271 | 362,798 | 354,850 | |||||||||||||||||||||||||||||||||||||||
| CDs and IRAs | 33,098 | 28,619 | 28,731 | 29,796 | 30,685 | |||||||||||||||||||||||||||||||||||||||
| Other | 4,084 | 3,966 | 4,059 | 5,800 | 4,724 | |||||||||||||||||||||||||||||||||||||||
| Total average deposit balances | $ | 1,026,242 | $ | 1,047,058 | $ | 1,069,093 | $ | 1,078,020 | $ | 1,056,100 | ||||||||||||||||||||||||||||||||||
| Deposit spreads (excludes noninterest costs) | ||||||||||||||||||||||||||||||||||||||||||||
| Checking | 2.22 | % | 2.09 | % | 1.98 | % | 1.93 | % | 1.91 | % | ||||||||||||||||||||||||||||||||||
| Savings | 2.53 | 2.33 | 2.19 | 2.19 | 2.19 | |||||||||||||||||||||||||||||||||||||||
| MMS | 2.99 | 2.25 | 1.64 | 1.29 | 1.23 | |||||||||||||||||||||||||||||||||||||||
| CDs and IRAs | 3.27 | 2.91 | 1.85 | 0.98 | 0.46 | |||||||||||||||||||||||||||||||||||||||
| Other | 4.37 | 3.35 | 2.04 | 1.04 | 0.41 | |||||||||||||||||||||||||||||||||||||||
| Total deposit spreads | 2.54 | 2.19 | 1.88 | 1.70 | 1.65 | |||||||||||||||||||||||||||||||||||||||
| Consumer investment assets | $ | 354,892 | $ | 319,648 | $ | 302,413 | $ | 315,243 | $ | 357,593 | ||||||||||||||||||||||||||||||||||
Active digital banking users (in thousands) (1) | 44,962 | 44,054 | 43,496 | 42,690 | 42,269 | |||||||||||||||||||||||||||||||||||||||
Active mobile banking users (in thousands) (2) | 36,322 | 35,452 | 34,922 | 34,167 | 33,589 | |||||||||||||||||||||||||||||||||||||||
| Financial centers | 3,892 | 3,913 | 3,932 | 3,984 | 4,056 | |||||||||||||||||||||||||||||||||||||||
| ATMs | 15,407 | 15,528 | 15,572 | 15,730 | 15,959 | |||||||||||||||||||||||||||||||||||||||
Total credit card (3) | ||||||||||||||||||||||||||||||||||||||||||||
| Loans | ||||||||||||||||||||||||||||||||||||||||||||
| Average credit card outstandings | $ | 91,775 | $ | 89,575 | $ | 85,009 | $ | 81,024 | $ | 78,409 | ||||||||||||||||||||||||||||||||||
| Ending credit card outstandings | 92,469 | 93,421 | 87,296 | 84,010 | 79,356 | |||||||||||||||||||||||||||||||||||||||
| Credit quality | ||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | $ | 501 | $ | 386 | $ | 328 | $ | 323 | $ | 297 | ||||||||||||||||||||||||||||||||||
| 2.21 | % | 1.71 | % | 1.53 | % | 1.60 | % | 1.53 | % | |||||||||||||||||||||||||||||||||||
| 30+ delinquency | $ | 1,674 | $ | 1,505 | $ | 1,202 | $ | 1,008 | $ | 1,003 | ||||||||||||||||||||||||||||||||||
| 1.81 | % | 1.61 | % | 1.38 | % | 1.20 | % | 1.26 | % | |||||||||||||||||||||||||||||||||||
| 90+ delinquency | $ | 828 | $ | 717 | $ | 547 | $ | 493 | $ | 492 | ||||||||||||||||||||||||||||||||||
| 0.90 | % | 0.77 | % | 0.63 | % | 0.59 | % | 0.62 | % | |||||||||||||||||||||||||||||||||||
Other total credit card indicators (3) | ||||||||||||||||||||||||||||||||||||||||||||
| Gross interest yield | 11.85 | % | 11.18 | % | 10.71 | % | 9.76 | % | 9.90 | % | ||||||||||||||||||||||||||||||||||
| Risk-adjusted margin | 8.69 | 9.87 | 10.07 | 9.95 | 10.40 | |||||||||||||||||||||||||||||||||||||||
| New accounts (in thousands) | 1,187 | 1,096 | 1,256 | 1,068 | 977 | |||||||||||||||||||||||||||||||||||||||
| Purchase volumes | $ | 85,544 | $ | 92,800 | $ | 91,064 | $ | 91,810 | $ | 80,914 | ||||||||||||||||||||||||||||||||||
| Debit card data | ||||||||||||||||||||||||||||||||||||||||||||
| Purchase volumes | $ | 124,376 | $ | 130,157 | $ | 127,135 | $ | 128,707 | $ | 117,584 | ||||||||||||||||||||||||||||||||||
Loan production (4) | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking: | ||||||||||||||||||||||||||||||||||||||||||||
| First mortgage | $ | 1,956 | $ | 2,286 | $ | 4,028 | $ | 6,551 | $ | 8,116 | ||||||||||||||||||||||||||||||||||
| Home equity | 2,183 | 2,113 | 1,999 | 2,151 | 1,725 | |||||||||||||||||||||||||||||||||||||||
Total (5): | ||||||||||||||||||||||||||||||||||||||||||||
| First mortgage | $ | 3,937 | $ | 5,217 | $ | 8,724 | $ | 14,471 | $ | 16,353 | ||||||||||||||||||||||||||||||||||
| Home equity | 2,596 | 2,596 | 2,420 | 2,535 | 2,040 | |||||||||||||||||||||||||||||||||||||||
(1) Represents mobile and/or online active users over the past 90 days.
(2) Represents mobile active users over the past 90 days.
(3) In addition to the credit card portfolio in Consumer Banking, the remaining credit card portfolio is in GWIM.
(4) Loan production amounts represent the unpaid principal balance of loans and, in the case of home equity, the principal amount of the total line of credit.
(5) In addition to loan production in Consumer Banking, there is also first mortgage and home equity loan production in GWIM.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 14 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking Quarterly Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Banking | Deposits | Consumer Lending | Total Consumer Banking | Deposits | Consumer Lending | |||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 8,593 | $ | 5,816 | $ | 2,777 | $ | 8,494 | $ | 5,719 | $ | 2,775 | ||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Card income | 1,274 | (10) | 1,284 | 1,333 | (9) | 1,342 | ||||||||||||||||||||||||||||||||||||||
| Service charges | 599 | 598 | 1 | 586 | 585 | 1 | ||||||||||||||||||||||||||||||||||||||
| All other income | 240 | 197 | 43 | 369 | 214 | 155 | ||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 2,113 | 785 | 1,328 | 2,288 | 790 | 1,498 | ||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 10,706 | 6,601 | 4,105 | 10,782 | 6,509 | 4,273 | ||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,089 | 183 | 906 | 944 | 176 | 768 | ||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 5,473 | 3,415 | 2,058 | 5,100 | 3,189 | 1,911 | ||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 4,144 | 3,003 | 1,141 | 4,738 | 3,144 | 1,594 | ||||||||||||||||||||||||||||||||||||||
| Income tax expense | 1,036 | 751 | 285 | 1,161 | 771 | 390 | ||||||||||||||||||||||||||||||||||||||
| Net income | $ | 3,108 | $ | 2,252 | $ | 856 | $ | 3,577 | $ | 2,373 | $ | 1,204 | ||||||||||||||||||||||||||||||||
| Net interest yield | 3.27 | % | 2.31 | % | 3.76 | % | 3.11 | % | 2.18 | % | 3.71 | % | ||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 30 | 67 | 12 | 35 | 72 | 18 | ||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 51.12 | 51.76 | 50.10 | 47.29 | 49.00 | 44.70 | ||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 303,772 | $ | 4,119 | $ | 299,653 | $ | 300,360 | $ | 4,132 | $ | 296,228 | ||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,065,202 | 1,022,445 | 299,794 | 1,083,850 | 1,042,289 | 296,535 | ||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,105,245 | 1,056,007 | 306,275 | 1,123,813 | 1,075,446 | 303,340 | ||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,026,242 | 1,021,374 | 4,868 | 1,047,058 | 1,041,669 | 5,389 | ||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 42,000 | 13,700 | 28,300 | 40,000 | 13,000 | 27,000 | ||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 304,480 | $ | 4,065 | $ | 300,415 | $ | 304,761 | $ | 4,148 | $ | 300,613 | ||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,081,780 | 1,038,545 | 300,595 | 1,085,079 | 1,043,049 | 300,787 | ||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,124,438 | 1,074,571 | 307,227 | 1,126,453 | 1,077,203 | 308,007 | ||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,044,768 | 1,039,744 | 5,024 | 1,048,799 | 1,043,194 | 5,605 | ||||||||||||||||||||||||||||||||||||||
| First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Banking | Deposits | Consumer Lending | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 6,680 | $ | 4,052 | $ | 2,628 | ||||||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Card income | 1,185 | (8) | 1,193 | |||||||||||||||||||||||||||||||||||||||||
| Service charges | 844 | 843 | 1 | |||||||||||||||||||||||||||||||||||||||||
| All other income | 104 | 68 | 36 | |||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 2,133 | 903 | 1,230 | |||||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 8,813 | 4,955 | 3,858 | |||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | (52) | 73 | (125) | |||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 4,921 | 3,008 | 1,913 | |||||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 3,944 | 1,874 | 2,070 | |||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 966 | 459 | 507 | |||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 2,978 | $ | 1,415 | $ | 1,563 | ||||||||||||||||||||||||||||||||||||||
| Net interest yield | 2.48 | % | 1.56 | % | 3.79 | % | ||||||||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 30 | 44 | 23 | |||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 55.84 | 60.71 | 49.58 | |||||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 284,068 | $ | 4,215 | $ | 279,853 | ||||||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,092,742 | 1,050,490 | 281,255 | |||||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,133,001 | 1,084,343 | 287,660 | |||||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,056,100 | 1,050,247 | 5,853 | |||||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 40,000 | 13,000 | 27,000 | |||||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 286,322 | $ | 4,165 | $ | 282,157 | ||||||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,125,963 | 1,083,664 | 284,069 | |||||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,166,443 | 1,117,241 | 290,972 | |||||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,088,940 | 1,082,885 | 6,055 | |||||||||||||||||||||||||||||||||||||||||
(1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2) For presentation purposes, in segments or businesses where the total of liabilities and equity exceeds assets, the Corporation allocates assets from All Other to match the segments’ and businesses’ liabilities and allocated shareholders’ equity. As a result, total earning assets and total assets of the businesses may not equal total Consumer Banking.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 15 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Wealth & Investment Management Segment Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 1,876 | $ | 2,015 | $ | 1,981 | $ | 1,802 | $ | 1,668 | ||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 3,238 | 3,166 | 3,255 | 3,486 | 3,654 | |||||||||||||||||||||||||||||||||||||||
| All other income | 201 | 229 | 193 | 145 | 154 | |||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 3,439 | 3,395 | 3,448 | 3,631 | 3,808 | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 5,315 | 5,410 | 5,429 | 5,433 | 5,476 | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 25 | 37 | 37 | 33 | (41) | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 4,067 | 3,784 | 3,816 | 3,875 | 4,015 | |||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 1,223 | 1,589 | 1,576 | 1,525 | 1,502 | |||||||||||||||||||||||||||||||||||||||
| Income tax expense | 306 | 389 | 386 | 374 | 368 | |||||||||||||||||||||||||||||||||||||||
| Net income | $ | 917 | $ | 1,200 | $ | 1,190 | $ | 1,151 | $ | 1,134 | ||||||||||||||||||||||||||||||||||
| Net interest yield | 2.20 | % | 2.29 | % | 2.12 | % | 1.82 | % | 1.62 | % | ||||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 20 | 27 | 27 | 26 | 26 | |||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 76.53 | 69.96 | 70.28 | 71.34 | 73.31 | |||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 221,448 | $ | 225,094 | $ | 223,734 | $ | 219,277 | $ | 210,937 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 346,384 | 348,718 | 370,733 | 396,611 | 418,248 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 359,164 | 361,592 | 383,468 | 409,472 | 431,040 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 314,019 | 317,849 | 339,487 | 363,943 | 384,902 | |||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 18,500 | 17,500 | 17,500 | 17,500 | 17,500 | |||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 217,804 | $ | 223,910 | $ | 224,858 | $ | 221,705 | $ | 214,273 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 336,560 | 355,461 | 357,434 | 380,771 | 419,903 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 349,888 | 368,893 | 370,790 | 393,948 | 433,122 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 301,471 | 323,899 | 324,859 | 347,991 | 385,288 | |||||||||||||||||||||||||||||||||||||||
(1)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2)Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 16 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Wealth & Investment Management Key Indicators | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Revenue by Business | ||||||||||||||||||||||||||||||||||||||||||||
| Merrill Wealth Management | $ | 4,397 | $ | 4,486 | $ | 4,524 | $ | 4,536 | $ | 4,589 | ||||||||||||||||||||||||||||||||||
| Bank of America Private Bank | 918 | 924 | 905 | 897 | 887 | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | $ | 5,315 | $ | 5,410 | $ | 5,429 | $ | 5,433 | $ | 5,476 | ||||||||||||||||||||||||||||||||||
| Client Balances by Business, at period end | ||||||||||||||||||||||||||||||||||||||||||||
| Merrill Wealth Management | $ | 2,952,681 | $ | 2,822,910 | $ | 2,710,985 | $ | 2,819,998 | $ | 3,116,052 | ||||||||||||||||||||||||||||||||||
| Bank of America Private Bank | 568,925 | 563,931 | 537,771 | 547,116 | 598,100 | |||||||||||||||||||||||||||||||||||||||
| Total client balances | $ | 3,521,606 | $ | 3,386,841 | $ | 3,248,756 | $ | 3,367,114 | $ | 3,714,152 | ||||||||||||||||||||||||||||||||||
| Client Balances by Type, at period end | ||||||||||||||||||||||||||||||||||||||||||||
Assets under management (1) | $ | 1,467,242 | $ | 1,401,474 | $ | 1,329,557 | $ | 1,411,344 | $ | 1,571,605 | ||||||||||||||||||||||||||||||||||
| Brokerage and other assets | 1,571,409 | 1,482,025 | 1,413,946 | 1,437,562 | 1,592,802 | |||||||||||||||||||||||||||||||||||||||
| Deposits | 301,471 | 323,899 | 324,859 | 347,991 | 385,288 | |||||||||||||||||||||||||||||||||||||||
Loans and leases (2) | 220,633 | 226,973 | 228,129 | 224,847 | 217,461 | |||||||||||||||||||||||||||||||||||||||
| Less: Managed deposits in assets under management | (39,149) | (47,530) | (47,735) | (54,630) | (53,004) | |||||||||||||||||||||||||||||||||||||||
| Total client balances | $ | 3,521,606 | $ | 3,386,841 | $ | 3,248,756 | $ | 3,367,114 | $ | 3,714,152 | ||||||||||||||||||||||||||||||||||
| Assets Under Management Rollforward | ||||||||||||||||||||||||||||||||||||||||||||
| Assets under management, beginning balance | $ | 1,401,474 | $ | 1,329,557 | $ | 1,411,344 | $ | 1,571,605 | $ | 1,638,782 | ||||||||||||||||||||||||||||||||||
| Net client flows | 15,262 | 105 | 4,110 | 1,033 | 15,537 | |||||||||||||||||||||||||||||||||||||||
| Market valuation/other | 50,506 | 71,812 | (85,897) | (161,294) | (82,714) | |||||||||||||||||||||||||||||||||||||||
| Total assets under management, ending balance | $ | 1,467,242 | $ | 1,401,474 | $ | 1,329,557 | $ | 1,411,344 | $ | 1,571,605 | ||||||||||||||||||||||||||||||||||
| Advisors, at period end | ||||||||||||||||||||||||||||||||||||||||||||
Total wealth advisors (3) | 19,243 | 19,273 | 18,841 | 18,449 | 18,571 | |||||||||||||||||||||||||||||||||||||||
(1)Defined as managed assets under advisory and/or discretion of GWIM.
(2)Includes margin receivables which are classified in customer and other receivables on the Consolidated Balance Sheet.
(3)Includes advisors across all wealth management businesses in GWIM and Consumer Banking.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 17 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Banking Segment Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 3,907 | $ | 3,880 | $ | 3,326 | $ | 2,634 | $ | 2,344 | ||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Service charges | 714 | 703 | 771 | 933 | 886 | |||||||||||||||||||||||||||||||||||||||
| Investment banking fees | 668 | 706 | 726 | 692 | 880 | |||||||||||||||||||||||||||||||||||||||
| All other income | 914 | 1,149 | 768 | 747 | 1,084 | |||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 2,296 | 2,558 | 2,265 | 2,372 | 2,850 | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 6,203 | 6,438 | 5,591 | 5,006 | 5,194 | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | (237) | 149 | 170 | 157 | 165 | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 2,940 | 2,833 | 2,651 | 2,799 | 2,683 | |||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 3,500 | 3,456 | 2,770 | 2,050 | 2,346 | |||||||||||||||||||||||||||||||||||||||
| Income tax expense | 945 | 916 | 734 | 543 | 622 | |||||||||||||||||||||||||||||||||||||||
| Net income | $ | 2,555 | $ | 2,540 | $ | 2,036 | $ | 1,507 | $ | 1,724 | ||||||||||||||||||||||||||||||||||
| Net interest yield | 3.03 | % | 2.90 | % | 2.53 | % | 1.97 | % | 1.68 | % | ||||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 21 | 23 | 18 | 14 | 16 | |||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 47.41 | 44.03 | 47.41 | 55.90 | 51.65 | |||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 381,009 | $ | 380,385 | $ | 384,305 | $ | 377,248 | $ | 358,807 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 522,374 | 531,206 | 521,555 | 537,660 | 566,277 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 588,886 | 595,525 | 585,683 | 601,945 | 630,517 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 492,577 | 503,472 | 495,154 | 509,261 | 539,912 | |||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 49,250 | 44,500 | 44,500 | 44,500 | 44,500 | |||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 383,491 | $ | 379,107 | $ | 377,711 | $ | 385,376 | $ | 367,423 | ||||||||||||||||||||||||||||||||||
Total earning assets (2) | 524,299 | 522,539 | 511,494 | 526,879 | 558,639 | |||||||||||||||||||||||||||||||||||||||
Total assets (2) | 591,231 | 588,466 | 575,442 | 591,490 | 623,168 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 495,949 | 498,661 | 484,309 | 499,714 | 533,820 | |||||||||||||||||||||||||||||||||||||||
(1)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2)Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 18 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Banking Key Indicators | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
Investment Banking fees (1) | ||||||||||||||||||||||||||||||||||||||||||||
Advisory (2) | $ | 313 | $ | 446 | $ | 397 | $ | 361 | $ | 439 | ||||||||||||||||||||||||||||||||||
| Debt issuance | 290 | 184 | 273 | 283 | 359 | |||||||||||||||||||||||||||||||||||||||
| Equity issuance | 65 | 76 | 56 | 48 | 82 | |||||||||||||||||||||||||||||||||||||||
Total Investment Banking fees (3) | $ | 668 | $ | 706 | $ | 726 | $ | 692 | $ | 880 | ||||||||||||||||||||||||||||||||||
| Business Lending | ||||||||||||||||||||||||||||||||||||||||||||
| Corporate | $ | 1,034 | $ | 1,417 | $ | 902 | $ | 946 | $ | 1,060 | ||||||||||||||||||||||||||||||||||
| Commercial | 1,233 | 1,188 | 1,111 | 1,024 | 993 | |||||||||||||||||||||||||||||||||||||||
| Business Banking | 67 | 65 | 66 | 62 | 58 | |||||||||||||||||||||||||||||||||||||||
| Total Business Lending revenue | $ | 2,334 | $ | 2,670 | $ | 2,079 | $ | 2,032 | $ | 2,111 | ||||||||||||||||||||||||||||||||||
| Global Transaction Services | ||||||||||||||||||||||||||||||||||||||||||||
| Corporate | $ | 1,549 | $ | 1,546 | $ | 1,369 | $ | 1,138 | $ | 949 | ||||||||||||||||||||||||||||||||||
| Commercial | 1,129 | 1,185 | 1,112 | 973 | 896 | |||||||||||||||||||||||||||||||||||||||
| Business Banking | 387 | 378 | 322 | 270 | 243 | |||||||||||||||||||||||||||||||||||||||
| Total Global Transaction Services revenue | $ | 3,065 | $ | 3,109 | $ | 2,803 | $ | 2,381 | $ | 2,088 | ||||||||||||||||||||||||||||||||||
| Average deposit balances | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing | $ | 257,012 | $ | 225,671 | $ | 171,203 | $ | 142,366 | $ | 157,126 | ||||||||||||||||||||||||||||||||||
| Noninterest-bearing | 235,565 | 277,801 | 323,951 | 366,895 | 382,786 | |||||||||||||||||||||||||||||||||||||||
| Total average deposits | $ | 492,577 | $ | 503,472 | $ | 495,154 | $ | 509,261 | $ | 539,912 | ||||||||||||||||||||||||||||||||||
| Loan spread | 1.55 | % | 1.52 | % | 1.51 | % | 1.49 | % | 1.53 | % | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | $ | (237) | $ | 149 | $ | 170 | $ | 157 | $ | 165 | ||||||||||||||||||||||||||||||||||
Credit quality (4, 5) | ||||||||||||||||||||||||||||||||||||||||||||
| Reservable criticized utilized exposure | $ | 18,104 | $ | 17,519 | $ | 15,809 | $ | 15,999 | $ | 18,304 | ||||||||||||||||||||||||||||||||||
| 4.46 | % | 4.37 | % | 3.95 | % | 3.92 | % | 4.72 | % | |||||||||||||||||||||||||||||||||||
| Nonperforming loans, leases and foreclosed properties | $ | 1,023 | $ | 923 | $ | 1,057 | $ | 1,126 | $ | 1,329 | ||||||||||||||||||||||||||||||||||
| 0.27 | % | 0.25 | % | 0.28 | % | 0.29 | % | 0.37 | % | |||||||||||||||||||||||||||||||||||
| Average loans and leases by product | ||||||||||||||||||||||||||||||||||||||||||||
| U.S. commercial | $ | 229,558 | $ | 230,591 | $ | 233,027 | $ | 225,820 | $ | 211,568 | ||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 82,412 | 82,222 | 84,287 | 86,092 | 80,783 | |||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 55,019 | 54,104 | 53,042 | 50,973 | 51,400 | |||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | 14,019 | 13,467 | 13,948 | 14,362 | 15,055 | |||||||||||||||||||||||||||||||||||||||
| Other | 1 | 1 | 1 | 1 | 1 | |||||||||||||||||||||||||||||||||||||||
| Total average loans and leases | $ | 381,009 | $ | 380,385 | $ | 384,305 | $ | 377,248 | $ | 358,807 | ||||||||||||||||||||||||||||||||||
| Total Corporation Investment Banking fees | ||||||||||||||||||||||||||||||||||||||||||||
Advisory (2) | $ | 363 | $ | 486 | $ | 432 | $ | 392 | $ | 473 | ||||||||||||||||||||||||||||||||||
| Debt issuance | 644 | 414 | 616 | 662 | 831 | |||||||||||||||||||||||||||||||||||||||
| Equity issuance | 168 | 189 | 156 | 139 | 225 | |||||||||||||||||||||||||||||||||||||||
| Total investment banking fees including self-led deals | 1,175 | 1,089 | 1,204 | 1,193 | 1,529 | |||||||||||||||||||||||||||||||||||||||
| Self-led deals | (12) | (18) | (37) | (65) | (72) | |||||||||||||||||||||||||||||||||||||||
| Total Investment Banking fees | $ | 1,163 | $ | 1,071 | $ | 1,167 | $ | 1,128 | $ | 1,457 | ||||||||||||||||||||||||||||||||||
(1)Investment banking fees represent total investment banking fees for Global Banking inclusive of self-led deals and fees included within Business Lending.
(2)Advisory includes fees on debt and equity advisory and mergers and acquisitions.
(3)Investment banking fees represent only the fee component in Global Banking and do not include certain other items shared with the Investment Banking Group under internal revenue sharing agreements.
(4)Criticized exposure corresponds to the Special Mention, Substandard and Doubtful asset categories defined by regulatory authorities. The reservable criticized exposure is on an end-of-period basis and is also shown as a percentage of total commercial reservable utilized exposure, including loans and leases, standby letters of credit, financial guarantees, commercial letters of credit and bankers’ acceptances.
(5)Nonperforming loans, leases and foreclosed properties are on an end-of-period basis. The nonperforming ratio is nonperforming assets divided by loans, leases and foreclosed properties.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 19 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Markets Segment Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 109 | $ | 371 | $ | 743 | $ | 981 | $ | 993 | ||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 533 | 482 | 457 | 518 | 545 | |||||||||||||||||||||||||||||||||||||||
| Investment banking fees | 469 | 347 | 430 | 461 | 582 | |||||||||||||||||||||||||||||||||||||||
| Market making and similar activities | 4,398 | 2,685 | 2,874 | 2,657 | 3,190 | |||||||||||||||||||||||||||||||||||||||
| All other income | 117 | (24) | (21) | (115) | (18) | |||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 5,517 | 3,490 | 3,740 | 3,521 | 4,299 | |||||||||||||||||||||||||||||||||||||||
Total revenue, net of interest expense (1) | 5,626 | 3,861 | 4,483 | 4,502 | 5,292 | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | (53) | 4 | 11 | 8 | 5 | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 3,351 | 3,171 | 3,023 | 3,109 | 3,117 | |||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 2,328 | 686 | 1,449 | 1,385 | 2,170 | |||||||||||||||||||||||||||||||||||||||
| Income tax expense | 640 | 182 | 384 | 367 | 575 | |||||||||||||||||||||||||||||||||||||||
| Net income | $ | 1,688 | $ | 504 | $ | 1,065 | $ | 1,018 | $ | 1,595 | ||||||||||||||||||||||||||||||||||
Return on average allocated capital (2) | 15 | % | 5 | % | 10 | % | 10 | % | 15 | % | ||||||||||||||||||||||||||||||||||
| Efficiency ratio | 59.56 | 82.14 | 67.42 | 69.07 | 58.90 | |||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total trading-related assets | $ | 626,035 | $ | 608,493 | $ | 592,391 | $ | 606,135 | $ | 596,154 | ||||||||||||||||||||||||||||||||||
| Total loans and leases | 125,046 | 123,022 | 120,435 | 114,375 | 108,576 | |||||||||||||||||||||||||||||||||||||||
| Total earning assets | 627,935 | 610,045 | 591,883 | 598,832 | 610,926 | |||||||||||||||||||||||||||||||||||||||
| Total assets | 870,038 | 857,319 | 847,899 | 866,742 | 858,719 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 36,109 | 37,219 | 38,820 | 41,192 | 44,393 | |||||||||||||||||||||||||||||||||||||||
Allocated capital (2) | 45,500 | 42,500 | 42,500 | 42,500 | 42,500 | |||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total trading-related assets | $ | 599,841 | $ | 564,769 | $ | 592,938 | $ | 577,309 | $ | 616,811 | ||||||||||||||||||||||||||||||||||
| Total loans and leases | 130,804 | 127,735 | 121,721 | 118,290 | 110,037 | |||||||||||||||||||||||||||||||||||||||
| Total earning assets | 632,873 | 587,772 | 595,988 | 571,921 | 609,290 | |||||||||||||||||||||||||||||||||||||||
| Total assets | 861,477 | 812,489 | 848,752 | 835,129 | 883,304 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 33,624 | 39,077 | 37,318 | 40,055 | 43,371 | |||||||||||||||||||||||||||||||||||||||
| Trading-related assets (average) | ||||||||||||||||||||||||||||||||||||||||||||
| Trading account securities | $ | 339,248 | $ | 309,217 | $ | 308,514 | $ | 295,190 | $ | 301,285 | ||||||||||||||||||||||||||||||||||
| Reverse repurchases | 126,760 | 122,753 | 112,828 | 131,456 | 138,581 | |||||||||||||||||||||||||||||||||||||||
| Securities borrowed | 116,280 | 119,334 | 114,032 | 119,200 | 114,468 | |||||||||||||||||||||||||||||||||||||||
| Derivative assets | 43,747 | 57,189 | 57,017 | 60,289 | 41,820 | |||||||||||||||||||||||||||||||||||||||
| Total trading-related assets | $ | 626,035 | $ | 608,493 | $ | 592,391 | $ | 606,135 | $ | 596,154 | ||||||||||||||||||||||||||||||||||
(1)Substantially all of Global Markets total revenue is sales and trading revenue and investment banking fees, with a small portion related to certain revenue sharing agreements with other business segments. For additional sales and trading revenue information, see page 21.
(2)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 20 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Global Markets Key Indicators | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
Sales and trading revenue (1) | ||||||||||||||||||||||||||||||||||||||||||||
| Fixed-income, currencies and commodities | $ | 3,440 | $ | 2,157 | $ | 2,552 | $ | 2,500 | $ | 2,708 | ||||||||||||||||||||||||||||||||||
| Equities | 1,627 | 1,368 | 1,540 | 1,653 | 2,011 | |||||||||||||||||||||||||||||||||||||||
| Total sales and trading revenue | $ | 5,067 | $ | 3,525 | $ | 4,092 | $ | 4,153 | $ | 4,719 | ||||||||||||||||||||||||||||||||||
Sales and trading revenue, excluding net debit valuation adjustment (2,3) | ||||||||||||||||||||||||||||||||||||||||||||
| Fixed-income, currencies and commodities | $ | 3,429 | $ | 2,343 | $ | 2,567 | $ | 2,340 | $ | 2,648 | ||||||||||||||||||||||||||||||||||
| Equities | 1,624 | 1,375 | 1,539 | 1,655 | 2,002 | |||||||||||||||||||||||||||||||||||||||
| Total sales and trading revenue, excluding net debit valuation adjustment | $ | 5,053 | $ | 3,718 | $ | 4,106 | $ | 3,995 | $ | 4,650 | ||||||||||||||||||||||||||||||||||
| Sales and trading revenue breakdown | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | (74) | $ | 188 | $ | 586 | $ | 851 | $ | 911 | ||||||||||||||||||||||||||||||||||
| Commissions | 529 | 476 | 444 | 504 | 531 | |||||||||||||||||||||||||||||||||||||||
| Trading | 4,398 | 2,684 | 2,873 | 2,656 | 3,190 | |||||||||||||||||||||||||||||||||||||||
| Other | 214 | 177 | 189 | 142 | 87 | |||||||||||||||||||||||||||||||||||||||
| Total sales and trading revenue | $ | 5,067 | $ | 3,525 | $ | 4,092 | $ | 4,153 | $ | 4,719 | ||||||||||||||||||||||||||||||||||
(1) Includes Global Banking sales and trading revenue of $177 million, $262 million, $287 million, $319 million and $179 million for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively.
(2) For this presentation, sales and trading revenue excludes net debit valuation adjustment (DVA) gains (losses) which include net DVA on derivatives, as well as amortization of own credit portion of purchase discount and realized DVA on structured liabilities. Sales and trading revenue excluding net DVA gains (losses) represents a non-GAAP financial measure. We believe the use of this non-GAAP financial measure provides additional useful information to assess the underlying performance of these businesses and to allow better comparison of period-to-period operating performance.
(3)Net DVA gains (losses) were $14 million, $(193) million, $(14) million, $158 million and $69 million for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively. FICC net DVA gains (losses) were $11 million, $(186) million, $(15) million, $160 million and $60 million for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively. Equities net DVA gains (losses) were $3 million, $(7) million, $1 million, $(2) million and $9 million for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 21 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
All Other Results (1) | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 97 | $ | 44 | $ | 37 | $ | 43 | $ | (7) | ||||||||||||||||||||||||||||||||||
| Noninterest income (loss) | (1,555) | (1,880) | (836) | (1,329) | (1,434) | |||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | (1,458) | (1,836) | (799) | (1,286) | (1,441) | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 107 | (42) | (58) | (25) | (47) | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 407 | 655 | 716 | 531 | 583 | |||||||||||||||||||||||||||||||||||||||
| Loss before income taxes | (1,972) | (2,449) | (1,457) | (1,792) | (1,977) | |||||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | (1,865) | (1,760) | (1,176) | (1,474) | (1,613) | |||||||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | (107) | $ | (689) | $ | (281) | $ | (318) | $ | (364) | ||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 10,077 | $ | 10,386 | $ | 10,629 | $ | 14,391 | $ | 15,405 | ||||||||||||||||||||||||||||||||||
Total assets (2) | 172,725 | 136,040 | 142,650 | 124,923 | 154,425 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 24,702 | 19,946 | 20,221 | 19,663 | 20,504 | |||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 9,827 | $ | 10,234 | $ | 10,351 | $ | 10,825 | $ | 15,090 | ||||||||||||||||||||||||||||||||||
Total assets (3) | 267,623 | 155,074 | 128,051 | 136,673 | 132,186 | |||||||||||||||||||||||||||||||||||||||
| Total deposits | 34,590 | 19,905 | 19,031 | 19,374 | 20,990 | |||||||||||||||||||||||||||||||||||||||
(1)All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments.
(2)Includes elimination of segments’ excess asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity of $1.0 trillion, $1.0 trillion, $1.1 trillion, $1.1 trillion and $1.2 trillion for the first quarter of 2023 and the fourth, third, second and first quarters of 2022, respectively.
(3)Includes elimination of segments’ excess asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity of $1.0 trillion, $1.0 trillion, $1.1 trillion, $1.1 trillion and $1.2 trillion at March 31, 2023, December 31, 2022, September 30, 2022, June 30, 2022 and March 31, 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 22 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Outstanding Loans and Leases | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| March 31 2023 | December 31 2022 | March 31 2022 | |||||||||||||||
| Consumer | |||||||||||||||||
| Residential mortgage | $ | 228,827 | $ | 229,670 | $ | 226,030 | |||||||||||
| Home equity | 25,868 | 26,563 | 26,936 | ||||||||||||||
| Credit card | 92,469 | 93,421 | 79,356 | ||||||||||||||
Direct/Indirect consumer (1) | 104,540 | 106,236 | 105,754 | ||||||||||||||
Other consumer (2) | 120 | 156 | 205 | ||||||||||||||
| Total consumer loans excluding loans accounted for under the fair value option | 451,824 | 456,046 | 438,281 | ||||||||||||||
Consumer loans accounted for under the fair value option (3) | 334 | 339 | 568 | ||||||||||||||
| Total consumer | 452,158 | 456,385 | 438,849 | ||||||||||||||
| Commercial | |||||||||||||||||
| U.S. commercial | 360,655 | 358,481 | 330,973 | ||||||||||||||
| Non-U.S. commercial | 124,827 | 124,479 | 122,267 | ||||||||||||||
Commercial real estate (4) | 73,051 | 69,766 | 62,533 | ||||||||||||||
| Commercial lease financing | 13,448 | 13,644 | 14,008 | ||||||||||||||
| 571,981 | 566,370 | 529,781 | |||||||||||||||
U.S. small business commercial (5) | 18,204 | 17,560 | 17,972 | ||||||||||||||
| Total commercial loans excluding loans accounted for under the fair value option | 590,185 | 583,930 | 547,753 | ||||||||||||||
Commercial loans accounted for under the fair value option (3) | 4,063 | 5,432 | 6,543 | ||||||||||||||
| Total commercial | 594,248 | 589,362 | 554,296 | ||||||||||||||
| Total loans and leases | $ | 1,046,406 | $ | 1,045,747 | $ | 993,145 | |||||||||||
(1)Includes primarily auto and specialty lending loans and leases of $52.7 billion, $51.8 billion and $49.7 billion, U.S. securities-based lending loans of $48.1 billion, $50.4 billion and $51.9 billion and non-U.S. consumer loans of $2.8 billion, $3.0 billion and $3.2 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(2)Substantially all of other consumer is consumer overdrafts.
(3)Consumer loans accounted for under the fair value option includes residential mortgage loans of $72 million, $71 million and $248 million and home equity loans of $262 million, $268 million and $320 million at March 31, 2023, December 31, 2022 and March 31, 2022, respectively. Commercial loans accounted for under the fair value option includes U.S. commercial loans of $2.2 billion, $2.9 billion and $4.0 billion and non-U.S. commercial loans of $1.9 billion, $2.5 billion and $2.6 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(4)Includes U.S. commercial real estate loans of $67.2 billion, $64.9 billion and $58.3 billion and non-U.S. commercial real estate loans of $5.8 billion, $4.8 billion and $4.3 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(5)Includes card-related products and Paycheck Protection Program (PPP) loans.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 23 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Quarterly Average Loans and Leases by Business Segment and All Other | ||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 229,275 | $ | 117,747 | $ | 103,700 | $ | 1 | $ | — | $ | 7,827 | ||||||||||||||||||||||||||
| Home equity | 26,513 | 21,571 | 2,444 | — | 200 | 2,298 | ||||||||||||||||||||||||||||||||
| Credit card | 91,775 | 88,731 | 3,045 | — | — | (1) | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 105,657 | 52,728 | 52,927 | — | — | 2 | ||||||||||||||||||||||||||||||||
| Total consumer | 453,220 | 280,777 | 162,116 | 1 | 200 | 10,126 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 376,852 | 22,985 | 52,067 | 229,558 | 72,074 | 168 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 127,003 | — | 999 | 82,412 | 43,478 | 114 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 70,591 | 10 | 6,266 | 55,019 | 9,294 | 2 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 13,686 | — | — | 14,019 | — | (333) | ||||||||||||||||||||||||||||||||
| Total commercial | 588,132 | 22,995 | 59,332 | 381,008 | 124,846 | (49) | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,041,352 | $ | 303,772 | $ | 221,448 | $ | 381,009 | $ | 125,046 | $ | 10,077 | ||||||||||||||||||||||||||
| Fourth Quarter 2022 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 229,364 | $ | 118,051 | $ | 103,331 | $ | 1 | $ | — | $ | 7,981 | ||||||||||||||||||||||||||
| Home equity | 26,983 | 21,834 | 2,485 | — | 207 | 2,457 | ||||||||||||||||||||||||||||||||
| Credit card | 89,575 | 86,540 | 3,036 | — | — | (1) | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 106,598 | 51,501 | 55,093 | — | — | 4 | ||||||||||||||||||||||||||||||||
| Total consumer | 452,520 | 277,926 | 163,945 | 1 | 207 | 10,441 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 378,850 | 22,423 | 54,306 | 230,591 | 71,330 | 200 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 125,983 | 1 | 1,090 | 82,222 | 42,590 | 80 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 68,764 | 10 | 5,753 | 54,104 | 8,895 | 2 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 13,130 | — | — | 13,467 | — | (337) | ||||||||||||||||||||||||||||||||
| Total commercial | 586,727 | 22,434 | 61,149 | 380,384 | 122,815 | (55) | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,039,247 | $ | 300,360 | $ | 225,094 | $ | 380,385 | $ | 123,022 | $ | 10,386 | ||||||||||||||||||||||||||
| First Quarter 2022 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 223,979 | $ | 115,388 | $ | 96,221 | $ | 1 | $ | — | $ | 12,369 | ||||||||||||||||||||||||||
| Home equity | 27,784 | 21,963 | 2,400 | — | 241 | 3,180 | ||||||||||||||||||||||||||||||||
| Credit card | 78,409 | 75,730 | 2,679 | — | — | — | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 104,632 | 49,292 | 55,338 | — | — | 2 | ||||||||||||||||||||||||||||||||
| Total consumer | 434,804 | 262,373 | 156,638 | 1 | 241 | 15,551 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 346,510 | 21,683 | 48,496 | 211,568 | 64,566 | 197 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 118,767 | — | 1,237 | 80,783 | 36,684 | 63 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 63,065 | 12 | 4,566 | 51,400 | 7,085 | 2 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 14,647 | — | — | 15,055 | — | (408) | ||||||||||||||||||||||||||||||||
| Total commercial | 542,989 | 21,695 | 54,299 | 358,806 | 108,335 | (146) | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 977,793 | $ | 284,068 | $ | 210,937 | $ | 358,807 | $ | 108,576 | $ | 15,405 | ||||||||||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 24 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||
Commercial Credit Exposure by Industry (1, 2, 3, 4, 6) | |||||||||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||||||||
| Commercial Utilized | Total Commercial Committed | ||||||||||||||||||||||||||||||||||
| March 31 2023 | December 31 2022 | March 31 2022 | March 31 2023 | December 31 2022 | March 31 2022 | ||||||||||||||||||||||||||||||
| Asset managers & funds | $ | 102,345 | $ | 106,842 | $ | 102,558 | $ | 164,480 | $ | 165,087 | $ | 158,973 | |||||||||||||||||||||||
Real estate (5) | 73,515 | 72,180 | 67,211 | 101,072 | 99,722 | 93,888 | |||||||||||||||||||||||||||||
| Capital goods | 48,146 | 45,580 | 44,545 | 88,060 | 87,314 | 85,942 | |||||||||||||||||||||||||||||
| Finance companies | 58,226 | 55,248 | 50,559 | 81,811 | 79,546 | 76,101 | |||||||||||||||||||||||||||||
| Healthcare equipment and services | 34,245 | 33,554 | 33,164 | 59,280 | 58,761 | 58,264 | |||||||||||||||||||||||||||||
| Materials | 27,224 | 26,304 | 27,570 | 56,244 | 55,589 | 60,017 | |||||||||||||||||||||||||||||
| Retailing | 26,021 | 24,785 | 26,678 | 54,127 | 53,714 | 51,557 | |||||||||||||||||||||||||||||
| Consumer services | 27,475 | 26,980 | 27,045 | 48,491 | 47,372 | 47,344 | |||||||||||||||||||||||||||||
| Government & public education | 33,443 | 34,861 | 35,212 | 46,931 | 48,134 | 49,213 | |||||||||||||||||||||||||||||
| Food, beverage and tobacco | 24,307 | 23,232 | 23,332 | 46,838 | 47,486 | 46,566 | |||||||||||||||||||||||||||||
| Individuals and trusts | 31,874 | 34,897 | 29,340 | 43,488 | 45,572 | 38,961 | |||||||||||||||||||||||||||||
| Commercial services and supplies | 24,136 | 23,628 | 20,818 | 41,711 | 41,596 | 42,809 | |||||||||||||||||||||||||||||
| Utilities | 19,118 | 20,292 | 18,908 | 39,209 | 40,164 | 38,178 | |||||||||||||||||||||||||||||
| Energy | 13,667 | 15,132 | 16,770 | 34,923 | 36,043 | 36,001 | |||||||||||||||||||||||||||||
| Transportation | 22,051 | 22,273 | 21,268 | 33,846 | 33,858 | 32,034 | |||||||||||||||||||||||||||||
| Technology hardware and equipment | 10,500 | 11,441 | 10,551 | 29,807 | 29,825 | 26,479 | |||||||||||||||||||||||||||||
| Global commercial banks | 26,910 | 27,217 | 25,092 | 29,047 | 29,293 | 26,234 | |||||||||||||||||||||||||||||
| Media | 15,102 | 14,781 | 11,693 | 29,006 | 28,216 | 27,525 | |||||||||||||||||||||||||||||
| Software and services | 11,678 | 12,961 | 12,075 | 25,300 | 25,633 | 30,195 | |||||||||||||||||||||||||||||
| Consumer durables and apparel | 10,167 | 10,009 | 10,989 | 21,784 | 21,389 | 22,089 | |||||||||||||||||||||||||||||
| Pharmaceuticals and biotechnology | 6,581 | 7,547 | 6,175 | 21,419 | 26,208 | 19,093 | |||||||||||||||||||||||||||||
| Vehicle dealers | 13,281 | 12,909 | 11,438 | 21,237 | 20,638 | 20,381 | |||||||||||||||||||||||||||||
| Insurance | 10,007 | 10,224 | 6,784 | 19,109 | 19,444 | 18,120 | |||||||||||||||||||||||||||||
| Telecommunication services | 9,646 | 9,679 | 10,500 | 17,666 | 17,349 | 18,453 | |||||||||||||||||||||||||||||
| Automobiles and components | 8,163 | 8,774 | 9,195 | 15,910 | 16,911 | 17,782 | |||||||||||||||||||||||||||||
| Food and staples retailing | 7,331 | 7,157 | 7,304 | 12,507 | 11,908 | 12,772 | |||||||||||||||||||||||||||||
| Financial markets infrastructure (clearinghouses) | 3,013 | 3,913 | 4,359 | 8,526 | 8,752 | 6,966 | |||||||||||||||||||||||||||||
| Religious and social organizations | 2,542 | 2,467 | 2,906 | 4,557 | 4,689 | 5,345 | |||||||||||||||||||||||||||||
| Total commercial credit exposure by industry | $ | 700,714 | $ | 704,867 | $ | 674,039 | $ | 1,196,386 | $ | 1,200,213 | $ | 1,167,282 | |||||||||||||||||||||||
(1)Includes loans and leases, standby letters of credit and financial guarantees, derivative assets, assets held-for-sale, commercial letters of credit, bankers’ acceptances, securitized assets, foreclosed properties and other collateral acquired. Derivative assets are carried at fair value, reflect the effects of legally enforceable master netting agreements and have been reduced by cash collateral of $29.1 billion, $33.8 billion and $34.1 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively. Not reflected in utilized and committed exposure is additional non-cash derivative collateral held of $51.0 billion, $51.1 billion and $45.6 billion, which consists primarily of other marketable securities, at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(2)Total utilized and total committed exposure includes loans of $4.1 billion, $5.4 billion and $6.5 billion and issued letters of credit with a notional amount of $15 million, $28 million and $48 million accounted for under the fair value option at March 31, 2023, December 31, 2022 and March 31, 2022, respectively. In addition, total committed exposure includes unfunded loan commitments accounted for under the fair value option with a notional amount of $3.1 billion, $3.0 billion and $4.0 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(3)Includes U.S. small business commercial exposure.
(4)Includes the notional amount of unfunded legally binding lending commitments net of amounts distributed (e.g., syndicated or participated) to other financial institutions.
(5)Industries are viewed from a variety of perspectives to best isolate the perceived risks. For purposes of this table, the real estate industry is defined based on the primary business activity of the borrowers or the counterparties using operating cash flows and primary source of repayment as key factors.
(6)Includes $749 million, $1.0 billion and $3.0 billion of PPP loan exposure across impacted industries at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 25 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||
| Nonperforming Loans, Leases and Foreclosed Properties | ||||||||||||||||||||||||||||||||
(Dollars in millions) | ||||||||||||||||||||||||||||||||
| March 31 2023 | December 31 2022 | September 30 2022 | June 30 2022 | March 31 2022 | ||||||||||||||||||||||||||||
| Residential mortgage | $ | 2,125 | $ | 2,167 | $ | 2,187 | $ | 2,245 | $ | 2,422 | ||||||||||||||||||||||
| Home equity | 488 | 510 | 532 | 563 | 615 | |||||||||||||||||||||||||||
| Direct/Indirect consumer | 101 | 77 | 41 | 58 | 67 | |||||||||||||||||||||||||||
| Total consumer | 2,714 | 2,754 | 2,760 | 2,866 | 3,104 | |||||||||||||||||||||||||||
| U.S. commercial | 559 | 553 | 640 | 742 | 818 | |||||||||||||||||||||||||||
| Non-U.S. commercial | 125 | 212 | 274 | 279 | 268 | |||||||||||||||||||||||||||
| Commercial real estate | 502 | 271 | 282 | 218 | 361 | |||||||||||||||||||||||||||
| Commercial lease financing | 4 | 4 | 11 | 44 | 54 | |||||||||||||||||||||||||||
| 1,190 | 1,040 | 1,207 | 1,283 | 1,501 | ||||||||||||||||||||||||||||
| U.S. small business commercial | 14 | 14 | 16 | 15 | 20 | |||||||||||||||||||||||||||
| Total commercial | 1,204 | 1,054 | 1,223 | 1,298 | 1,521 | |||||||||||||||||||||||||||
| Total nonperforming loans and leases | 3,918 | 3,808 | 3,983 | 4,164 | 4,625 | |||||||||||||||||||||||||||
| Foreclosed properties | 165 | 170 | 173 | 162 | 153 | |||||||||||||||||||||||||||
Total nonperforming loans, leases and foreclosed properties (1, 2) | $ | 4,083 | $ | 3,978 | $ | 4,156 | $ | 4,326 | $ | 4,778 | ||||||||||||||||||||||
| Fully-insured home loans past due 30 days or more and still accruing | $ | 580 | $ | 627 | $ | 672 | $ | 734 | $ | 817 | ||||||||||||||||||||||
| Consumer credit card past due 30 days or more and still accruing | 1,674 | 1,505 | 1,202 | 1,008 | 1,003 | |||||||||||||||||||||||||||
| Other loans past due 30 days or more and still accruing | 3,146 | 4,008 | 3,281 | 3,494 | 3,736 | |||||||||||||||||||||||||||
Total loans past due 30 days or more and still accruing (3, 4) | $ | 5,400 | $ | 6,140 | $ | 5,155 | $ | 5,236 | $ | 5,556 | ||||||||||||||||||||||
| Fully-insured home loans past due 90 days or more and still accruing | $ | 338 | $ | 368 | $ | 427 | $ | 492 | $ | 574 | ||||||||||||||||||||||
Consumer credit card past due 90 days or more and still accruing | 828 | 717 | 547 | 493 | 492 | |||||||||||||||||||||||||||
| Other loans past due 90 days or more and still accruing | 508 | 626 | 647 | 720 | 607 | |||||||||||||||||||||||||||
Total loans past due 90 days or more and still accruing (4) | $ | 1,674 | $ | 1,711 | $ | 1,621 | $ | 1,705 | $ | 1,673 | ||||||||||||||||||||||
Nonperforming loans, leases and foreclosed properties/Total assets (5) | 0.13 | % | 0.13 | % | 0.14 | % | 0.14 | % | 0.15 | % | ||||||||||||||||||||||
Nonperforming loans, leases and foreclosed properties/Total loans, leases and foreclosed properties (5) | 0.39 | 0.38 | 0.40 | 0.42 | 0.48 | |||||||||||||||||||||||||||
Nonperforming loans and leases/Total loans and leases (5) | 0.38 | 0.37 | 0.39 | 0.41 | 0.47 | |||||||||||||||||||||||||||
Commercial reservable criticized utilized exposure (6) | $ | 19,789 | $ | 19,274 | $ | 17,659 | $ | 18,114 | $ | 20,682 | ||||||||||||||||||||||
Commercial reservable criticized utilized exposure/Commercial reservable utilized exposure (6) | 3.17 | % | 3.12 | % | 2.88 | % | 2.95 | % | 3.54 | % | ||||||||||||||||||||||
Total commercial criticized utilized exposure/Commercial utilized exposure (6) | 3.67 | 3.70 | 2.82 | 2.99 | 3.47 | |||||||||||||||||||||||||||
(1)Balances do not include past due consumer credit card, consumer loans secured by real estate where repayments are insured by the FHA and individually insured long-term stand-by agreements (fully-insured home loans), and in general, other consumer and commercial loans not secured by real estate.
(2)Balances do not include nonperforming loans held-for-sale of $250 million, $219 million, $222 million, $270 million and $336 million at March 31, 2023, December 31, 2022, September 30, 2022, June 30, 2022 and March 31, 2022, respectively.
(3)Balances do not include loans held-for-sale past due 30 days or more and still accruing of $36 million, $58 million, $81 million, $179 million and $654 million at March 31, 2023, December 31, 2022, September 30, 2022, June 30, 2022 and March 31, 2022, respectively.
(4)These balances are excluded from total nonperforming loans, leases and foreclosed properties.
(5)Total assets and total loans and leases do not include loans accounted for under the fair value option of $4.4 billion, $5.8 billion, $4.9 billion, $5.5 billion and $7.1 billion at March 31, 2023, December 31, 2022, September 30, 2022, June 30, 2022 and March 31, 2022, respectively.
(6)Criticized exposure corresponds to the Special Mention, Substandard and Doubtful asset categories defined by regulatory authorities. The reservable criticized exposure excludes loans held-for-sale, exposure accounted for under the fair value option and other nonreservable exposure.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 26 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||
Nonperforming Loans, Leases and Foreclosed Properties Activity (1) | ||||||||||||||||||||||||||||||||
(Dollars in millions) | ||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | ||||||||||||||||||||||||||||
| Nonperforming Consumer Loans and Leases: | ||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 2,754 | $ | 2,760 | $ | 2,866 | $ | 3,104 | $ | 2,989 | ||||||||||||||||||||||
| Additions | 253 | 208 | 236 | 365 | 644 | |||||||||||||||||||||||||||
| Reductions: | ||||||||||||||||||||||||||||||||
| Paydowns and payoffs | (103) | (89) | (124) | (147) | (175) | |||||||||||||||||||||||||||
| Sales | (2) | (1) | (1) | (269) | (131) | |||||||||||||||||||||||||||
Returns to performing status (2) | (170) | (109) | (193) | (157) | (202) | |||||||||||||||||||||||||||
Charge-offs (3) | (12) | (6) | (12) | (23) | (15) | |||||||||||||||||||||||||||
| Transfers to foreclosed properties | (6) | (9) | (12) | (7) | (6) | |||||||||||||||||||||||||||
| Total net additions (reductions) to nonperforming loans and leases | (40) | (6) | (106) | (238) | 115 | |||||||||||||||||||||||||||
| Total nonperforming consumer loans and leases, end of period | 2,714 | 2,754 | 2,760 | 2,866 | 3,104 | |||||||||||||||||||||||||||
| Foreclosed properties | 117 | 121 | 125 | 115 | 118 | |||||||||||||||||||||||||||
| Nonperforming consumer loans, leases and foreclosed properties, end of period | $ | 2,831 | $ | 2,875 | $ | 2,885 | $ | 2,981 | $ | 3,222 | ||||||||||||||||||||||
Nonperforming Commercial Loans and Leases (4): | ||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 1,054 | $ | 1,223 | $ | 1,298 | $ | 1,521 | $ | 1,578 | ||||||||||||||||||||||
| Additions | 419 | 141 | 307 | 321 | 183 | |||||||||||||||||||||||||||
| Reductions: | ||||||||||||||||||||||||||||||||
| Paydowns | (72) | (144) | (180) | (342) | (159) | |||||||||||||||||||||||||||
| Sales | — | (4) | (12) | (16) | (25) | |||||||||||||||||||||||||||
Returns to performing status (5) | (52) | (35) | (148) | (146) | (5) | |||||||||||||||||||||||||||
| Charge-offs | (88) | (127) | (42) | (40) | (12) | |||||||||||||||||||||||||||
| Transfers to loans held-for-sale | (57) | — | — | — | (39) | |||||||||||||||||||||||||||
| Total net additions (reductions) to nonperforming loans and leases | 150 | (169) | (75) | (223) | (57) | |||||||||||||||||||||||||||
| Total nonperforming commercial loans and leases, end of period | 1,204 | 1,054 | 1,223 | 1,298 | 1,521 | |||||||||||||||||||||||||||
| Foreclosed properties | 48 | 49 | 48 | 47 | 35 | |||||||||||||||||||||||||||
| Nonperforming commercial loans, leases and foreclosed properties, end of period | $ | 1,252 | $ | 1,103 | $ | 1,271 | $ | 1,345 | $ | 1,556 | ||||||||||||||||||||||
(1)For amounts excluded from nonperforming loans, leases and foreclosed properties, see footnotes to Nonperforming Loans, Leases and Foreclosed Properties table on page 26.
(2)Consumer loans and leases may be returned to performing status when all principal and interest is current and full repayment of the remaining contractual principal and interest is expected, or when the loan otherwise becomes well-secured and is in the process of collection. Prior to January 1, 2023, certain troubled debt restructurings were classified as nonperforming at the time of restructuring and were only returned to performing status after considering the borrower’s sustained repayment performance for a reasonable period, generally six months.
(3)Our policy is not to classify consumer credit card and non-bankruptcy related consumer loans not secured by real estate as nonperforming; therefore, the charge-offs on these loans have no impact on nonperforming activity and, accordingly, are excluded from this table.
(4)Includes U.S. small business commercial activity. Small business card loans are excluded as they are not classified as nonperforming.
(5)Commercial loans and leases may be returned to performing status when all principal and interest is current and full repayment of the remaining contractual principal and interest is expected, or when the loan otherwise becomes well-secured and is in the process of collection. Prior to January 1, 2023, troubled debt restructurings were generally classified as performing after a sustained period of demonstrated payment performance.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 27 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Quarterly Net Charge-offs and Net Charge-off Ratios (1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amount | Percent | Amount | Percent | Amount | Percent | Amount | Percent | Amount | Percent | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Charge-offs | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgage (2) | $ | 1 | — | % | $ | (1) | — | % | $ | (3) | (0.01) | % | $ | 86 | 0.15 | % | $ | (10) | (0.02) | % | |||||||||||||||||||||||||||||||||||||||
Home equity (3) | (12) | (0.18) | (18) | (0.27) | (18) | (0.25) | (24) | (0.37) | (30) | (0.44) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 501 | 2.21 | 386 | 1.71 | 328 | 1.53 | 323 | 1.60 | 297 | 1.53 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Direct/Indirect consumer | 1 | — | 1 | — | 9 | 0.03 | 4 | 0.02 | 4 | 0.02 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 162 | n/m | 163 | n/m | 143 | n/m | 136 | n/m | 79 | n/m | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer | 653 | 0.58 | 531 | 0.47 | 459 | 0.41 | 525 | 0.47 | 340 | 0.32 | |||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 47 | 0.05 | 47 | 0.05 | 23 | 0.03 | 15 | 0.02 | (14) | (0.02) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 20 | 0.07 | 31 | 0.10 | (6) | (0.02) | (5) | (0.01) | 1 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial and industrial | 67 | 0.06 | 78 | 0.06 | 17 | 0.01 | 10 | 0.01 | (13) | (0.01) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 22 | 0.12 | 34 | 0.20 | 13 | 0.08 | (4) | (0.03) | 23 | 0.15 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | (1) | (0.01) | 2 | 0.05 | (1) | (0.05) | 4 | 0.13 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| 88 | 0.06 | 114 | 0.08 | 29 | 0.02 | 10 | 0.01 | 10 | 0.01 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. small business commercial | 66 | 1.48 | 44 | 0.99 | 32 | 0.72 | 36 | 0.79 | 42 | 0.94 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 154 | 0.11 | 158 | 0.11 | 61 | 0.04 | 46 | 0.03 | 52 | 0.04 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total net charge-offs | $ | 807 | 0.32 | $ | 689 | 0.26 | $ | 520 | 0.20 | $ | 571 | 0.23 | $ | 392 | 0.16 | ||||||||||||||||||||||||||||||||||||||||||||
| By Business Segment and All Other | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking | $ | 729 | 0.97 | % | $ | 591 | 0.78 | % | $ | 512 | 0.69 | % | $ | 502 | 0.70 | % | $ | 416 | 0.59 | % | |||||||||||||||||||||||||||||||||||||||
| Global Wealth & Investment Management | 6 | 0.01 | 4 | 0.01 | 5 | 0.01 | 9 | 0.02 | 1 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Global Banking | 87 | 0.09 | 112 | 0.12 | 26 | 0.03 | 14 | 0.01 | (12) | (0.01) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Global Markets | — | — | (1) | (0.01) | (1) | — | (4) | (0.01) | 21 | 0.08 | |||||||||||||||||||||||||||||||||||||||||||||||||
| All Other | (15) | (0.59) | (17) | (0.66) | (22) | (0.80) | 50 | 1.40 | (34) | (0.91) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total net charge-offs | $ | 807 | 0.32 | $ | 689 | 0.26 | $ | 520 | 0.20 | $ | 571 | 0.23 | $ | 392 | 0.16 | ||||||||||||||||||||||||||||||||||||||||||||
(1)Net charge-off ratios are calculated as annualized net charge-offs divided by average outstanding loans and leases excluding loans accounted for under the fair value option during the period for each loan and lease category.
(2)Includes loan sale net charge-offs (recoveries) of $90 million and $(6) million for the second and first quarters of 2022 and $0 for the remaining quarters.
(3)Includes loan sale net recoveries of $6 million and $2 million for the second and first quarters of 2022 and $0 for the remaining quarters.
n/m = not meaningful
| Current-period information is preliminary and based on company data available at the time of the presentation. | 28 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allocation of the Allowance for Credit Losses by Product Type | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2023 | December 31, 2022 | March 31, 2022 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amount | Percent of Loans and Leases Outstanding (1, 2) | Amount | Percent of Loans and Leases Outstanding (1, 2) | Amount | Percent of Loans and Leases Outstanding (1, 2) | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 305 | 0.13% | $ | 328 | 0.14% | $ | 301 | 0.13% | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 98 | 0.38 | 92 | 0.35 | 172 | 0.64 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 6,220 | 6.73 | 6,136 | 6.57 | 5,684 | 7.16 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Direct/Indirect consumer | 628 | 0.60 | 585 | 0.55 | 512 | 0.48 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 110 | n/m | 96 | n/m | 46 | n/m | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer | 7,361 | 1.63 | 7,237 | 1.59 | 6,715 | 1.53 | ||||||||||||||||||||||||||||||||||||||||||||||||||
U.S. commercial (3) | 2,835 | 0.75 | 3,007 | 0.80 | 2,966 | 0.85 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 1,019 | 0.82 | 1,194 | 0.96 | 1,155 | 0.94 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 1,253 | 1.72 | 1,192 | 1.71 | 1,218 | 1.95 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | 46 | 0.34 | 52 | 0.38 | 50 | 0.36 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 5,153 | 0.87 | 5,445 | 0.93 | 5,389 | 0.98 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses | 12,514 | 1.20 | 12,682 | 1.22 | 12,104 | 1.23 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Reserve for unfunded lending commitments | 1,437 | 1,540 | 1,379 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | $ | 13,951 | $ | 14,222 | $ | 13,483 | ||||||||||||||||||||||||||||||||||||||||||||||||||
Asset Quality Indicators | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Allowance for loan and lease losses/Total loans and leases (2) | 1.20% | 1.22% | 1.23% | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Allowance for loan and lease losses/Total nonperforming loans and leases (4) | 319 | 333 | 262 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Ratio of the allowance for loan and lease losses/Annualized net charge-offs | 3.83 | 4.64 | 7.62 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Ratios are calculated as allowance for loan and lease losses as a percentage of loans and leases outstanding excluding loans accounted for under the fair value option. Consumer loans accounted for under the fair value option include residential mortgage loans of $72 million, $71 million and $248 million, and home equity loans of $262 million, $268 million and $320 million at March 31, 2023, December 31, 2022 and March 31, 2022, respectively. Commercial loans accounted for under the fair value option include U.S. commercial loans of $2.2 billion, $2.9 billion and $4.0 billion and non-U.S. commercial loans of $1.9 billion, $2.5 billion and $2.6 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(2)Total loans and leases do not include loans accounted for under the fair value option of $4.4 billion, $5.8 billion and $7.1 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(3)Includes allowance for loan and lease losses for U.S. small business commercial loans of $864 million, $844 million and $1.0 billion at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
(4)Allowance for loan and lease losses includes $7.1 billion, $7.0 billion and $6.6 billion allocated to products (primarily the Consumer Lending portfolios within Consumer Banking) that are excluded from nonperforming loans and leases at March 31, 2023, December 31, 2022 and March 31, 2022, respectively. Excluding these amounts, allowance for loan and lease losses as a percentage of total nonperforming loans and leases was 138 percent, 149 percent and 118 percent at March 31, 2023, December 31, 2022 and March 31, 2022, respectively.
n/m = not meaningful
| Current-period information is preliminary and based on company data available at the time of the presentation. | 29 | ||||
| Exhibit A: Non-GAAP Reconciliations | |||||||||||||||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Reconciliations to GAAP Financial Measures | |||||||||||||||||
| (Dollars in millions, except per share information) | |||||||||||||||||
The Corporation evaluates its business based on the following ratios that utilize tangible equity, a non-GAAP financial measure. Tangible equity represents shareholders’ equity or common shareholders’ equity reduced by goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities ("adjusted" shareholders' equity or common shareholders’ equity). Return on average tangible common shareholders’ equity measures the Corporation’s net income applicable to common shareholders as a percentage of adjusted average common shareholders’ equity. The tangible common equity ratio represents adjusted ending common shareholders’ equity divided by total tangible assets (total assets less goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities). Return on average tangible shareholders’ equity measures the Corporation’s net income as a percentage of adjusted average total shareholders’ equity. The tangible equity ratio represents adjusted ending shareholders’ equity divided by total tangible assets. Tangible book value per common share represents adjusted ending common shareholders’ equity divided by ending common shares outstanding. These measures are used to evaluate the Corporation’s use of equity. In addition, profitability, relationship and investment models all use return on average tangible shareholders’ equity as key measures to support our overall growth goals.
See the tables below for reconciliations of these non-GAAP financial measures to the most closely related financial measures defined by GAAP for the three months ended March 31, 2023, December 31, 2022, September 30, 2022, June 30, 2022 and March 31, 2022. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. Other companies may define or calculate supplemental financial data differently.
| First Quarter 2023 | Fourth Quarter 2022 | Third Quarter 2022 | Second Quarter 2022 | First Quarter 2022 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of income before income taxes to pretax, pre-provision income | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Income before income taxes | $ | 9,089 | $ | 7,897 | $ | 8,301 | $ | 6,892 | $ | 7,879 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 931 | 1,092 | 898 | 523 | 30 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Pretax, pre-provision income | $ | 10,020 | $ | 8,989 | $ | 9,199 | $ | 7,415 | $ | 7,909 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of average shareholders’ equity to average tangible shareholders’ equity and average tangible common shareholders’ equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | $ | 277,252 | $ | 272,629 | $ | 271,017 | $ | 268,197 | $ | 269,309 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Goodwill | (69,022) | (69,022) | (69,022) | (69,022) | (69,022) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (2,068) | (2,088) | (2,107) | (2,127) | (2,146) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Related deferred tax liabilities | 899 | 914 | 920 | 926 | 929 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders’ equity | $ | 207,061 | $ | 202,433 | $ | 200,808 | $ | 197,974 | $ | 199,070 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred stock | (28,397) | (28,982) | (29,134) | (28,674) | (26,444) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 178,664 | $ | 173,451 | $ | 171,674 | $ | 169,300 | $ | 172,626 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of period-end shareholders’ equity to period-end tangible shareholders’ equity and period-end tangible common shareholders’ equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | $ | 280,196 | $ | 273,197 | $ | 269,524 | $ | 269,118 | $ | 266,617 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Goodwill | (69,022) | (69,022) | (69,022) | (69,022) | (69,022) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (2,055) | (2,075) | (2,094) | (2,114) | (2,133) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Related deferred tax liabilities | 895 | 899 | 915 | 920 | 926 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible shareholders’ equity | $ | 210,014 | $ | 202,999 | $ | 199,323 | $ | 198,902 | $ | 196,388 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred stock | (28,397) | (28,397) | (29,134) | (29,134) | (27,137) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 181,617 | $ | 174,602 | $ | 170,189 | $ | 169,768 | $ | 169,251 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Reconciliation of period-end assets to period-end tangible assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets | $ | 3,194,657 | $ | 3,051,375 | $ | 3,072,953 | $ | 3,111,606 | $ | 3,238,223 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Goodwill | (69,022) | (69,022) | (69,022) | (69,022) | (69,022) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (2,055) | (2,075) | (2,094) | (2,114) | (2,133) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Related deferred tax liabilities | 895 | 899 | 915 | 920 | 926 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible assets | $ | 3,124,475 | $ | 2,981,177 | $ | 3,002,752 | $ | 3,041,390 | $ | 3,167,994 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Book value per share of common stock | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Common shareholders’ equity | $ | 251,799 | $ | 244,800 | $ | 240,390 | $ | 239,984 | $ | 239,480 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Ending common shares issued and outstanding | 7,972.4 | 7,996.8 | 8,024.5 | 8,035.2 | 8,062.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Book value per share of common stock | $ | 31.58 | $ | 30.61 | $ | 29.96 | $ | 29.87 | $ | 29.70 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible book value per share of common stock | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 181,617 | $ | 174,602 | $ | 170,189 | $ | 169,768 | $ | 169,251 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Ending common shares issued and outstanding | 7,972.4 | 7,996.8 | 8,024.5 | 8,035.2 | 8,062.1 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Tangible book value per share of common stock | $ | 22.78 | $ | 21.83 | $ | 21.21 | $ | 21.13 | $ | 20.99 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 30 | ||||