
PNC 8-K
Pnc Financial Services Group, Inc. (PNC)
8-K
2021-04-16
For: 2021-04-16
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported)
THE PNC FINANCIAL SERVICES GROUP, INC.
(Exact name of registrant as specified in its charter)
Commission File Number 001-09718
| (State or other jurisdiction of | (I.R.S. Employer | ||||
| incorporation) | Identification No.) | ||||
The Tower at PNC Plaza
(Address of principal executive offices, including zip code)
(888 ) 762-2265
(Registrant’s telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||
Floating Rate Non-Cumulative Perpetual Preferred Stock, Series P | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 16, 2021 , The PNC Financial Services Group, Inc. (“the Corporation”) issued a press release regarding the Corporation’s earnings and business results for the first quarter of 2021. In connection therewith, the Corporation provided supplementary financial information on its web site. A copy of the Corporation’s supplementary financial information is included in this Report as Exhibit 99.1 and is furnished herewith.
Item 8.01 Other Events
On April 16, 2021 , the Corporation held a conference call for investors regarding the Corporation’s earnings and business results for the first quarter of 2021. The Corporation provided electronic presentation slides on its web site used in connection with the related investor conference call. Copies of the electronic presentation slides are included in this Report as Exhibit 99.2 and are furnished herewith.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| Number | Description | Method of Filing | ||||||
| 99.1 | Furnished herewith | |||||||
| 99.2 | Furnished herewith | |||||||
| 104 | The cover page of this Current Report on Form 8-K, formatted in Inline XBRL. | |||||||
- 2 -
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
THE PNC FINANCIAL SERVICES GROUP, INC. (Registrant) | |||||||||||
| Date: | April 16, 2021 | By: | Gregory H. Kozich | ||||||||
| Gregory H. Kozich | |||||||||||
| Senior Vice President and Controller | |||||||||||
- 3 -
Exhibit 99.1
THE PNC FINANCIAL SERVICES GROUP, INC.
FINANCIAL SUPPLEMENT
FIRST QUARTER 2021
(Unaudited)
THE PNC FINANCIAL SERVICES GROUP, INC.
FINANCIAL SUPPLEMENT
FIRST QUARTER 2021
(UNAUDITED)
The information contained in this Financial Supplement is preliminary, unaudited and based on data available on April 16, 2021. We have reclassified certain prior period amounts to be consistent with the current period presentation, which we believe is more meaningful to readers of our consolidated financial statements. This information speaks only as of the particular date or dates included in the schedules. We do not undertake any obligation to, and disclaim any duty to, correct or update any of the information provided in this Financial Supplement. Our future financial performance is subject to risks and uncertainties as described in our United States Securities and Exchange Commission (SEC) filings.
BUSINESS
PNC is one of the largest diversified financial services companies in the United States (U.S) and is headquartered in Pittsburgh, Pennsylvania. PNC has businesses engaged in retail banking, including residential mortgage, corporate and institutional banking and asset management, providing many of its products and services nationally. PNC's retail branch network is located primarily in markets across the Mid-Atlantic, Midwest and Southeast. PNC also has strategic international offices in four countries outside the U.S.
DISCONTINUED OPERATIONS
On May 15, 2020, PNC completed the sale of its 31.6 million shares of BlackRock, Inc., common and preferred stock through a registered secondary offering. In addition, BlackRock repurchased 2.65 million shares from PNC. The total proceeds from the sale were $14.2 billion in cash, net of $0.2 billion in expenses, and resulted in a gain on sale of $4.3 billion. Additionally, PNC contributed 500,000 BlackRock shares to the PNC Foundation on May 18, 2020. As a result, PNC has divested its entire holding in BlackRock. PNC and its affiliates only hold shares of BlackRock stock in a fiduciary capacity for clients of PNC and its affiliates. Activity for BlackRock for all periods presented on the Consolidated Income Statement have been reclassified to discontinued operations and prior period BlackRock investment balances have been reclassified to the Asset held for sale line on the Consolidated Balance Sheet in accordance with Accounting Standard Codification (ASC) 205-20, Presentation of Financial Statements - Discontinued Operations.
PENDING ACQUISITION OF BBVA USA BANCSHARES, INC.
On November 16, 2020, PNC announced the signing of a definitive agreement with BBVA, S.A. to acquire BBVA USA Bancshares, Inc., a U.S. financial holding company conducting its business operations primarily through its U.S. banking subsidiary, BBVA USA for a fixed purchase price of $11.6 billion in cash. BBVA USA has over 600 branches in Texas, Alabama, Arizona, California, Florida, Colorado and New Mexico. The transaction is expected to add approximately $102 billion in total assets, $86 billion of deposits and $66 billion of loans to PNC's Consolidated Balance Sheet and to close in mid-2021, subject to customary closing conditions, including receipt of regulatory approvals.
| THE PNC FINANCIAL SERVICES GROUP, INC. | ||||||||
| Cross Reference Index to First Quarter 2021 Financial Supplement (Unaudited) | ||||||||
| Financial Supplement Table Reference | ||||||||
| Table | Description | Page | ||||||
| 1 | ||||||||
| 2 | ||||||||
| 3 | ||||||||
| 4 | ||||||||
| 5 | ||||||||
| 6 | ||||||||
| 7 | ||||||||
| 8 | ||||||||
| 9 | ||||||||
| 10 | ||||||||
| 11 | ||||||||
| 12 | ||||||||
| 13 | ||||||||
| 14 | ||||||||
| 15 | ||||||||
| 16 | ||||||||
| 17 | ||||||||
| 18 | 15-16 | |||||||
| 19 | ||||||||
| 20 | ||||||||
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 1 | |||||||
Table 1: Consolidated Income Statement (Unaudited)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| In millions, except per share data | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Interest Income | |||||||||||||||||||||||||||||
| Loans | $ | 1,996 | $ | 2,074 | $ | 2,116 | $ | 2,257 | $ | 2,480 | |||||||||||||||||||
| Investment securities | 421 | 442 | 490 | 527 | 582 | ||||||||||||||||||||||||
| Other | 66 | 60 | 70 | 71 | 138 | ||||||||||||||||||||||||
| Total interest income | 2,483 | 2,576 | 2,676 | 2,855 | 3,200 | ||||||||||||||||||||||||
| Interest Expense | |||||||||||||||||||||||||||||
| Deposits | 40 | 53 | 74 | 141 | 375 | ||||||||||||||||||||||||
| Borrowed funds | 95 | 99 | 118 | 187 | 314 | ||||||||||||||||||||||||
| Total interest expense | 135 | 152 | 192 | 328 | 689 | ||||||||||||||||||||||||
| Net interest income | 2,348 | 2,424 | 2,484 | 2,527 | 2,511 | ||||||||||||||||||||||||
| Noninterest Income | |||||||||||||||||||||||||||||
| Asset management | 226 | 221 | 215 | 199 | 201 | ||||||||||||||||||||||||
| Consumer services | 384 | 387 | 390 | 330 | 377 | ||||||||||||||||||||||||
| Corporate services | 555 | 650 | 479 | 512 | 526 | ||||||||||||||||||||||||
| Residential mortgage | 105 | 99 | 137 | 158 | 210 | ||||||||||||||||||||||||
| Service charges on deposits | 119 | 134 | 119 | 79 | 168 | ||||||||||||||||||||||||
| Other (a) | 483 | 293 | 457 | 271 | 343 | ||||||||||||||||||||||||
| Total noninterest income | 1,872 | 1,784 | 1,797 | 1,549 | 1,825 | ||||||||||||||||||||||||
| Total revenue | 4,220 | 4,208 | 4,281 | 4,076 | 4,336 | ||||||||||||||||||||||||
| Provision For (Recapture of) Credit Losses | (551) | (254) | 52 | 2,463 | 914 | ||||||||||||||||||||||||
| Noninterest Expense | |||||||||||||||||||||||||||||
| Personnel | 1,477 | 1,521 | 1,410 | 1,373 | 1,369 | ||||||||||||||||||||||||
| Occupancy | 215 | 215 | 205 | 199 | 207 | ||||||||||||||||||||||||
| Equipment | 293 | 296 | 292 | 301 | 287 | ||||||||||||||||||||||||
| Marketing | 45 | 64 | 67 | 47 | 58 | ||||||||||||||||||||||||
| Other | 544 | 612 | 557 | 595 | 622 | ||||||||||||||||||||||||
| Total noninterest expense | 2,574 | 2,708 | 2,531 | 2,515 | 2,543 | ||||||||||||||||||||||||
| Income (loss) from continuing operations before income taxes and noncontrolling interests | 2,197 | 1,754 | 1,698 | (902) | 879 | ||||||||||||||||||||||||
| Income taxes (benefit) from continuing operations | 371 | 298 | 166 | (158) | 120 | ||||||||||||||||||||||||
| Net income (loss) from continuing operations | 1,826 | 1,456 | 1,532 | (744) | 759 | ||||||||||||||||||||||||
| Income from discontinued operations before taxes | 5,596 | 181 | |||||||||||||||||||||||||||
| Income taxes from discontinued operations | 1,197 | 25 | |||||||||||||||||||||||||||
| Net income from discontinued operations | 4,399 | 156 | |||||||||||||||||||||||||||
| Net income | 1,826 | 1,456 | 1,532 | 3,655 | 915 | ||||||||||||||||||||||||
| Less: Net income attributable to noncontrolling interests | 10 | 14 | 13 | 7 | 7 | ||||||||||||||||||||||||
| Preferred stock dividends (b) | 57 | 48 | 63 | 55 | 63 | ||||||||||||||||||||||||
| Preferred stock discount accretion and redemptions | 1 | 1 | 1 | 1 | 1 | ||||||||||||||||||||||||
| Net income attributable to common shareholders | $ | 1,758 | $ | 1,393 | $ | 1,455 | $ | 3,592 | $ | 844 | |||||||||||||||||||
| Earnings Per Common Share | |||||||||||||||||||||||||||||
| Basic earnings (loss) from continuing operations | $ | 4.11 | $ | 3.26 | $ | 3.40 | $ | (1.90) | $ | 1.59 | |||||||||||||||||||
| Basic earnings from discontinued operations | 10.28 | 0.37 | |||||||||||||||||||||||||||
| Total basic earnings | $ | 4.11 | $ | 3.26 | $ | 3.40 | $ | 8.40 | $ | 1.96 | |||||||||||||||||||
| Diluted earnings (loss) from continuing operations | $ | 4.10 | $ | 3.26 | $ | 3.39 | $ | (1.90) | $ | 1.59 | |||||||||||||||||||
| Diluted earnings from discontinued operations | 10.28 | 0.36 | |||||||||||||||||||||||||||
| Total diluted earnings | $ | 4.10 | $ | 3.26 | $ | 3.39 | $ | 8.40 | $ | 1.95 | |||||||||||||||||||
| Average Common Shares Outstanding | |||||||||||||||||||||||||||||
| Basic | 426 | 425 | 426 | 426 | 429 | ||||||||||||||||||||||||
| Diluted | 426 | 426 | 426 | 426 | 430 | ||||||||||||||||||||||||
| Efficiency | 61 | % | 64 | % | 59 | % | 62 | % | 59 | % | |||||||||||||||||||
| Noninterest income to total revenue | 44 | % | 42 | % | 42 | % | 38 | % | 42 | % | |||||||||||||||||||
| Effective tax rate from continuing operations (c) | 16.9 | % | 17.0 | % | 9.8 | % | 17.5 | % | 13.7 | % | |||||||||||||||||||
(a)Includes net gains on sales of securities of $25 million, $51 million, $32 million, $40 million and $182 million for the quarters ended March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020, respectively.
(b)Dividends are payable quarterly other than Series O, Series R and Series S preferred stock, which are payable semiannually, with the Series O payable in different quarters than the Series R and Series S preferred stock.
(c)The effective income tax rates are generally lower than the statutory rate due to the relationship of pretax income to tax credits and earnings that are not subject to tax.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 2 | |||||||
Table 2: Consolidated Balance Sheet (Unaudited)
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| In millions, except par value | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 7,455 | $ | 7,017 | $ | 6,629 | $ | 6,338 | $ | 7,493 | |||||||||||||||||||
| Interest-earning deposits with banks (a) | 86,161 | 85,173 | 70,959 | 50,233 | 19,986 | ||||||||||||||||||||||||
| Loans held for sale (b) | 1,967 | 1,597 | 1,787 | 1,443 | 1,693 | ||||||||||||||||||||||||
| Asset held for sale (c) | 8,511 | ||||||||||||||||||||||||||||
| Investment securities – available for sale | 96,799 | 87,358 | 89,747 | 97,052 | 89,077 | ||||||||||||||||||||||||
| Investment securities – held to maturity | 1,456 | 1,441 | 1,438 | 1,441 | 1,469 | ||||||||||||||||||||||||
| Loans (b) | 237,013 | 241,928 | 249,279 | 258,236 | 264,643 | ||||||||||||||||||||||||
| Allowance for loan and lease losses | (4,714) | (5,361) | (5,751) | (5,928) | (3,944) | ||||||||||||||||||||||||
| Net loans | 232,299 | 236,567 | 243,528 | 252,308 | 260,699 | ||||||||||||||||||||||||
| Equity investments | 6,386 | 6,052 | 4,938 | 4,943 | 4,694 | ||||||||||||||||||||||||
| Mortgage servicing rights | 1,680 | 1,242 | 1,113 | 1,067 | 1,082 | ||||||||||||||||||||||||
| Goodwill | 9,317 | 9,233 | 9,233 | 9,233 | 9,233 | ||||||||||||||||||||||||
| Other (b) | 30,894 | 30,999 | 32,445 | 34,920 | 41,556 | ||||||||||||||||||||||||
| Total assets | $ | 474,414 | $ | 466,679 | $ | 461,817 | $ | 458,978 | $ | 445,493 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing | $ | 120,641 | $ | 112,637 | $ | 107,281 | $ | 99,458 | $ | 81,614 | |||||||||||||||||||
| Interest-bearing | 254,426 | 252,708 | 247,798 | 246,539 | 223,590 | ||||||||||||||||||||||||
| Total deposits | 375,067 | 365,345 | 355,079 | 345,997 | 305,204 | ||||||||||||||||||||||||
| Borrowed funds | |||||||||||||||||||||||||||||
| Federal Home Loan Bank borrowings | 1,500 | 3,500 | 5,500 | 8,500 | 23,491 | ||||||||||||||||||||||||
| Bank notes and senior debt | 22,139 | 24,271 | 26,839 | 27,704 | 31,438 | ||||||||||||||||||||||||
| Subordinated debt | 6,241 | 6,403 | 6,465 | 6,500 | 6,475 | ||||||||||||||||||||||||
| Other (b) | 3,150 | 3,021 | 3,306 | 4,322 | 11,995 | ||||||||||||||||||||||||
| Total borrowed funds | 33,030 | 37,195 | 42,110 | 47,026 | 73,399 | ||||||||||||||||||||||||
| Allowance for unfunded lending related commitments | 507 | 584 | 689 | 662 | 450 | ||||||||||||||||||||||||
| Accrued expenses and other liabilities | 11,931 | 9,514 | 10,629 | 12,345 | 17,150 | ||||||||||||||||||||||||
| Total liabilities | 420,535 | 412,638 | 408,507 | 406,030 | 396,203 | ||||||||||||||||||||||||
| Equity | |||||||||||||||||||||||||||||
| Preferred stock (d) | |||||||||||||||||||||||||||||
| Common stock - $5 par value | |||||||||||||||||||||||||||||
| Authorized 800 shares, issued 543, 543, 542, 542, and 542 shares | 2,713 | 2,713 | 2,712 | 2,712 | 2,712 | ||||||||||||||||||||||||
| Capital surplus | 15,879 | 15,884 | 15,836 | 16,284 | 16,288 | ||||||||||||||||||||||||
| Retained earnings | 48,113 | 46,848 | 45,947 | 44,986 | 41,885 | ||||||||||||||||||||||||
| Accumulated other comprehensive income | 1,290 | 2,770 | 2,997 | 3,069 | 2,518 | ||||||||||||||||||||||||
| Common stock held in treasury at cost:118, 119, 118, 117 and 118 shares | (14,146) | (14,205) | (14,216) | (14,128) | (14,140) | ||||||||||||||||||||||||
| Total shareholders’ equity | 53,849 | 54,010 | 53,276 | 52,923 | 49,263 | ||||||||||||||||||||||||
| Noncontrolling interests | 30 | 31 | 34 | 25 | 27 | ||||||||||||||||||||||||
| Total equity | 53,879 | 54,041 | 53,310 | 52,948 | 49,290 | ||||||||||||||||||||||||
| Total liabilities and equity | $ | 474,414 | $ | 466,679 | $ | 461,817 | $ | 458,978 | $ | 445,493 | |||||||||||||||||||
(a)Amounts include balances held with the Federal Reserve Bank of Cleveland of $85.8 billion, $84.9 billion, $70.6 billion, $50.0 billion and $19.6 billion as of March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020, respectively.
(b)Amounts include assets and liabilities for which PNC has elected the fair value option. Our 2020 Form 10-K included, and our first quarter 2021 Form 10-Q will include, additional information regarding these items.
(c)Represents our held for sale investment in BlackRock. In the second quarter of 2020, PNC divested its entire holding in BlackRock. Prior period BlackRock investment balances have been reclassified to the Asset held for sale line in accordance with Accounting Standards Codification 205-20, Presentation of Financial Statements - Discontinued Operations. Our 2020 Form 10-K included additional information related to this divestiture.
(d)Par value less than $0.5 million at each date.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 3 | |||||||
| Table 3: Average Consolidated Balance Sheet (Unaudited) (a) | |||||||||||||||||||||||||||||
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| In millions | 2021 | 2021 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||
| Investment securities | |||||||||||||||||||||||||||||
| Securities available for sale | |||||||||||||||||||||||||||||
| Residential mortgage-backed | |||||||||||||||||||||||||||||
| Agency | $ | 45,298 | $ | 48,036 | $ | 52,215 | $ | 52,500 | $ | 49,636 | |||||||||||||||||||
| Non-agency | 1,236 | 1,337 | 1,437 | 1,529 | 1,617 | ||||||||||||||||||||||||
| Commercial mortgage-backed | 6,241 | 6,568 | 6,927 | 7,232 | 6,734 | ||||||||||||||||||||||||
| Asset-backed | 5,304 | 5,017 | 5,033 | 5,309 | 5,003 | ||||||||||||||||||||||||
| U.S. Treasury and government agencies | 22,309 | 18,783 | 18,724 | 15,457 | 15,938 | ||||||||||||||||||||||||
| Other | 4,561 | 4,561 | 4,723 | 4,952 | 4,024 | ||||||||||||||||||||||||
| Total securities available for sale | 84,949 | 84,302 | 89,059 | 86,979 | 82,952 | ||||||||||||||||||||||||
| Securities held to maturity | |||||||||||||||||||||||||||||
| Asset-backed | 22 | 51 | |||||||||||||||||||||||||||
| U.S. Treasury and government agencies | 797 | 793 | 788 | 783 | 779 | ||||||||||||||||||||||||
| Other | 650 | 650 | 655 | 646 | 640 | ||||||||||||||||||||||||
| Total securities held to maturity | 1,447 | 1,443 | 1,443 | 1,451 | 1,470 | ||||||||||||||||||||||||
| Total investment securities | 86,396 | 85,745 | 90,502 | 88,430 | 84,422 | ||||||||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Commercial and industrial | 129,996 | 134,944 | 139,795 | 153,595 | 128,723 | ||||||||||||||||||||||||
| Commercial real estate | 28,598 | 28,991 | 29,081 | 28,707 | 28,275 | ||||||||||||||||||||||||
| Equipment lease financing | 6,332 | 6,380 | 6,771 | 7,035 | 7,066 | ||||||||||||||||||||||||
| Consumer | 50,904 | 52,872 | 54,692 | 56,485 | 57,680 | ||||||||||||||||||||||||
| Residential real estate | 22,305 | 22,638 | 22,753 | 22,292 | 21,828 | ||||||||||||||||||||||||
| Total loans | 238,135 | 245,825 | 253,092 | 268,114 | 243,572 | ||||||||||||||||||||||||
| Interest-earning deposits with banks (b) | 85,410 | 76,374 | 60,327 | 34,600 | 17,569 | ||||||||||||||||||||||||
| Other interest-earning assets | 7,829 | 8,134 | 9,752 | 10,867 | 9,468 | ||||||||||||||||||||||||
| Total interest-earning assets | 417,770 | 416,078 | 413,673 | 402,011 | 355,031 | ||||||||||||||||||||||||
| Noninterest-earning assets | 50,450 | 48,901 | 48,466 | 55,302 | 57,405 | ||||||||||||||||||||||||
| Total assets | $ | 468,220 | $ | 464,979 | $ | 462,139 | $ | 457,313 | $ | 412,436 | |||||||||||||||||||
| Liabilities and Equity | |||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||
| Interest-bearing deposits | |||||||||||||||||||||||||||||
| Money market | $ | 59,083 | $ | 62,621 | $ | 63,598 | $ | 61,346 | $ | 53,287 | |||||||||||||||||||
| Demand | 91,619 | 88,026 | 87,226 | 82,881 | 70,931 | ||||||||||||||||||||||||
| Savings | 82,926 | 79,430 | 77,479 | 75,345 | 69,977 | ||||||||||||||||||||||||
| Time deposits | 18,449 | 19,448 | 20,248 | 21,873 | 21,141 | ||||||||||||||||||||||||
| Total interest-bearing deposits | 252,077 | 249,525 | 248,551 | 241,445 | 215,336 | ||||||||||||||||||||||||
| Borrowed funds | |||||||||||||||||||||||||||||
| Federal Home Loan Bank borrowings | 2,411 | 4,761 | 7,196 | 12,559 | 13,440 | ||||||||||||||||||||||||
| Bank notes and senior debt | 22,799 | 24,022 | 25,858 | 28,298 | 29,988 | ||||||||||||||||||||||||
| Subordinated debt | 5,929 | 5,936 | 5,936 | 5,937 | 5,934 | ||||||||||||||||||||||||
| Other | 4,057 | 3,433 | 4,354 | 6,435 | 7,826 | ||||||||||||||||||||||||
| Total borrowed funds | 35,196 | 38,152 | 43,344 | 53,229 | 57,188 | ||||||||||||||||||||||||
| Total interest-bearing liabilities | 287,273 | 287,677 | 291,895 | 294,674 | 272,524 | ||||||||||||||||||||||||
| Noninterest-bearing liabilities and equity: | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 113,299 | 109,878 | 101,931 | 93,776 | 74,396 | ||||||||||||||||||||||||
| Accrued expenses and other liabilities | 14,258 | 14,348 | 15,341 | 16,989 | 16,437 | ||||||||||||||||||||||||
| Equity | 53,390 | 53,076 | 52,972 | 51,874 | 49,079 | ||||||||||||||||||||||||
| Total liabilities and equity | $ | 468,220 | $ | 464,979 | $ | 462,139 | $ | 457,313 | $ | 412,436 | |||||||||||||||||||
(a)Calculated using average daily balances.
(b)Amounts include average balances held with the Federal Reserve Bank of Cleveland of $85.2 billion, $76.1 billion, $60.0 billion, $34.2 billion and $17.3 billion for the three months ended March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020, respectively.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 4 | |||||||
| Table 4: Details of Net Interest Margin (Unaudited) | |||||||||||||||||||||||||||||
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||
| Average yields/rates (a) | |||||||||||||||||||||||||||||
| Yield on interest-earning assets | |||||||||||||||||||||||||||||
| Investment securities | |||||||||||||||||||||||||||||
| Securities available for sale | |||||||||||||||||||||||||||||
| Residential mortgage-backed | |||||||||||||||||||||||||||||
| Agency | 1.72 | % | 1.81 | % | 2.03 | % | 2.29 | % | 2.63 | % | |||||||||||||||||||
| Non-agency | 7.24 | % | 7.15 | % | 7.26 | % | 7.13 | % | 7.87 | % | |||||||||||||||||||
| Commercial mortgage-backed | 2.58 | % | 2.66 | % | 2.50 | % | 2.59 | % | 2.95 | % | |||||||||||||||||||
| Asset-backed | 1.84 | % | 2.04 | % | 2.44 | % | 2.60 | % | 3.05 | % | |||||||||||||||||||
| U.S. Treasury and government agencies | 1.68 | % | 1.77 | % | 1.64 | % | 1.77 | % | 2.29 | % | |||||||||||||||||||
| Other | 3.28 | % | 3.45 | % | 3.39 | % | 3.47 | % | 3.69 | % | |||||||||||||||||||
| Total securities available for sale | 1.95 | % | 2.05 | % | 2.16 | % | 2.39 | % | 2.77 | % | |||||||||||||||||||
| Securities held to maturity | |||||||||||||||||||||||||||||
| Asset-backed | 2.38 | % | 2.77 | % | |||||||||||||||||||||||||
| U.S. Treasury and government agencies | 2.83 | % | 2.88 | % | 2.86 | % | 2.84 | % | 2.84 | % | |||||||||||||||||||
| Other | 4.17 | % | 4.20 | % | 4.20 | % | 4.27 | % | 4.48 | % | |||||||||||||||||||
| Total securities held to maturity | 3.43 | % | 3.47 | % | 3.47 | % | 3.47 | % | 3.56 | % | |||||||||||||||||||
| Total investment securities | 1.97 | % | 2.08 | % | 2.18 | % | 2.41 | % | 2.78 | % | |||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Commercial and industrial | 2.91 | % | 2.87 | % | 2.82 | % | 2.83 | % | 3.62 | % | |||||||||||||||||||
| Commercial real estate | 2.80 | % | 2.63 | % | 2.65 | % | 2.84 | % | 3.64 | % | |||||||||||||||||||
| Equipment lease financing | 3.90 | % | 3.90 | % | 3.80 | % | 3.82 | % | 3.93 | % | |||||||||||||||||||
| Consumer | 4.78 | % | 4.74 | % | 4.69 | % | 4.86 | % | 5.38 | % | |||||||||||||||||||
| Residential real estate | 3.53 | % | 3.69 | % | 3.74 | % | 3.86 | % | 3.96 | % | |||||||||||||||||||
| Total loans | 3.38 | % | 3.35 | % | 3.32 | % | 3.37 | % | 4.08 | % | |||||||||||||||||||
| Interest-earning deposits with banks | 0.10 | % | 0.10 | % | 0.10 | % | 0.10 | % | 1.27 | % | |||||||||||||||||||
| Other interest-earning assets | 2.34 | % | 1.99 | % | 2.23 | % | 2.26 | % | 3.51 | % | |||||||||||||||||||
| Total yield on interest-earning assets | 2.40 | % | 2.46 | % | 2.57 | % | 2.85 | % | 3.62 | % | |||||||||||||||||||
| Rate on interest-bearing liabilities | |||||||||||||||||||||||||||||
| Interest-bearing deposits | |||||||||||||||||||||||||||||
| Money market | 0.03 | % | 0.05 | % | 0.07 | % | 0.15 | % | 0.72 | % | |||||||||||||||||||
| Demand | 0.04 | % | 0.04 | % | 0.05 | % | 0.08 | % | 0.41 | % | |||||||||||||||||||
| Savings | 0.06 | % | 0.08 | % | 0.11 | % | 0.31 | % | 0.79 | % | |||||||||||||||||||
| Time deposits | 0.32 | % | 0.41 | % | 0.58 | % | 0.80 | % | 1.34 | % | |||||||||||||||||||
| Total interest-bearing deposits | 0.06 | % | 0.08 | % | 0.12 | % | 0.23 | % | 0.70 | % | |||||||||||||||||||
| Borrowed funds | |||||||||||||||||||||||||||||
| Federal Home Loan Bank borrowings | 0.43 | % | 0.40 | % | 0.47 | % | 1.00 | % | 1.69 | % | |||||||||||||||||||
| Bank notes and senior debt | 1.04 | % | 1.00 | % | 1.08 | % | 1.56 | % | 2.41 | % | |||||||||||||||||||
| Subordinated debt | 1.43 | % | 1.38 | % | 1.51 | % | 1.91 | % | 2.73 | % | |||||||||||||||||||
Other | 1.21 | % | 1.39 | % | 1.31 | % | 0.92 | % | 1.69 | % | |||||||||||||||||||
| Total borrowed funds | 1.09 | % | 1.02 | % | 1.06 | % | 1.39 | % | 2.18 | % | |||||||||||||||||||
| Total rate on interest-bearing liabilities | 0.19 | % | 0.21 | % | 0.26 | % | 0.44 | % | 1.00 | % | |||||||||||||||||||
| Interest rate spread | 2.21 | % | 2.25 | % | 2.31 | % | 2.41 | % | 2.62 | % | |||||||||||||||||||
| Benefit from use of noninterest bearing sources (b) | 0.06 | 0.07 | 0.08 | 0.11 | 0.22 | ||||||||||||||||||||||||
| Net interest margin | 2.27 | % | 2.32 | % | 2.39 | % | 2.52 | % | 2.84 | % | |||||||||||||||||||
(a)Yields and rates are calculated using the applicable annualized interest income or interest expense divided by the applicable average earning assets or interest-bearing liabilities. Net interest margin is the total yield on interest-earning assets minus the total rate on interest-bearing liabilities and includes the benefit from use of noninterest-bearing sources. To provide more meaningful comparisons of net interest margins, we use net interest income on a taxable-equivalent basis in calculating average yields used in the calculation of net interest margin by increasing the interest income earned on tax-exempt assets to make it fully equivalent to interest income earned on taxable investments. This adjustment is not permitted under GAAP in the Consolidated Income Statement. The taxable-equivalent adjustments to net interest income for the three months ended March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020 were $15 million, $17 million, $17 million, $19 million and $22 million, respectively.
(b)Represents the positive effects of investing noninterest-bearing sources in interest-earning assets.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 5 | |||||||
| Table 5: Per Share Related Information (Unaudited) | |||||||||||||||||||||||||||||
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| In millions, except per share data | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Basic | |||||||||||||||||||||||||||||
| Net income (loss) from continuing operations | $ | 1,826 | $ | 1,456 | $ | 1,532 | $ | (744) | $ | 759 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Net income attributable to noncontrolling interests | 10 | 14 | 13 | 7 | 7 | ||||||||||||||||||||||||
| Preferred stock dividends | 57 | 48 | 63 | 55 | 63 | ||||||||||||||||||||||||
| Preferred stock discount accretion and redemptions | 1 | 1 | 1 | 1 | 1 | ||||||||||||||||||||||||
| Net income (loss) from continuing operations attributable to common shareholders | 1,758 | 1,393 | 1,455 | (807) | 688 | ||||||||||||||||||||||||
| Less: Dividends and undistributed earnings allocated to nonvested restricted shares | 8 | 6 | 8 | 1 | 3 | ||||||||||||||||||||||||
| Net income (loss) from continuing operations attributable to basic common shareholders | $ | 1,750 | $ | 1,387 | $ | 1,447 | $ | (808) | $ | 685 | |||||||||||||||||||
| Net income from discontinued operations attributable to common shareholders | $ | 4,399 | $ | 156 | |||||||||||||||||||||||||
| Less: Undistributed earnings allocated to nonvested restricted shares | 21 | 1 | |||||||||||||||||||||||||||
| Net income from discontinued operations attributable to basic common shareholders | $ | 4,378 | $ | 155 | |||||||||||||||||||||||||
| Basic weighted-average common shares outstanding | 426 | 425 | 426 | 426 | 429 | ||||||||||||||||||||||||
| Basic earnings (loss) per common share from continuing operations (a) | $ | 4.11 | $ | 3.26 | $ | 3.40 | $ | (1.90) | $ | 1.59 | |||||||||||||||||||
| Basic earnings per common share from discontinued operations (a) | $ | 10.28 | $ | 0.37 | |||||||||||||||||||||||||
| Basic earnings per common share | $ | 4.11 | $ | 3.26 | $ | 3.40 | $ | 8.40 | $ | 1.96 | |||||||||||||||||||
| Diluted | |||||||||||||||||||||||||||||
| Net income (loss) from continuing operations attributable to diluted common shareholder | $ | 1,750 | $ | 1,387 | $ | 1,447 | $ | (808) | $ | 685 | |||||||||||||||||||
| Net income from discontinued operations attributable to basic common shareholders | $ | 4,378 | $ | 155 | |||||||||||||||||||||||||
| Less: Impact of earnings per share dilution from discontinued operations | 1 | 1 | |||||||||||||||||||||||||||
| Net income from discontinued operations attributable to diluted common shareholders | $ | 4,377 | $ | 154 | |||||||||||||||||||||||||
| Basic weighted-average common shares outstanding | 426 | 425 | 426 | 426 | 429 | ||||||||||||||||||||||||
| Dilutive potential common shares | 1 | 1 | |||||||||||||||||||||||||||
| Diluted weighted-average common shares outstanding | 426 | 426 | 426 | 426 | 430 | ||||||||||||||||||||||||
| Diluted earnings (loss) per common share from continuing operations (a) | $ | 4.10 | $ | 3.26 | $ | 3.39 | $ | (1.90) | $ | 1.59 | |||||||||||||||||||
| Diluted earnings per common share from discontinued operations (a) | $ | 10.28 | $ | 0.36 | |||||||||||||||||||||||||
| Diluted earnings per common share | $ | 4.10 | $ | 3.26 | $ | 3.39 | $ | 8.40 | $ | 1.95 | |||||||||||||||||||
(a)Dividends are payable quarterly other than the Series O, Series R and Series S preferred stock, which are payable semiannually, with the Series O payable in different quarters than the Series R and Series S preferred stock.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 6 | |||||||
Table 6: Details of Loans (Unaudited)
| March 31 | December 31 | September 30 | June 30 | March 31 | ||||||||||||||||||||||||||||
| In millions | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||
| Commercial and industrial | ||||||||||||||||||||||||||||||||
| Retail/wholesale trade | $ | 20,349 | $ | 20,218 | $ | 20,287 | $ | 21,747 | $ | 24,408 | ||||||||||||||||||||||
| Manufacturing | 20,032 | 20,712 | 22,551 | 25,590 | 27,225 | |||||||||||||||||||||||||||
| Service providers | 19,403 | 19,419 | 20,260 | 21,347 | 19,411 | |||||||||||||||||||||||||||
| Financial services | 13,382 | 14,909 | 15,005 | 13,596 | 13,473 | |||||||||||||||||||||||||||
| Real estate related (a) | 13,052 | 13,369 | 14,040 | 14,634 | 14,843 | |||||||||||||||||||||||||||
| Health care | 8,741 | 8,987 | 9,368 | 10,109 | 9,238 | |||||||||||||||||||||||||||
| Transportation and warehousing | 6,751 | 7,095 | 7,295 | 7,771 | 8,160 | |||||||||||||||||||||||||||
| Other industries | 28,088 | 27,364 | 28,381 | 29,541 | 32,373 | |||||||||||||||||||||||||||
| Total commercial and industrial | 129,798 | 132,073 | 137,187 | 144,335 | 149,131 | |||||||||||||||||||||||||||
| Commercial real estate | 28,319 | 28,716 | 29,028 | 28,763 | 28,544 | |||||||||||||||||||||||||||
| Equipment lease financing | 6,389 | 6,414 | 6,479 | 7,097 | 7,061 | |||||||||||||||||||||||||||
| Total commercial | 164,506 | 167,203 | 172,694 | 180,195 | 184,736 | |||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||
| Home equity | 23,493 | 24,088 | 24,539 | 24,879 | 25,081 | |||||||||||||||||||||||||||
| Residential real estate | 22,418 | 22,560 | 22,886 | 22,469 | 22,250 | |||||||||||||||||||||||||||
| Automobile | 13,584 | 14,218 | 14,977 | 16,157 | 17,194 | |||||||||||||||||||||||||||
| Credit card | 5,675 | 6,215 | 6,303 | 6,575 | 7,132 | |||||||||||||||||||||||||||
| Education | 2,842 | 2,946 | 3,051 | 3,132 | 3,247 | |||||||||||||||||||||||||||
| Other consumer | 4,495 | 4,698 | 4,829 | 4,829 | 5,003 | |||||||||||||||||||||||||||
| Total consumer | 72,507 | 74,725 | 76,585 | 78,041 | 79,907 | |||||||||||||||||||||||||||
| Total loans | $ | 237,013 | $ | 241,928 | $ | 249,279 | $ | 258,236 | $ | 264,643 | ||||||||||||||||||||||
(a) Represents loans to customers in the real estate and construction industries.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 7 | |||||||
Allowance for Credit Losses (Unaudited)
Table 7: Change in Allowance for Loan and Lease Losses
| Three months ended | ||||||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | ||||||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||||
Allowance for loan and lease losses | ||||||||||||||||||||||||||||||||
| Beginning balance | $ | 5,361 | $ | 5,751 | $ | 5,928 | $ | 3,944 | $ | 2,742 | ||||||||||||||||||||||
| Adoption of ASU 2016-03 (a) | 463 | |||||||||||||||||||||||||||||||
| Gross charge-offs: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | (59) | (133) | (59) | (112) | (78) | |||||||||||||||||||||||||||
| Commercial real estate | (5) | (1) | (1) | |||||||||||||||||||||||||||||
| Equipment lease financing | (5) | (4) | (4) | (10) | (5) | |||||||||||||||||||||||||||
| Home equity | (7) | (11) | (12) | (8) | (11) | |||||||||||||||||||||||||||
| Residential real estate | (4) | (6) | (2) | (2) | ||||||||||||||||||||||||||||
| Automobile | (52) | (55) | (57) | (69) | (84) | |||||||||||||||||||||||||||
| Credit card | (69) | (72) | (74) | (76) | (78) | |||||||||||||||||||||||||||
| Education | (5) | (3) | (3) | (4) | (6) | |||||||||||||||||||||||||||
| Other consumer | (37) | (42) | (35) | (35) | (40) | |||||||||||||||||||||||||||
| Total gross charge-offs | (243) | (327) | (247) | (314) | (304) | |||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | 14 | 23 | 21 | 13 | 18 | |||||||||||||||||||||||||||
| Commercial real estate | 1 | 3 | 2 | 4 | ||||||||||||||||||||||||||||
| Equipment lease financing | 3 | 3 | 3 | 2 | 2 | |||||||||||||||||||||||||||
| Home equity | 17 | 17 | 15 | 15 | 14 | |||||||||||||||||||||||||||
| Residential real estate | 5 | 4 | 4 | 4 | 4 | |||||||||||||||||||||||||||
| Automobile | 38 | 33 | 31 | 29 | 35 | |||||||||||||||||||||||||||
| Credit card | 12 | 9 | 9 | 9 | 8 | |||||||||||||||||||||||||||
| Education | 2 | 2 | 2 | 2 | 2 | |||||||||||||||||||||||||||
| Other consumer | 5 | 4 | 5 | 4 | 5 | |||||||||||||||||||||||||||
| Total recoveries | 97 | 98 | 92 | 78 | 92 | |||||||||||||||||||||||||||
| Net (charge-offs) / recoveries: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | (45) | (110) | (38) | (99) | (60) | |||||||||||||||||||||||||||
| Commercial real estate | (4) | 2 | 1 | 4 | ||||||||||||||||||||||||||||
| Equipment lease financing | (2) | (1) | (1) | (8) | (3) | |||||||||||||||||||||||||||
| Home equity | 10 | 6 | 3 | 7 | 3 | |||||||||||||||||||||||||||
| Residential real estate | 1 | (2) | 2 | 4 | 2 | |||||||||||||||||||||||||||
| Automobile | (14) | (22) | (26) | (40) | (49) | |||||||||||||||||||||||||||
| Credit card | (57) | (63) | (65) | (67) | (70) | |||||||||||||||||||||||||||
| Education | (3) | (1) | (1) | (2) | (4) | |||||||||||||||||||||||||||
| Other consumer | (32) | (38) | (30) | (31) | (35) | |||||||||||||||||||||||||||
| Total net (charge-offs) | (146) | (229) | (155) | (236) | (212) | |||||||||||||||||||||||||||
| Provision for (recapture of) credit losses (b) | (502) | (164) | (23) | 2,220 | 952 | |||||||||||||||||||||||||||
| Other | 1 | 3 | 1 | (1) | ||||||||||||||||||||||||||||
| Ending balance | $ | 4,714 | $ | 5,361 | $ | 5,751 | $ | 5,928 | $ | 3,944 | ||||||||||||||||||||||
| Supplemental Information | ||||||||||||||||||||||||||||||||
| Net charge-offs | ||||||||||||||||||||||||||||||||
| Commercial net charge-offs | $ | (51) | $ | (109) | $ | (38) | $ | (107) | $ | (59) | ||||||||||||||||||||||
| Consumer net charge-offs | (95) | (120) | (117) | (129) | (153) | |||||||||||||||||||||||||||
| Total net charge-offs | $ | (146) | $ | (229) | $ | (155) | $ | (236) | $ | (212) | ||||||||||||||||||||||
| Net charge-offs to average loans (annualized) | 0.25 | % | 0.37 | % | 0.24 | % | 0.35 | % | 0.35 | % | ||||||||||||||||||||||
| Commercial | 0.13 | % | 0.25 | % | 0.09 | % | 0.23 | % | 0.14 | % | ||||||||||||||||||||||
| Consumer | 0.53 | % | 0.63 | % | 0.60 | % | 0.66 | % | 0.77 | % | ||||||||||||||||||||||
(a) Represents the impact of adopting ASU 2016-13, Financial Instruments - Credit Losses on January 1, 2020, and our transition from an incurred loss methodology for our reserves to an expected credit loss methodology. Our 2020 Form 10-K included additional information related to our adoption of the CECL standard.
(b) See Table 8 for the components of the Provision for (recapture of) credit losses being reported on the Consolidated Income Statement.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 8 | |||||||
Allowance for Credit Losses (Unaudited) (Continued)
Table 8: Components of the Provision for (Recapture of) Credit Losses
| Three months ended | ||||||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | ||||||||||||||||||||||||||||
| In millions | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||||
| Provision for (recapture of) credit losses | ||||||||||||||||||||||||||||||||
| Loans and leases | $ | (502) | $ | (164) | $ | (23) | $ | 2,220 | $ | 952 | ||||||||||||||||||||||
| Unfunded lending related commitments | (77) | (105) | 27 | 212 | (47) | |||||||||||||||||||||||||||
| Investment securities | 26 | 11 | 39 | 30 | ||||||||||||||||||||||||||||
| Other financial assets | 2 | 4 | 9 | 1 | 9 | |||||||||||||||||||||||||||
| Total provision for (recapture of) credit losses | $ | (551) | $ | (254) | $ | 52 | $ | 2,463 | $ | 914 | ||||||||||||||||||||||
Table 9: Allowance for Credit Losses by Loan Class (a)
| March 31, 2021 | December 31, 2020 | ||||||||||||||||||||||||||||
Dollars in millions | Allowance Amount | Total Loans | % of Total Loans | Allowance Amount | Total Loans | % of Total Loans | |||||||||||||||||||||||
| Allowance for loan and lease losses | |||||||||||||||||||||||||||||
| Commercial | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 1,815 | $ | 129,798 | 1.40 | % | $ | 2,300 | $ | 132,073 | 1.74 | % | |||||||||||||||||
| Commercial real estate | 1,126 | 28,319 | 3.98 | % | 880 | 28,716 | 3.06 | % | |||||||||||||||||||||
| Equipment lease financing | 142 | 6,389 | 2.22 | % | 157 | 6,414 | 2.45 | % | |||||||||||||||||||||
| Total commercial | 3,083 | 164,506 | 1.87 | % | 3,337 | 167,203 | 2.00 | % | |||||||||||||||||||||
| Consumer | |||||||||||||||||||||||||||||
| Home equity | 239 | 23,493 | 1.02 | % | 313 | 24,088 | 1.30 | % | |||||||||||||||||||||
| Residential real estate | (17) | 22,418 | (0.08) | % | 28 | 22,560 | 0.12 | % | |||||||||||||||||||||
| Automobile | 344 | 13,584 | 2.53 | % | 379 | 14,218 | 2.67 | % | |||||||||||||||||||||
| Credit card | 693 | 5,675 | 12.21 | % | 816 | 6,215 | 13.13 | % | |||||||||||||||||||||
| Education | 112 | 2,842 | 3.94 | % | 129 | 2,946 | 4.38 | % | |||||||||||||||||||||
| Other consumer | 260 | 4,495 | 5.78 | % | 359 | 4,698 | 7.64 | % | |||||||||||||||||||||
| Total consumer | 1,631 | 72,507 | 2.25 | % | 2,024 | 74,725 | 2.71 | % | |||||||||||||||||||||
Total | 4,714 | $ | 237,013 | 1.99 | % | 5,361 | $ | 241,928 | 2.22 | % | |||||||||||||||||||
Allowance for unfunded lending related commitments | 507 | 584 | |||||||||||||||||||||||||||
Allowance for credit losses | $ | 5,221 | $ | 5,945 | |||||||||||||||||||||||||
| Supplemental Information | |||||||||||||||||||||||||||||
Allowance for credit losses to total loans | 2.20 | % | 2.46 | % | |||||||||||||||||||||||||
| Commercial | 2.12 | % | 2.29 | % | |||||||||||||||||||||||||
| Consumer | 2.39 | % | 2.84 | % | |||||||||||||||||||||||||
(a) Excludes allowances for investment securities and other financial assets, which together totaled $136 million and $109 million at March 31, 2021 and December 31, 2020,
respectively.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 9 | |||||||
Details of Nonperforming Assets (Unaudited)
Table 10: Nonperforming Assets by Type
| March 31 | December 31 | September 30 | June 30 | March 31 | ||||||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||||
| Nonperforming loans, including TDRs | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||
| Commercial and industrial | ||||||||||||||||||||||||||||||||
| Retail/wholesale trade | $ | 66 | $ | 61 | $ | 90 | $ | 117 | $ | 121 | ||||||||||||||||||||||
| Manufacturing | 55 | 81 | 80 | 58 | 79 | |||||||||||||||||||||||||||
| Service providers | 79 | 90 | 69 | 57 | 63 | |||||||||||||||||||||||||||
| Real estate related (a) | 48 | 95 | 140 | 158 | 25 | |||||||||||||||||||||||||||
| Health care | 19 | 20 | 20 | 19 | 14 | |||||||||||||||||||||||||||
| Transportation and warehousing | 18 | 20 | 14 | 20 | 23 | |||||||||||||||||||||||||||
| Other industries | 227 | 299 | 264 | 264 | 169 | |||||||||||||||||||||||||||
| Total commercial and industrial | 512 | 666 | 677 | 693 | 494 | |||||||||||||||||||||||||||
| Commercial real estate | 221 | 224 | 217 | 43 | 42 | |||||||||||||||||||||||||||
| Equipment lease financing | 16 | 33 | 21 | 22 | 30 | |||||||||||||||||||||||||||
| Total commercial | 749 | 923 | 915 | 758 | 566 | |||||||||||||||||||||||||||
| Consumer (b) | ||||||||||||||||||||||||||||||||
| Home equity | 656 | 645 | 639 | 636 | 617 | |||||||||||||||||||||||||||
| Residential real estate | 541 | 528 | 339 | 305 | 292 | |||||||||||||||||||||||||||
| Automobile | 178 | 175 | 171 | 156 | 154 | |||||||||||||||||||||||||||
| Credit card | 7 | 8 | 13 | 15 | 10 | |||||||||||||||||||||||||||
| Other consumer | 7 | 7 | 8 | 6 | 5 | |||||||||||||||||||||||||||
| Total consumer | 1,389 | 1,363 | 1,170 | 1,118 | 1,078 | |||||||||||||||||||||||||||
| Total nonperforming loans (c) | 2,138 | 2,286 | 2,085 | 1,876 | 1,644 | |||||||||||||||||||||||||||
| OREO and foreclosed assets | 41 | 51 | 67 | 79 | 111 | |||||||||||||||||||||||||||
| Total nonperforming assets | $ | 2,179 | $ | 2,337 | $ | 2,152 | $ | 1,955 | $ | 1,755 | ||||||||||||||||||||||
| Nonperforming loans to total loans | 0.90 | % | 0.94 | % | 0.84 | % | 0.73 | % | 0.62 | % | ||||||||||||||||||||||
| Nonperforming assets to total loans, OREO and foreclosed assets | 0.92 | % | 0.97 | % | 0.86 | % | 0.76 | % | 0.66 | % | ||||||||||||||||||||||
| Nonperforming assets to total assets | 0.46 | % | 0.50 | % | 0.47 | % | 0.43 | % | 0.39 | % | ||||||||||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 220 | % | 235 | % | 276 | % | 316 | % | 240 | % | ||||||||||||||||||||||
(a)Represents loans related to customers in the real estate and construction industries.
(b)Excludes most unsecured consumer loans and lines of credit, which are charged off after 120 to 180 days past due and are not placed on nonperforming status.
(c)Nonperforming loans exclude certain government insured or guaranteed loans, loans held for sale and loans accounted for under the fair value option.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 10 | |||||||
Details of Nonperforming Assets (Unaudited) (Continued)
Table 11: Change in Nonperforming Assets
| January 1, 2021 - | October 1, 2020 - | July 1, 2020 - | April 1, 2020 - | January 1, 2020 - | ||||||||||||||||||||||||||||
| In millions | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | |||||||||||||||||||||||||||
| Beginning balance | $ | 2,337 | $ | 2,152 | $ | 1,955 | $ | 1,755 | $ | 1,752 | ||||||||||||||||||||||
| New nonperforming assets | 249 | 586 | 512 | 458 | 391 | |||||||||||||||||||||||||||
| Charge-offs and valuation adjustments | (70) | (97) | (75) | (104) | (145) | |||||||||||||||||||||||||||
| Principal activity, including paydowns and payoffs | (186) | (185) | (175) | (85) | (158) | |||||||||||||||||||||||||||
| Asset sales and transfers to loans held for sale | (86) | (14) | (20) | (28) | (20) | |||||||||||||||||||||||||||
| Returned to performing status | (65) | (105) | (45) | (41) | (65) | |||||||||||||||||||||||||||
| Ending balance | $ | 2,179 | $ | 2,337 | $ | 2,152 | $ | 1,955 | $ | 1,755 | ||||||||||||||||||||||
Table 12: Largest Individual Nonperforming Assets (a)
| March 31, 2021 - Dollars in millions | |||||||||||||||||
| Ranking | Outstandings | Industry | |||||||||||||||
| 1 | $ | 141 | Real Estate and Rental and Leasing | ||||||||||||||
| 2 | 38 | Wholesale Trade | |||||||||||||||
| 3 | 31 | Real Estate and Rental and Leasing | |||||||||||||||
| 4 | 29 | Real Estate and Rental and Leasing | |||||||||||||||
| 5 | 28 | Real Estate and Rental and Leasing | |||||||||||||||
| 6 | 24 | Mining, Quarrying, and Oil and Gas Extraction | |||||||||||||||
| 7 | 24 | Mining, Quarrying, and Oil and Gas Extraction | |||||||||||||||
| 8 | 22 | Mining, Quarrying, and Oil and Gas Extraction | |||||||||||||||
| 9 | 22 | Information | |||||||||||||||
| 10 | 20 | Mining, Quarrying, and Oil and Gas Extraction | |||||||||||||||
| Total | $ | 379 | |||||||||||||||
| As a percent of total nonperforming assets | 17% | ||||||||||||||||
(a) Amounts shown are not net of related allowance for loan and lease losses, if applicable.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 11 | |||||||
Accruing Loans Past Due (Unaudited)
Pursuant to the interagency guidance issued in April 2020 and in connection with the credit reporting rules from the U.S. Coronavirus Aid, Relief and Economic Security Act (CARES Act), the delinquency status of loans modified due to COVID-19 related hardships are reported as of March 31, 2021, December 31, 2020, September 30, 2020 and June 30, 2020 in alignment with the rules set forth for banks to report delinquency status to the credit agencies. These rules require that COVID-19 related loan modifications be reported as follows:
•if current at the time of modification, the loan remains current throughout the modification period,
•if delinquent at the time of modification and the borrower was not made current as part of the modification, the loan maintains its reported as delinquent status during the modification period, or
•if delinquent at the time of modification and the borrower was made current as part of the modification or became current during the modification period, the loan is reported as current.
As a result, certain loans modified due to COVID-19 related hardships are not being reported as past due as of March 31, 2021, December 31, 2020, September 30, 2020 and June 30, 2020 based on the contractual terms of the loan, even where borrowers may not be making payments on their loans during the modification period. Our 2020 Form 10-K included, and our first quarter 2021 Form 10-Q will include, additional information on COVID-19 related loan modifications.
Table 13: Accruing Loans Past Due 30 to 59 Days (a)
| Amount | Percent of Total Outstandings | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 80 | $ | 106 | $ | 56 | $ | 49 | $ | 97 | 0.06 | % | 0.08 | % | 0.04 | % | 0.03 | % | 0.07 | % | ||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 12 | 6 | 6 | 51 | 6 | 0.04 | % | 0.02 | % | 0.02 | % | 0.18 | % | 0.02 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing | 21 | 31 | 7 | 8 | 42 | 0.33 | % | 0.48 | % | 0.11 | % | 0.11 | % | 0.59 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 43 | 50 | 48 | 70 | 65 | 0.18 | % | 0.21 | % | 0.20 | % | 0.28 | % | 0.26 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential real estate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non government insured | 61 | 89 | 99 | 135 | 121 | 0.27 | % | 0.39 | % | 0.43 | % | 0.60 | % | 0.54 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Government insured | 101 | 92 | 89 | 63 | 52 | 0.45 | % | 0.41 | % | 0.39 | % | 0.28 | % | 0.23 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 76 | 134 | 116 | 105 | 177 | 0.56 | % | 0.94 | % | 0.77 | % | 0.65 | % | 1.03 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 31 | 43 | 44 | 53 | 59 | 0.55 | % | 0.69 | % | 0.70 | % | 0.81 | % | 0.83 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Non government insured | 6 | 5 | 6 | 3 | 7 | 0.21 | % | 0.17 | % | 0.20 | % | 0.10 | % | 0.22 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Government insured | 43 | 50 | 51 | 36 | 45 | 1.51 | % | 1.70 | % | 1.67 | % | 1.15 | % | 1.39 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 11 | 14 | 17 | 17 | 17 | 0.24 | % | 0.30 | % | 0.35 | % | 0.35 | % | 0.34 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 485 | $ | 620 | $ | 539 | $ | 590 | $ | 688 | 0.20 | % | 0.26 | % | 0.22 | % | 0.23 | % | 0.26 | % | ||||||||||||||||||||||||||||||||||||||||||
Table 14: Accruing Loans Past Due 60 to 89 Days (a)
| Amount | Percent of Total Outstandings | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 13 | $ | 26 | $ | 37 | $ | 28 | $ | 22 | 0.01 | % | 0.02 | % | 0.03 | % | 0.02 | % | 0.01 | % | ||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 1 | 1 | 6 | 4 | 1 | 0.00 | % | 0.00 | % | 0.02 | % | 0.01 | % | 0.00 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Equipment lease financing | 1 | 5 | 4 | 9 | 2 | 0.02 | % | 0.08 | % | 0.06 | % | 0.13 | % | 0.03 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 20 | 21 | 22 | 27 | 28 | 0.09 | % | 0.09 | % | 0.09 | % | 0.11 | % | 0.11 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential real estate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non government insured | 13 | 16 | 22 | 34 | 30 | 0.06 | % | 0.07 | % | 0.10 | % | 0.15 | % | 0.13 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Government insured | 60 | 62 | 58 | 59 | 52 | 0.27 | % | 0.27 | % | 0.25 | % | 0.26 | % | 0.23 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 19 | 34 | 32 | 34 | 49 | 0.14 | % | 0.24 | % | 0.21 | % | 0.21 | % | 0.28 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 24 | 30 | 33 | 38 | 37 | 0.42 | % | 0.48 | % | 0.52 | % | 0.58 | % | 0.52 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Non government insured | 3 | 2 | 2 | 2 | 4 | 0.11 | % | 0.07 | % | 0.07 | % | 0.06 | % | 0.12 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Government insured | 22 | 27 | 24 | 21 | 26 | 0.77 | % | 0.92 | % | 0.79 | % | 0.67 | % | 0.80 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 6 | 10 | 11 | 8 | 10 | 0.13 | % | 0.21 | % | 0.23 | % | 0.17 | % | 0.20 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 182 | $ | 234 | $ | 251 | $ | 264 | $ | 261 | 0.08 | % | 0.10 | % | 0.10 | % | 0.10 | % | 0.10 | % | ||||||||||||||||||||||||||||||||||||||||||
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 12 | |||||||
Accruing Loans Past Due (Unaudited) (Continued)
Table 15: Accruing Loans Past Due 90 Days or More (a)
| Amount | Percent of Total Outstandings | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | Mar. 31 | Dec. 31 | Sept. 30 | Jun. 30 | Mar. 31 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 63 | $ | 30 | $ | 36 | $ | 34 | $ | 51 | 0.05 | % | 0.02 | % | 0.03 | % | 0.02 | % | 0.03 | % | ||||||||||||||||||||||||||||||||||||||||||
| Residential real estate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non government insured | 17 | 27 | 28 | 19 | 18 | 0.08 | % | 0.12 | % | 0.12 | % | 0.08 | % | 0.08 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Government insured | 258 | 292 | 241 | 245 | 282 | 1.15 | % | 1.29 | % | 1.05 | % | 1.09 | % | 1.27 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 6 | 12 | 12 | 19 | 19 | 0.04 | % | 0.08 | % | 0.08 | % | 0.12 | % | 0.11 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 52 | 60 | 60 | 61 | 70 | 0.92 | % | 0.97 | % | 0.95 | % | 0.93 | % | 0.98 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Non government insured | 2 | 2 | 1 | 1 | 2 | 0.07 | % | 0.07 | % | 0.03 | % | 0.03 | % | 0.06 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Government insured | 74 | 75 | 62 | 65 | 82 | 2.60 | % | 2.55 | % | 2.03 | % | 2.08 | % | 2.53 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 7 | 11 | 8 | 12 | 10 | 0.16 | % | 0.23 | % | 0.17 | % | 0.25 | % | 0.20 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $ | 479 | $ | 509 | $ | 448 | $ | 456 | $ | 534 | 0.20 | % | 0.21 | % | 0.18 | % | 0.18 | % | 0.20 | % | ||||||||||||||||||||||||||||||||||||||||||
(a) Excludes loans held for sale.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 13 | |||||||
Business Segment Descriptions (Unaudited)
Retail Banking provides deposit, lending, brokerage, insurance services, investment management and cash management products and services to consumer and small business customers. Our customers are serviced through our branch network, ATMs, call centers, online banking and mobile channels. The branch network is located primarily in markets across the Mid-Atlantic, Midwest and Southeast. In 2018, Retail Banking launched its national expansion strategy designed to grow customers with digitally-led banking and a thin branch network in markets outside of our existing retail branch network. Deposit products include checking, savings and money market accounts and certificates of deposit. Lending products include residential mortgages, home equity loans and lines of credit, auto loans, credit cards, education loans and personal and small business loans and lines of credit. The residential mortgage loans are directly originated within our branch network and nationwide, and are typically underwritten to agency and/or third-party standards, and either sold, servicing retained, or held on our balance sheet. Brokerage, investment management and cash management products and services include managed, education, retirement and trust accounts.
Corporate & Institutional Banking provides lending, treasury management, and capital markets-related products and services to mid-sized and large corporations, and government and not-for-profit entities. Lending products include secured and unsecured loans, letters of credit and equipment leases. The Treasury Management business provides payables, receivables, deposit and account services, liquidity and investments, and online and mobile banking products and services to our clients. Capital markets-related products and services include foreign exchange, derivatives, securities underwriting, loan syndications, mergers and acquisitions advisory and equity capital markets advisory related services. We also provide commercial loan servicing and technology solutions for the commercial real estate finance industry. Products and services are provided nationally.
Asset Management Group provides personal wealth management for high net worth and ultra high net worth clients and institutional asset management. The Asset Management group is comprised of three distinct operating units:
•Wealth management provides products and services to individuals and their families including investment and retirement planning, customized investment management, private banking, and trust management and administration for individuals and their families.
•Our Hawthorn unit provides multi-generational family planning including estate, financial, tax planning, fiduciary, investment management and consulting, private banking, personal administrative services, asset custody and customized performance reporting to ultra high net worth clients.
•Institutional asset management provides outsourced chief investment officer, custody, private real estate, cash and fixed income client solutions, and fiduciary retirement advisory services to institutional clients including corporations, healthcare systems, insurance companies, unions, municipalities and non-profits.
Table 16: Period End Employees
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||||||||
| Full-time employees | |||||||||||||||||||||||||||||
| Retail Banking | 27,690 | 27,621 | 27,808 | 29,051 | 28,737 | ||||||||||||||||||||||||
| Other full-time employees | 22,281 | 21,928 | 21,997 | 21,752 | 21,776 | ||||||||||||||||||||||||
| Total full-time employees | 49,971 | 49,549 | 49,805 | 50,803 | 50,513 | ||||||||||||||||||||||||
| Part-time employees | |||||||||||||||||||||||||||||
| Retail Banking | 1,697 | 1,611 | 1,593 | 1,854 | 1,780 | ||||||||||||||||||||||||
| Other part-time employees | 101 | 97 | 104 | 476 | 129 | ||||||||||||||||||||||||
| Total part-time employees | 1,798 | 1,708 | 1,697 | 2,330 | 1,909 | ||||||||||||||||||||||||
| Total | 51,769 | 51,257 | 51,502 | 53,133 | 52,422 | ||||||||||||||||||||||||
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 14 | |||||||
Table 17: Summary of Business Segment Net Income and Revenue (Unaudited) (a)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| In millions | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Income | |||||||||||||||||||||||||||||
| Retail Banking | $ | 607 | $ | 336 | $ | 530 | $ | (223) | $ | 201 | |||||||||||||||||||
| Corporate & Institutional Banking | 1,058 | 992 | 670 | (358) | 370 | ||||||||||||||||||||||||
| Asset Management Group | 99 | 82 | 91 | 28 | 54 | ||||||||||||||||||||||||
| Other | 52 | 32 | 228 | (198) | 127 | ||||||||||||||||||||||||
| Net income (loss) from continuing operations excluding noncontrolling interest | $ | 1,816 | $ | 1,442 | $ | 1,519 | $ | (751) | $ | 752 | |||||||||||||||||||
| Revenue | |||||||||||||||||||||||||||||
| Retail Banking | $ | 2,016 | $ | 1,853 | $ | 2,056 | $ | 1,975 | $ | 2,244 | |||||||||||||||||||
| Corporate & Institutional Banking | 1,808 | 1,913 | 1,748 | 1,790 | 1,660 | ||||||||||||||||||||||||
| Asset Management Group | 322 | 316 | 310 | 293 | 292 | ||||||||||||||||||||||||
| Other | 74 | 126 | 167 | 18 | 140 | ||||||||||||||||||||||||
| Total revenue | $ | 4,220 | $ | 4,208 | $ | 4,281 | $ | 4,076 | $ | 4,336 | |||||||||||||||||||
(a)Our business information is presented based on our internal management reporting practices. Net interest income in business segment results reflects PNC’s internal funds transfer pricing methodology. Assets receive a funding charge and liabilities and capital receive a funding credit based on a transfer pricing methodology that incorporates product repricing characteristics, tenor and other factors.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 15 | |||||||
Table 18: Retail Banking (Unaudited) (a)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Income Statement | |||||||||||||||||||||||||||||
| Net interest income | $ | 1,362 | $ | 1,380 | $ | 1,383 | $ | 1,390 | $ | 1,456 | |||||||||||||||||||
| Noninterest income | 654 | 473 | 673 | 585 | 788 | ||||||||||||||||||||||||
| Total revenue | 2,016 | 1,853 | 2,056 | 1,975 | 2,244 | ||||||||||||||||||||||||
| Provision for (recapture of) credit losses | (257) | (81) | (157) | 761 | 445 | ||||||||||||||||||||||||
| Noninterest expense | 1,476 | 1,482 | 1,512 | 1,497 | 1,528 | ||||||||||||||||||||||||
| Pretax earnings (loss) | 797 | 452 | 701 | (283) | 271 | ||||||||||||||||||||||||
| Income taxes (benefit) | 183 | 105 | 162 | (63) | 62 | ||||||||||||||||||||||||
| Noncontrolling interest | 7 | 11 | 9 | 3 | 8 | ||||||||||||||||||||||||
| Earnings (loss) | $ | 607 | $ | 336 | $ | 530 | $ | (223) | $ | 201 | |||||||||||||||||||
| Average Balance Sheet | |||||||||||||||||||||||||||||
| Loans held for sale | $ | 891 | $ | 672 | $ | 700 | $ | 829 | $ | 779 | |||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Consumer | |||||||||||||||||||||||||||||
| Home equity | $ | 21,833 | $ | 22,366 | $ | 22,647 | $ | 22,790 | $ | 22,736 | |||||||||||||||||||
| Residential real estate | 17,468 | 18,042 | 18,435 | 18,244 | 17,964 | ||||||||||||||||||||||||
| Automobile | 13,890 | 14,536 | 15,573 | 16,688 | 17,096 | ||||||||||||||||||||||||
| Credit card | 5,819 | 6,218 | 6,408 | 6,690 | 7,207 | ||||||||||||||||||||||||
| Education | 2,938 | 3,027 | 3,119 | 3,218 | 3,343 | ||||||||||||||||||||||||
| Other consumer | 1,898 | 2,086 | 2,262 | 2,454 | 2,533 | ||||||||||||||||||||||||
| Total consumer | 63,846 | 66,275 | 68,444 | 70,084 | 70,879 | ||||||||||||||||||||||||
| Commercial | 13,743 | 13,391 | 13,356 | 13,612 | 10,524 | ||||||||||||||||||||||||
| Total loans | $ | 77,589 | $ | 79,666 | $ | 81,800 | $ | 83,696 | $ | 81,403 | |||||||||||||||||||
| Total assets | $ | 92,891 | $ | 94,303 | $ | 98,731 | $ | 102,103 | $ | 97,062 | |||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 44,845 | $ | 43,818 | $ | 43,752 | $ | 39,134 | $ | 32,225 | |||||||||||||||||||
| Interest-bearing demand | 54,269 | 50,702 | 49,274 | 47,339 | 42,865 | ||||||||||||||||||||||||
| Money market | 24,198 | 24,112 | 23,816 | 22,942 | 22,866 | ||||||||||||||||||||||||
| Savings | 75,180 | 72,041 | 70,236 | 67,947 | 62,781 | ||||||||||||||||||||||||
| Certificates of deposit | 9,742 | 10,156 | 10,852 | 11,661 | 12,233 | ||||||||||||||||||||||||
| Total deposits | $ | 208,234 | $ | 200,829 | $ | 197,930 | $ | 189,023 | $ | 172,970 | |||||||||||||||||||
| Performance Ratios | |||||||||||||||||||||||||||||
| Return on average assets | 2.65 | % | 1.41 | % | 2.13 | % | (0.88) | % | 0.84 | % | |||||||||||||||||||
| Noninterest income to total revenue | 32 | % | 26 | % | 33 | % | 30 | % | 35 | % | |||||||||||||||||||
| Efficiency | 73 | % | 80 | % | 74 | % | 76 | % | 68 | % | |||||||||||||||||||
(a)See note (a) on page 14.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 16 | |||||||
Retail Banking (Unaudited) (Continued)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| Dollars in millions, except as noted | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Supplemental Noninterest Income Information | |||||||||||||||||||||||||||||
| Consumer services | $ | 368 | $ | 369 | $ | 371 | $ | 315 | $ | 372 | |||||||||||||||||||
| Residential mortgage | $ | 105 | $ | 99 | $ | 137 | $ | 158 | $ | 210 | |||||||||||||||||||
| Service charges on deposits | $ | 119 | $ | 133 | $ | 118 | $ | 80 | $ | 166 | |||||||||||||||||||
| Residential Mortgage Information | |||||||||||||||||||||||||||||
| Residential mortgage servicing statistics (in billions, except as noted) (a) | |||||||||||||||||||||||||||||
| Serviced portfolio balance (b) | $ | 117 | $ | 121 | $ | 119 | $ | 122 | $ | 118 | |||||||||||||||||||
| Serviced portfolio acquisitions | $ | 7 | $ | 12 | $ | 8 | $ | 11 | $ | 2 | |||||||||||||||||||
| MSR asset value (b) | $ | 1.0 | $ | 0.7 | $ | 0.6 | $ | 0.6 | $ | 0.6 | |||||||||||||||||||
| MSR capitalization value (in basis points) (b) | 83 | 56 | 50 | 47 | 51 | ||||||||||||||||||||||||
| Servicing income: (in millions) | |||||||||||||||||||||||||||||
| Servicing fees, net (c) | $ | 5 | $ | 13 | $ | 25 | $ | 36 | $ | 44 | |||||||||||||||||||
| Mortgage servicing rights valuation, net of economic hedge | $ | 14 | $ | (1) | $ | 17 | $ | 20 | $ | 101 | |||||||||||||||||||
| Residential mortgage loan statistics | |||||||||||||||||||||||||||||
| Loan origination volume (in billions) | $ | 4.3 | $ | 3.7 | $ | 4.0 | $ | 4.2 | $ | 3.2 | |||||||||||||||||||
| Loan sale margin percentage | 3.28 | % | 3.75 | % | 3.62 | % | 3.67 | % | 3.16 | % | |||||||||||||||||||
| Percentage of originations represented by: | |||||||||||||||||||||||||||||
| Purchase volume (d) | 34 | % | 45 | % | 44 | % | 34 | % | 36 | % | |||||||||||||||||||
| Refinance volume | 66 | % | 55 | % | 56 | % | 66 | % | 64 | % | |||||||||||||||||||
| Other Information (b) | |||||||||||||||||||||||||||||
| Customer-related statistics (average) | |||||||||||||||||||||||||||||
| Non-teller deposit transactions (e) | 66 | % | 66 | % | 67 | % | 65 | % | 59 | % | |||||||||||||||||||
| Digital consumer customers (f) | 79 | % | 77 | % | 75 | % | 73 | % | 71 | % | |||||||||||||||||||
| Credit-related statistics | |||||||||||||||||||||||||||||
| Nonperforming assets | $ | 1,229 | $ | 1,211 | $ | 1,077 | $ | 1,037 | $ | 1,011 | |||||||||||||||||||
| Net charge-offs - loans and leases | $ | 108 | $ | 136 | $ | 125 | $ | 142 | $ | 166 | |||||||||||||||||||
| Other statistics | |||||||||||||||||||||||||||||
| ATMs | 8,874 | 8,900 | 9,058 | 9,058 | 9,048 | ||||||||||||||||||||||||
| Branches (g) | 2,137 | 2,162 | 2,207 | 2,256 | 2,277 | ||||||||||||||||||||||||
| Brokerage account client assets (in billions) (h) | $ | 61 | $ | 59 | $ | 55 | $ | 53 | $ | 49 | |||||||||||||||||||
(a)Represents mortgage loan servicing balances for third parties and the related income.
(b)Presented as of period end, except for average customer-related statistics and net charge-offs, which are both shown for the three months ended.
(c)Servicing fees net of impact of decrease in MSR value due to passage of time, including the impact from both regularly scheduled loan payments, prepayments, and loans that were paid down or paid off during the period.
(d)Mortgages with borrowers as part of residential real estate purchase transactions.
(e)Percentage of total consumer and business banking deposit transactions processed at an ATM or through our mobile banking application.
(f)Represents consumer checking relationships that process the majority of their transactions through non-teller channels.
(g)Excludes stand-alone mortgage offices and satellite offices (e.g., drive-ups, electronic branches and retirement centers) that provide limited products and/or services.
(h)Includes cash and money market balances.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 17 | |||||||
Table 19: Corporate & Institutional Banking (Unaudited) (a)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| Dollars in millions | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Income Statement | |||||||||||||||||||||||||||||
| Net interest income | $ | 1,001 | $ | 994 | $ | 1,025 | $ | 1,064 | $ | 966 | |||||||||||||||||||
| Noninterest income | 807 | 919 | 723 | 726 | 694 | ||||||||||||||||||||||||
| Total revenue | 1,808 | 1,913 | 1,748 | 1,790 | 1,660 | ||||||||||||||||||||||||
| Provision for (recapture of) credit losses | (282) | (166) | 211 | 1,585 | 458 | ||||||||||||||||||||||||
| Noninterest expense | 711 | 801 | 663 | 670 | 722 | ||||||||||||||||||||||||
| Pretax earnings (loss) | 1,379 | 1,278 | 874 | (465) | 480 | ||||||||||||||||||||||||
| Income taxes (benefit) | 318 | 282 | 201 | (110) | 110 | ||||||||||||||||||||||||
| Noncontrolling interest | 3 | 4 | 3 | 3 | |||||||||||||||||||||||||
| Earnings (loss) | $ | 1,058 | $ | 992 | $ | 670 | $ | (358) | $ | 370 | |||||||||||||||||||
| Average Balance Sheet | |||||||||||||||||||||||||||||
| Loans held for sale | $ | 691 | $ | 1,039 | $ | 904 | $ | 704 | $ | 395 | |||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Commercial | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 114,944 | $ | 120,297 | $ | 125,187 | $ | 138,992 | $ | 117,288 | |||||||||||||||||||
| Commercial real estate | 27,182 | 27,509 | 27,511 | 27,106 | 26,589 | ||||||||||||||||||||||||
| Equipment lease financing | 6,332 | 6,381 | 6,772 | 7,036 | 7,066 | ||||||||||||||||||||||||
| Total commercial | 148,458 | 154,187 | 159,470 | 173,134 | 150,943 | ||||||||||||||||||||||||
| Consumer | 9 | 10 | 11 | 8 | 9 | ||||||||||||||||||||||||
| Total loans | $ | 148,467 | $ | 154,197 | $ | 159,481 | $ | 173,142 | $ | 150,952 | |||||||||||||||||||
| Total assets | $ | 170,531 | $ | 177,792 | $ | 183,266 | $ | 199,254 | $ | 172,502 | |||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 66,666 | $ | 64,334 | $ | 56,433 | $ | 53,157 | $ | 40,651 | |||||||||||||||||||
| Interest-bearing demand | 28,118 | 28,793 | 29,730 | 27,674 | 21,101 | ||||||||||||||||||||||||
| Money market | 33,182 | 36,705 | 38,015 | 36,595 | 28,468 | ||||||||||||||||||||||||
| Other | 8,368 | 8,928 | 8,956 | 9,546 | 7,868 | ||||||||||||||||||||||||
| Total deposits | $ | 136,334 | $ | 138,760 | $ | 133,134 | $ | 126,972 | $ | 98,088 | |||||||||||||||||||
| Performance Ratios | |||||||||||||||||||||||||||||
| Return on average assets | 2.52 | % | 2.21 | % | 1.45 | % | (0.72) | % | 0.87 | % | |||||||||||||||||||
| Noninterest income to total revenue | 45 | % | 48 | % | 41 | % | 41 | % | 42 | % | |||||||||||||||||||
| Efficiency | 39 | % | 42 | % | 38 | % | 37 | % | 43 | % | |||||||||||||||||||
| Other Information | |||||||||||||||||||||||||||||
Consolidated revenue from: | |||||||||||||||||||||||||||||
| Treasury Management (b) | $ | 494 | $ | 472 | $ | 452 | $ | 469 | $ | 491 | |||||||||||||||||||
| Capital Markets (b) | $ | 403 | $ | 530 | $ | 345 | $ | 388 | $ | 344 | |||||||||||||||||||
| Commercial mortgage banking activities | |||||||||||||||||||||||||||||
| Commercial mortgage loans held for sale (c) | $ | 30 | $ | 45 | $ | 46 | $ | 42 | $ | 29 | |||||||||||||||||||
| Commercial mortgage loan servicing income (d) | 90 | 82 | 76 | 67 | 69 | ||||||||||||||||||||||||
| Commercial mortgage servicing rights valuation, net of economic hedge (e) | 17 | 14 | 16 | 22 | 20 | ||||||||||||||||||||||||
| Total | $ | 137 | $ | 141 | $ | 138 | $ | 131 | $ | 118 | |||||||||||||||||||
| MSR asset value (f) | $ | 702 | $ | 569 | $ | 515 | $ | 490 | $ | 477 | |||||||||||||||||||
| Average loans by C&IB business | |||||||||||||||||||||||||||||
| Corporate Banking | $ | 74,459 | $ | 76,664 | $ | 81,617 | $ | 91,634 | $ | 78,057 | |||||||||||||||||||
| Real Estate | 38,395 | 41,427 | 40,592 | 42,124 | 37,368 | ||||||||||||||||||||||||
| Business Credit | 21,552 | 21,337 | 21,845 | 23,943 | 23,251 | ||||||||||||||||||||||||
| Commercial Banking | 10,807 | 11,375 | 11,770 | 10,708 | 7,784 | ||||||||||||||||||||||||
| Other | 3,254 | 3,394 | 3,657 | 4,733 | 4,492 | ||||||||||||||||||||||||
| Total average loans | $ | 148,467 | $ | 154,197 | $ | 159,481 | $ | 173,142 | $ | 150,952 | |||||||||||||||||||
Credit-related statistics | |||||||||||||||||||||||||||||
| Nonperforming assets (f) | $ | 658 | $ | 827 | $ | 832 | $ | 674 | $ | 508 | |||||||||||||||||||
| Net charge-offs - loans and leases | $ | 44 | $ | 99 | $ | 32 | $ | 99 | $ | 50 | |||||||||||||||||||
(a)See note (a) on page 14.
(b)Amounts reported in net interest income and noninterest income.
(c)Represents other noninterest income for valuations on commercial mortgage loans held for sale and related commitments, derivative valuations, originations fees, gains on sale of loans held for sale and net interest income on loans held for sale.
(d)Represents net interest income and noninterest income (primarily in corporate service fees) from loan servicing net of reduction in commercial mortgage servicing rights due to amortization expense and payoffs. Commercial mortgage servicing rights valuation, net of economic hedge is shown separately.
(e)Amounts are reported in corporate service fees.
(f)Presented as of period end.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 18 | |||||||
Table 20: Asset Management Group (Unaudited) (a)
| Three months ended | |||||||||||||||||||||||||||||
| March 31 | December 31 | September 30 | June 30 | March 31 | |||||||||||||||||||||||||
| Dollars in millions, except as noted | 2021 | 2020 | 2020 | 2020 | 2020 | ||||||||||||||||||||||||
| Income Statement | |||||||||||||||||||||||||||||
| Net interest income | $ | 93 | $ | 91 | $ | 89 | $ | 89 | $ | 88 | |||||||||||||||||||
| Noninterest income | 229 | 225 | 221 | 204 | 204 | ||||||||||||||||||||||||
| Total revenue | 322 | 316 | 310 | 293 | 292 | ||||||||||||||||||||||||
| Provision for (recapture of) credit losses | (9) | (2) | (19) | 39 | 3 | ||||||||||||||||||||||||
| Noninterest expense | 202 | 211 | 211 | 217 | 219 | ||||||||||||||||||||||||
| Pretax earnings | 129 | 107 | 118 | 37 | 70 | ||||||||||||||||||||||||
| Income taxes | 30 | 25 | 27 | 9 | 16 | ||||||||||||||||||||||||
| Earnings | $ | 99 | $ | 82 | $ | 91 | $ | 28 | $ | 54 | |||||||||||||||||||
| Average Balance Sheet | |||||||||||||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Consumer | |||||||||||||||||||||||||||||
| Residential real estate | $ | 3,635 | $ | 3,326 | $ | 2,976 | $ | 2,636 | $ | 2,385 | |||||||||||||||||||
| Other consumer | 4,008 | 4,077 | 4,065 | 3,975 | 4,052 | ||||||||||||||||||||||||
| Total consumer | 7,643 | 7,403 | 7,041 | 6,611 | 6,437 | ||||||||||||||||||||||||
| Commercial | 756 | 774 | 810 | 883 | 856 | ||||||||||||||||||||||||
| Total loans | $ | 8,399 | $ | 8,177 | $ | 7,851 | $ | 7,494 | $ | 7,293 | |||||||||||||||||||
| Total assets | $ | 8,873 | $ | 8,615 | $ | 8,361 | $ | 7,958 | $ | 7,801 | |||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,754 | $ | 1,689 | $ | 1,692 | $ | 1,421 | $ | 1,468 | |||||||||||||||||||
| Interest-bearing demand | 9,104 | 8,404 | 8,101 | 7,742 | 6,850 | ||||||||||||||||||||||||
| Money market | 1,520 | 1,606 | 1,542 | 1,597 | 1,709 | ||||||||||||||||||||||||
| Savings | 7,747 | 7,388 | 7,243 | 7,398 | 7,197 | ||||||||||||||||||||||||
| Other | 454 | 482 | 554 | 722 | 847 | ||||||||||||||||||||||||
| Total deposits | $ | 20,579 | $ | 19,569 | $ | 19,132 | $ | 18,880 | $ | 18,071 | |||||||||||||||||||
| Performance Ratios | |||||||||||||||||||||||||||||
| Return on average assets | 4.52 | % | 3.78 | % | 4.32 | % | 1.41 | % | 2.81 | % | |||||||||||||||||||
| Noninterest income to total revenue | 71 | % | 71 | % | 71 | % | 70 | % | 70 | % | |||||||||||||||||||
| Efficiency | 63 | % | 67 | % | 68 | % | 74 | % | 75 | % | |||||||||||||||||||
| Other Information | |||||||||||||||||||||||||||||
| Nonperforming assets (b) | $ | 68 | $ | 66 | $ | 39 | $ | 38 | $ | 34 | |||||||||||||||||||
| Net charge-offs (recoveries) - loans and leases | $ | 1 | $ | 1 | $ | (1) | |||||||||||||||||||||||
| Client Assets Under Administration (in billions) (b) (c) | |||||||||||||||||||||||||||||
| Discretionary client assets under management | $ | 173 | $ | 170 | $ | 158 | $ | 151 | $ | 136 | |||||||||||||||||||
| Nondiscretionary client assets under administration | 161 | 154 | 142 | 138 | 128 | ||||||||||||||||||||||||
| Total | $ | 334 | $ | 324 | $ | 300 | $ | 289 | $ | 264 | |||||||||||||||||||
| Discretionary client assets under management | |||||||||||||||||||||||||||||
| Personal | $ | 110 | $ | 108 | $ | 99 | $ | 94 | $ | 84 | |||||||||||||||||||
| Institutional | 63 | 62 | 59 | 57 | 52 | ||||||||||||||||||||||||
| Total | $ | 173 | $ | 170 | $ | 158 | $ | 151 | $ | 136 | |||||||||||||||||||
(a)See note (a) on page 14.
(b)As of period end.
(c)Excludes brokerage account client assets.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 19 | |||||||
Glossary of Terms
2019 Tailoring Rules – Rules adopted by the federal banking agencies to better tailor the application of their capital, liquidity, and enhanced prudential requirements for banking organizations to the asset size and risk profile (as measured by certain regulatory metrics) of the banking organization. Effective January 1, 2020, the agencies' capital and liquidity rules classify all BHCs with $100 billion or more in total assets into one of four categories (Category I, Category II, Category III, and Category IV).
Adjusted average total assets - Primarily consisted of total average quarterly (or annual) assets plus/less unrealized losses (gains) on investment securities, less goodwill and certain other intangible assets (net of eligible deferred taxes).
Allowance for credit losses (ACL) – A valuation account that is deducted from or added to the amortized cost basis of the related
financial assets to present the net carrying value at the amount expected to be collected on the financial asset.
Amortized cost basis - Amount at which a financial asset is originated or acquired, adjusted for applicable accretion or amortization of premiums, discounts and net deferred fees or costs, collection of cash, charge-offs, foreign exchange and fair value hedge accounting adjustments.
Basel III common equity Tier 1 (CET1) capital (Tailoring Rules) - Common stock plus related surplus, net of treasury stock, plus retained earnings, less goodwill, net of associated deferred tax liabilities, less other disallowed intangibles, net of deferred tax liabilities and plus/less other adjustments. Investments in unconsolidated financial institutions, as well as mortgage servicing rights and deferred tax assets, must then be deducted to the extent such items (net of associated deferred tax liabilities) individually exceed 25% of our adjusted Basel III common equity Tier 1 capital.
Basel III common equity Tier 1 capital ratio - Common equity Tier 1 capital divided by period-end risk-weighted assets (as applicable).
Basel III Tier 1 capital - Common equity Tier 1 capital, plus qualifying preferred stock, plus certain trust preferred capital securities, plus certain noncontrolling interests that are held by others and plus/less other adjustments.
Basel III Tier 1 capital ratio - Tier 1 capital divided by period-end risk-weighted assets (as applicable).
Basel III Total capital - Tier 1 capital plus qualifying subordinated debt, plus certain trust preferred securities, plus, under the Basel III transitional rules and the standardized approach, the allowance for loan and lease losses included in Tier 2 capital and other.
Basel III Total capital ratio - Basel III Total capital divided by period-end risk-weighted assets (as applicable).
BBVA – BBVA USA Bancshares, Inc.
BBVA, S.A. – Banco Bilbao Vizcaya Argentaria, S.A.
BBVA USA – BBVA USA, the Alabama-chartered bank subsidiary of BBVA USA Bancshares, Inc.
BlackRock – BlackRock, Inc.
Charge-off - Process of removing a loan or portion of a loan from our balance sheet because it is considered uncollectible. We also record a charge-off when a loan is transferred from portfolio holdings to held for sale by reducing the loan carrying amount to the fair value of the loan, if fair value is less than carrying amount.
Common shareholders’ equity - Total shareholders' equity less the liquidation value of preferred stock.
Credit valuation adjustment - Represents an adjustment to the fair value of our derivatives for our own and counterparties’ non-performance risk.
Criticized commercial loans - Loans with potential or identified weaknesses based upon internal risk ratings that comply with the regulatory classification definitions of “Special Mention,” “Substandard” or “Doubtful.”
Current Expected Credit Loss (CECL) - Methodology for estimating the allowance for credit losses on in-scope financial assets held at amortized cost and unfunded lending related commitments which uses a combination of expected losses over a reasonable and supportable forecast period, a reversion period and long run average credit losses for their estimated contractual term.
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 20 | |||||||
Discretionary client assets under management - Assets over which we have sole or shared investment authority for our customers/clients. We do not include these assets on our Consolidated Balance Sheet.
Earning assets - Assets that generate income, which include: interest-earning deposits with banks; loans held for sale; loans; investment securities; and certain other assets.
Effective duration - A measurement, expressed in years, that, when multiplied by a change in interest rates, would approximate the percentage change in value of on- and off- balance sheet positions.
Efficiency - Noninterest expense divided by total revenue.
Fair value - The price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
Fee income - Refers to the following categories within Noninterest income: Asset management; Consumer services; Corporate services; Residential mortgage; and Service charges on deposits.
FICO score - A credit bureau-based industry standard score created by Fair Isaac Co. which predicts the likelihood of borrower default. We use FICO scores both in underwriting and assessing credit risk in our consumer lending portfolio. Lower FICO scores indicate likely higher risk of default, while higher FICO scores indicate likely lower risk of default. FICO scores are updated on a periodic basis.
GAAP - Accounting principles generally accepted in the United States of America.
Leverage ratio - Basel III Tier 1 capital divided by average quarterly adjusted total assets.
Nondiscretionary client assets under administration - Assets we hold for our customers/clients in a nondiscretionary, custodial capacity. We do not include these assets on our Consolidated Balance Sheet.
Nonperforming assets - Nonperforming assets include nonperforming loans, OREO and foreclosed assets. We do not accrue interest income on assets classified as nonperforming.
Nonperforming loans - Loans accounted for at amortized cost whose credit quality has deteriorated to the extent that full collection of contractual principal and interest is not probable, including TDRs which have not returned to performing status. Interest income is not recognized on nonperforming loans. Nonperforming loans exclude certain government insured or guaranteed loans for which we expect to collect substantially all principal and interest, loans held for sale and loans accounted for under the fair value option.
Operating leverage - The period to period dollar or percentage change in total revenue less the dollar or percentage change in noninterest expense. A positive variance indicates that revenue growth exceeded expense growth (i.e., positive operating leverage) while a negative variance implies expense growth exceeded revenue growth (i.e., negative operating leverage).
Other real estate owned (OREO) and foreclosed assets - Assets taken in settlement of troubled loans primarily through deed-in-lieu of foreclosure or foreclosure. Foreclosed assets include real and personal property. Certain assets that have a government-guarantee which are classified as other receivables are excluded.
Purchased credit deteriorated assets (PCD) - Acquired loans or debt securities that, at acquisition, are determined to have experienced a more-than-insignificant deterioration in credit quality since origination or issuance.
Risk-weighted assets - Computed by the assignment of specific risk-weights (as defined by the Board of Governors of the Federal Reserve System) to assets and off-balance sheet instruments.
Servicing rights - Intangible assets or liabilities created by an obligation to service assets for others. Typical servicing rights include the right to receive a fee for collecting and forwarding payments on loans and related taxes and insurance premiums held in escrow.
Supplementary leverage ratio - Basel III Tier 1 capital divided by Supplementary leverage exposure.
Taxable-equivalent interest income - The interest income earned on certain assets that is completely or partially exempt from federal income tax. These tax-exempt instruments typically yield lower returns than taxable investments. To provide more meaningful comparisons of yields and margins for all interest-earning assets, we use interest income on a taxable-equivalent basis in calculating average yields and net interest margins by increasing the interest income earned on tax-exempt assets to make it fully equivalent to
THE PNC FINANCIAL SERVICES GROUP, INC. | Page 21 | |||||||
interest income earned on other taxable investments. This adjustment is not permitted under GAAP on the Consolidated Income Statement.
Troubled debt restructuring (TDR) - A loan whose terms have been restructured in a manner that grants a concession to a borrower experiencing financial difficulties.
Unfunded lending related commitments - Standby letters of credit, financial guarantees, commitments to extend credit and similar unfunded obligations that are not unilaterally, unconditionally, cancelable at PNC’s option.
Yield curve - A graph showing the relationship between the yields on financial instruments or market indices of the same credit quality with different maturities. For example, a “normal” or “positive” yield curve exists when long-term bonds have higher yields than short-term bonds. A “flat” yield curve exists when yields are the same for short-term and long-term bonds. A “steep” yield curve exists when yields on long-term bonds are significantly higher than on short-term bonds. An “inverted” or “negative” yield curve exists when short-term bonds have higher yields than long-term bonds.
The PNC Financial Services Group First Quarter 2021 Earnings Conference Call April 16, 2021 Exhibit 99.2
Cautionary Statement Regarding Forward-Looking and Non-GAAP Financial Information Our earnings conference call presentation is not intended as a full business or financial review and should be viewed in the context of all of the information made available by PNC in its SEC filings and on our corporate website. The presentation contains forward-looking statements regarding our outlook for earnings, revenues, expenses, tax rates, capital and liquidity levels and ratios, asset levels, asset quality, financial position, and other matters regarding or affecting PNC and its future business and operations. Forward-looking statements are necessarily subject to numerous assumptions, risks and uncertainties, which change over time. The forward-looking statements in this presentation are qualified by the factors affecting forward-looking statements identified in the more detailed Cautionary Statement included in the Appendix. We provide greater detail regarding these as well as other factors in our 2020 Form 10-K and our other subsequent SEC filings. Our forward-looking statements may also be subject to risks and uncertainties including those we may discuss in this presentation or in our SEC filings. Future events or circumstances may change our outlook and may also affect the nature of the assumptions, risks and uncertainties to which our forward-looking statements are subject. Forward-looking statements in this presentation speak only as of the date of this presentation. We do not assume any duty and do not undertake to update those statements. Actual results or future events could differ, possibly materially, from those anticipated in forward-looking statements, as well as from historical performance. As a result, we caution against placing undue reliance on any forward-looking statements. We include non-GAAP financial information in this presentation. Non-GAAP financial information includes financial metrics such as fee income, tangible book value, pretax, pre-provision earnings, net interest margin and return on tangible common equity. Reconciliations for such financial information may be found in our presentation, in these slides, including the Appendix, in other materials on our corporate website, and in our SEC filings. This information supplements our results as reported in accordance with GAAP and should not be viewed in isolation from, or as a substitute for, our GAAP results. We believe that this information and the related reconciliations may be useful to investors, analysts, regulators and others to help understand and evaluate our financial results, and with respect to adjusted metrics, because we believe they better reflect the ongoing financial results and trends of our businesses and increase comparability of period-to-period results. We may also use annualized, pro forma, estimated or third party numbers for illustrative or comparative purposes only. These may not reflect actual results. References to our corporate website are to www.pnc.com under “About Us - Investor Relations.” Our SEC filings are available both on our corporate website and on the SEC’s website at www.sec.gov. We include web addresses here as inactive textual references only. Information on these websites is not part of this presentation. 1
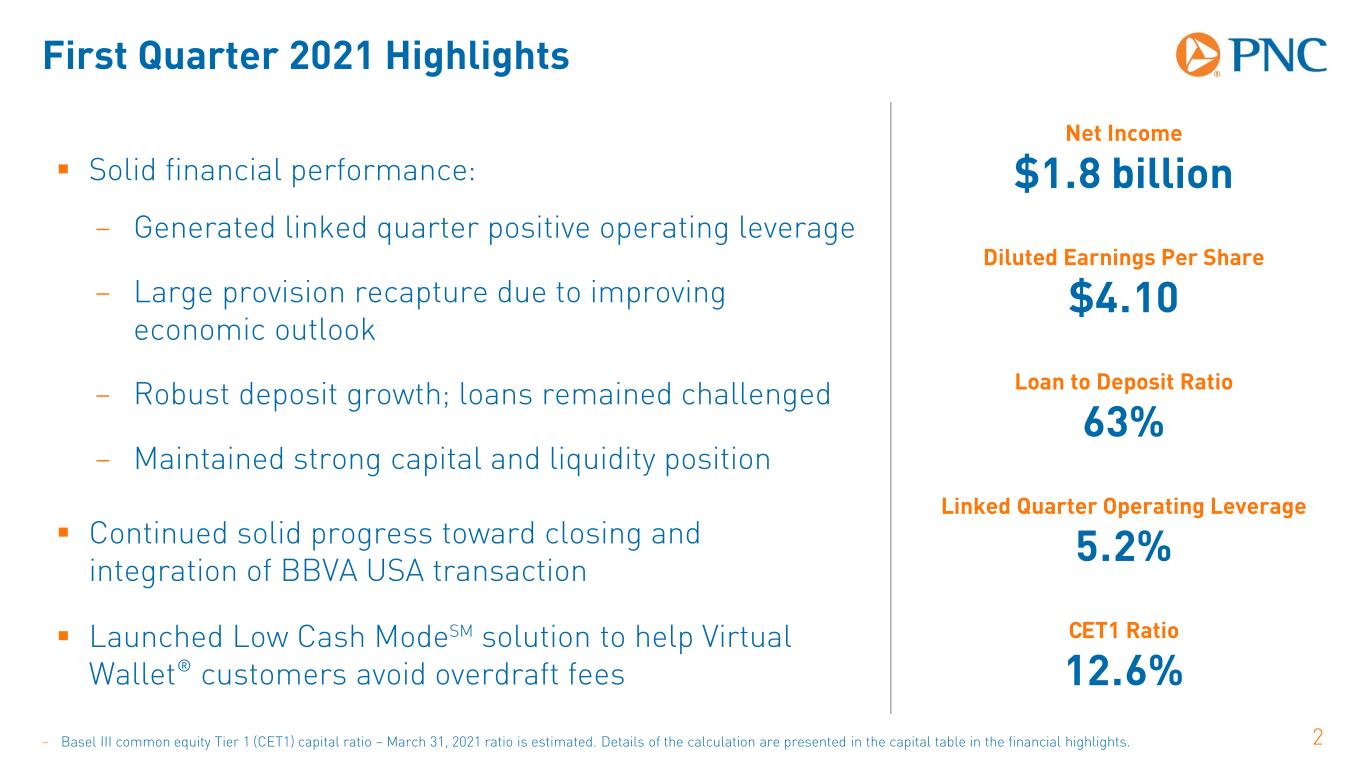
First Quarter 2021 Highlights 2 Solid financial performance: – Generated linked quarter positive operating leverage – Large provision recapture due to improving economic outlook – Robust deposit growth; loans remained challenged – Maintained strong capital and liquidity position Continued solid progress toward closing and integration of BBVA USA transaction Launched Low Cash ModeSM solution to help Virtual Wallet® customers avoid overdraft fees Net Income $1.8 billion Diluted Earnings Per Share $4.10 Loan to Deposit Ratio 63% Linked Quarter Operating Leverage 5.2% CET1 Ratio 12.6% – Basel III common equity Tier 1 (CET1) capital ratio – March 31, 2021 ratio is estimated. Details of the calculation are presented in the capital table in the financial highlights.
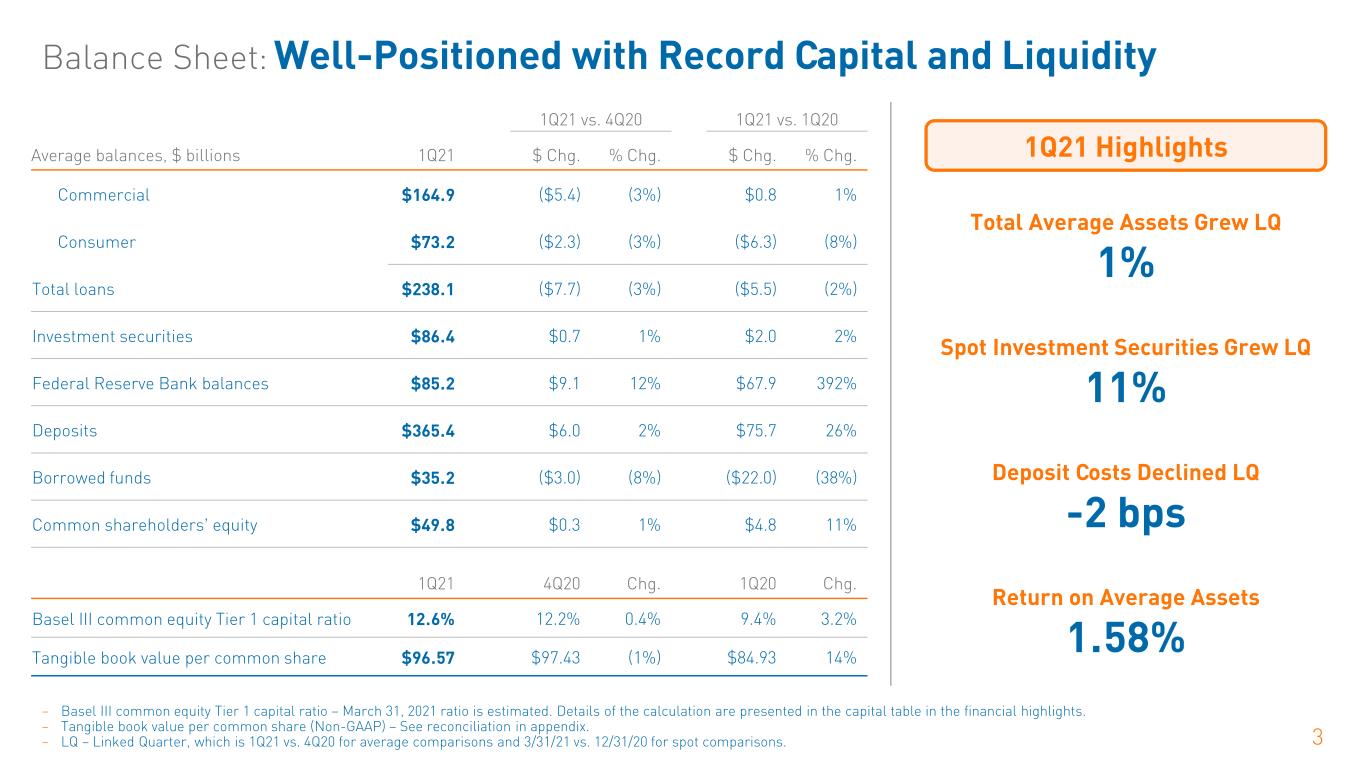
Balance Sheet: Well-Positioned with Record Capital and Liquidity 3 Total Average Assets Grew LQ 1% Spot Investment Securities Grew LQ 11% Deposit Costs Declined LQ -2 bps Return on Average Assets 1.58% 1Q21 vs. 4Q20 1Q21 vs. 1Q20 Average balances, $ billions 1Q21 $ Chg. % Chg. $ Chg. % Chg. Commercial $164.9 ($5.4) (3%) $0.8 1% Consumer $73.2 ($2.3) (3%) ($6.3) (8%) Total loans $238.1 ($7.7) (3%) ($5.5) (2%) Investment securities $86.4 $0.7 1% $2.0 2% Federal Reserve Bank balances $85.2 $9.1 12% $67.9 392% Deposits $365.4 $6.0 2% $75.7 26% Borrowed funds $35.2 ($3.0) (8%) ($22.0) (38%) Common shareholders’ equity $49.8 $0.3 1% $4.8 11% 1Q21 4Q20 Chg. 1Q20 Chg. Basel III common equity Tier 1 capital ratio 12.6% 12.2% 0.4% 9.4% 3.2% Tangible book value per common share $96.57 $97.43 (1%) $84.93 14% – Basel III common equity Tier 1 capital ratio – March 31, 2021 ratio is estimated. Details of the calculation are presented in the capital table in the financial highlights. – Tangible book value per common share (Non-GAAP) – See reconciliation in appendix. – LQ – Linked Quarter, which is 1Q21 vs. 4Q20 for average comparisons and 3/31/21 vs. 12/31/20 for spot comparisons. 1Q21 Highlights
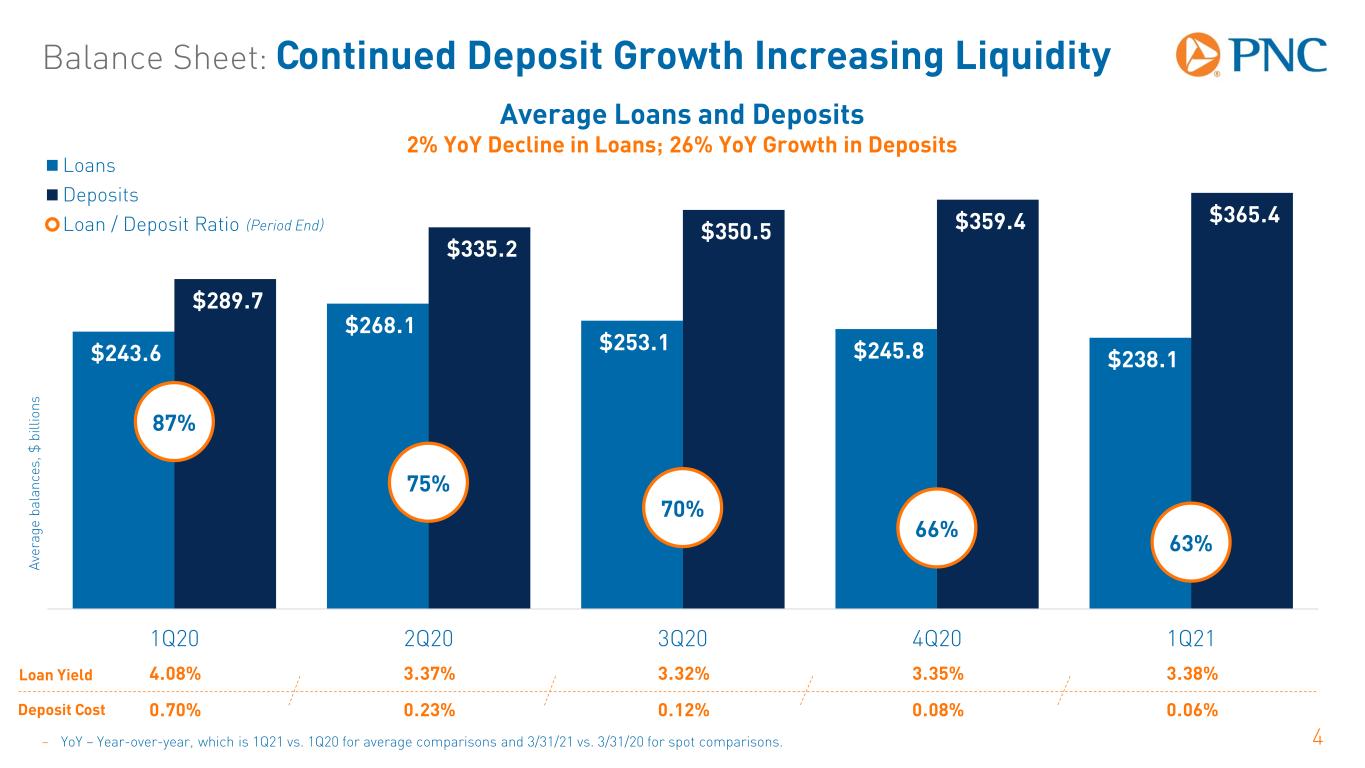
Balance Sheet: Continued Deposit Growth Increasing Liquidity 4 Loan Yield Deposit Cost 4.08% 3.37% 3.32% 3.35% 3.38% 0.70% 0.23% 0.12% 0.08% 0.06% A ve ra ge b al an ce s, $ b ill io n s $243.6 $268.1 $253.1 $245.8 $238.1 $289.7 $335.2 $350.5 $359.4 $365.4 87% 75% 70% 66% 63% 50% 60% 70% 80% 90% 100% 110% 120% 130% 140% $- $50.0 $100.0 $150.0 $200.0 $250.0 $300.0 $350.0 $400.0 1Q20 2Q20 3Q20 4Q20 1Q21 Loans Deposits Loan / Deposit Ratio (Period End) Average Loans and Deposits 2% YoY Decline in Loans; 26% YoY Growth in Deposits – YoY – Year-over-year, which is 1Q21 vs. 1Q20 for average comparisons and 3/31/21 vs. 3/31/20 for spot comparisons.
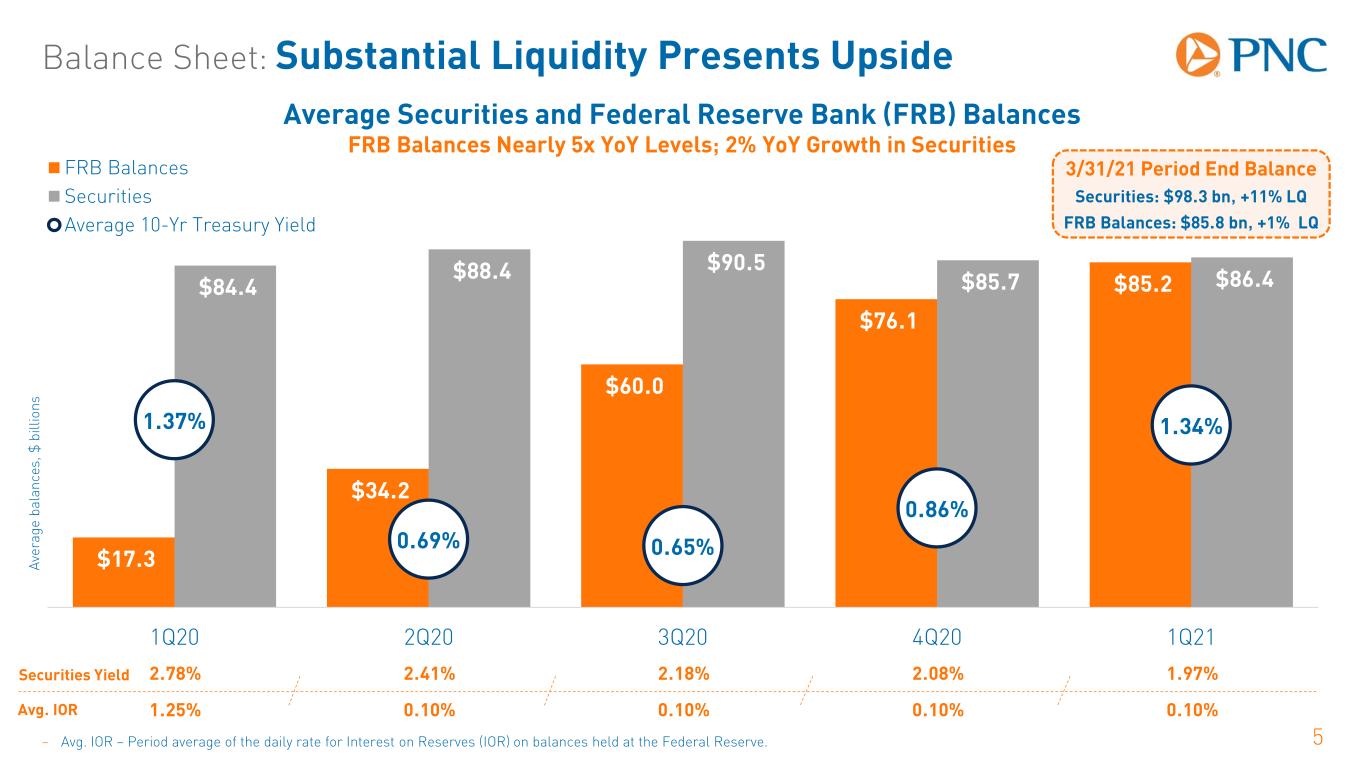
Balance Sheet: Substantial Liquidity Presents Upside 5 Securities Yield Avg. IOR 2.78% 2.41% 2.18% 2.08% 1.97% 1.25% 0.10% 0.10% 0.10% 0.10% A ve ra ge b al an ce s, $ b ill io n s – Avg. IOR – Period average of the daily rate for Interest on Reserves (IOR) on balances held at the Federal Reserve. $17.3 $34.2 $60.0 $76.1 $85.2 $84.4 $88.4 $90.5 $85.7 $86.4 1.37% 0.69% 0.65% 0.86% 1.34% 0.30% 0.80% 1.30% 1.80% 2.30% $- $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 $70.0 $80.0 $90.0 $100.0 1Q20 2Q20 3Q20 4Q20 1Q21 FRB Balances Securities Average 10-Yr Treasury Yield Average Securities and Federal Reserve Bank (FRB) Balances FRB Balances Nearly 5x YoY Levels; 2% YoY Growth in Securities 3/31/21 Period End Balance Securities: $98.3 bn, +11% LQ FRB Balances: $85.8 bn, +1% LQ
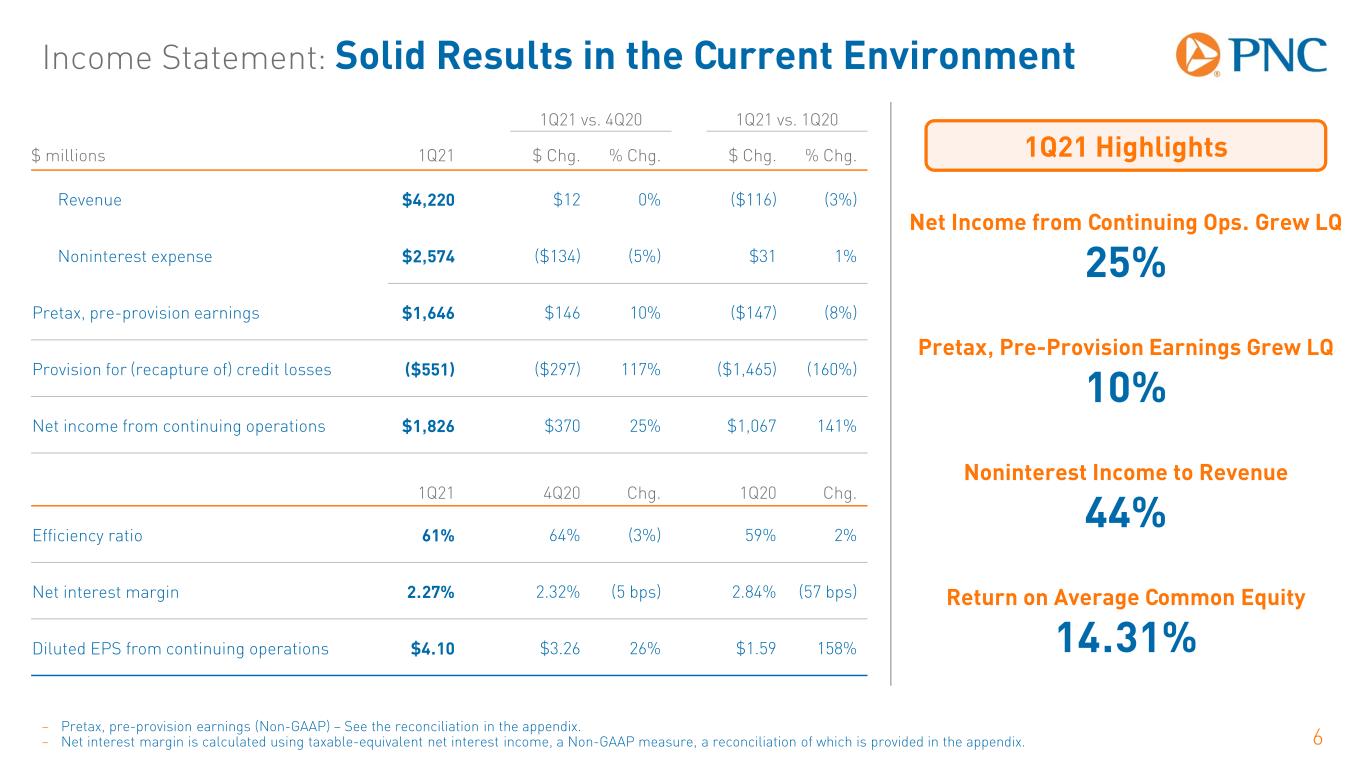
Income Statement: Solid Results in the Current Environment 6 – Pretax, pre-provision earnings (Non-GAAP) – See the reconciliation in the appendix. – Net interest margin is calculated using taxable-equivalent net interest income, a Non-GAAP measure, a reconciliation of which is provided in the appendix. 1Q21 vs. 4Q20 1Q21 vs. 1Q20 $ millions 1Q21 $ Chg. % Chg. $ Chg. % Chg. Revenue $4,220 $12 0% ($116) (3%) Noninterest expense $2,574 ($134) (5%) $31 1% Pretax, pre-provision earnings $1,646 $146 10% ($147) (8%) Provision for (recapture of) credit losses ($551) ($297) 117% ($1,465) (160%) Net income from continuing operations $1,826 $370 25% $1,067 141% 1Q21 4Q20 Chg. 1Q20 Chg. Efficiency ratio 61% 64% (3%) 59% 2% Net interest margin 2.27% 2.32% (5 bps) 2.84% (57 bps) Diluted EPS from continuing operations $4.10 $3.26 26% $1.59 158% Net Income from Continuing Ops. Grew LQ 25% Pretax, Pre-Provision Earnings Grew LQ 10% Noninterest Income to Revenue 44% Return on Average Common Equity 14.31% 1Q21 Highlights
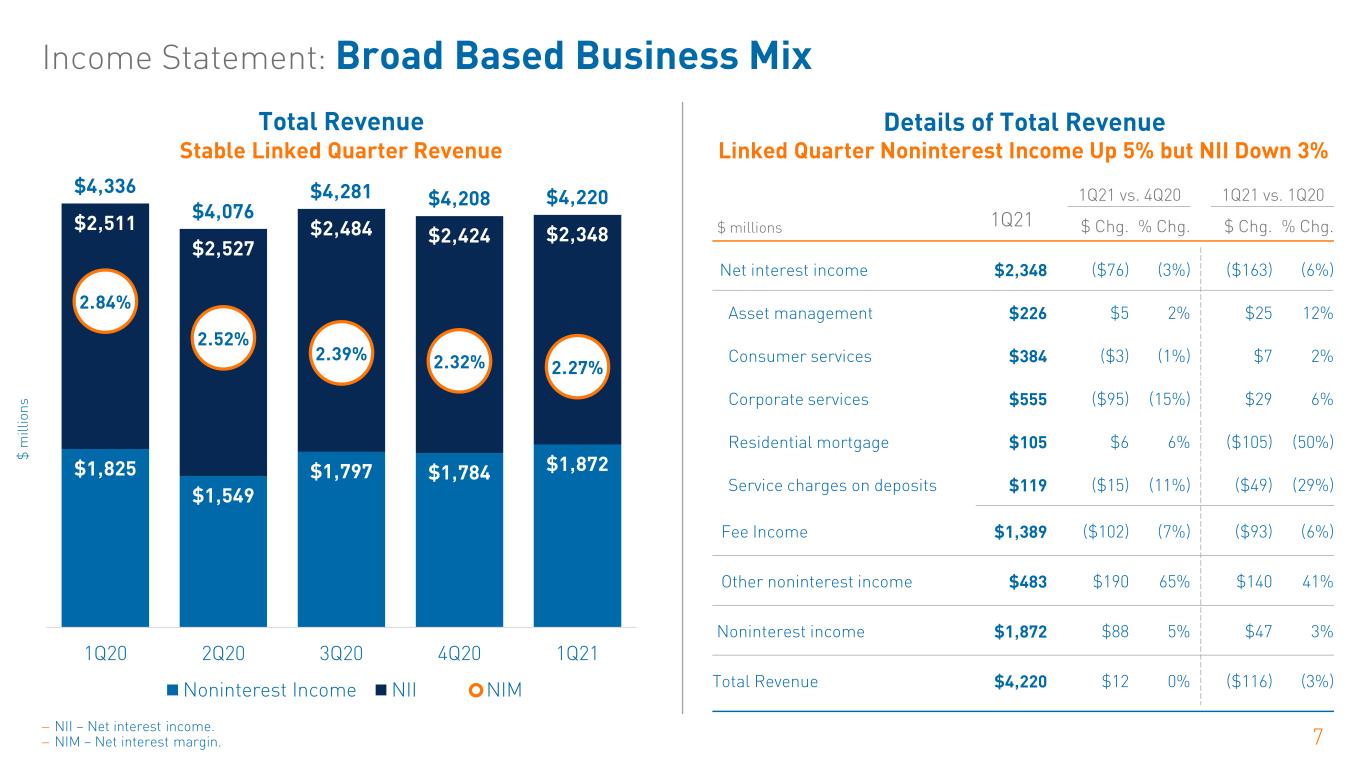
Income Statement: Broad Based Business Mix 7 Total Revenue Stable Linked Quarter Revenue Details of Total Revenue Linked Quarter Noninterest Income Up 5% but NII Down 3% 1Q21 vs. 4Q20 1Q21 vs. 1Q20 $ millions 1Q21 $ Chg. % Chg. $ Chg. % Chg. Net interest income $2,348 ($76) (3%) ($163) (6%) Asset management $226 $5 2% $25 12% Consumer services $384 ($3) (1%) $7 2% Corporate services $555 ($95) (15%) $29 6% Residential mortgage $105 $6 6% ($105) (50%) Service charges on deposits $119 ($15) (11%) ($49) (29%) Fee Income $1,389 ($102) (7%) ($93) (6%) Other noninterest income $483 $190 65% $140 41% Noninterest income $1,872 $88 5% $47 3% Total Revenue $4,220 $12 0% ($116) (3%) $ m ill io n s $1,825 $1,549 $1,797 $1,784 $1,872 $2,511 $2,527 $2,484 $2,424 $2,348 $4,336 $4,076 $4,281 $4,208 $4,220 2.84% 2.52% 2.39% 2.32% 2.27% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 4.00% 0 500 1000 1500 2000 2500 3000 3500 4000 4500 1Q20 2Q20 3Q20 4Q20 1Q21 Noninterest Income NII NIM − NII – Net interest income. − NIM – Net interest margin.
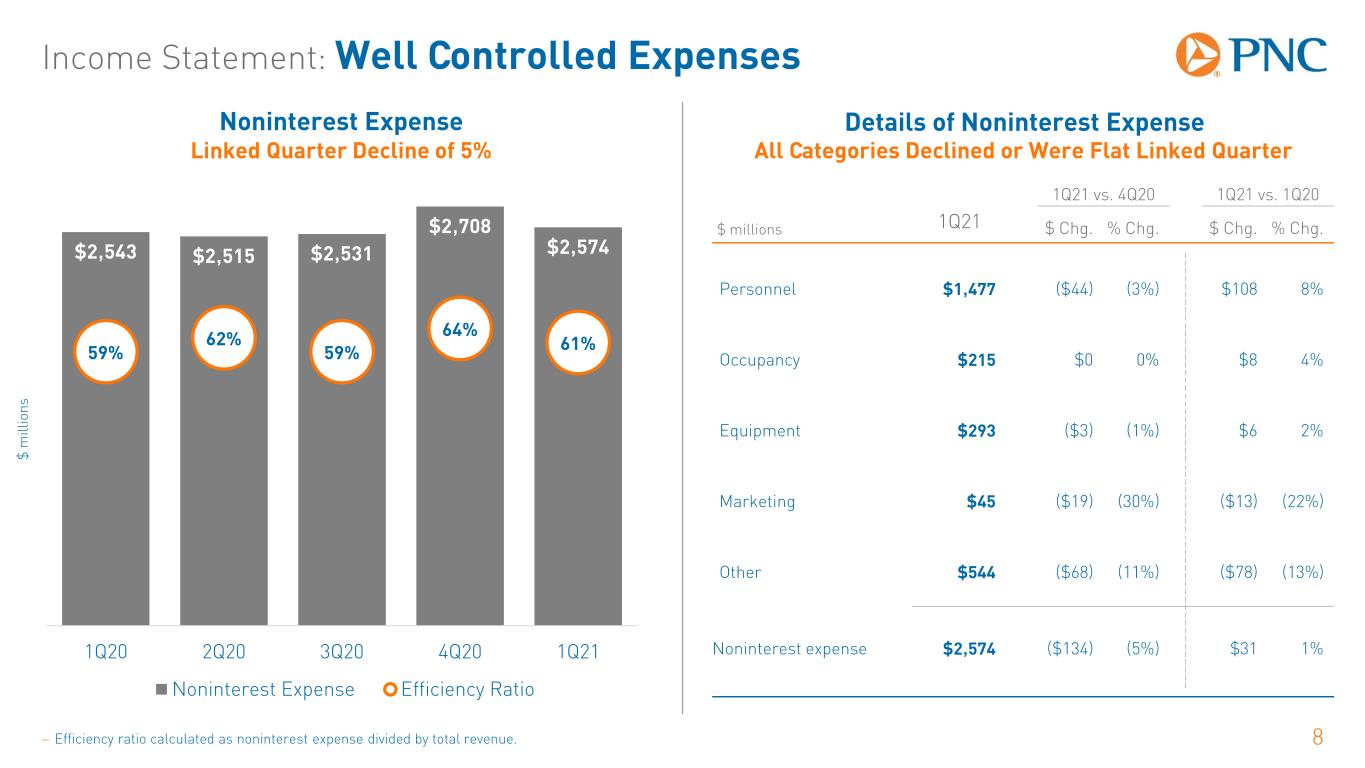
Income Statement: Well Controlled Expenses 8 Noninterest Expense Linked Quarter Decline of 5% Details of Noninterest Expense All Categories Declined or Were Flat Linked Quarter 1Q21 vs. 4Q20 1Q21 vs. 1Q20 $ millions 1Q21 $ Chg. % Chg. $ Chg. % Chg. Personnel $1,477 ($44) (3%) $108 8% Occupancy $215 $0 0% $8 4% Equipment $293 ($3) (1%) $6 2% Marketing $45 ($19) (30%) ($13) (22%) Other $544 ($68) (11%) ($78) (13%) Noninterest expense $2,574 ($134) (5%) $31 1% $2,543 $2,515 $2,531 $2,708 $2,574 59% 62% 59% 64% 61% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 0 500 1000 1500 2000 2500 3000 1Q20 2Q20 3Q20 4Q20 1Q21 Noninterest Expense Efficiency Ratio $ m ill io n s − Efficiency ratio calculated as noninterest expense divided by total revenue.
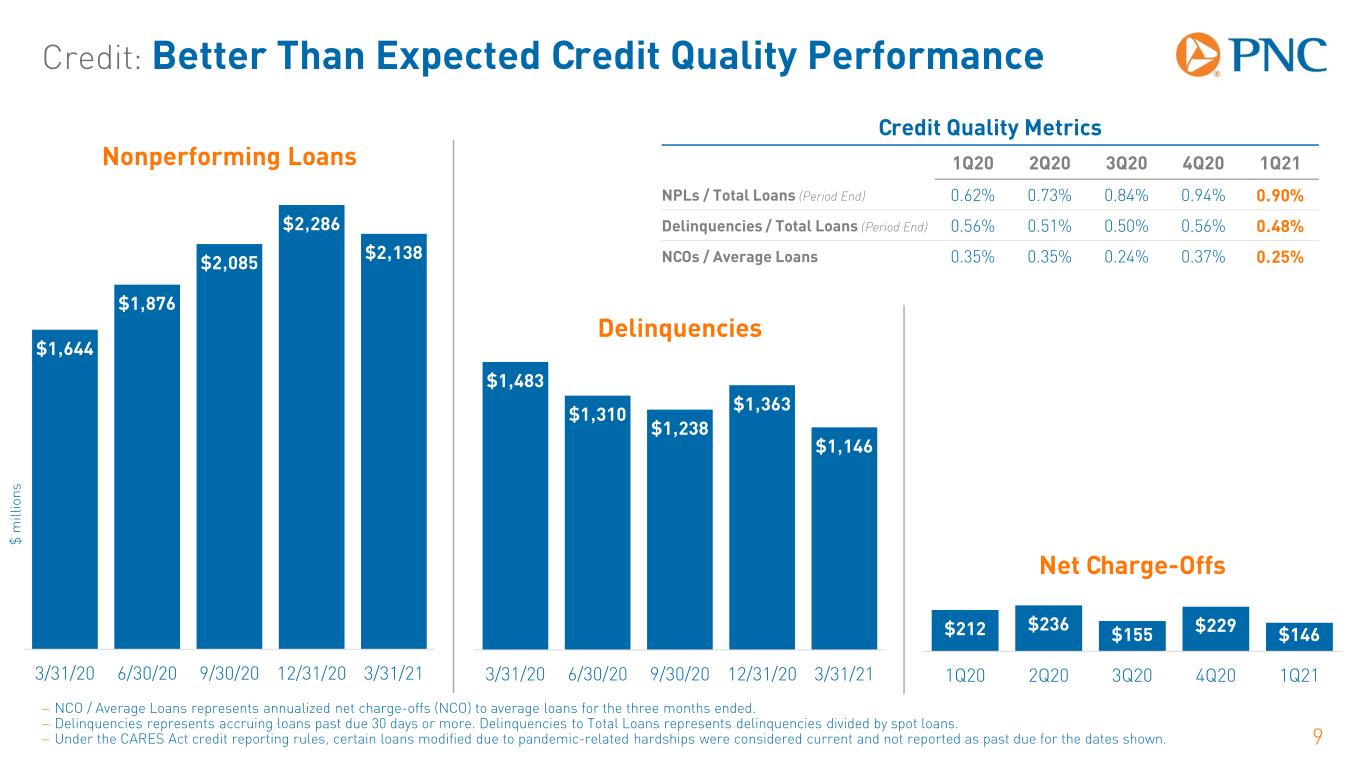
Credit: Better Than Expected Credit Quality Performance 9 − NCO / Average Loans represents annualized net charge-offs (NCO) to average loans for the three months ended. − Delinquencies represents accruing loans past due 30 days or more. Delinquencies to Total Loans represents delinquencies divided by spot loans. − Under the CARES Act credit reporting rules, certain loans modified due to pandemic-related hardships were considered current and not reported as past due for the dates shown. $1,483 $1,310 $1,238 $1,363 $1,146 0 500 1000 1500 2000 3/31/20 6/30/20 9/30/20 12/31/20 3/31/21 $1,644 $1,876 $2,085 $2,286 $2,138 0 500 1000 1500 2000 3/31/20 6/30/20 9/30/20 12/31/20 3/31/21 $212 $236 $155 $229 $146 0 500 1000 1500 2000 1Q20 2Q20 3Q20 4Q20 1Q21 $ m ill io n s Nonperforming Loans Delinquencies Net Charge-Offs Credit Quality Metrics 1Q20 2Q20 3Q20 4Q20 1Q21 NPLs / Total Loans (Period End) 0.62% 0.73% 0.84% 0.94% 0.90% Delinquencies / Total Loans (Period End) 0.56% 0.51% 0.50% 0.56% 0.48% NCOs / Average Loans 0.35% 0.35% 0.24% 0.37% 0.25%
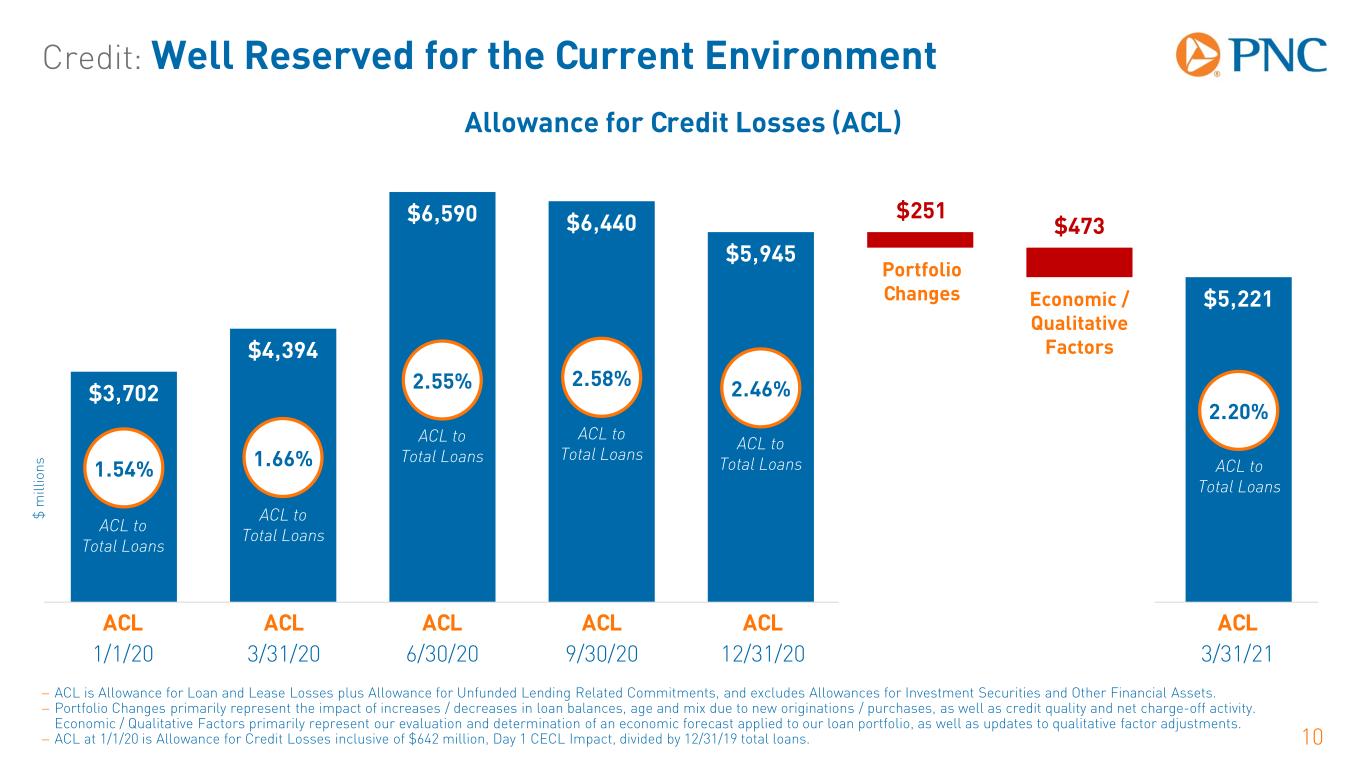
Credit: Well Reserved for the Current Environment 10 − ACL is Allowance for Loan and Lease Losses plus Allowance for Unfunded Lending Related Commitments, and excludes Allowances for Investment Securities and Other Financial Assets. − Portfolio Changes primarily represent the impact of increases / decreases in loan balances, age and mix due to new originations / purchases, as well as credit quality and net charge-off activity. Economic / Qualitative Factors primarily represent our evaluation and determination of an economic forecast applied to our loan portfolio, as well as updates to qualitative factor adjustments. − ACL at 1/1/20 is Allowance for Credit Losses inclusive of $642 million, Day 1 CECL Impact, divided by 12/31/19 total loans. Allowance for Credit Losses (ACL) ACL 1/1/20 ACL 12/31/20 ACL 9/30/20 ACL 6/30/20 ACL 3/31/20 ACL 3/31/21 $3,702 $4,394 $6,590 $6,440 $5,945 $5,221 $251 $473 1.54% 1.66% 2.55% 2.58% 2.46% 2.20% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 0 1000 2000 3000 4000 5000 6000 7000 1/1/2020 3/31/2020 6/30/2020 9/30/2020 12/31/2020 Port Chgs . E / Q Factors 3/31/2021 ACL to Total Loans ACL to Total Loans ACL to Total Loans $ m ill io n s ACL to Total Loans ACL to Total Loans ACL to Total Loans Portfolio Changes Economic / Qualitative Factors
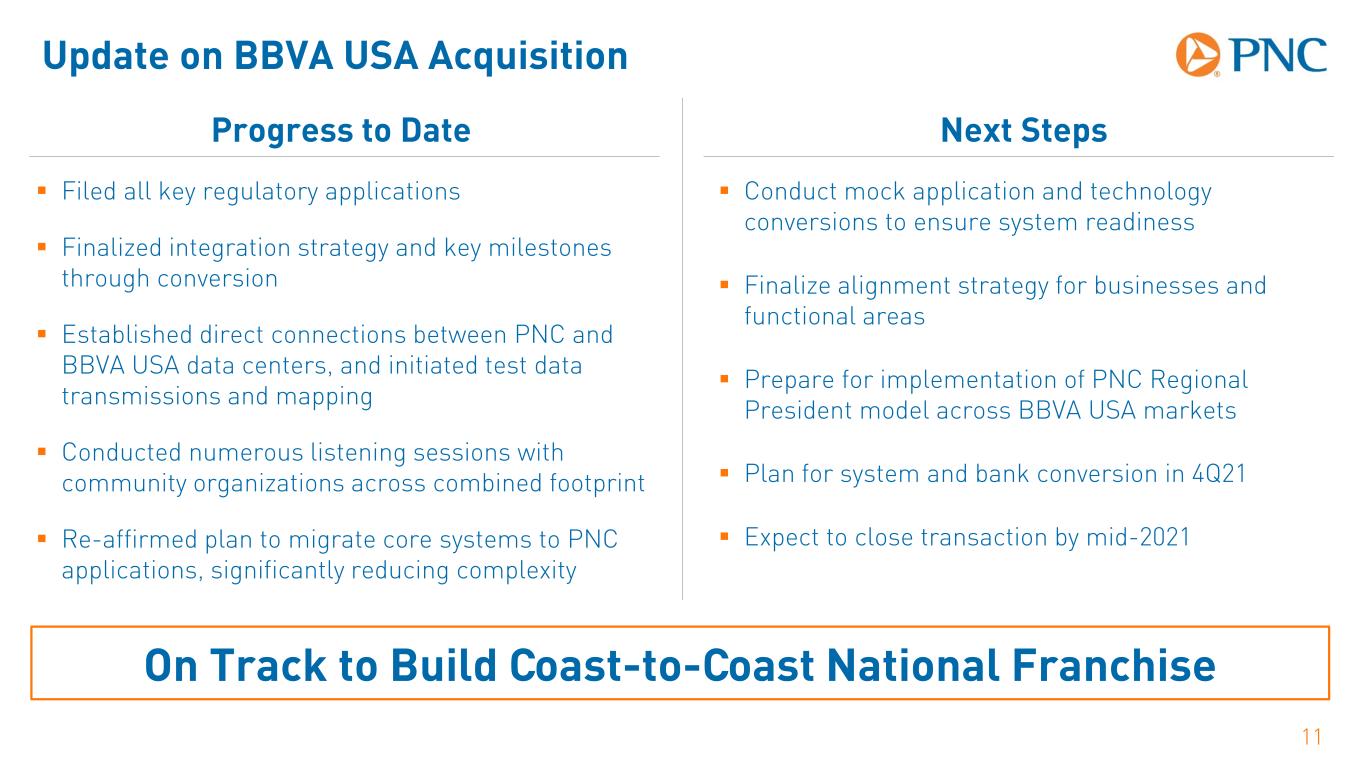
Update on BBVA USA Acquisition 11 Progress to Date Next Steps Conduct mock application and technology conversions to ensure system readiness Finalize alignment strategy for businesses and functional areas Prepare for implementation of PNC Regional President model across BBVA USA markets Plan for system and bank conversion in 4Q21 Expect to close transaction by mid-2021 On Track to Build Coast-to-Coast National Franchise Filed all key regulatory applications Finalized integration strategy and key milestones through conversion Established direct connections between PNC and BBVA USA data centers, and initiated test data transmissions and mapping Conducted numerous listening sessions with community organizations across combined footprint Re-affirmed plan to migrate core systems to PNC applications, significantly reducing complexity
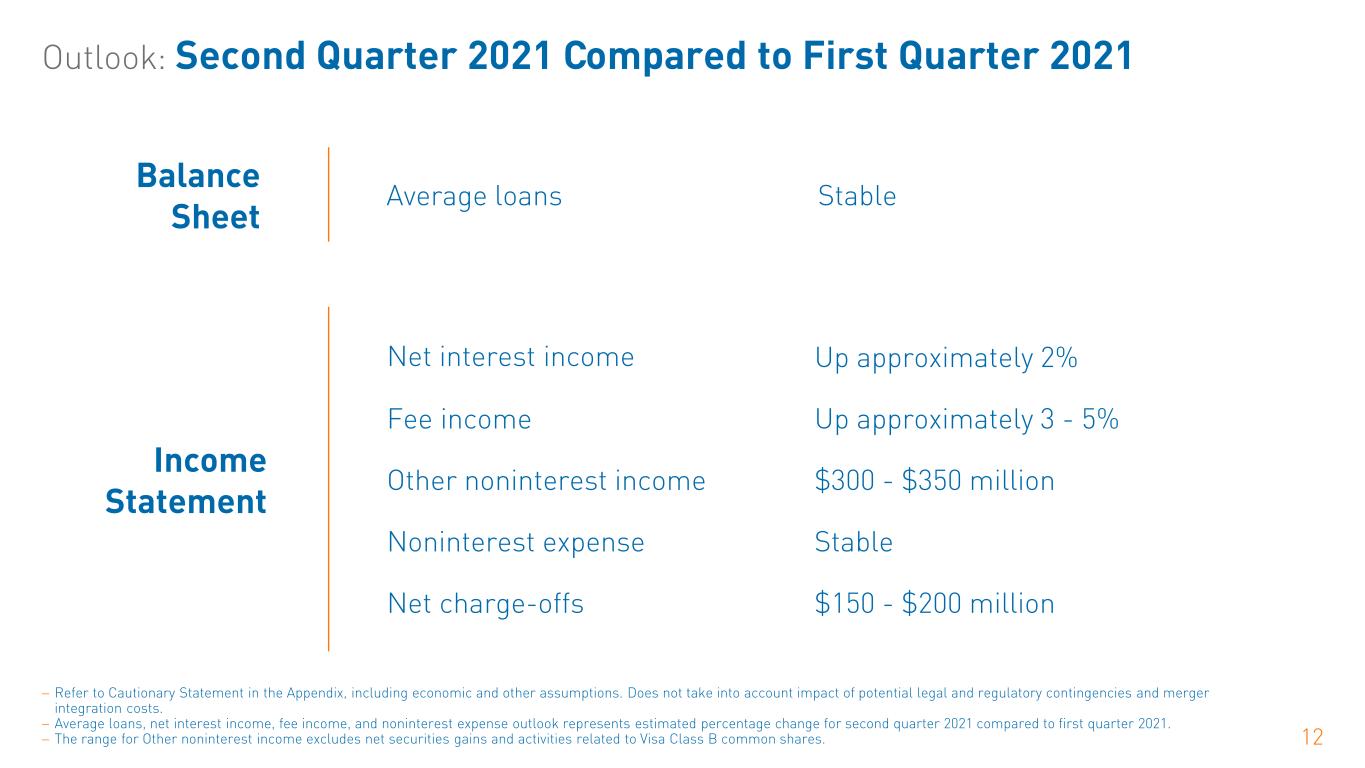
Outlook: Second Quarter 2021 Compared to First Quarter 2021 12 − Refer to Cautionary Statement in the Appendix, including economic and other assumptions. Does not take into account impact of potential legal and regulatory contingencies and merger integration costs. − Average loans, net interest income, fee income, and noninterest expense outlook represents estimated percentage change for second quarter 2021 compared to first quarter 2021. − The range for Other noninterest income excludes net securities gains and activities related to Visa Class B common shares. Balance Sheet Income Statement Net interest income Up approximately 2% Fee income Up approximately 3 - 5% Other noninterest income $300 - $350 million Noninterest expense Stable Net charge-offs $150 - $200 million Average loans Stable
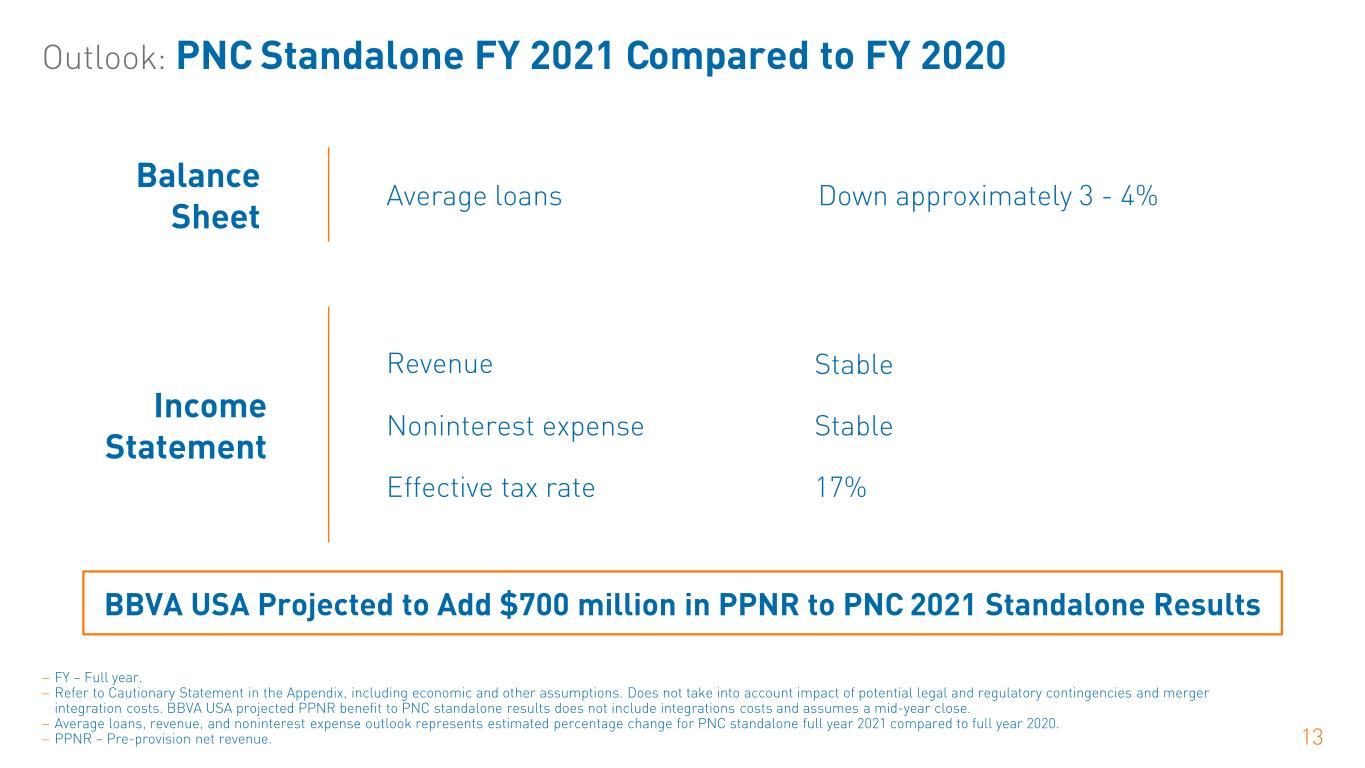
Outlook: PNC Standalone FY 2021 Compared to FY 2020 13 − FY – Full year. − Refer to Cautionary Statement in the Appendix, including economic and other assumptions. Does not take into account impact of potential legal and regulatory contingencies and merger integration costs. BBVA USA projected PPNR benefit to PNC standalone results does not include integrations costs and assumes a mid-year close. − Average loans, revenue, and noninterest expense outlook represents estimated percentage change for PNC standalone full year 2021 compared to full year 2020. − PPNR – Pre-provision net revenue. Balance Sheet Average loans Down approximately 3 - 4% Revenue Stable Noninterest expense Stable Effective tax rate 17% Income Statement BBVA USA Projected to Add $700 million in PPNR to PNC 2021 Standalone Results
Appendix: Cautionary Statement Regarding Forward-Looking Information 14 This presentation includes “snapshot” information about PNC used by way of illustration and is not intended as a full business or financial review. It should not be viewed in isolation but rather in the context of all of the information made available by PNC in its SEC filings. We also make statements in this presentation, and we may from time to time make other statements, regarding our outlook for earnings, revenues, expenses, tax rates, capital and liquidity levels and ratios, asset levels, asset quality, financial position, and other matters regarding or affecting PNC and its future business and operations that are forward-looking statements within the meaning of the Private Securities Litigation Reform Act. Forward-looking statements are typically identified by words such as “believe,” “plan,” “expect,” “anticipate,” “see,” “look,” “intend,” “outlook,” “project,” “forecast,” “estimate,” “goal,” “will,” “should” and other similar words and expressions. Forward-looking statements are necessarily subject to numerous assumptions, risks and uncertainties, which change over time. Future events or circumstances may change our outlook and may also affect the nature of the assumptions, risks and uncertainties to which our forward-looking statements are subject. Forward-looking statements speak only as of the date made. We do not assume any duty and do not undertake to update forward-looking statements. Actual results or future events could differ, possibly materially, from those anticipated in forward-looking statements, as well as from historical performance. As a result, we caution against placing undue reliance on any forward-looking statements. Our forward-looking statements are subject to the following principal risks and uncertainties. Our businesses, financial results and balance sheet values are affected by business and economic conditions, including the following: − Changes in interest rates and valuations in debt, equity and other financial markets, − Disruptions in the U.S. and global financial markets, − Actions by the Federal Reserve Board, U.S. Treasury and other government agencies, including those that impact money supply and market interest rates, − Changes in customer behavior due to changing business and economic conditions or legislative or regulatory initiatives, − Changes in customers’, suppliers’ and other counterparties’ performance and creditworthiness, − Impacts of tariffs and other trade policies of the U.S. and its global trading partners, − The length and extent of the economic impact of the COVID-19 pandemic, − The impact of the results of the recent U.S. elections on the regulatory landscape, capital markets, and the response to and management of the COVID-19 pandemic, including the effectiveness of already-enacted fiscal stimulus from the federal government and a potential infrastructure bill, and − Commodity price volatility.
Appendix: Cautionary Statement Regarding Forward-Looking Information 15 Our forward-looking financial statements are subject to the risk that economic and financial market conditions will be substantially different than those we are currently expecting and do not take into account potential legal and regulatory contingencies. These statements are based on our view that: − The U.S. economy is in an economic recovery, following a very severe but very short economic contraction in the first half of 2020 due to the COVID-19 pandemic and public health measures to contain it. − Despite the improvement in the economy in recent months, economic activity remains below its pre-pandemic level and unemployment remains elevated. − Growth will pick up in the spring of 2021 as vaccine distribution continues and the federal government provides aid to households, small and medium-sized businesses, and state and local governments. PNC expects real GDP to return to its pre-pandemic level in the third quarter of 2021, and employment in the second half of 2022. − PNC expects the Federal Open Market Committee to keep the fed funds rate in its current range of 0.00 to 0.25 percent until late 2023. PNC's ability to take certain capital actions, including returning capital to shareholders, is subject to PNC meeting or exceeding a stress capital buffer established by the Federal Reserve Board in connection with the Federal Reserve Board's Comprehensive Capital Analysis and Review (CCAR) process. The Federal Reserve also has imposed additional limitations on capital distributions through the second quarter of 2021 by CCAR-participating bank holding companies. PNC’s regulatory capital ratios in the future will depend on, among other things, the company’s financial performance, the scope and terms of final capital regulations then in effect and management actions affecting the composition of PNC’s balance sheet. In addition, PNC’s ability to determine, evaluate and forecast regulatory capital ratios, and to take actions (such as capital distributions) based on actual or forecasted capital ratios, will be dependent at least in part on the development, validation and regulatory review of related models. Legal and regulatory developments could have an impact on our ability to operate our businesses, financial condition, results of operations, competitive position, reputation, or pursuit of attractive acquisition opportunities. Reputational impacts could affect matters such as business generation and retention, liquidity, funding, and ability to attract and retain management. These developments could include: − Changes to laws and regulations, including changes affecting oversight of the financial services industry, consumer protection, bank capital and liquidity standards, pension, bankruptcy and other industry aspects, and changes in accounting policies and principles. − Unfavorable resolution of legal proceedings or other claims and regulatory and other governmental investigations or other inquiries. These matters may result in monetary judgments or settlements or other remedies, including fines, penalties, restitution or alterations in our business practices, and in additional expenses and collateral costs, and may cause reputational harm to PNC. − Results of the regulatory examination and supervision process, including our failure to satisfy requirements of agreements with governmental agencies. − Impact on business and operating results of any costs associated with obtaining rights in intellectual property claimed by others and of adequacy of our intellectual property protection in general.
Appendix: Cautionary Statement Regarding Forward-Looking Information 16 Business and operating results are affected by our ability to identify and effectively manage risks inherent in our businesses, including, where appropriate, through effective use of systems and controls, third-party insurance, derivatives, and capital management techniques, and to meet evolving regulatory capital and liquidity standards. Our planned acquisition of BBVA USA Bancshares, Inc. presents us with risks and uncertainties related both to the acquisition transaction itself and to the integration of the acquired business into PNC after closing: − The business of BBVA USA Bancshares, Inc., including its U.S. banking subsidiary, BBVA USA, going forward may not perform as we currently project or in a manner consistent with historical performance. As a result, the anticipated benefits, including estimated cost savings, of the transaction may be significantly harder or take longer to achieve than expected or may not be achieved in their entirety as a result of unexpected factors or events, including those that are outside of our control. − The combination of BBVA USA Bancshares, Inc., including its U.S. banking subsidiary, BBVA USA, with that of PNC and PNC Bank may be more difficult to achieve than anticipated or have unanticipated adverse results relating to BBVA USA Bancshares, Inc., including its U.S. banking subsidiary, BBVA USA, or our existing businesses. − Completion of the transaction is dependent on the satisfaction of customary closing conditions, which cannot be assured. The timing of completion of the transaction is dependent on various factors that cannot be predicted with precision at this point. In addition to the planned BBVA USA Bancshares, Inc. transaction, we grow our business in part through acquisitions and new strategic initiatives. Risks and uncertainties include those presented by the nature of the business acquired and strategic initiative, including in some cases those associated with our entry into new businesses or new geographic or other markets and risks resulting from our inexperience in those new areas, as well as risks and uncertainties related to the acquisition transactions themselves, regulatory issues, and the integration of the acquired businesses into PNC after closing. Competition can have an impact on customer acquisition, growth and retention and on credit spreads and product pricing, which can affect market share, deposits and revenues. Our ability to anticipate and respond to technological changes can also impact our ability to respond to customer needs and meet competitive demands. Business and operating results can also be affected by widespread natural and other disasters, pandemics, dislocations, terrorist activities, system failures, security breaches, cyberattacks or international hostilities through impacts on the economy and financial markets generally or on us or our counterparties specifically. We provide greater detail regarding these as well as other factors in our 2020 Form 10-K, including in the Risk Factors and Risk Management sections and the Legal Proceedings and Commitments Notes of the Notes To Consolidated Financial Statements in those reports, and in our other subsequent SEC filings. Our forward-looking statements may also be subject to other risks and uncertainties, including those we may discuss elsewhere in this presentation or in our SEC filings, accessible on the SEC’s website at www.sec.gov and on our corporate website at www.pnc.com/secfilings. We have included these web addresses as inactive textual references only. Information on these websites is not part of this document.
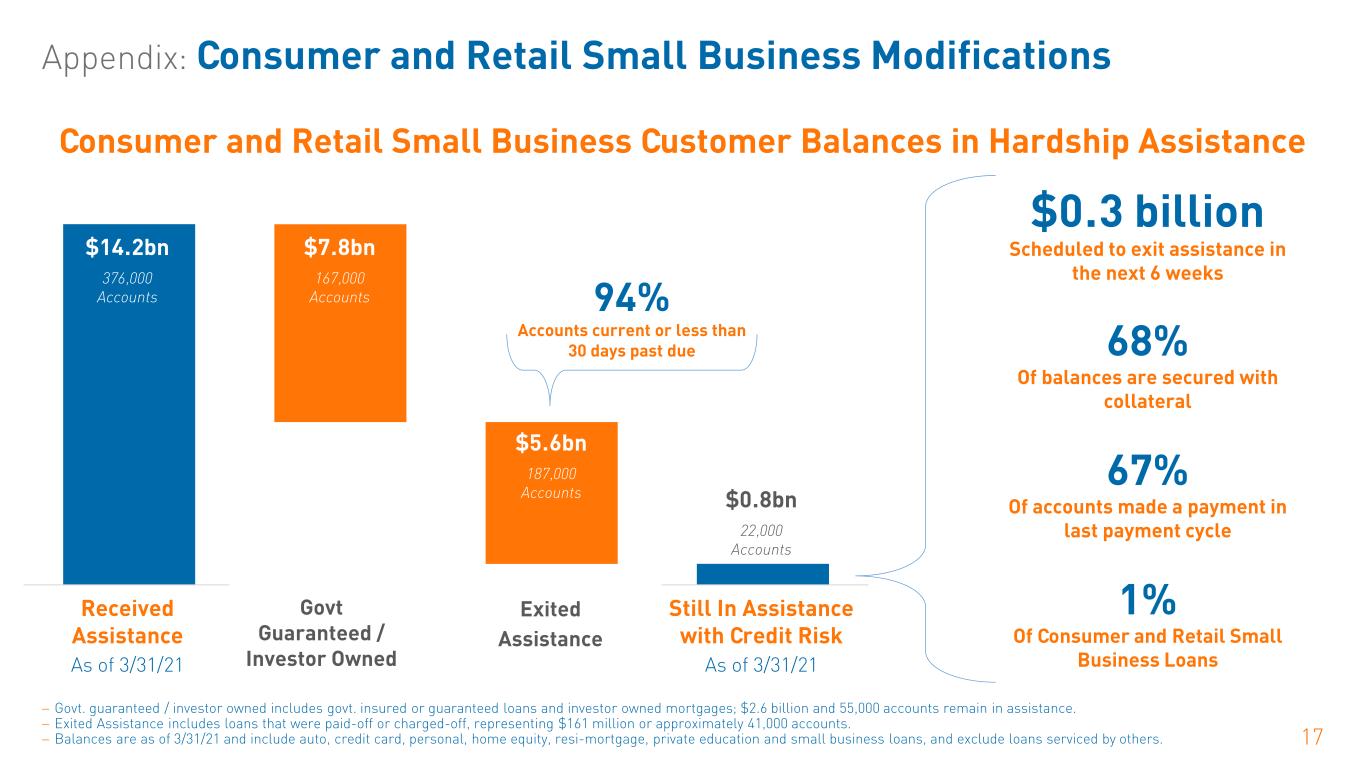
Appendix: Consumer and Retail Small Business Modifications 17 − Govt. guaranteed / investor owned includes govt. insured or guaranteed loans and investor owned mortgages; $2.6 billion and 55,000 accounts remain in assistance. − Exited Assistance includes loans that were paid-off or charged-off, representing $161 million or approximately 41,000 accounts. − Balances are as of 3/31/21 and include auto, credit card, personal, home equity, resi-mortgage, private education and small business loans, and exclude loans serviced by others. Consumer and Retail Small Business Customer Balances in Hardship Assistance 1 2 3 4 Received Assistance As of 3/31/21 Govt Guaranteed / Investor Owned Exited Assistance Still In Assistance with Credit Risk As of 3/31/21 $7.8bn 167,000 Accounts $14.2bn 376,000 Accounts $5.6bn 187,000 Accounts $0.8bn 22,000 Accounts 94% Accounts current or less than 30 days past due $0.3 billion Scheduled to exit assistance in the next 6 weeks 67% Of accounts made a payment in last payment cycle 1% Of Consumer and Retail Small Business Loans 68% Of balances are secured with collateral
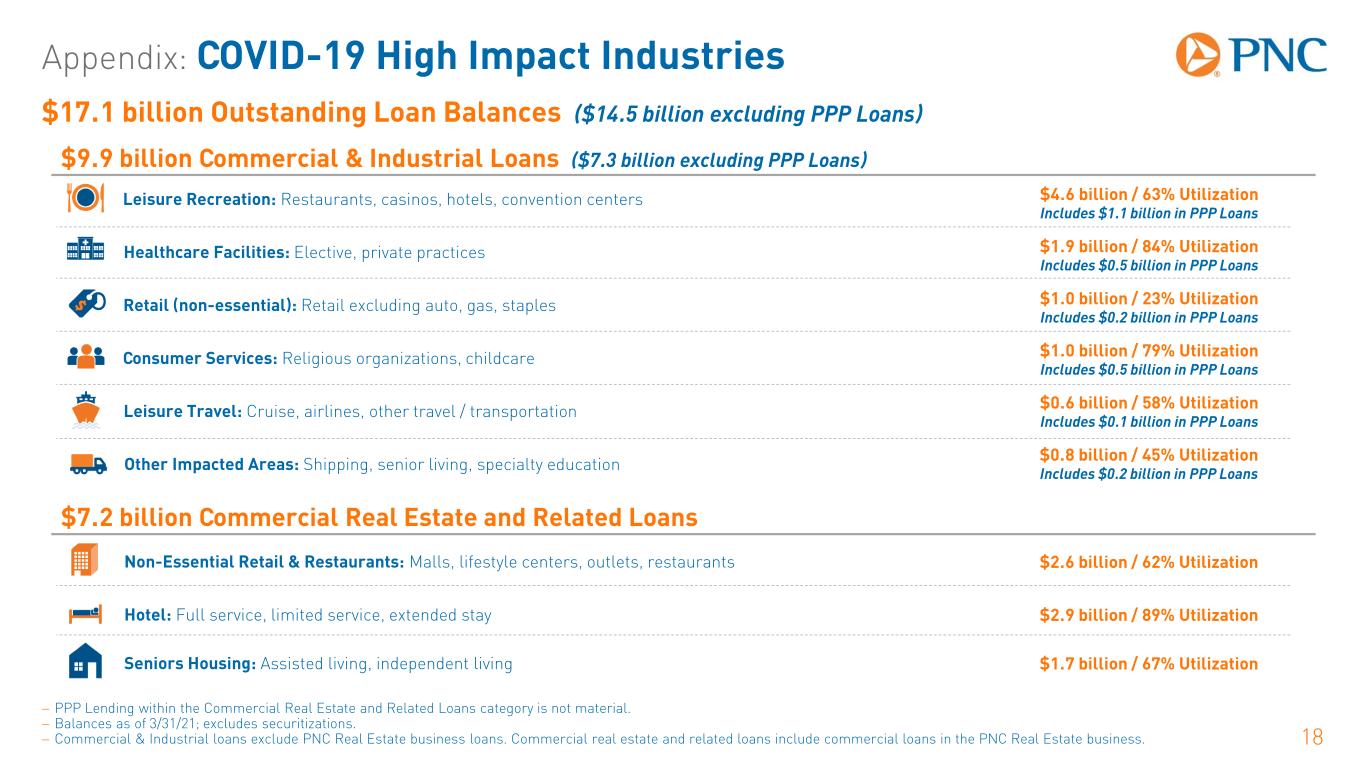
Appendix: COVID-19 High Impact Industries 18 − PPP Lending within the Commercial Real Estate and Related Loans category is not material. − Balances as of 3/31/21; excludes securitizations. − Commercial & Industrial loans exclude PNC Real Estate business loans. Commercial real estate and related loans include commercial loans in the PNC Real Estate business. $7.2 billion Commercial Real Estate and Related Loans Non-Essential Retail & Restaurants: Malls, lifestyle centers, outlets, restaurants Hotel: Full service, limited service, extended stay Seniors Housing: Assisted living, independent living $2.6 billion / 62% Utilization $2.9 billion / 89% Utilization $1.7 billion / 67% Utilization $17.1 billion Outstanding Loan Balances ($14.5 billion excluding PPP Loans) $9.9 billion Commercial & Industrial Loans ($7.3 billion excluding PPP Loans) Leisure Recreation: Restaurants, casinos, hotels, convention centers Healthcare Facilities: Elective, private practices Other Impacted Areas: Shipping, senior living, specialty education Consumer Services: Religious organizations, childcare $1.9 billion / 84% Utilization Includes $0.5 billion in PPP Loans $0.8 billion / 45% Utilization Includes $0.2 billion in PPP Loans $1.0 billion / 79% Utilization Includes $0.5 billion in PPP Loans Leisure Travel: Cruise, airlines, other travel / transportation $0.6 billion / 58% Utilization Includes $0.1 billion in PPP Loans Retail (non-essential): Retail excluding auto, gas, staples $1.0 billion / 23% Utilization Includes $0.2 billion in PPP Loans $4.6 billion / 63% Utilization Includes $1.1 billion in PPP Loans
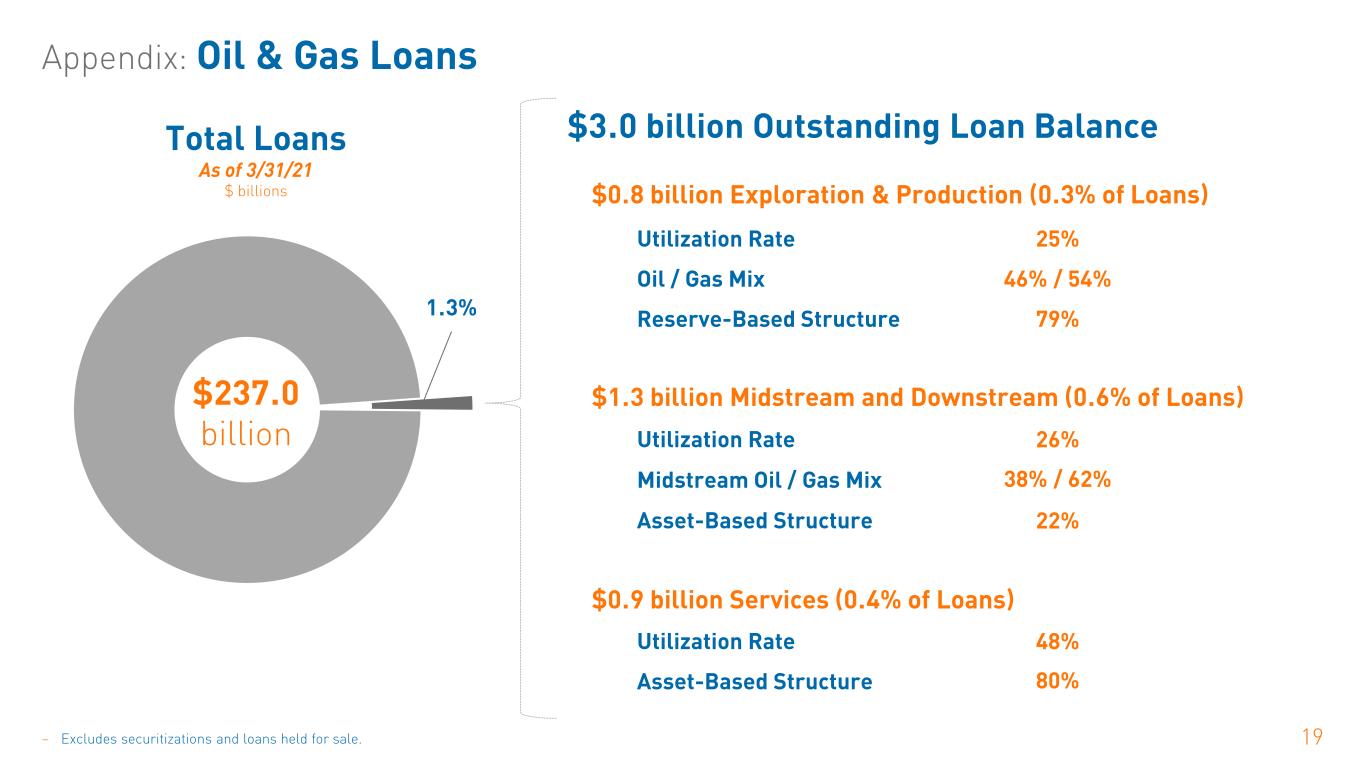
Appendix: Oil & Gas Loans 19– Excludes securitizations and loans held for sale. $0.8 billion Exploration & Production (0.3% of Loans) Utilization Rate 25% $3.0 billion Outstanding Loan Balance Oil / Gas Mix 46% / 54% Reserve-Based Structure 79% $1.3 billion Midstream and Downstream (0.6% of Loans) $0.9 billion Services (0.4% of Loans) Utilization Rate 48% Asset-Based Structure 80% Utilization Rate 26% Midstream Oil / Gas Mix 38% / 62% Asset-Based Structure 22% 1.3% Total Loans As of 3/31/21 $ billions $237.0 billion
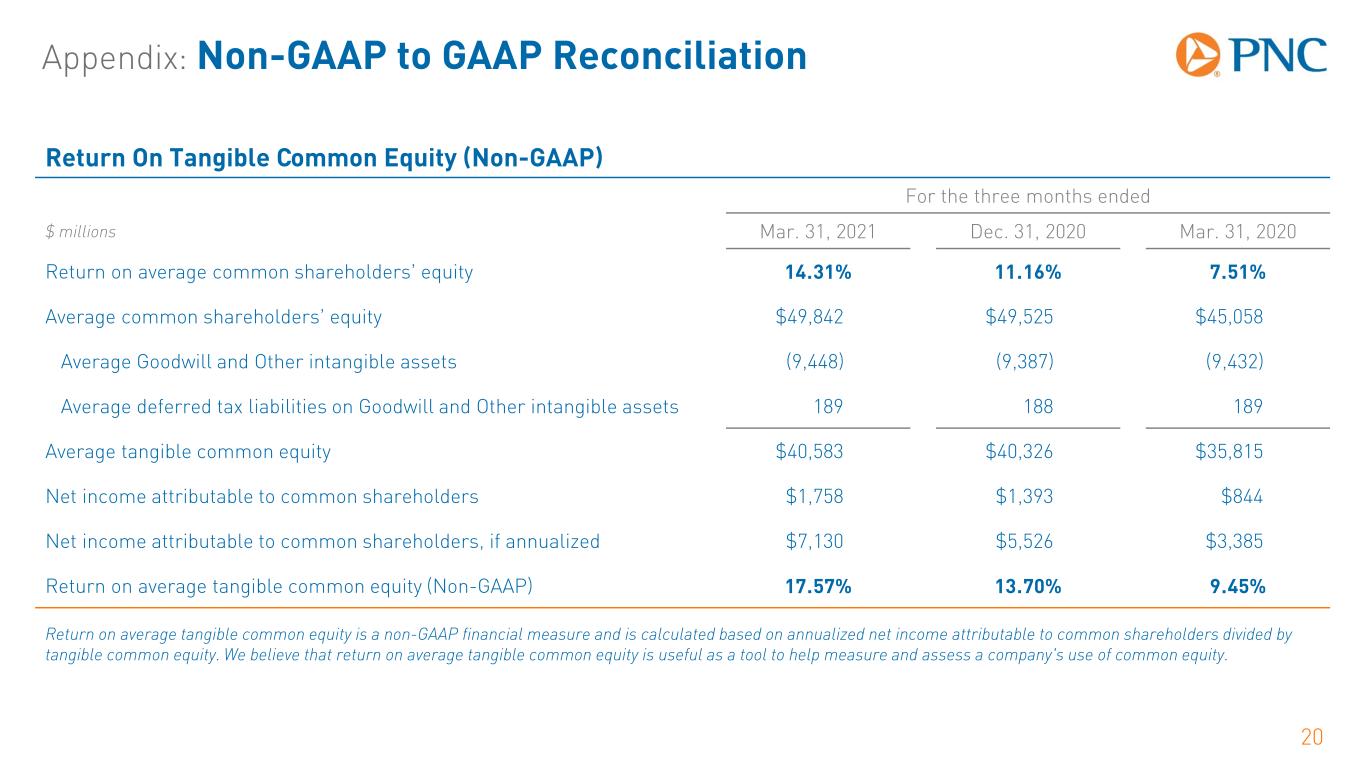
Appendix: Non-GAAP to GAAP Reconciliation 20 Return On Tangible Common Equity (Non-GAAP) For the three months ended $ millions Mar. 31, 2021 Dec. 31, 2020 Mar. 31, 2020 Return on average common shareholders’ equity 14.31% 11.16% 7.51% Average common shareholders’ equity $49,842 $49,525 $45,058 Average Goodwill and Other intangible assets (9,448) (9,387) (9,432) Average deferred tax liabilities on Goodwill and Other intangible assets 189 188 189 Average tangible common equity $40,583 $40,326 $35,815 Net income attributable to common shareholders $1,758 $1,393 $844 Net income attributable to common shareholders, if annualized $7,130 $5,526 $3,385 Return on average tangible common equity (Non-GAAP) 17.57% 13.70% 9.45% Return on average tangible common equity is a non-GAAP financial measure and is calculated based on annualized net income attributable to common shareholders divided by tangible common equity. We believe that return on average tangible common equity is useful as a tool to help measure and assess a company's use of common equity.
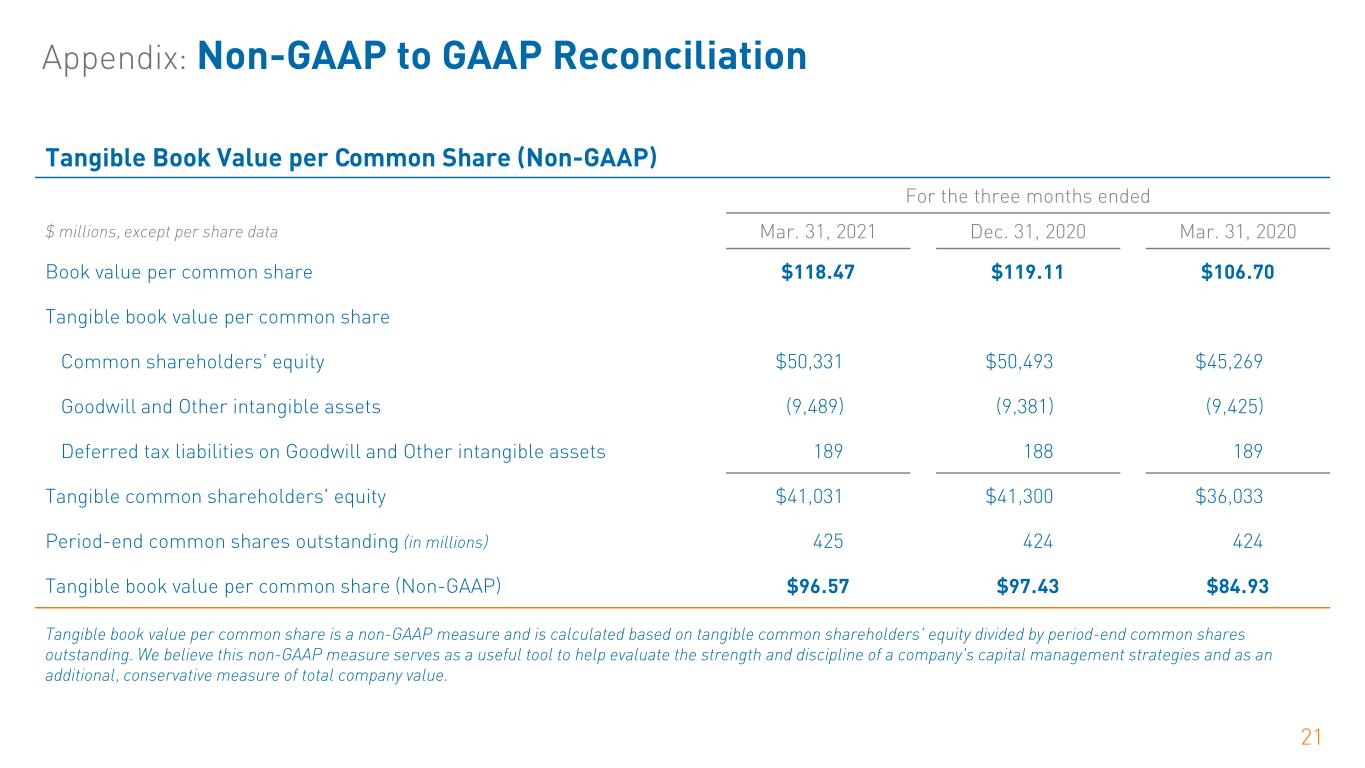
Appendix: Non-GAAP to GAAP Reconciliation 21 Tangible Book Value per Common Share (Non-GAAP) For the three months ended $ millions, except per share data Mar. 31, 2021 Dec. 31, 2020 Mar. 31, 2020 Book value per common share $118.47 $119.11 $106.70 Tangible book value per common share Common shareholders’ equity $50,331 $50,493 $45,269 Goodwill and Other intangible assets (9,489) (9,381) (9,425) Deferred tax liabilities on Goodwill and Other intangible assets 189 188 189 Tangible common shareholders' equity $41,031 $41,300 $36,033 Period-end common shares outstanding (in millions) 425 424 424 Tangible book value per common share (Non-GAAP) $96.57 $97.43 $84.93 Tangible book value per common share is a non-GAAP measure and is calculated based on tangible common shareholders’ equity divided by period-end common shares outstanding. We believe this non-GAAP measure serves as a useful tool to help evaluate the strength and discipline of a company's capital management strategies and as an additional, conservative measure of total company value.
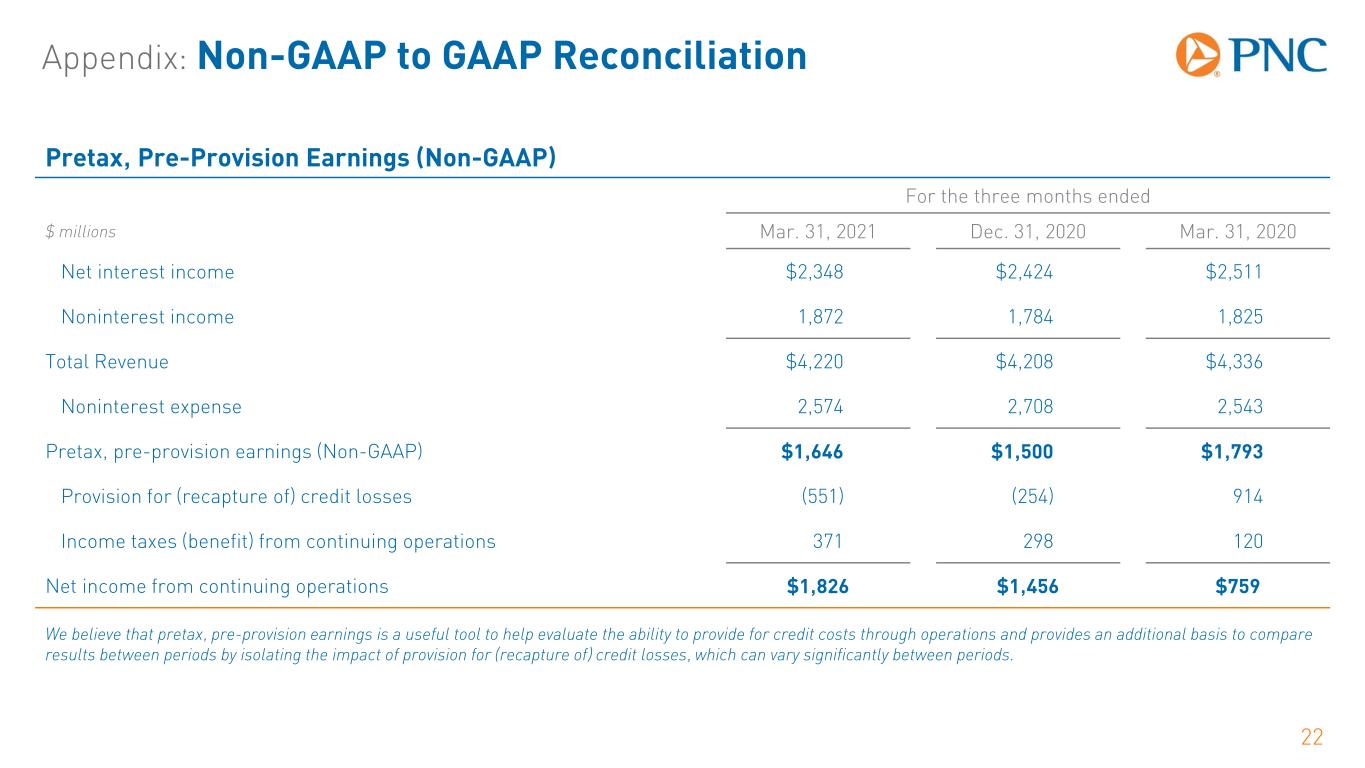
Appendix: Non-GAAP to GAAP Reconciliation 22 Pretax, Pre-Provision Earnings (Non-GAAP) For the three months ended $ millions Mar. 31, 2021 Dec. 31, 2020 Mar. 31, 2020 Net interest income $2,348 $2,424 $2,511 Noninterest income 1,872 1,784 1,825 Total Revenue $4,220 $4,208 $4,336 Noninterest expense 2,574 2,708 2,543 Pretax, pre-provision earnings (Non-GAAP) $1,646 $1,500 $1,793 Provision for (recapture of) credit losses (551) (254) 914 Income taxes (benefit) from continuing operations 371 298 120 Net income from continuing operations $1,826 $1,456 $759 We believe that pretax, pre-provision earnings is a useful tool to help evaluate the ability to provide for credit costs through operations and provides an additional basis to compare results between periods by isolating the impact of provision for (recapture of) credit losses, which can vary significantly between periods.
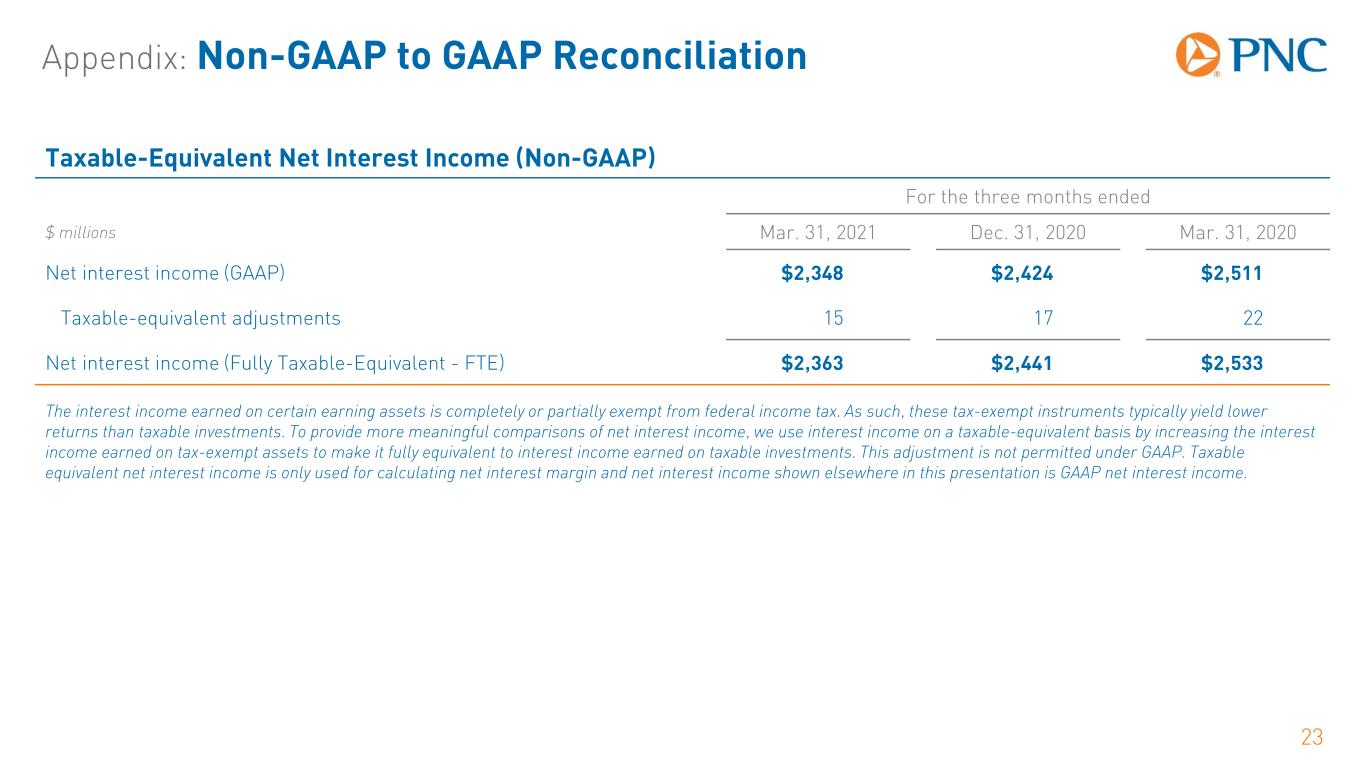
Appendix: Non-GAAP to GAAP Reconciliation 23 Taxable-Equivalent Net Interest Income (Non-GAAP) For the three months ended $ millions Mar. 31, 2021 Dec. 31, 2020 Mar. 31, 2020 Net interest income (GAAP) $2,348 $2,424 $2,511 Taxable-equivalent adjustments 15 17 22 Net interest income (Fully Taxable-Equivalent - FTE) $2,363 $2,441 $2,533 The interest income earned on certain earning assets is completely or partially exempt from federal income tax. As such, these tax-exempt instruments typically yield lower returns than taxable investments. To provide more meaningful comparisons of net interest income, we use interest income on a taxable-equivalent basis by increasing the interest income earned on tax-exempt assets to make it fully equivalent to interest income earned on taxable investments. This adjustment is not permitted under GAAP. Taxable equivalent net interest income is only used for calculating net interest margin and net interest income shown elsewhere in this presentation is GAAP net interest income.