
TBBK 8-K
Bancorp, Inc. (TBBK)
8-K
2026-07-30
For: 2026-07-30
View Original
Added on
July 31, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 8-K
Current Report
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): July 30, 2026
(Exact name of registrant as specified in its charter)
Commission File Number: 000-51018
| (State or other jurisdiction of | (IRS Employer | ||||
| incorporation) | Identification No.) | ||||
(Address of principal executive offices, including zip code)
(Registrant’s telephone number, including area code)
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2).
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. [ ]
| Item 2.02. | Results of Operations and Financial Condition | ||||
On July 30, 2026, The Bancorp, Inc. (the “Company”) issued a press release regarding its earnings for the three and six months ended June 30, 2026. A copy of this press release is furnished with this report as Exhibit 99.1.
| Item 7.01. | Regulation FD Disclosure | ||||
The Company hereby furnishes the information set forth in the presentation attached hereto as Exhibit 99.2, which is incorporated herein by reference.
The information being furnished pursuant to Item 2.02 and Item 7.01 in this Current Report, including the exhibits hereto, is to be considered “furnished” pursuant to Form 8-K and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that section. The information in this Current Report shall not be incorporated by reference into any registration statement or other document pursuant to the Securities Act of 1933, as amended.
| Item 9.01. | Financial Statements and Exhibits | ||||
(d)Exhibits
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: | July 30, 2026 | The Bancorp, Inc. | |||||||||
| By: | /S/ DOMINIC C. CANUSO | ||||||||||
| Name: | Dominic C. Canuso | ||||||||||
| Title: | Chief Financial Officer (Principal Financial Officer) | ||||||||||
Exhibit 99.1
THE BANCORP REPORTS 2Q 2026 EPS OF $1.45, ROA OF 2.51%, AND ROE OF 34.7%
DRIVEN BY STRONG GROWTH IN LOANS AND FINTECH FEES;
CONTINUED IMPROVEMENT IN CREDIT AND COST EFFICIENCIES
Second Quarter 2026 Highlights
•Earnings per diluted share (“EPS”) of $1.45 compared to $1.27 for 2Q 2025, an increase of 14.2%.
•Net income of $60.7 million compared to net income of $59.8 million for 2Q 2025.
•Return on assets of 2.51% compared to 2.64% for 2Q 2025.
•Return on equity of 34.7% compared to 28.4% for 2Q 2025.
•Net interest income of $90.5 million compared to $97.5 million for 2Q 2025.
•Net interest margin of 3.85% compared to 4.44% for 2Q 2025.
•Ending Loans, net of deferred fees and costs of $7.07 billion compared to $6.54 billion at 2Q 2025, an 8.2% increase, and $7.75 billion at 1Q 2026, an 8.8% decrease (not annualized).
•Ending Fintech loans of $901.5 million, or 12.5% of total loans, a 32.5% increase from $680.5 million at 2Q 2025 and a 45.3% decrease (not annualized) from $1.65 billion at 1Q 2026, primarily driven by a change in payment processing timing. Average Fintech loans of $1.39 billion, an $853.9 million increase, or 159.0% from 2Q 2025, and an increase of $275.7 million, or 24.7% (not annualized), compared to 1Q 2026.
•Average deposits of $8.41 billion increased $357.2 million, or 4.4% from 2Q 2025 and increased $97.3 million, or 1.2% (not annualized) from 1Q 2026. The average cost of deposits was 1.63% compared to 2.18% for 2Q 2025 and 1.70% in 1Q 2026.
•Gross dollar volume (“GDV”), representing the total amount spent on prepaid, debit and credit cards totaled $53.45 billion, an increase of $9.80 billion, or 22.5%, compared to $43.65 billion in 2Q 2025 and an increase of $939.9 million, or 1.8% (not annualized), compared to 1Q 2026.
•Consumer credit fees from fintech loans increased 64.9% to $6.5 million compared to $4.0 million for 2Q 2025 and increased 17.0% from $5.6 million in 1Q 2026.
•Total prepaid, debit card, ACH, and other payment fees of $34.3 million, an increase of $2.7 million, or 8.4%, compared to $31.7 million in 2Q 2025, and a $1.8 million increase, or 5.8%, compared to $32.5 million in 1Q 2026.
•Non-interest income totaled $73.0 million, or 44.7% of total revenue and $47.3 million,* or 34.3% of total revenue when excluding credit enhancement income.* This compares to 46.2% of total revenue in 2Q 2025, or 29.4% when excluding credit enhancement income,* and 45.0% of total revenue in 1Q 2026, or 33.0% when excluding credit enhancement income.*
•Share repurchases of $50.0 million for 870,129 shares, or 2.1% of issued and outstanding shares, at an average cost of $57.46.
_______
*See “Non-GAAP Financial Measures” section at the end of the document for a detailed description.
1
Wilmington, DE – July 30, 2026 – The Bancorp, Inc. (NASDAQ: TBBK), a financial holding company, today reported its financial results for the second quarter of 2026, reporting net income of $60.7 million and $1.45 per diluted share for the quarter, reflecting diluted EPS growth of 14.2% from the second quarter of 2025.
“Our performance in the second quarter of 2026 significantly surpassed our own forecasts of profitability and GDV growth, which we believe demonstrates our strong momentum as we head into the second half of the year,” said Damian Kozlowski, President and CEO of The Bancorp. “We are increasing our full-year 2026 EPS guidance to a range of $5.95-$6.05, which includes a range of $1.65-$1.75 in the fourth quarter. We are maintaining our 2027 EPS guidance range of between $8.10-$8.30.”
| (Dollars in thousands except per share data and where otherwise noted. Unaudited) | 2Q 2026 | 1Q 2026 | 2Q 2025 | ||||||||||||||||||||||||||
| Key Performance Metrics: | |||||||||||||||||||||||||||||
Return on assets(1) | 2.51 | % | 2.57 | % | 2.64 | % | |||||||||||||||||||||||
Return on equity(1) | 34.7 | % | 35.1 | % | 28.4 | % | |||||||||||||||||||||||
Efficiency ratio(2) | 41.0 | % | 41.5 | % | 41.5 | % | |||||||||||||||||||||||
| Net interest margin | 3.85 | % | 3.87 | % | 4.44 | % | |||||||||||||||||||||||
| Non-interest income as a percentage of total revenue | 44.7 | % | 45.0 | % | 46.2 | % | |||||||||||||||||||||||
Non-interest income as a percentage of total revenue (excluding credit enhancement income)(2) | 34.3 | % | 33.0 | % | 29.4 | % | |||||||||||||||||||||||
| Fintech fees as a percentage of total revenue | 25.0 | % | 23.6 | % | 19.7 | % | |||||||||||||||||||||||
Fintech fees as a percentage of total revenue (excluding credit enhancement income)(2) | 29.7 | % | 28.7 | % | 25.8 | % | |||||||||||||||||||||||
| Book value per share (as of period end) | $ | 17.19 | $ | 16.65 | $ | 18.60 | |||||||||||||||||||||||
| Results of Operations: | |||||||||||||||||||||||||||||
| Net income | $ | 60,656 | $ | 60,069 | $ | 59,821 | |||||||||||||||||||||||
| Net income per share - diluted | $ | 1.45 | $ | 1.41 | $ | 1.27 | |||||||||||||||||||||||
| Weighted average shares - diluted | 41,794,160 | 42,594,824 | 47,182,770 | ||||||||||||||||||||||||||
| Net interest income | $ | 90,466 | $ | 88,814 | $ | 97,492 | |||||||||||||||||||||||
| Provision (reversal) for credit losses on non-fintech loans | $ | 365 | $ | (1,348) | $ | 1,494 | |||||||||||||||||||||||
| Non-interest income - total fintech fees | $ | 40,894 | $ | 38,069 | $ | 35,645 | |||||||||||||||||||||||
| Total non-interest expense | $ | 56,476 | $ | 55,026 | $ | 57,223 | |||||||||||||||||||||||
| Income tax expense | $ | 20,285 | $ | 18,643 | $ | 19,828 | |||||||||||||||||||||||
| Volume: | |||||||||||||||||||||||||||||
| Average loan portfolio (dollars in millions) | $ | 7,629 | $ | 7,255 | $ | 6,569 | |||||||||||||||||||||||
| Average assets (dollars in millions) | $ | 9,704 | $ | 9,484 | $ | 9,088 | |||||||||||||||||||||||
| Average deposits (dollars in millions) | $ | 8,414 | $ | 8,317 | $ | 8,057 | |||||||||||||||||||||||
Prepaid debit, and credit card gross dollar volume (GDV)(3) | $ | 53,452,821 | $ | 52,512,908 | $ | 43,649,005 | |||||||||||||||||||||||
__________
(1)Annualized.
(2) See “Non-GAAP Financial Measures” section at the end of the document for detailed description.
(3)Gross dollar volume represents the total dollar amount spent on prepaid, debit and credit cards issued by The Bancorp Bank, N.A.
Earnings Release Conference Call
Management will conduct a conference call to review second quarter of 2026 results at 8:00 AM ET on Friday, July 31, 2026. Interested parties may access the live conference call by clicking on the webcast link on The Bancorp’s homepage at www.thebancorp.com or by dialing 1.833.461.5787 and entering Conference ID 274712196.
For those who cannot access the live broadcast, the replay will be available following the live call via webcast on The Bancorp’s website or by visiting https://events.q4inc.com/attendee/274712196.
2
Financial Results:
Loan Portfolio
The following table summarizes our total loan portfolio at June 30, 2026 compared to prior periods:
| (in thousands) | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||||||||
| Mix | Mix | Mix | ||||||||||||||||||||||||
| Loans, at amortized cost: | ||||||||||||||||||||||||||
| Real estate bridge lending | $ | 2,233,688 | 31.1 | % | $ | 2,279,454 | 28.9 | % | $ | 2,140,039 | 31.8 | % | ||||||||||||||
| SBLOC / IBLOC | 1,825,301 | 25.4 | % | 1,708,709 | 21.7 | % | 1,601,405 | 23.8 | % | |||||||||||||||||
| Small business loans | 1,034,264 | 14.4 | % | 998,860 | 12.7 | % | 958,546 | 14.3 | % | |||||||||||||||||
| Fintech | 901,502 | 12.5 | % | 1,646,600 | 20.9 | % | 680,487 | 10.1 | % | |||||||||||||||||
| Direct lease financing | 670,902 | 9.3 | % | 678,740 | 8.6 | % | 698,086 | 10.4 | % | |||||||||||||||||
| Advisor financing | 240,049 | 3.3 | % | 270,811 | 3.4 | % | 272,155 | 4.0 | % | |||||||||||||||||
| Other loans | 152,604 | 2.3 | % | 155,825 | 2.0 | % | 169,945 | 2.7 | % | |||||||||||||||||
| Total loans | 7,058,310 | 98.3 | % | 7,738,999 | 98.2 | % | 6,520,663 | 97.1 | % | |||||||||||||||||
| Unamortized loan fees and costs | 15,596 | 0.2 | % | 14,684 | 0.2 | % | 14,769 | 0.2 | % | |||||||||||||||||
| Loans, net of deferred fees and costs | $ | 7,073,906 | 98.5 | % | $ | 7,753,683 | 98.4 | % | $ | 6,535,432 | 97.3 | % | ||||||||||||||
| Loans, at fair value: | ||||||||||||||||||||||||||
| SBLs, at fair value | $ | 60,617 | 0.8 | % | $ | 64,530 | 0.8 | % | $ | 76,830 | 1.1 | % | ||||||||||||||
| Real estate bridge loans (non-SBA), at fair value | 53,545 | 0.7 | % | 63,730 | 0.8 | % | 108,646 | 1.6 | % | |||||||||||||||||
| Total commercial loans, at fair value | $ | 114,162 | 1.5 | % | $ | 128,260 | 1.6 | % | $ | 185,476 | 2.7 | % | ||||||||||||||
| Total loan portfolio | $ | 7,188,068 | 100.0 | % | $ | 7,881,943 | 100.0 | % | $ | 6,720,908 | 100.0 | % | ||||||||||||||
As of June 30, 2026, Loans, net of deferred fees and costs were $7.07 billion, an 8.8% decrease (not annualized) from $7.75 billion at March 31, 2026, and an 8.2% increase compared to $6.54 billion at June 30, 2025. The $679.8 million decrease in Loans, net from March 31, 2026 was primarily driven by a $745.1 million decrease in fintech loans, partially offset by a $116.6 million increase in securities-backed lines of credit (“SBLOC”) and insurance policy cash value-backed lines of credit (“IBLOC”). The decline in Fintech balance compared to prior quarter was primarily attributable to a change in payment processing timing, which impacted period-end balances and did not reflect a change in underlying customer activity. The $538.5 million increase in Loans, net from June 30, 2025 was primarily driven by growth in fintech loans of $221.0 million reflecting the continued growth in sponsored lending, and a $223.9 million increase in SBLOC/IBLOC.
Fintech loans of $901.5 million include $336.3 million from secured credit card accounts and $565.2 million from short-term liquidity products, and account for 12.5% of the total loan portfolio. Secured credit card accounts are backed by cash collateral by each individual cardholder, held on the balance sheet as non-interest earning deposits, with the loan balance required to be repaid in full monthly. Short-term liquidity products to individual borrowers range in maturity from 30 days to 365 days. All fintech loans are covered by credit enhancements, where our partners provide financial protection against consumer credit losses. We maintain cash collateral balances for our fintech partners equivalent to the expected losses on dollars already lent, as well as having the offset rights related to other revenues generated through those relationships.
Average Fintech loans were $1.39 billion, an $853.9 million increase, or 159% from 2Q 2025, and an increase of $275.7 million, or 25% (not annualized), compared to 1Q 2026.
Deposits & Liquidity
Average deposits for 2Q 2026 were $8.41 billion, a 1.2% increase (not annualized) from $8.32 billion in 1Q 2026, and a 4.4% increase from $8.06 billion in 2Q 2025. The increase from 2Q 2025 was primarily driven by continued growth in deposits sourced from our fintech relationships.
The average interest rate on deposits for 2Q 2026 was 1.63%, a 7-basis point decrease compared to 1Q 2026 and a 55-basis point decrease compared to 2Q 2025, driven by the mix of deposits and the short-term interest rate environment.
3
Our fintech partnerships generate 96% of our total deposits, and such deposits are low balance, insured deposits, and accordingly, do not constitute the same liquidity risk experienced by traditional branch deposit franchises. As of June 30, 2026, 94% of the deposits are insured, 3% are low balance accounts such as anonymous gift cards and corporate incentive cards for which there is no identified depositor, and 3% are other uninsured deposits.
As of June 30, 2026, we had $1.12 billion of off-balance sheet deposits, which consist of deposits swept to other financial institutions to manage our balance sheet composition and deposit portfolio diversity. Off-balance sheet deposits were $1.34 billion as of March 31, 2026 and $617.4 million as of June 30, 2025.
We maintain secured borrowing lines of credit with the Federal Reserve Bank and Federal Home Loan Bank that are collateralized by pledged loans and investments. As of June 30, 2026, we had $744.0 million of short-term borrowings under these facilities, which averaged $302.2 million for 2Q 2026. Based on the current amount of loans and securities pledged, there was $3.79 billion of additional available capacity.
Net Interest Income and Net Interest Margin
Net interest income was $90.5 million for 2Q 2026, compared to $88.8 million for 1Q 2026 and $97.5 million for 2Q 2025. The $1.7 million increase compared to 1Q 2026 was driven primarily by slightly higher interest earning assets. The $7.0 million decrease compared to 2Q 2025 was driven by $2.7 million higher interest cost from senior debt issuance in 3Q 2025, given the higher rate and upsizing, a one-time gain recognized in 2Q 2025 of $3.0 million from the repayment of a CRE-2 investment security, and the remaining decrease was primarily driven by the shift of our portfolio mix to more fintech loans for which we primarily earn fee income.
Net interest margin was 3.85% for 2Q 2026, compared to 3.87% for 1Q 2026 and 4.44% for 2Q 2025. The decline from 2Q 2025 was primarily driven by the shift of our portfolio mix to more fintech loans for which we primarily earn fee income, although we recognize interest income on certain fintech loan products.
Credit Quality
Total Provision, including provision for fintech loans that are supported by credit enhancements, was $26.1 million in 2Q 2026, a $1.5 million decrease compared to $27.6 million in 1Q 2026, and an $18.3 million decrease from $44.4 million in 2Q 2025. Provision expense for non-Fintech loans was $0.4 million in 2Q 2026, compared to a provision release of $(1.3) million in 1Q 2026 and a provision expense of $1.5 million in 2Q 2025. Provision in 2Q 2026 reflects continued improvement in performance of the Leasing, Real estate bridge lending (“REBL”) and Institutional Banking portfolios, while the provision release in 1Q 2026 was primarily driven by improvements in credit performance in our leasing portfolio. Provision for fintech loans was $25.8 million in 2Q 2026, compared to $28.8 million in 1Q 2026 and $43.2 million in 2Q 2025. The lower provision for fintech loans was primarily driven by lower charge-offs and improved credit quality.
The allowance for credit losses was $63.5 million at June 30, 2026, consisting of $30.7 million related to fintech loans, or 3.41% of fintech loans, and $32.8 million for non-fintech loans, or 0.53% of non-fintech loans. That compares to the allowance at March 31, 2026 of $63.0 million, consisting of $29.8 million for fintech, or 1.81% of fintech loans, and $33.2 million for non-fintech, or 0.54% of non-fintech loans. The fintech coverage ratio increase from 1.81% to 3.41% was driven by the previously mentioned customer payment cycle changes that meaningfully reduced the mix of secured credit cards in the total fintech portfolio. Secured credit cards have a low rate of expected loss, and the shift in fintech to more unsecured products resulted in an increase in the ending blended coverage rate. Allowance at June 30, 2025 was $59.4 million, consisting of $27.0 million related to fintech loans, or 3.97% of fintech loans, and $32.4 million allowance for non-fintech loans, or 0.55% of non-fintech loans. The decrease in fintech coverage from 3.97% at June 30, 2025 to 3.41% at June 30, 2026 primarily reflects improved performance of those loans.
Total net charge-offs for 2Q 2026, including fintech loans which are supported by credit enhancements, were $25.7 million, a decrease from $30.7 million for 1Q 2026 and a decrease from $37.8 million for 2Q 2025, resulting in ratios of total net charge-offs to average loans of 1.35%, 1.69%, and 2.30% for the respective periods (annualized). The improvement in net charge-offs was primarily driven by improved performance of the fintech portfolio. Net charge-offs for non-fintech loans were $0.9 million for 2Q 2026, compared to $0.5 million for 1Q 2026 and $1.4 million for 2Q 2025, resulting in ratios of non-fintech net charge-offs to non-fintech average loans of 0.05%, 0.03%, and 0.09% (annualized) for each of the respective periods.
Ending total criticized loans of $146.7 million at 2Q 2026 decreased 10% from $163.1 million at the end of 1Q 2026 primarily driven by a $12.9 million decrease in criticized REBL and a $4.3 million decrease in direct lease financing, partially offset by a $1.3 million increase in criticized small business loans. Ending criticized loans showed significant
4
improvement from $305.2 million at 2Q 2025, with the $158.5 million decrease primarily driven by a $169.6 million decrease in criticized REBL and an $11.1 million decrease in criticized direct lease financing, partially offset by a $21.5 million increase in criticized small business loans.
Non-Interest Income
Non-interest income for 2Q 2026 was $73.0 million, which includes $25.8 million of credit enhancement income compared to $72.5 million in 1Q 2026, which includes $28.8 million of credit enhancement income and $83.7 million in 2Q 2025 which includes $43.2 million of credit enhancement income.
Excluding credit enhancement, non-interest income for 2Q 2026 was $47.3 million, a $3.6 million increase, or 8.2% (not annualized), compared to 1Q 2026, and a $6.8 million increase, or 16.7%, compared to 2Q 2025. The $3.6 million increase compared to 1Q 2026 was primarily driven by a $2.8 million increase in total fintech fees and a $0.8 million increase in other non-interest income, primarily driven by higher other fee income from loans. The $6.8 million increase compared to 2Q 2025 reflects a $5.3 million increase in total fintech fees, driven by organic volume growth with existing partners and products, and our focus on expanding our fintech business. In addition, other non-interest income increased $2.1 million from 2Q 2025, primarily driven by $1.3 million of higher other fee income from loans and $0.7 million earned on deposit sweeps.
Non-interest income mix to total revenue, excluding credit enhancement,* was 34.3% compared to 33.0% in 1Q 2026 and 29.4% in 2Q 2025. Fintech fees as a percentage of total revenue, excluding credit enhancement,* were 29.7% compared to 28.7% in 1Q 2026 and 25.8% in 2Q 2025.
Non-Interest Expense
Total non-interest expense of $56.5 million increased $1.5 million from 1Q 2026 and decreased $0.7 million from 2Q 2025. The increase from 1Q 2026 was primarily driven by a $(2.0) million legal settlement recovery recognized in 1Q 2026. The decrease of $0.7 million from 2Q 2025 was primarily driven by $0.6 million lower legal expense. Revenue growth continues to outpace cost growth, driven by our investments in AI, repositioning our revenues towards Fintech, and the demonstrated scale of our Fintech platform.
Efficiency ratio was 41.0% for 2Q 2026, compared to 41.5% for 1Q 2026 and 41.5% for 2Q 2025.*
Income Taxes
Income tax expense was $20.3 million for 2Q 2026, $18.6 million for 1Q 2026, and $19.8 million for 2Q 2025. Our effective income tax rate was 25.1% for 2Q 2026, 23.7% for 1Q 2026, and 24.9% for 2Q 2025. The relatively lower rate for 1Q 2026 was primarily driven by vesting activity of stock awards in that period.
Capital
As of June 30, 2026, capital levels for The Bancorp Bank, N.A. (the “Bank”) continue to be strong and in excess of the “Well Capitalized” regulatory benchmarks, with Tier 1 Capital to average assets (Leverage), Tier 1 Capital to Risk-Weighted Assets, Total Capital to Risk-Weighted Assets and Common Equity Tier 1 to Risk-Weighted Assets ratios for the Bank of 9.09%, 14.27%, 15.32%, and 14.27%, respectively, and for the Company of 7.26%, 11.41%, 12.45%, and 11.41%, respectively.
Book value per common share at June 30, 2026 was $17.19, compared to $16.65 at March 31, 2026 (a 13.0% increase, annualized). Total shareholders’ equity of $705.4 million increased by $8.4 million, primarily driven by $60.7 million of net income partially offset by $50.5 million of share repurchases and excise tax.
Compared to June 30, 2025, total shareholders’ equity decreased by $154.9 million, primarily driven by $403.6 million of share repurchases partially offset by $231.9 million of net income and $19.9 million of stock-based compensation. Outstanding shares decreased 5.219 million shares since June 30, 2025, driven by share repurchases.
Outstanding shares decreased by 815,066 since March 31, 2026 to 41.043 million, driven primarily by share repurchases. During 2Q 2026, we repurchased 870,129 shares of our common stock, or 2.1% of issued and outstanding shares, at an average cost of $57.46 per share, for a total capital return of $50.0 million.
________
*See “Non-GAAP Financial Measures” section at the end of the document for detailed description.
5
About The Bancorp
The Bancorp, Inc. (NASDAQ: TBBK), through its subsidiary, The Bancorp Bank, N.A., is defining the future of banking. As one of the first banks to embrace fintech, The Bancorp has been a driving force behind the industry’s evolution, serving as an essential financial enabler of Fintech innovation for more than 25 years. Led by its Fintech Solutions business, the company delivers a dynamic portfolio of payment and lending solutions that empowers its clients to turn bold ideas into real-world success.
Ranked by the Nilson Report as the No. 1 issuer of prepaid cards in the U.S. and among the top 10 debit card issuers nationally, The Bancorp also holds leading positions in its Institutional Banking, Small Business Lending, Fleet Management Services, and Real Estate Bridge Lending businesses. Across every line of business, The Bancorp fosters prosperity through the perpetual transformation of banking and aims to drive growth for its clients, investors, employees, and the communities it serves. For more information, visit https://thebancorp.com/.
Forward-Looking Statements
Statements in this earnings release regarding The Bancorp’s business that are not historical facts are “forward-looking statements.” These statements may be identified by the use of forward-looking terminology, including, but not limited to the words “estimate,” “project,” “plan,” “believe,” “expect,” “anticipate,” “intend,” “may,” “will,” “could,” “continue,” or the negative thereof and similar terms or expressions. Forward-looking statements include, but are not limited to, statements regarding our anticipated 2026 and 2027 results, including earnings per share accretion, future growth, profitability, productivity and efficiency, the expansion, expected timelines, and implementation of our Fintech initiatives and revenue streams, the possible benefits of our platform restructuring and adoption of AI tools, and share repurchases. Such forward-looking statements relate to our current assumptions, projections, and expectations about our business and future events, including current expectations about important economic and political factors, among other factors, and are subject to risks and uncertainties, which could cause the actual results, events, or achievements to differ materially from those set forth in or implied by the forward-looking statements and related assumptions. Factors that could cause results to differ from those expressed in the forward-looking statements also include, but are not limited to the risks and uncertainties referenced or described in The Bancorp’s filings with the Securities and Exchange Commission, including the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025 and other documents that the Company files from time to time with the Securities and Exchange Commission. The forward-looking statements speak only as of the date of this press release. The Bancorp does not undertake any duty to publicly revise or update forward-looking statements in this press release to reflect events or circumstances that arise after the date of this press release, except as may be required under applicable law.
The Bancorp, Inc. Contact
Andres Viroslav, Director, Investor Relations
215-861-7990
Source: The Bancorp, Inc.
6
THE BANCORP, INC.
SUPPLEMENTAL FINANCIAL INFORMATION (Unaudited)
| CONDENSED CONSOLIDATED INCOME STATEMENTS | |||||||||||||||||||||||
| (Dollars in thousands, except share and per share data) | |||||||||||||||||||||||
| Three Months Ended June 30, | Six Months Ended June 30, | ||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||
| Net interest income | $ | 90,466 | $ | 97,492 | $ | 179,280 | $ | 189,235 | |||||||||||||||
| Provision (reversal) for credit losses on non-fintech loans | 365 | 1,494 | (983) | 2,368 | |||||||||||||||||||
| Provision for credit losses on fintech loans | 25,766 | 43,233 | 54,609 | 89,101 | |||||||||||||||||||
| Provision (reversal) for unfunded commitments | (42) | (364) | 64 | (253) | |||||||||||||||||||
| Provision for credit losses, total | 26,089 | 44,363 | 53,690 | 91,216 | |||||||||||||||||||
| Net interest income after provision for credit losses | 64,377 | 53,129 | 125,590 | 98,019 | |||||||||||||||||||
| Non-interest income: | |||||||||||||||||||||||
| Fintech fees | |||||||||||||||||||||||
| ACH, card, and other payment fees | 6,559 | 5,562 | 12,355 | 10,694 | |||||||||||||||||||
| Prepaid, debit card and related fees | 27,790 | 26,113 | 54,467 | 51,827 | |||||||||||||||||||
| Consumer credit fintech fees | 6,545 | 3,970 | 12,141 | 7,570 | |||||||||||||||||||
| Total fintech fees | 40,894 | 35,645 | 78,963 | 70,091 | |||||||||||||||||||
| Net realized and unrealized gains on commercial loans, at fair value | 130 | 344 | 136 | 705 | |||||||||||||||||||
| Leasing related income | 1,773 | 2,131 | 3,674 | 4,103 | |||||||||||||||||||
| Fintech loan credit enhancement | 25,766 | 43,233 | 54,609 | 89,101 | |||||||||||||||||||
| Other non-interest income | 4,477 | 2,390 | 8,183 | 3,385 | |||||||||||||||||||
| Total non-interest income | 73,040 | 83,743 | 145,565 | 167,385 | |||||||||||||||||||
| Non-interest expense: | |||||||||||||||||||||||
| Salaries and employee benefits | 37,426 | 37,134 | 74,903 | 70,803 | |||||||||||||||||||
| Data processing expense | 1,387 | 1,227 | 2,696 | 2,432 | |||||||||||||||||||
| Legal expense | 1,221 | 1,863 | 2,811 | 3,820 | |||||||||||||||||||
| Legal settlement (reimbursement) | — | — | (2,000) | — | |||||||||||||||||||
| FDIC insurance | 1,106 | 1,202 | 2,357 | 2,255 | |||||||||||||||||||
| Software | 5,632 | 5,144 | 11,001 | 10,157 | |||||||||||||||||||
| Other non-interest expense | 9,704 | 10,653 | 19,734 | 21,050 | |||||||||||||||||||
| Total non-interest expense | 56,476 | 57,223 | 111,502 | 110,517 | |||||||||||||||||||
| Income before income taxes | 80,941 | 79,649 | 159,653 | 154,887 | |||||||||||||||||||
| Income tax expense | 20,285 | 19,828 | 38,928 | 37,893 | |||||||||||||||||||
| Net income | $ | 60,656 | $ | 59,821 | $ | 120,725 | $ | 116,994 | |||||||||||||||
| Earnings per share - basic | $ | 1.46 | $ | 1.28 | $ | 2.89 | $ | 2.49 | |||||||||||||||
| Earnings per share - diluted | $ | 1.45 | $ | 1.27 | $ | 2.86 | $ | 2.46 | |||||||||||||||
| Weighted average shares - basic | 41,461,889 | 46,598,535 | 41,795,740 | 46,904,592 | |||||||||||||||||||
| Weighted average shares - diluted | 41,794,160 | 47,182,770 | 42,180,516 | 47,565,580 | |||||||||||||||||||
7
| CONDENSED CONSOLIDATED BALANCE SHEETS | |||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | December 31, 2025 | June 30, 2025 | ||||||||||||||||||||
| Assets: | |||||||||||||||||||||||
| Cash and cash equivalents | |||||||||||||||||||||||
| Cash and due from banks | $ | 9,527 | $ | 8,673 | $ | 8,038 | $ | 11,637 | |||||||||||||||
| Interest-earning deposits | 70,556 | 58,510 | 104,611 | 328,628 | |||||||||||||||||||
| Total cash and cash equivalents | 80,083 | 67,183 | 112,649 | 340,265 | |||||||||||||||||||
| Investment securities, available-for-sale, at fair value | 1,614,890 | 1,646,541 | 1,671,750 | 1,481,500 | |||||||||||||||||||
| Commercial loans, at fair value | 114,162 | 128,260 | 139,389 | 185,476 | |||||||||||||||||||
| Loans, net of deferred fees and costs | 7,073,906 | 7,753,683 | 7,116,676 | 6,535,432 | |||||||||||||||||||
| Allowance for credit losses | (63,495) | (63,017) | (66,200) | (59,393) | |||||||||||||||||||
| Loans, net | 7,010,411 | 7,690,666 | 7,050,476 | 6,476,039 | |||||||||||||||||||
| Stock in Federal Reserve, Federal Home Loan and Atlantic Central Bankers Banks | 50,115 | 37,785 | 25,205 | 16,250 | |||||||||||||||||||
| Accrued interest receivable | 43,342 | 41,315 | 43,090 | 40,607 | |||||||||||||||||||
| Other real estate owned | 62,011 | 60,998 | 60,695 | 66,054 | |||||||||||||||||||
| Deferred tax asset, net | 23,491 | 21,139 | 18,679 | 12,436 | |||||||||||||||||||
| Credit enhancement asset | 30,733 | 29,769 | 31,138 | 26,982 | |||||||||||||||||||
| Other | 186,739 | 175,108 | 199,354 | 193,622 | |||||||||||||||||||
| Total assets | $ | 9,215,977 | $ | 9,898,764 | $ | 9,352,425 | $ | 8,839,231 | |||||||||||||||
| Liabilities: | |||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||
| Demand and interest checking | $ | 7,353,151 | $ | 8,281,037 | $ | 7,827,037 | $ | 7,705,813 | |||||||||||||||
| Savings and money market | 123,051 | 148,988 | 338,459 | 60,122 | |||||||||||||||||||
| Total deposits | 7,476,202 | 8,430,025 | 8,165,496 | 7,765,935 | |||||||||||||||||||
| Short-term borrowings | 744,000 | 470,000 | 199,000 | — | |||||||||||||||||||
| Senior debt | 196,528 | 196,320 | 196,253 | 96,391 | |||||||||||||||||||
| Subordinated debenture | 13,401 | 13,401 | 13,401 | 13,401 | |||||||||||||||||||
| Other long-term borrowings | 4,327 | 13,626 | 13,712 | 13,898 | |||||||||||||||||||
| Other liabilities | 76,138 | 78,442 | 74,767 | 89,340 | |||||||||||||||||||
| Total liabilities | 8,510,596 | 9,201,814 | 8,662,629 | 7,978,965 | |||||||||||||||||||
| Total shareholders' equity | 705,381 | 696,950 | 689,796 | 860,266 | |||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 9,215,977 | $ | 9,898,764 | $ | 9,352,425 | $ | 8,839,231 | |||||||||||||||
8
| AVERAGE BALANCE SHEET - QTD | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Three months ended June 30, 2026 | Three months ended June 30, 2025 | ||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Rate | Average Balance | Interest | Average Rate | ||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Non-fintech loans | $ | 6,231,014 | $ | 107,634 | 6.91 | % | $ | 6,023,895 | $ | 111,702 | 7.42 | % | |||||||||||||||||||||||
| Fintech loans | 1,390,866 | 2,834 | 0.82 | % | 536,978 | 486 | 0.36 | % | |||||||||||||||||||||||||||
Loans, net of deferred fees and costs(1) | 7,621,880 | 110,468 | 5.80 | % | 6,560,873 | 112,188 | 6.84 | % | |||||||||||||||||||||||||||
Leases-bank qualified(2) | 7,028 | 146 | 8.31 | % | 7,723 | 174 | 9.01 | % | |||||||||||||||||||||||||||
| Investment securities-taxable | 1,619,710 | 19,924 | 4.92 | % | 1,462,603 | 22,393 | 6.12 | % | |||||||||||||||||||||||||||
Investment securities-nontaxable(2) | 12,648 | 197 | 6.23 | % | 8,385 | 131 | 6.25 | % | |||||||||||||||||||||||||||
| Interest-earning deposits | 155,465 | 1,386 | 3.57 | % | 756,603 | 8,326 | 4.40 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 9,416,731 | 132,121 | 5.61 | % | 8,796,187 | 143,212 | 6.51 | % | |||||||||||||||||||||||||||
| Allowance for credit losses | (55,726) | (52,444) | |||||||||||||||||||||||||||||||||
| Other assets | 342,586 | 344,627 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 9,703,591 | $ | 9,088,370 | |||||||||||||||||||||||||||||||
| Liabilities and Shareholders' Equity: | |||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
| Demand and interest checking | $ | 8,311,353 | $ | 33,400 | 1.61 | % | $ | 7,991,121 | $ | 43,402 | 2.17 | % | |||||||||||||||||||||||
| Savings and money market | 102,639 | 934 | 3.64 | % | 65,637 | 561 | 3.42 | % | |||||||||||||||||||||||||||
| Total deposits | 8,413,992 | 34,334 | 1.63 | % | 8,056,758 | 43,963 | 2.18 | % | |||||||||||||||||||||||||||
| Short-term borrowings | 302,236 | 2,949 | 3.90 | % | 439 | 5 | 4.56 | % | |||||||||||||||||||||||||||
| Long-term borrowings | 10,146 | 147 | 5.80 | % | 13,957 | 198 | 5.67 | % | |||||||||||||||||||||||||||
| Subordinated debentures | 13,401 | 236 | 7.04 | % | 13,401 | 257 | 7.67 | % | |||||||||||||||||||||||||||
| Senior debt | 196,391 | 3,917 | 7.98 | % | 96,333 | 1,233 | 5.12 | % | |||||||||||||||||||||||||||
| Total deposits and liabilities | 8,936,166 | 41,583 | 1.86 | % | 8,180,888 | 45,656 | 2.23 | % | |||||||||||||||||||||||||||
| Other liabilities | 66,260 | 62,505 | |||||||||||||||||||||||||||||||||
| Total liabilities | 9,002,426 | 8,243,393 | |||||||||||||||||||||||||||||||||
| Shareholders' equity | 701,165 | 844,977 | |||||||||||||||||||||||||||||||||
| $ | 9,703,591 | $ | 9,088,370 | ||||||||||||||||||||||||||||||||
Net interest income on tax equivalent basis(2) | $ | 90,538 | $ | 97,556 | |||||||||||||||||||||||||||||||
| Tax equivalent adjustment | 72 | 64 | |||||||||||||||||||||||||||||||||
| Net interest income | $ | 90,466 | $ | 97,492 | |||||||||||||||||||||||||||||||
Net interest margin(2) | 3.85 | % | 4.44 | % | |||||||||||||||||||||||||||||||
________
(1)Includes commercial loans, at fair value. All periods include non-accrual loans.
(2)Full taxable equivalent basis, using 21% statutory federal tax rate.
9
| AVERAGE BALANCE SHEET - YTD | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Six months ended June 30, 2026 | Six months ended June 30, 2025 | ||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Rate | Average Balance | Interest | Average Rate | ||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Non-fintech loans | $ | 6,182,243 | $ | 213,232 | 6.90 | % | $ | 5,969,155 | $ | 220,265 | 7.38 | % | |||||||||||||||||||||||
| Fintech loans | 1,253,763 | 4,660 | 0.74 | % | 502,087 | 725 | 0.29 | % | |||||||||||||||||||||||||||
Loans, net of deferred fees and costs(1) | 7,436,006 | 217,892 | 5.86 | % | 6,471,242 | 220,990 | 6.83 | % | |||||||||||||||||||||||||||
Leases-bank qualified(2) | 6,975 | 298 | 8.54 | % | 6,793 | 313 | 9.22 | % | |||||||||||||||||||||||||||
| Investment securities-taxable | 1,640,946 | 39,844 | 4.86 | % | 1,475,892 | 40,520 | 5.49 | % | |||||||||||||||||||||||||||
Investment securities-nontaxable(2) | 11,543 | 362 | 6.27 | % | 7,326 | 236 | 6.44 | % | |||||||||||||||||||||||||||
| Interest-earning deposits | 202,480 | 3,582 | 3.54 | % | 945,453 | 21,006 | 4.44 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 9,297,950 | 261,978 | 5.64 | % | 8,906,706 | 283,065 | 6.36 | % | |||||||||||||||||||||||||||
| Allowance for credit losses | (55,680) | (48,700) | |||||||||||||||||||||||||||||||||
| Other assets | 362,748 | 354,939 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 9,605,018 | $ | 9,212,945 | |||||||||||||||||||||||||||||||
| Liabilities and Shareholders' Equity: | |||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
| Demand and interest checking | $ | 8,200,639 | $ | 66,610 | 1.62 | % | $ | 8,082,390 | $ | 88,447 | 2.19 | % | |||||||||||||||||||||||
| Savings and money market | 164,954 | 3,013 | 3.65 | % | 100,966 | 1,891 | 3.75 | % | |||||||||||||||||||||||||||
| Total deposits | 8,365,593 | 69,623 | 1.66 | % | 8,183,356 | 90,338 | 2.21 | % | |||||||||||||||||||||||||||
| Short-term borrowings | 224,492 | 4,330 | 3.86 | % | 220 | 5 | 4.55 | % | |||||||||||||||||||||||||||
| Long-term borrowings | 11,907 | 344 | 5.78 | % | 14,003 | 393 | 5.61 | % | |||||||||||||||||||||||||||
| Subordinated debentures | 13,401 | 471 | 7.03 | % | 13,401 | 512 | 7.64 | % | |||||||||||||||||||||||||||
| Senior debt | 196,297 | 7,792 | 7.94 | % | 96,289 | 2,467 | 5.12 | % | |||||||||||||||||||||||||||
| Total deposits and liabilities | 8,811,690 | 82,560 | 1.87 | % | 8,307,269 | 93,715 | 2.26 | % | |||||||||||||||||||||||||||
| Other liabilities | 95,739 | 80,651 | |||||||||||||||||||||||||||||||||
| Total liabilities | 8,907,429 | 8,387,920 | |||||||||||||||||||||||||||||||||
| Shareholders' equity | 697,589 | 825,025 | |||||||||||||||||||||||||||||||||
| $ | 9,605,018 | $ | 9,212,945 | ||||||||||||||||||||||||||||||||
Net interest income on tax equivalent basis(2) | $ | 179,418 | $ | 189,350 | |||||||||||||||||||||||||||||||
| Tax equivalent adjustment | 138 | 115 | |||||||||||||||||||||||||||||||||
| Net interest income | $ | 179,280 | $ | 189,235 | |||||||||||||||||||||||||||||||
Net interest margin(2) | 3.86 | % | 4.25 | % | |||||||||||||||||||||||||||||||
________
(1)Includes commercial loans, at fair value. All periods include non-accrual loans.
(2)Full taxable equivalent basis, using 21% statutory federal tax rate.
10
| BUSINESS LINE QUARTERLY SUMMARY - AVERAGE QTD | |||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||||||||
| Average Balance | Average Rate (2) | Average Balance | Average Rate (2) | Average Balance | Average Rate (2) | ||||||||||||||||||||||||||||||||||||
Total Loan Portfolio (1) | |||||||||||||||||||||||||||||||||||||||||
| Credit Solutions: | |||||||||||||||||||||||||||||||||||||||||
| Real estate bridge loans - amortized cost | $ | 2,226,725 | 7.88% | $ | 2,203,082 | 7.99% | $ | 2,178,842 | 8.78% | ||||||||||||||||||||||||||||||||
| Real estate bridge loans - fair value | 58,085 | 6.96% | 66,399 | 6.79% | 119,746 | 7.52% | |||||||||||||||||||||||||||||||||||
| SBLOC/IBLOC and Advisor financing | 2,034,126 | 5.74% | 1,957,376 | 5.77% | 1,857,293 | 6.28% | |||||||||||||||||||||||||||||||||||
| Small business lending | 1,075,471 | 7.26% | 1,057,893 | 7.20% | 1,007,394 | 7.41% | |||||||||||||||||||||||||||||||||||
| Direct lease financing | 675,230 | 8.02% | 681,629 | 8.13% | 706,326 | 8.20% | |||||||||||||||||||||||||||||||||||
| Other loans | 152,964 | 5.11% | 158,114 | 5.22% | 148,282 | 5.50% | |||||||||||||||||||||||||||||||||||
| Unamortized loan fees and costs | 15,441 | — | 15,357 | — | 13,735 | — | |||||||||||||||||||||||||||||||||||
| Total Credit Solutions | 6,238,042 | 6.99% | 6,139,850 | 7.06% | 6,031,618 | 7.59% | |||||||||||||||||||||||||||||||||||
| Sponsored Lending: | |||||||||||||||||||||||||||||||||||||||||
| Fintech loans | 1,390,866 | 0.82% | 1,115,138 | 0.65% | 536,978 | 0.36% | |||||||||||||||||||||||||||||||||||
| Total loan portfolio | $ | 7,628,908 | 5.81% | $ | 7,254,988 | 6.01% | $ | 6,568,596 | 6.86% | ||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||
| Fintech | $ | 8,085,670 | 1.63% | $ | 7,775,692 | 1.64% | $ | 7,761,241 | 2.21% | ||||||||||||||||||||||||||||||||
| Non-fintech | 328,322 | 1.76% | 540,965 | 2.57% | 295,517 | 1.56% | |||||||||||||||||||||||||||||||||||
| Total deposits | $ | 8,413,992 | 1.63% | $ | 8,316,657 | 1.70% | $ | 8,056,758 | 2.18% | ||||||||||||||||||||||||||||||||
______________
(1)Total loan portfolio includes both loans recorded at amortized cost and loans at fair value.
(2)Rates are average annualized rates.
(3)Income related to non-interest-bearing loans is included in non-interest income.
11
| PORTFOLIO PERFORMANCE | ||||||||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||
| Credit Quality | ||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | ||||||||||||||||||
| As of period end: | ||||||||||||||||||||
Nonperforming loans to total loans(1) | 1.05 | % | 0.97 | % | 0.96 | % | ||||||||||||||
| Nonperforming assets to total assets | 1.48 | % | 1.37 | % | 1.45 | % | ||||||||||||||
Allowance for credit losses to loans outstanding:(1) | ||||||||||||||||||||
| Fintech | 3.41 | % | 1.81 | % | 3.97 | % | ||||||||||||||
| Non-fintech | 0.53 | % | 0.54 | % | 0.55 | % | ||||||||||||||
| Total | 0.90 | % | 0.81 | % | 0.91 | % | ||||||||||||||
| Allowance for credit losses to total assets | 0.69 | % | 0.64 | % | 0.67 | % | ||||||||||||||
| For the three months ended: | ||||||||||||||||||||
| Net charge-offs: | ||||||||||||||||||||
| Fintech | $ | 24,802 | $ | 30,211 | $ | 36,450 | ||||||||||||||
| Non-fintech | 851 | 467 | 1,381 | |||||||||||||||||
| Total | $ | 25,653 | $ | 30,678 | $ | 37,831 | ||||||||||||||
| Net charge-offs/average loans (annualized) | 1.35 | % | 1.69 | % | 2.30 | % | ||||||||||||||
| Net charge-offs/average assets (annualized) | 1.06 | % | 1.29 | % | 1.67 | % | ||||||||||||||
_____________
(1) Excludes loans recorded at fair value.
Loan Delinquency and Non-Accrual
| June 30, 2026 | |||||||||||||||||||||||||||||||||||||||||
| Past Due | |||||||||||||||||||||||||||||||||||||||||
| 30-59 days past due | 60-89 days past due | 90+ days still accruing | Non-accrual | Total past due | Current | Total loans | |||||||||||||||||||||||||||||||||||
| Real estate bridge loans | $ | — | $ | — | $ | — | $ | 22,454 | $ | 22,454 | $ | 2,211,234 | $ | 2,233,688 | |||||||||||||||||||||||||||
| SBLOC / IBLOC | 3,222 | 119 | — | — | 3,341 | 1,821,960 | 1,825,301 | ||||||||||||||||||||||||||||||||||
| Small business loans | 1,892 | — | — | 40,284 | 42,176 | 992,088 | 1,034,264 | ||||||||||||||||||||||||||||||||||
| Fintech | 22,956 | 4,087 | 1,798 | — | 28,841 | 872,661 | 901,502 | ||||||||||||||||||||||||||||||||||
| Direct lease financing | 1,642 | 165 | 506 | 9,120 | 11,433 | 659,469 | 670,902 | ||||||||||||||||||||||||||||||||||
| Advisor financing | — | — | — | — | — | 240,049 | 240,049 | ||||||||||||||||||||||||||||||||||
| Other loans | 431 | — | 1 | 390 | 822 | 151,782 | 152,604 | ||||||||||||||||||||||||||||||||||
| Total loans | $ | 30,143 | $ | 4,371 | $ | 2,305 | $ | 72,248 | $ | 109,067 | $ | 6,949,243 | $ | 7,058,310 | |||||||||||||||||||||||||||
| CAPITAL RATIOS | ||||||||||||||||||||||||||
| June 30, 2026 | ||||||||||||||||||||||||||
| The Bancorp, Inc. | The Bancorp Bank, N.A. | “Well Capitalized"(1) | ||||||||||||||||||||||||
| Tier 1 capital to average assets | 7.26 | % | 9.09 | % | 5.00 | % | ||||||||||||||||||||
| Tier 1 capital to risk-weighted assets | 11.41 | % | 14.27 | % | 8.00 | % | ||||||||||||||||||||
| Total capital to risk-weighted assets | 12.45 | % | 15.32 | % | 10.00 | % | ||||||||||||||||||||
| Common equity Tier 1 to risk-weighted assets | 11.41 | % | 14.27 | % | 6.50 | % | ||||||||||||||||||||
(1)“Well Capitalized” institution under federal regulations Basel III.
12
NON-GAAP FINANCIAL MEASURES | ||
We use certain financial measures which are not calculated and presented in accordance with U.S. generally accepted accounting principles (“GAAP”). These measures are focused on adjusting certain metrics used to measure our performance to exclude the impact of Non-interest income-Fintech loan credit enhancement. That income amount relates to credit enhancement agreements from third parties that cover losses from borrowers for fintech loans receivable. We recognize provision expense for credit losses on fintech loans and separately record an amount in Non-interest income—Fintech loan credit enhancement for the recovery from the third party. The measurement of the estimated credit losses and the estimated recovery from the credit enhancement are based on the same estimate and correlate to like amounts in our statement of operations. Our non-GAAP metrics are calculated to remove the volatility of that credit enhancement recovery from measures used to review the performance and growth of our business.
Non-GAAP measures include:
Efficiency ratio is calculated as: (i) GAAP total non-interest expense; divided by (ii) the total of GAAP Net interest income and Non-interest income less Fintech loan credit enhancement income, or “Adjusted total revenue.” This ratio compares revenues generated with the amount of expense required to generate such revenues and may be used as one measure of overall efficiency.
Total revenue, excluding credit enhancement, is calculated as: the total of GAAP Net interest income and Non-interest income less Fintech loan credit enhancement income. This figure adjusts our total revenue for amounts received related to credit enhancement agreements, to remove the volatility of that credit enhancement recovery when measuring our revenue results.
Non-interest income, excluding credit enhancement, is calculated as: GAAP Non-interest-income less Fintech loan credit enhancement income. This figure adjusts our non-interest income for amounts received related to credit enhancement agreements, to remove the volatility of that credit enhancement recovery when measuring our non-interest income results.
Non-interest income as a percentage of total revenue (excluding credit enhancement) is calculated as: (i) GAAP Non-interest-income less Fintech loan credit enhancement income; divided by (ii) Adjusted total revenue. This ratio is used to compare the amount of non-interest income, which is primarily fee-based, to our total revenue each period to review the growth in our fee-based business.
Fintech fees as a percentage of total revenue (excluding credit enhancement) is calculated as: (i) GAAP Non-interest income – Total fintech fees; divided by (ii) Adjusted total revenue. This ratio is used to compare the amount of fintech fee revenue to our total revenue each period to review the growth in that revenue area, which is one of our key areas of focus.
We believe that these non-GAAP measures are useful performance metrics for management, investors, and lenders, because they provide a means to evaluate period-to-period comparisons of the Company's financial performance without the effects of certain adjustments in accordance with GAAP that may not necessarily be indicative of current operating performance. Non-GAAP financial measures should not be considered as an alternative to GAAP financial measures. They may not be indicative of the historical operating results of the Company nor are they intended to be predictive of potential future results. Investors should not consider non-GAAP financial measures in isolation or as a substitute for performance measures calculated in accordance with GAAP.
Reconciliation of Non-GAAP Measures:
| (Dollars in thousands) | Three months ended | Six months ended | |||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | June 30, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||
| Net interest income | $ | 90,466 | $ | 88,814 | $ | 97,492 | $ | 179,280 | $ | 189,235 | |||||||||||||||||||||||||
| Non-interest income | A | 73,040 | 72,525 | 83,743 | 145,565 | 167,385 | |||||||||||||||||||||||||||||
| Total revenue | B | 163,506 | 161,339 | 181,235 | 324,845 | 356,620 | |||||||||||||||||||||||||||||
| Less: Fintech loan credit enhancement | (25,766) | $ | (28,843) | (43,233) | (54,609) | (89,101) | |||||||||||||||||||||||||||||
| Adjusted total revenue | C | $ | 137,740 | $ | 132,496 | $ | 138,002 | $ | 270,236 | $ | 267,519 | ||||||||||||||||||||||||
| Non-interest income | $ | 73,040 | $ | 72,525 | $ | 83,743 | $ | 145,565 | $ | 167,385 | |||||||||||||||||||||||||
| Less: Fintech loan credit enhancement | (25,766) | (28,843) | (43,233) | (54,609) | (89,101) | ||||||||||||||||||||||||||||||
| Adjusted non-interest income | D | $ | 47,274 | $ | 43,682 | $ | 40,510 | $ | 90,956 | $ | 78,284 | ||||||||||||||||||||||||
| Non-interest expense | E | $ | 56,476 | $ | 55,026 | $ | 57,223 | $ | 111,502 | $ | 110,517 | ||||||||||||||||||||||||
| Non-interest income - total fintech fees | F | $ | 40,894 | $ | 38,069 | $ | 35,645 | $ | 78,963 | $ | 70,091 | ||||||||||||||||||||||||
| Non-GAAP Measures | |||||||||||||||||||||||||||||||||||
| Efficiency ratio | E/C | 41.0 | % | 41.5 | % | 41.5 | % | 41.3 | % | 41.3 | % | ||||||||||||||||||||||||
| Total revenue, excluding credit enhancement | C | $ | 137,740 | $ | 132,496 | $ | 138,002 | $ | 270,236 | $ | 267,519 | ||||||||||||||||||||||||
| Non-interest income, excluding credit enhancement | D | $ | 47,274 | $ | 43,682 | $ | 40,510 | 90,956 | $ | 78,284 | |||||||||||||||||||||||||
| Non-interest income as a percentage of total revenue | A/B | 44.7 | % | 45.0 | % | 46.2 | % | 44.8 | % | 46.9 | % | ||||||||||||||||||||||||
| Non-interest income as a percentage of total revenue (excluding credit enhancement) | D/C | 34.3 | % | 33.0 | % | 29.4 | % | 33.7 | % | 29.3 | % | ||||||||||||||||||||||||
| Fintech fees as a percentage of total revenue | F/B | 25.0 | % | 23.6 | % | 19.7 | % | 24.3 | % | 19.7 | % | ||||||||||||||||||||||||
| Fintech fees as a percentage of total revenue (excluding credit enhancement income) | F/C | 29.7 | % | 28.7 | % | 25.8 | % | 29.2 | % | 26.2 | % | ||||||||||||||||||||||||
13
The Bancorp Investor Presentation July 2026
Forward Looking Statements & Other Disclosures © The Bancorp | Investor Presentation, July 2026 2 Statements in this presentation regarding The Bancorp, Inc.’s (“The Bancorp”) business, that are not historical facts are “forward-looking statements.” These statements may be identified by the use of forward-looking terminology, including, but not limited to the words “estimate,” “project,” “plan,” “believe,” “expect,” “anticipate,” “intend,” “may,” “will,” “could,” “continue” or the negative thereof and similar terms or expressions. Forward-looking statements include, but are not limited to, statements regarding our anticipated 2026 and 2027 results, including earnings per share accretion, future growth, profitability, productivity and efficiency, the expansion, expected timelines, and implementation of our Fintech initiatives and revenue streams, the possible benefits of our platform restructuring and adoption of AI tools, and share repurchases. These forward-looking statements relate to our current assumptions, projections, and expectations about our business and future events, including current expectations about important economic and political factors, among other factors, and are subject to risks and uncertainties, which could cause the actual results, events, or achievements to differ materially from those set forth in or implied by the forward-looking statements and related assumptions. Factors that could cause results to differ from those expressed in the forward-looking statements also include, but are not limited to, the risks and uncertainties referenced or described in The Bancorp’s filings with the Securities and Exchange Commission, including the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections of the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2025, and other documents that the Company files from time to time with the Securities and Exchange Commission. The Bancorp does not undertake any duty to publicly revise or update forward-looking statements in this presentation to reflect events or circumstances that arise after the date of this presentation., except as may be required under applicable law. This presentation contains information regarding financial results that is calculated and presented on the basis of methodologies other than in accordance with accounting principles generally accepted in the United States (“GAAP”), such as those identified in the Appendix. Any non-GAAP financial measures used in this presentation are in addition to, and should not be considered superior to, or a substitute for, financial statements prepared in accordance with GAAP. Non-GAAP financial measures are subject to significant inherent limitations. The non-GAAP measures presented herein may not be comparable to similar non-GAAP measures presented by other companies. This presentation includes market, industry and economic data that was obtained from various publicly available sources and other sources believed by the Company to be true. Although the Company believes it to be reliable, the Company has not independently verified any of the data from third party sources referred to in this presentation or analyzed or verified the underlying reports relied upon or referred to by such sources, or ascertained the underlying economic and other assumptions relied upon by such sources. The Company believes that its market, industry, and economic data is accurate and that its estimates and assumptions are reasonable, but there can be no assurance as to the accuracy or completeness thereof. Past performance is not indicative nor a guarantee of future results. Copies of the documents filed by The Bancorp with the SEC are available free of charge from the website of the SEC at www.sec.gov as well as on The Bancorp’s website at www.thebancorp.com..
Company Overview 3 We are defining the future of banking. Through our dynamic portfolio of payment, lending and platform solutions, we help propel our clients’ success, while delivering value to the investors we serve, the communities where we operate and the employees who enable our mutual success. Our Vision Fostering prosperity through the perpetual transformation of banking #1 U.S. Issuer of Prepaid cards #6 Debit and prepaid issuer volume Latest Nilson1 rankings: 1) Nilson Report, April 2026 © The Bancorp | Investor Presentation, July 2026 Fintech Solutions Credit Solutions
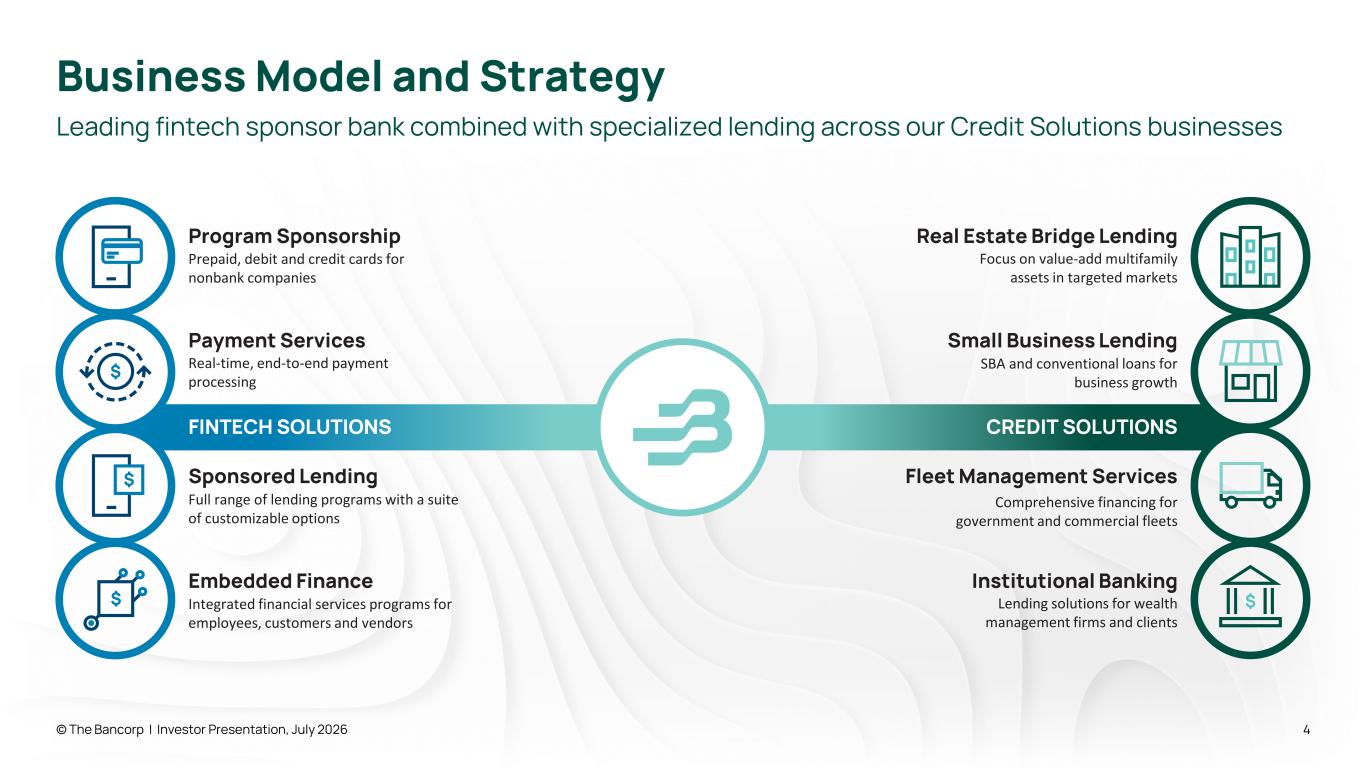
Business Model and Strategy © The Bancorp | Investor Presentation, July 2026 4 Leading fintech sponsor bank combined with specialized lending across our Credit Solutions businesses Real Estate Bridge Lending Focus on value-add multifamily assets in targeted markets Small Business Lending SBA and conventional loans for business growth Fleet Management Services Comprehensive financing for government and commercial fleets Institutional Banking Lending solutions for wealth management firms and clients Sponsored Lending Full range of lending programs with a suite of customizable options CREDIT SOLUTIONSFINTECH SOLUTIONS Payment Services Real-time, end-to-end payment processing Program Sponsorship Prepaid, debit and credit cards for nonbank companies Embedded Finance Integrated financial services programs for employees, customers and vendors
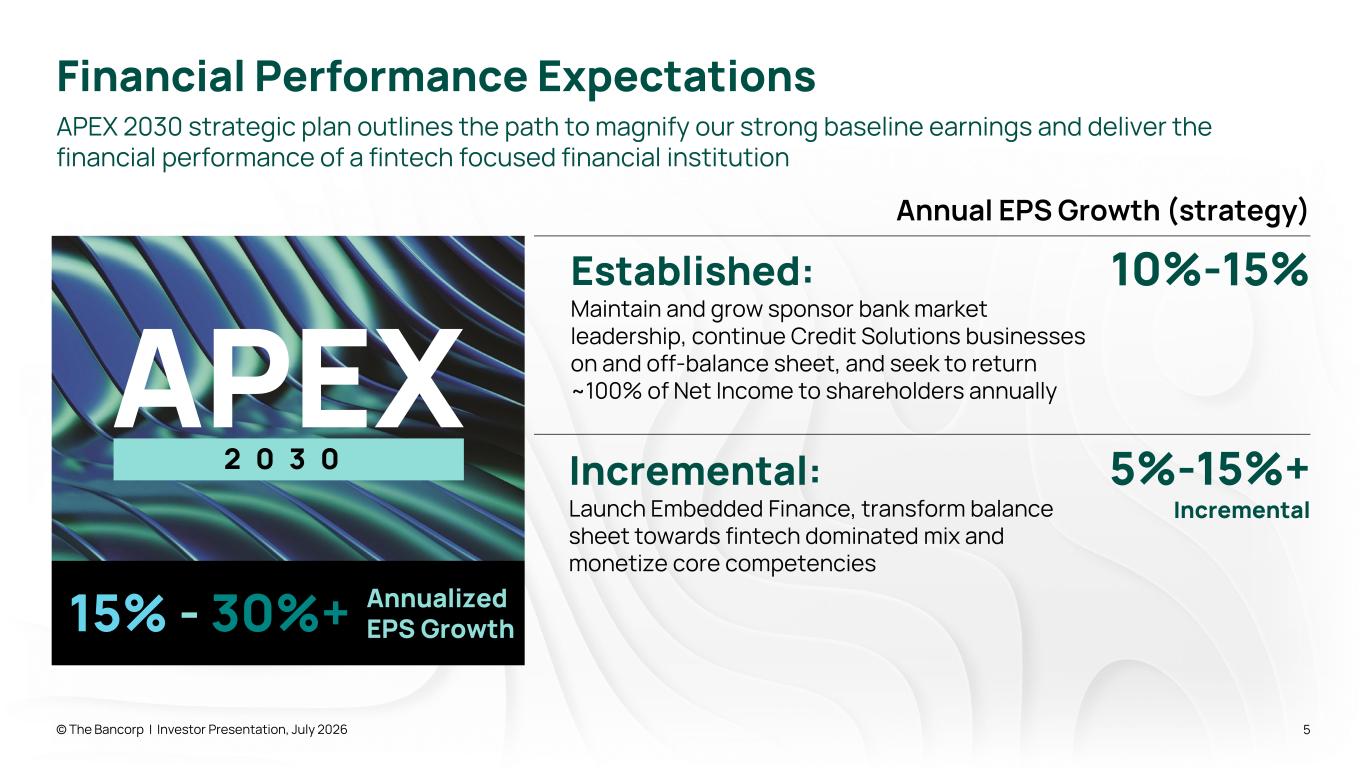
© The Bancorp | Investor Presentation, July 2026 5 Established: Maintain and grow sponsor bank market leadership, continue Credit Solutions businesses on and off-balance sheet, and seek to return ~100% of Net Income to shareholders annually Incremental: Launch Embedded Finance, transform balance sheet towards fintech dominated mix and monetize core competencies Annual EPS Growth (strategy) 10%-15% 5%-15%+ Incremental APEX 2 0 3 0 15% - 30%+ Annualized EPS Growth Financial Performance Expectations APEX 2030 strategic plan outlines the path to magnify our strong baseline earnings and deliver the financial performance of a fintech focused financial institution
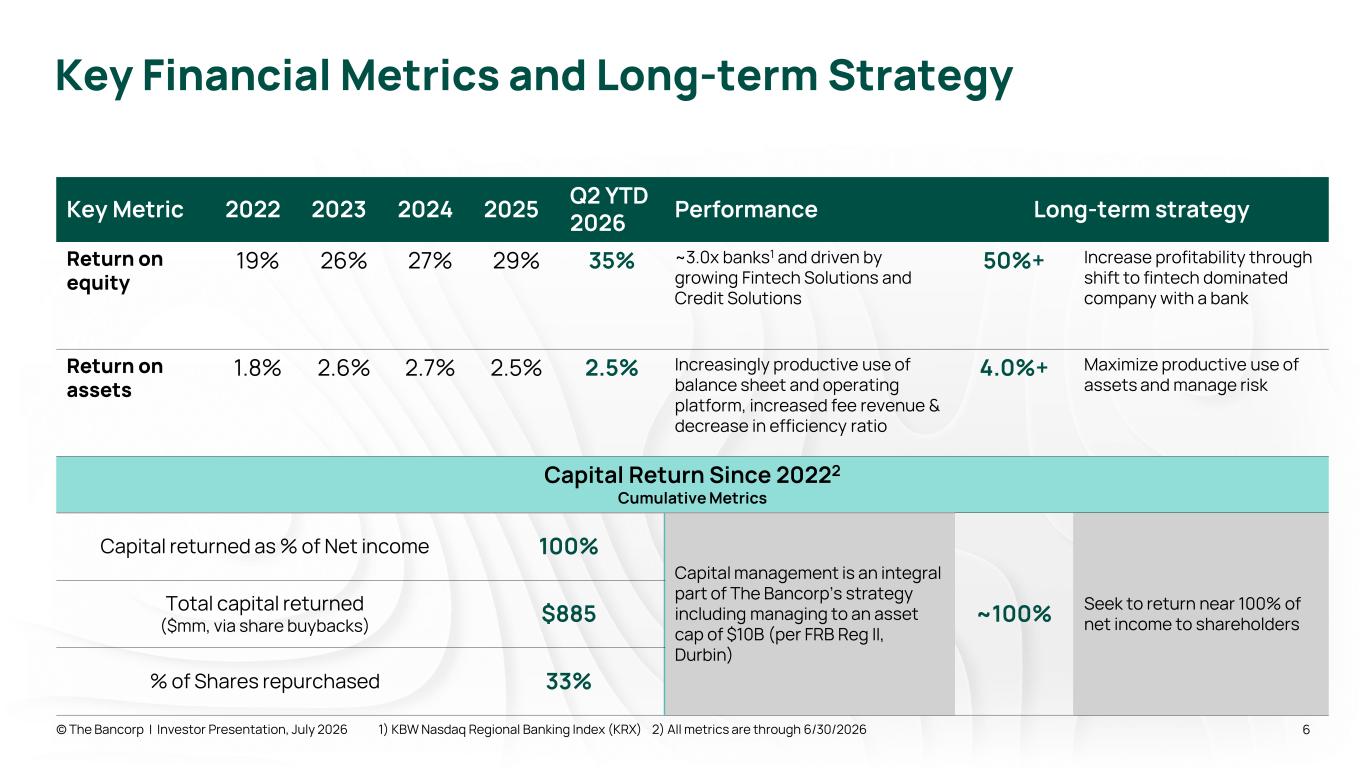
Key Financial Metrics and Long-term Strategy © The Bancorp | Investor Presentation, July 2026 6 Key Metric 2022 2023 2024 2025 Q2 YTD 2026 Performance Long-term strategy Return on equity 19% 26% 27% 29% 35% ~3.0x banks1 and driven by growing Fintech Solutions and Credit Solutions 50%+ Increase profitability through shift to fintech dominated company with a bank Return on assets 1.8% 2.6% 2.7% 2.5% 2.5% Increasingly productive use of balance sheet and operating platform, increased fee revenue & decrease in efficiency ratio 4.0%+ Maximize productive use of assets and manage risk Capital Return Since 20222 Cumulative Metrics Capital returned as % of Net income 100% Capital management is an integral part of The Bancorp’s strategy including managing to an asset cap of $10B (per FRB Reg II, Durbin) ~100% Seek to return near 100% of net income to shareholders Total capital returned ($mm, via share buybacks) $885 % of Shares repurchased 33% 1) KBW Nasdaq Regional Banking Index (KRX) 2) All metrics are through 6/30/2026
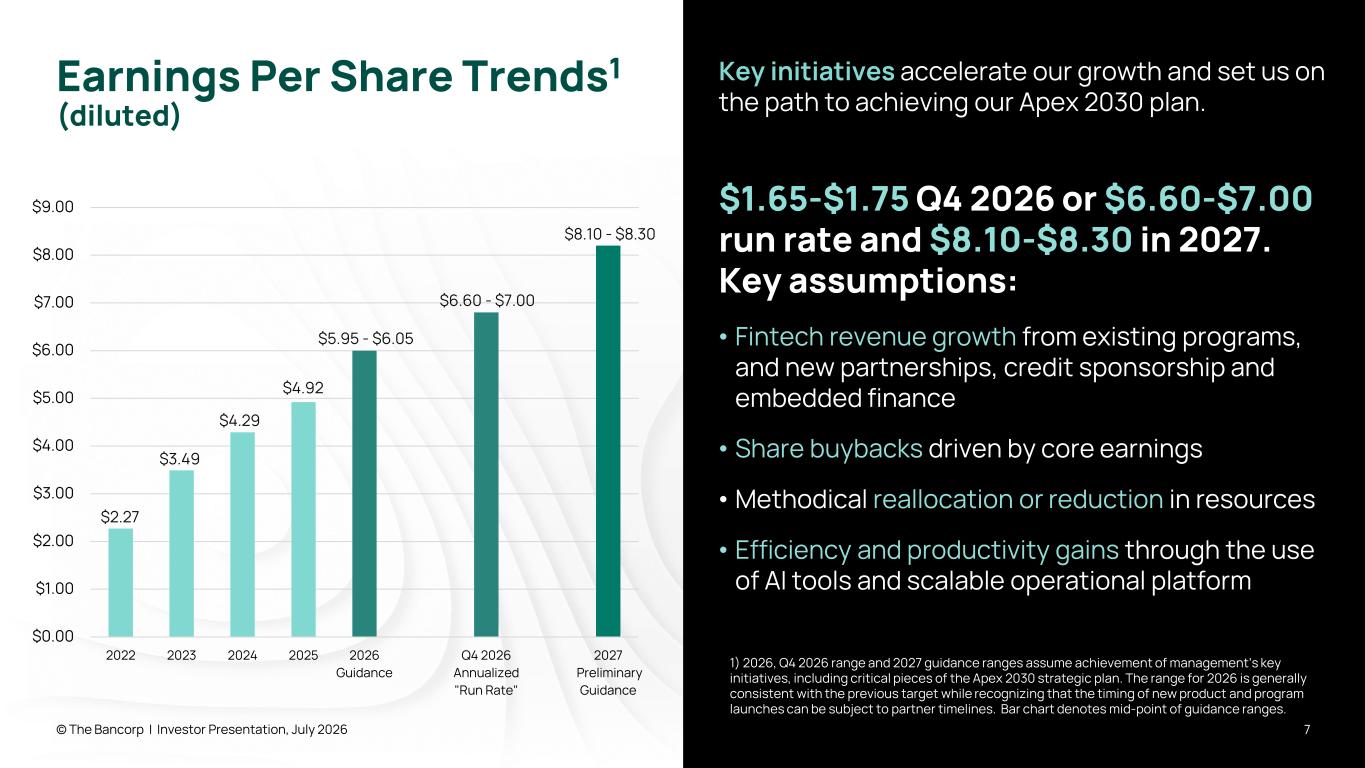
$0.00 $1.00 $2.00 $3.00 $4.00 $5.00 $6.00 $7.00 $8.00 $9.00 2022 2023 2024 2025 2026 Guidance Q4 2026 Annualized "Run Rate" 2027 Preliminary Guidance Earnings Per Share Trends1 (diluted) 7 Key initiatives accelerate our growth and set us on the path to achieving our Apex 2030 plan. $1.65-$1.75 Q4 2026 or $6.60-$7.00 run rate and $8.10-$8.30 in 2027. Key assumptions: • Fintech revenue growth from existing programs, and new partnerships, credit sponsorship and embedded finance • Share buybacks driven by core earnings • Methodical reallocation or reduction in resources • Efficiency and productivity gains through the use of AI tools and scalable operational platform $5.95 - $6.05 $6.60 - $7.00 $8.10 - $8.30 © The Bancorp | Investor Presentation, July 2026 1) 2026, Q4 2026 range and 2027 guidance ranges assume achievement of management’s key initiatives, including critical pieces of the Apex 2030 strategic plan. The range for 2026 is generally consistent with the previous target while recognizing that the timing of new product and program launches can be subject to partner timelines. Bar chart denotes mid-point of guidance ranges. $2.27 $3.49 $4.29 $4.92
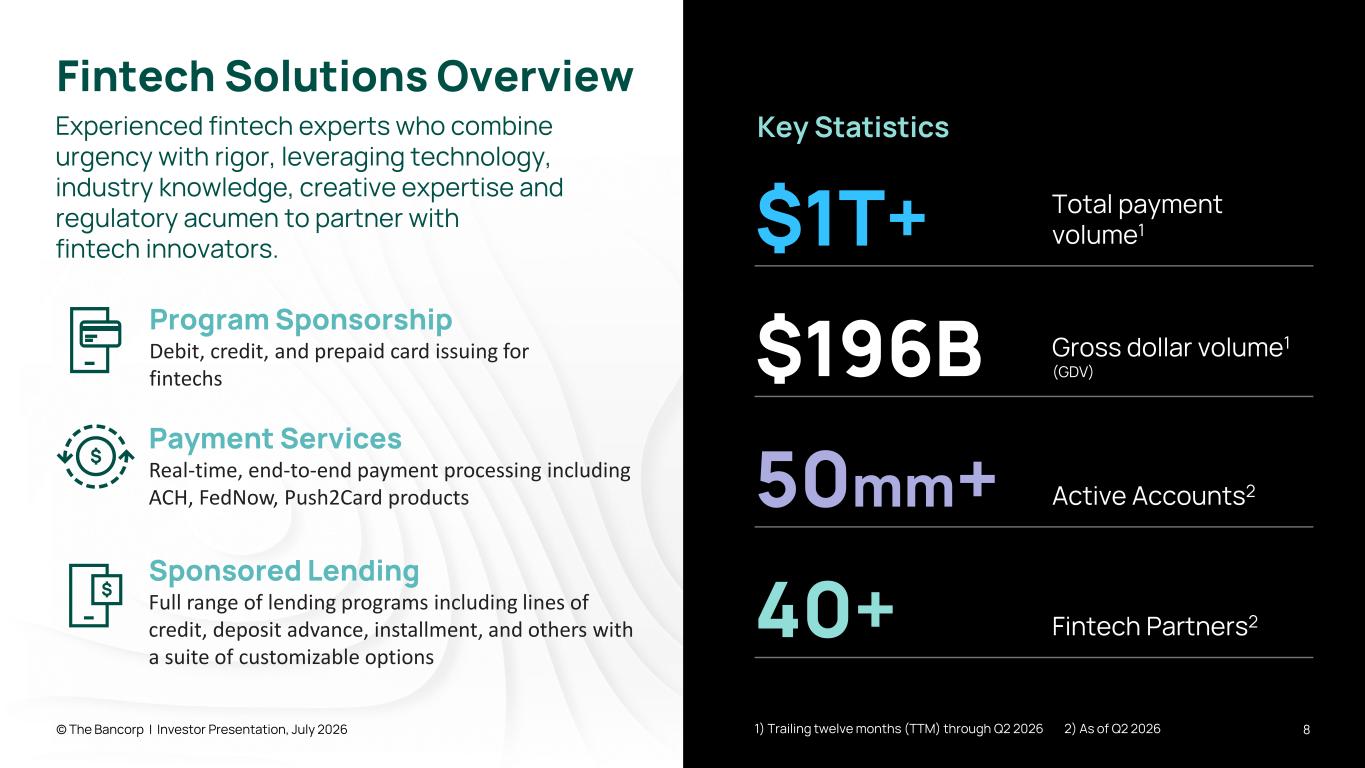
Fintech Solutions Overview © The Bancorp | Investor Presentation, July 2026 8 Key Statistics $1T+ Total payment volume1 $196B Gross dollar volume1 (GDV) 50mm+ Active Accounts2 40+ Fintech Partners2 1) Trailing twelve months (TTM) through Q2 2026 2) As of Q2 2026 Program Sponsorship Debit, credit, and prepaid card issuing for fintechs Sponsored Lending Full range of lending programs including lines of credit, deposit advance, installment, and others with a suite of customizable options Payment Services Real-time, end-to-end payment processing including ACH, FedNow, Push2Card products Experienced fintech experts who combine urgency with rigor, leveraging technology, industry knowledge, creative expertise and regulatory acumen to partner with fintech innovators.
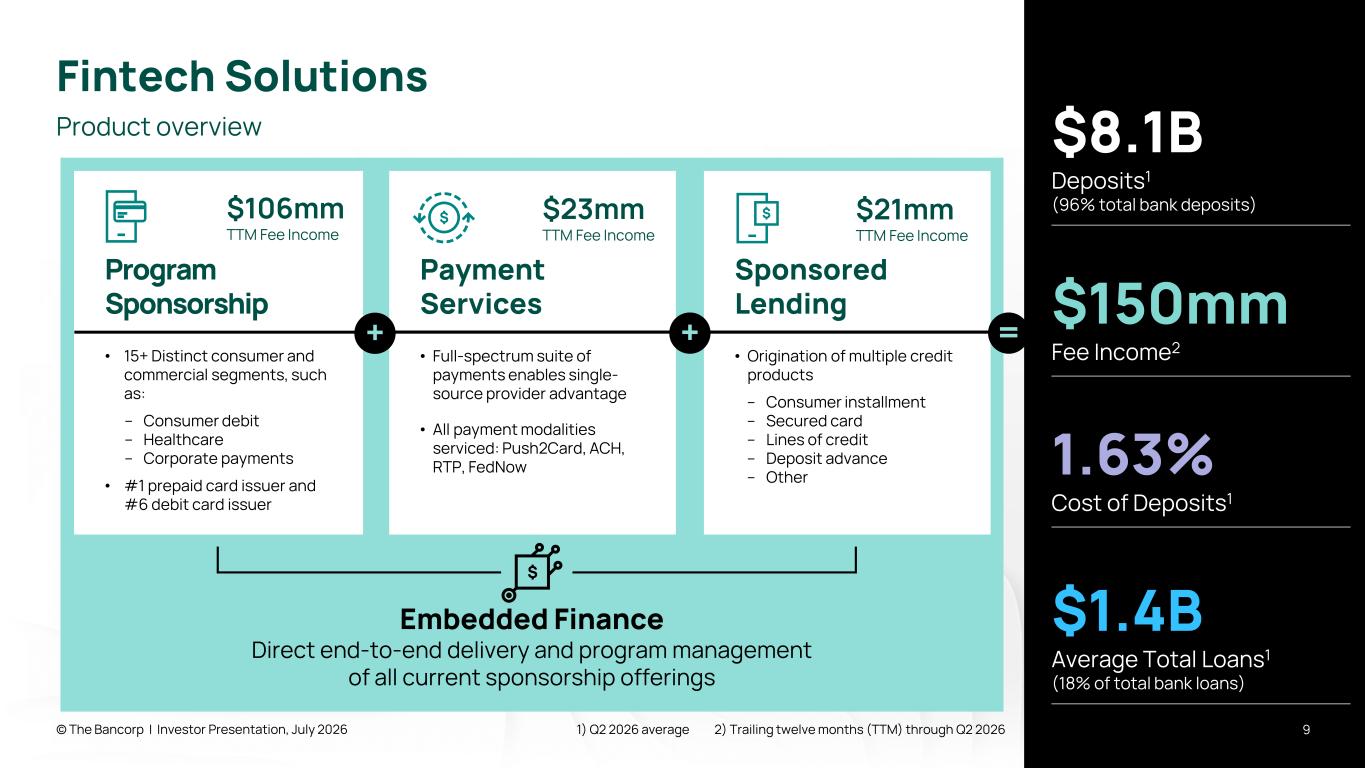
Embedded Finance Direct end-to-end delivery and program management of all current sponsorship offerings Fintech Solutions © The Bancorp | Investor Presentation, July 2026 9 Product overview $8.1B Deposits1 (96% total bank deposits) $150mm Fee Income2 1.63% Cost of Deposits1 $1.4B Average Total Loans1 (18% of total bank loans) Sponsored Lending • Origination of multiple credit products – Consumer installment – Secured card – Lines of credit – Deposit advance – Other $21mm TTM Fee Income 1) Q2 2026 average 2) Trailing twelve months (TTM) through Q2 2026 Payment Services • Full-spectrum suite of payments enables single- source provider advantage • All payment modalities serviced: Push2Card, ACH, RTP, FedNow $23mm TTM Fee Income Program Sponsorship • 15+ Distinct consumer and commercial segments, such as: – Consumer debit – Healthcare – Corporate payments • #1 prepaid card issuer and #6 debit card issuer $106mm TTM Fee Income + =+
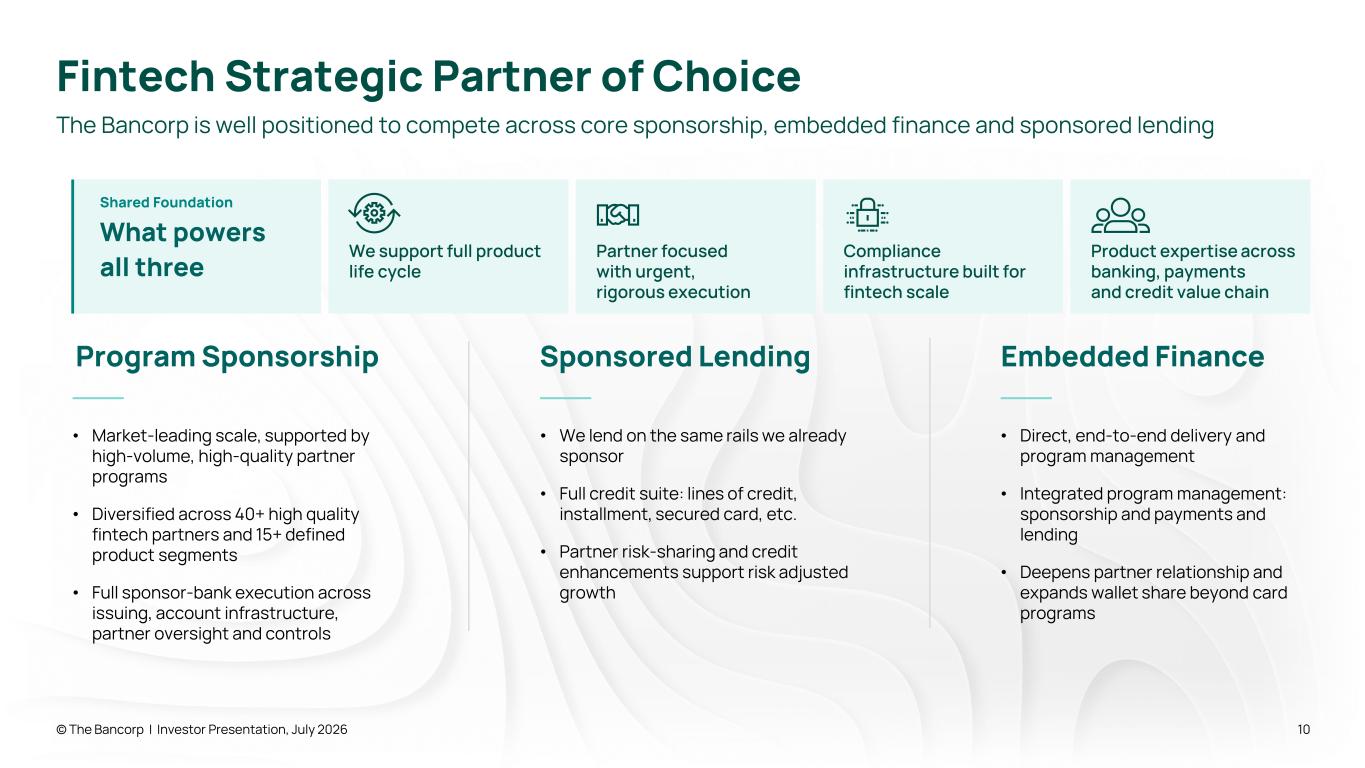
Fintech Strategic Partner of Choice © The Bancorp | Investor Presentation, July 2026 10 The Bancorp is well positioned to compete across core sponsorship, embedded finance and sponsored lending Shared Foundation What powers all three Program Sponsorship • Market-leading scale, supported by high-volume, high-quality partner programs • Diversified across 40+ high quality fintech partners and 15+ defined product segments • Full sponsor-bank execution across issuing, account infrastructure, partner oversight and controls Sponsored Lending • We lend on the same rails we already sponsor • Full credit suite: lines of credit, installment, secured card, etc. • Partner risk-sharing and credit enhancements support risk adjusted growth Embedded Finance • Direct, end-to-end delivery and program management • Integrated program management: sponsorship and payments and lending • Deepens partner relationship and expands wallet share beyond card programs We support full product life cycle Partner focused with urgent, rigorous execution Compliance infrastructure built for fintech scale Product expertise across banking, payments and credit value chain
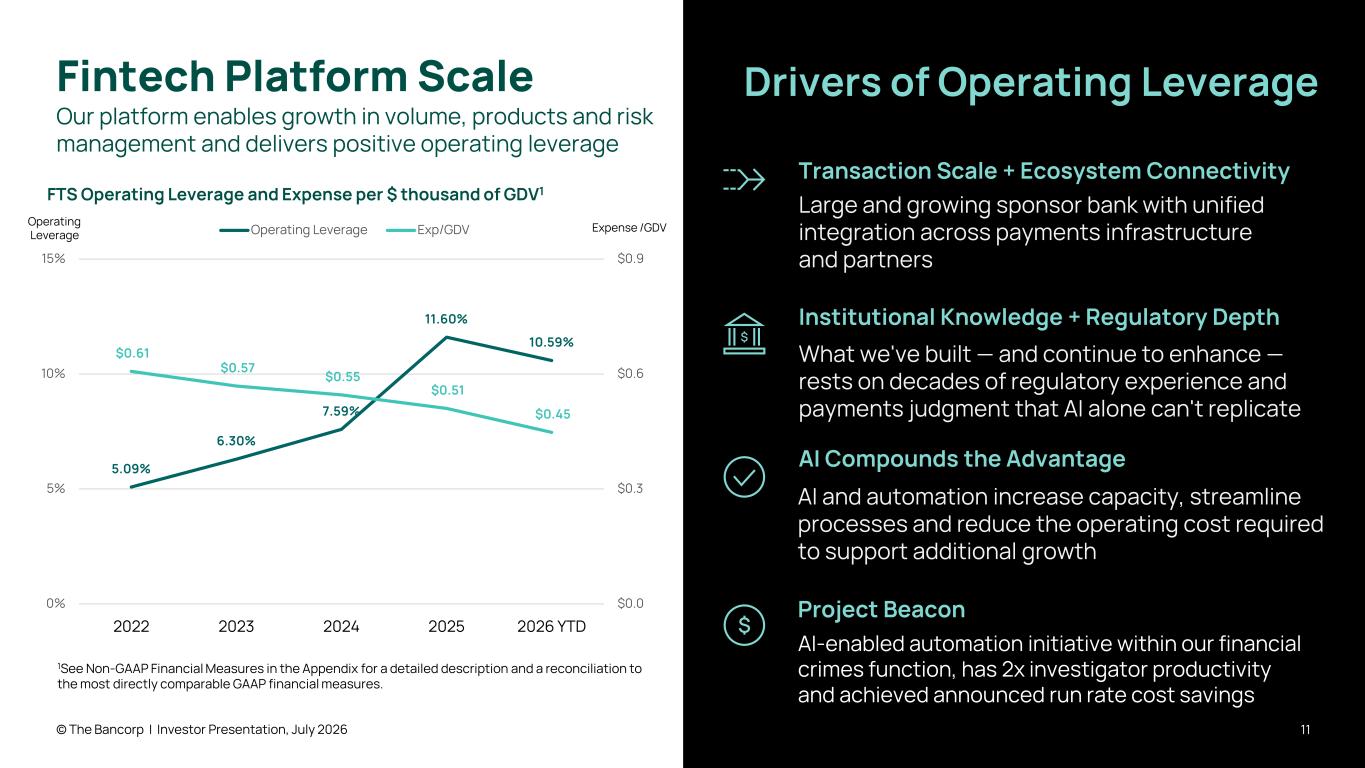
Fintech Platform Scale © The Bancorp | Investor Presentation, July 2026 11 Our platform enables growth in volume, products and risk management and delivers positive operating leverage Drivers of Operating Leverage Transaction Scale + Ecosystem Connectivity Large and growing sponsor bank with unified integration across payments infrastructure and partners AI Compounds the Advantage What we've built — and continue to enhance — rests on decades of regulatory experience and payments judgment that AI alone can't replicate Institutional Knowledge + Regulatory Depth AI and automation increase capacity, streamline processes and reduce the operating cost required to support additional growth 1See Non-GAAP Financial Measures in the Appendix for a detailed description and a reconciliation to the most directly comparable GAAP financial measures. Project Beacon AI-enabled automation initiative within our financial crimes function, has 2x investigator productivity and achieved announced run rate cost savings FTS Operating Leverage and Expense per $ thousand of GDV1 Operating Leverage Expense /GDV 5.09% 6.30% 7.59% 11.60% 10.59% $0.61 $0.57 $0.55 $0.51 $0.45 $0.0 $0.3 $0.6 $0.9 0% 5% 10% 15% 2022 2023 2024 2025 2026 YTD Operating Leverage Exp/GDV
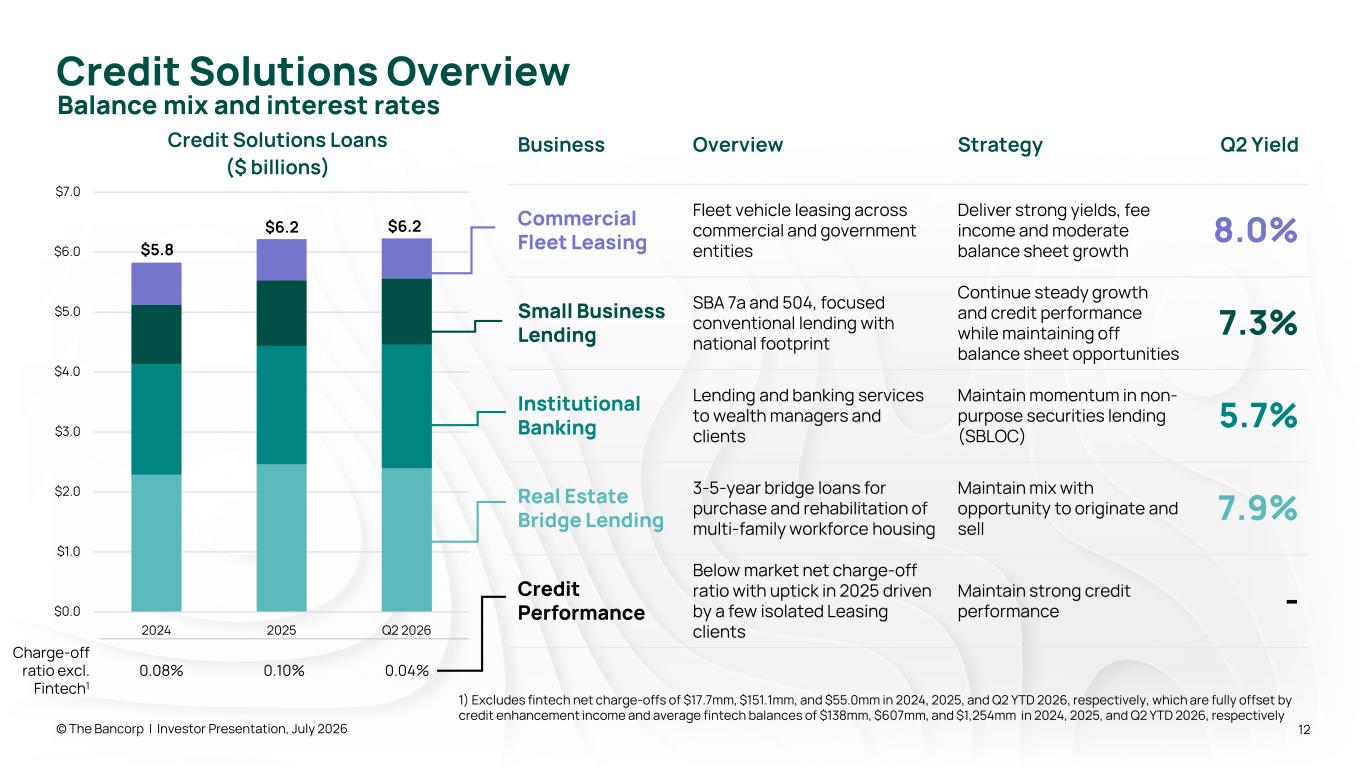
$0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 2024 2025 Q2 2026 Credit Solutions Loans ($ billions) © The Bancorp | Investor Presentation, July 2026 12 Business Overview Strategy Q2 Yield Commercial Fleet Leasing Fleet vehicle leasing across commercial and government entities Deliver strong yields, fee income and moderate balance sheet growth 8.0% Small Business Lending SBA 7a and 504, focused conventional lending with national footprint Continue steady growth and credit performance while maintaining off balance sheet opportunities 7.3% Institutional Banking Lending and banking services to wealth managers and clients Maintain momentum in non- purpose securities lending (SBLOC) 5.7% Real Estate Bridge Lending 3-5-year bridge loans for purchase and rehabilitation of multi-family workforce housing Maintain mix with opportunity to originate and sell 7.9% Credit Performance Below market net charge-off ratio with uptick in 2025 driven by a few isolated Leasing clients Maintain strong credit performance - Charge-off ratio excl. Fintech1 0.08% 0.10% 0.04% Balance mix and interest rates Credit Solutions Overview $6.2$6.2 $5.8 1) Excludes fintech net charge-offs of $17.7mm, $151.1mm, and $55.0mm in 2024, 2025, and Q2 YTD 2026, respectively, which are fully offset by credit enhancement income and average fintech balances of $138mm, $607mm, and $1,254mm in 2024, 2025, and Q2 YTD 2026, respectively
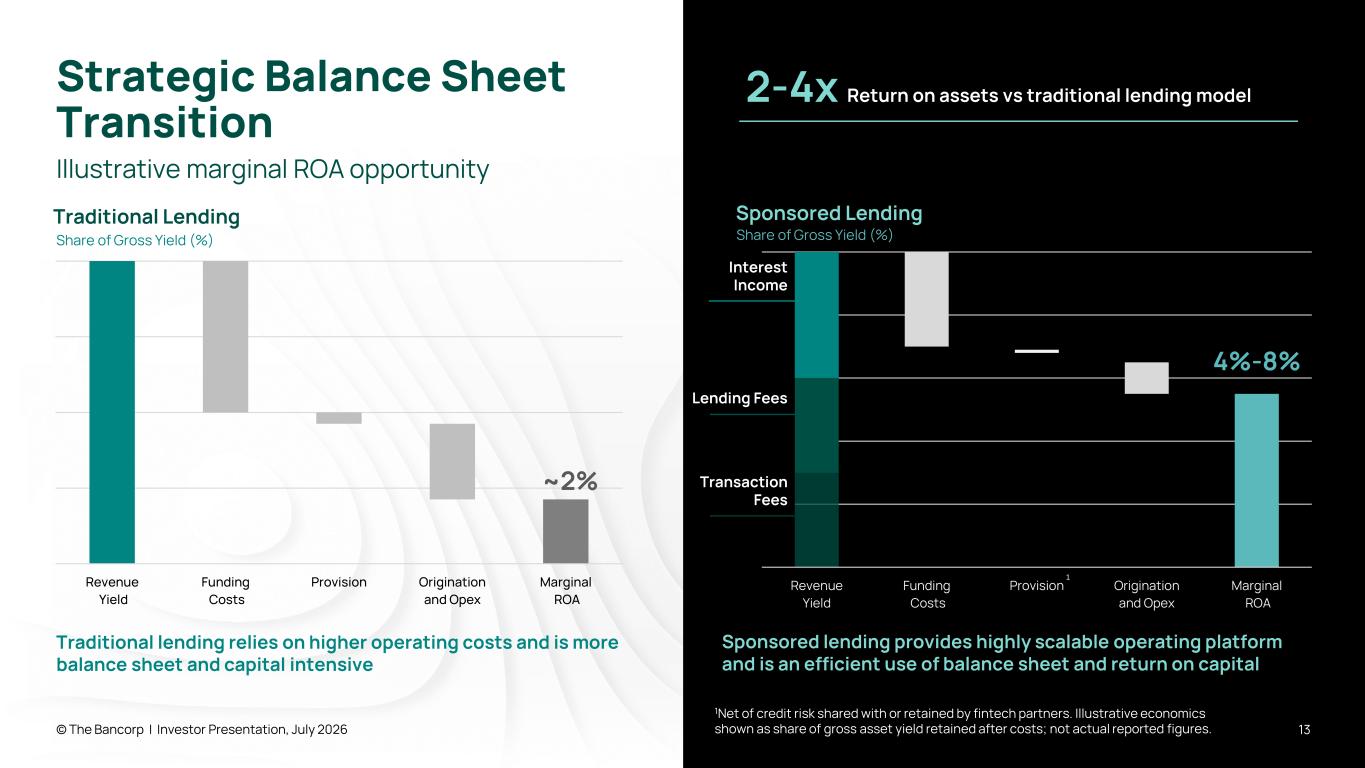
Revenue Yield Funding Costs Provision Origination and Opex Marginal ROA Sponsored Lending Strategic Balance Sheet Transition © The Bancorp | Investor Presentation, July 2026 13 Illustrative marginal ROA opportunity Revenue Yield Funding Costs Provision Origination and Opex Marginal ROA Traditional Lending Share of Gross Yield (%) 4%-8% Share of Gross Yield (%) ~2% Traditional lending relies on higher operating costs and is more balance sheet and capital intensive Sponsored lending provides highly scalable operating platform and is an efficient use of balance sheet and return on capital 1Net of credit risk shared with or retained by fintech partners. Illustrative economics shown as share of gross asset yield retained after costs; not actual reported figures. 1 2-4x Return on assets vs traditional lending model Lending Fees Interest Income Transaction Fees
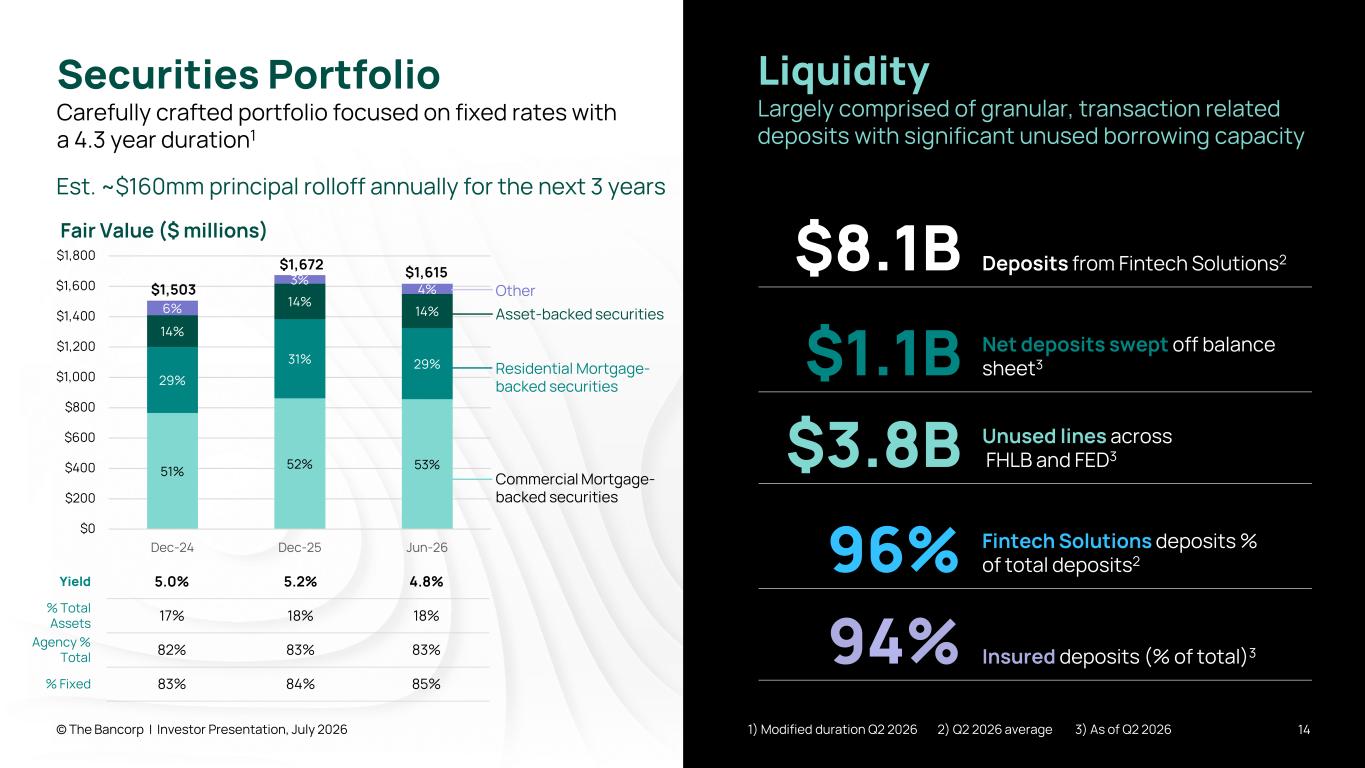
51% 52% 53% 29% 31% 29% 14% 14% 14%6% 3% 4% $0 $200 $400 $600 $800 $1,000 $1,200 $1,400 $1,600 $1,800 Dec-24 Dec-25 Jun-26 Fair Value ($ millions) © The Bancorp | Investor Presentation, July 2026 14 Securities Portfolio Carefully crafted portfolio focused on fixed rates with a 4.3 year duration1 Yield 5.0% 5.2% 4.8% % Total Assets 17% 18% 18% Agency % Total 82% 83% 83% % Fixed 83% 84% 85% Commercial Mortgage- backed securities Other Residential Mortgage- backed securities Asset-backed securities Liquidity Largely comprised of granular, transaction related deposits with significant unused borrowing capacity $8.1B Deposits from Fintech Solutions2 $1.1B Net deposits swept off balance sheet3 $3.8B Unused lines across FHLB and FED3 96% Fintech Solutions deposits % of total deposits2 94% Insured deposits (% of total)3 1) Modified duration Q2 2026 2) Q2 2026 average 3) As of Q2 2026 Est. ~$160mm principal rolloff annually for the next 3 years $1,615$1,672 $1,503
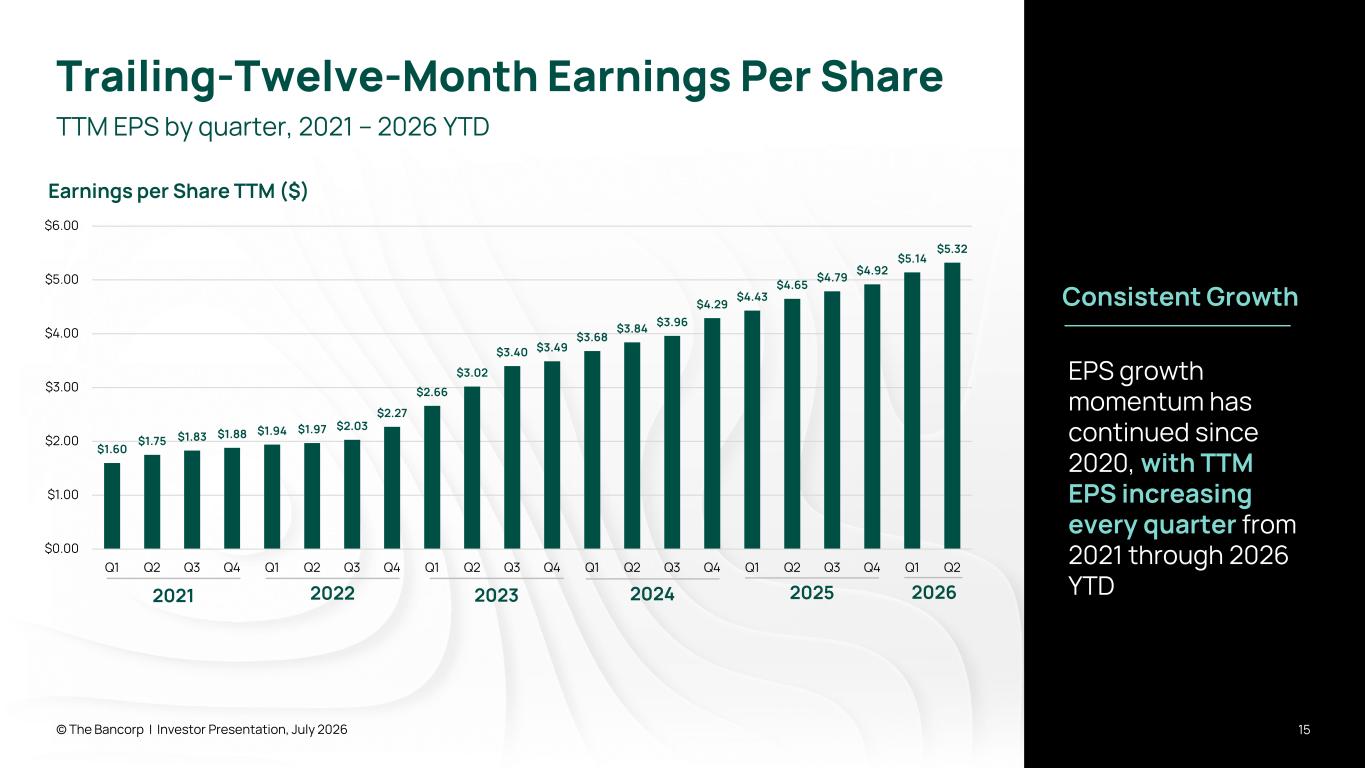
Trailing-Twelve-Month Earnings Per Share © The Bancorp | Investor Presentation, July 2026 15 TTM EPS by quarter, 2021 – 2026 YTD 2023 2024 202520222021 2026 EPS growth momentum has continued since 2020, with TTM EPS increasing every quarter from 2021 through 2026 YTD $1.60 $1.75 $1.83 $1.88 $1.94 $1.97 $2.03 $2.27 $2.66 $3.02 $3.40 $3.49 $3.68 $3.84 $3.96 $4.29 $4.43 $4.65 $4.79 $4.92 $5.14 $5.32 $0.00 $1.00 $2.00 $3.00 $4.00 $5.00 $6.00 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Earnings per Share TTM ($) Consistent Growth
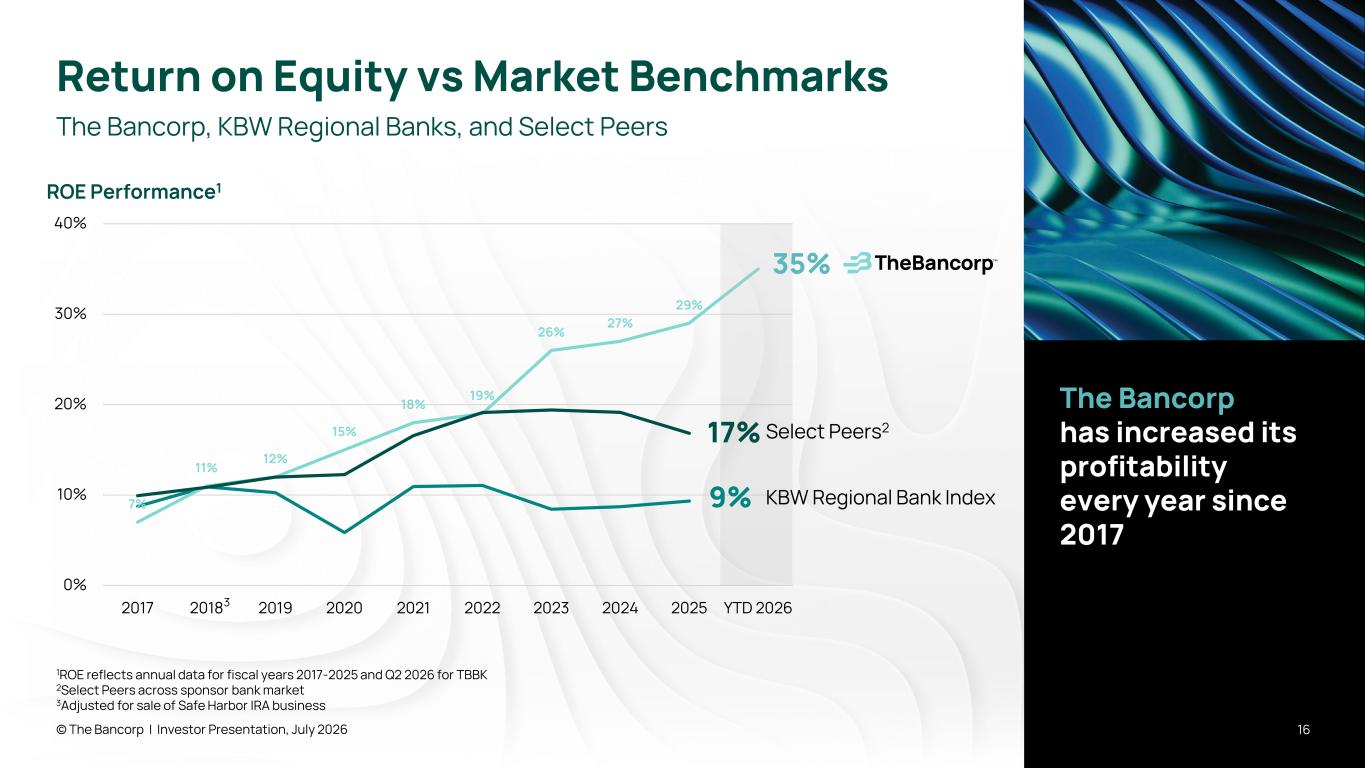
7% 11% 12% 15% 18% 19% 26% 27% 29% 0% 10% 20% 30% 40% 2017 2018 2019 2020 2021 2022 2023 2024 2025 YTD 2026 ROE Performance1 Return on Equity vs Market Benchmarks © The Bancorp | Investor Presentation, July 2026 16 The Bancorp, KBW Regional Banks, and Select Peers 3 35% KBW Regional Bank Index 17% Select Peers2 1ROE reflects annual data for fiscal years 2017-2025 and Q2 2026 for TBBK 2Select Peers across sponsor bank market 3Adjusted for sale of Safe Harbor IRA business The Bancorp has increased its profitability every year since 2017 9%
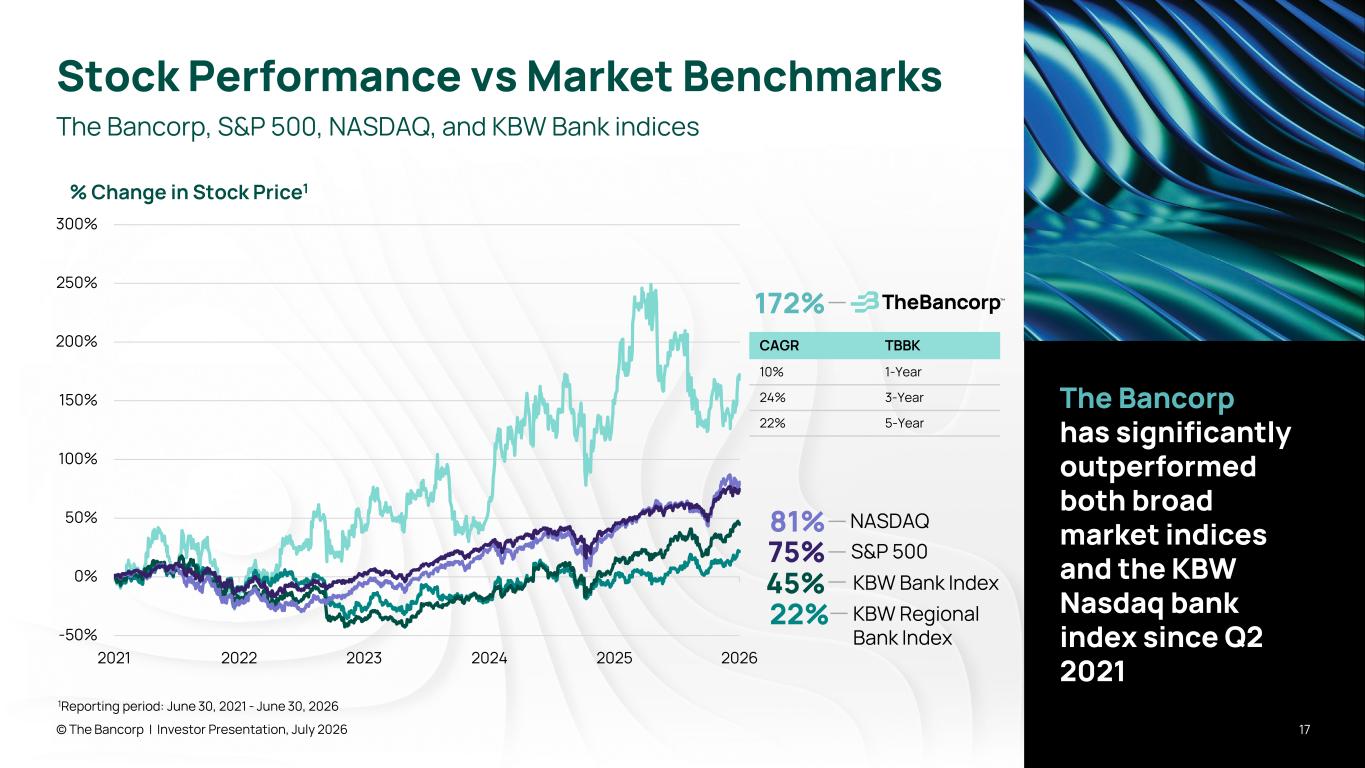
Stock Performance vs Market Benchmarks © The Bancorp | Investor Presentation, July 2026 17 The Bancorp, S&P 500, NASDAQ, and KBW Bank indices The Bancorp has significantly outperformed both broad market indices and the KBW Nasdaq bank index since Q2 2021 172% 75% 45% S&P 500 KBW Bank Index 81% NASDAQ CAGR TBBK 10% 1-Year 24% 3-Year 22% 5-Year KBW Regional Bank Index 22% 1Reporting period: June 30, 2021 - June 30, 2026 -50% 0% 50% 100% 150% 200% 250% 300% 2021 2022 2023 2024 2025 2026 % Change in Stock Price1
Appendix © The Bancorp | Investor Presentation, July 2026 18
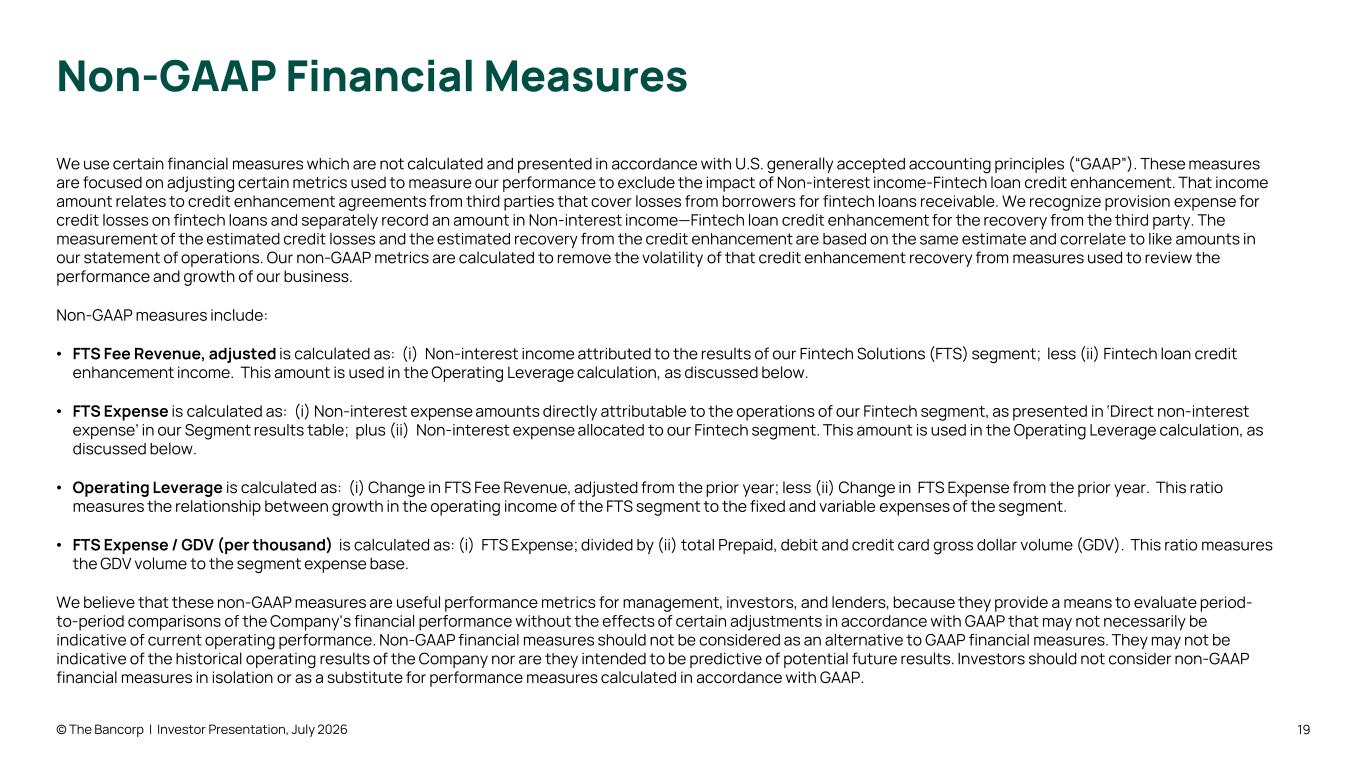
Non-GAAP Financial Measures We use certain financial measures which are not calculated and presented in accordance with U.S. generally accepted accounting principles (“GAAP”). These measures are focused on adjusting certain metrics used to measure our performance to exclude the impact of Non-interest income-Fintech loan credit enhancement. That income amount relates to credit enhancement agreements from third parties that cover losses from borrowers for fintech loans receivable. We recognize provision expense for credit losses on fintech loans and separately record an amount in Non-interest income—Fintech loan credit enhancement for the recovery from the third party. The measurement of the estimated credit losses and the estimated recovery from the credit enhancement are based on the same estimate and correlate to like amounts in our statement of operations. Our non-GAAP metrics are calculated to remove the volatility of that credit enhancement recovery from measures used to review the performance and growth of our business. Non-GAAP measures include: • FTS Fee Revenue, adjusted is calculated as: (i) Non-interest income attributed to the results of our Fintech Solutions (FTS) segment; less (ii) Fintech loan credit enhancement income. This amount is used in the Operating Leverage calculation, as discussed below. • FTS Expense is calculated as: (i) Non-interest expense amounts directly attributable to the operations of our Fintech segment, as presented in ‘Direct non-interest expense’ in our Segment results table; plus (ii) Non-interest expense allocated to our Fintech segment. This amount is used in the Operating Leverage calculation, as discussed below. • Operating Leverage is calculated as: (i) Change in FTS Fee Revenue, adjusted from the prior year; less (ii) Change in FTS Expense from the prior year. This ratio measures the relationship between growth in the operating income of the FTS segment to the fixed and variable expenses of the segment. • FTS Expense / GDV (per thousand) is calculated as: (i) FTS Expense; divided by (ii) total Prepaid, debit and credit card gross dollar volume (GDV). This ratio measures the GDV volume to the segment expense base. We believe that these non-GAAP measures are useful performance metrics for management, investors, and lenders, because they provide a means to evaluate period- to-period comparisons of the Company's financial performance without the effects of certain adjustments in accordance with GAAP that may not necessarily be indicative of current operating performance. Non-GAAP financial measures should not be considered as an alternative to GAAP financial measures. They may not be indicative of the historical operating results of the Company nor are they intended to be predictive of potential future results. Investors should not consider non-GAAP financial measures in isolation or as a substitute for performance measures calculated in accordance with GAAP. © The Bancorp | Investor Presentation, July 2026 19
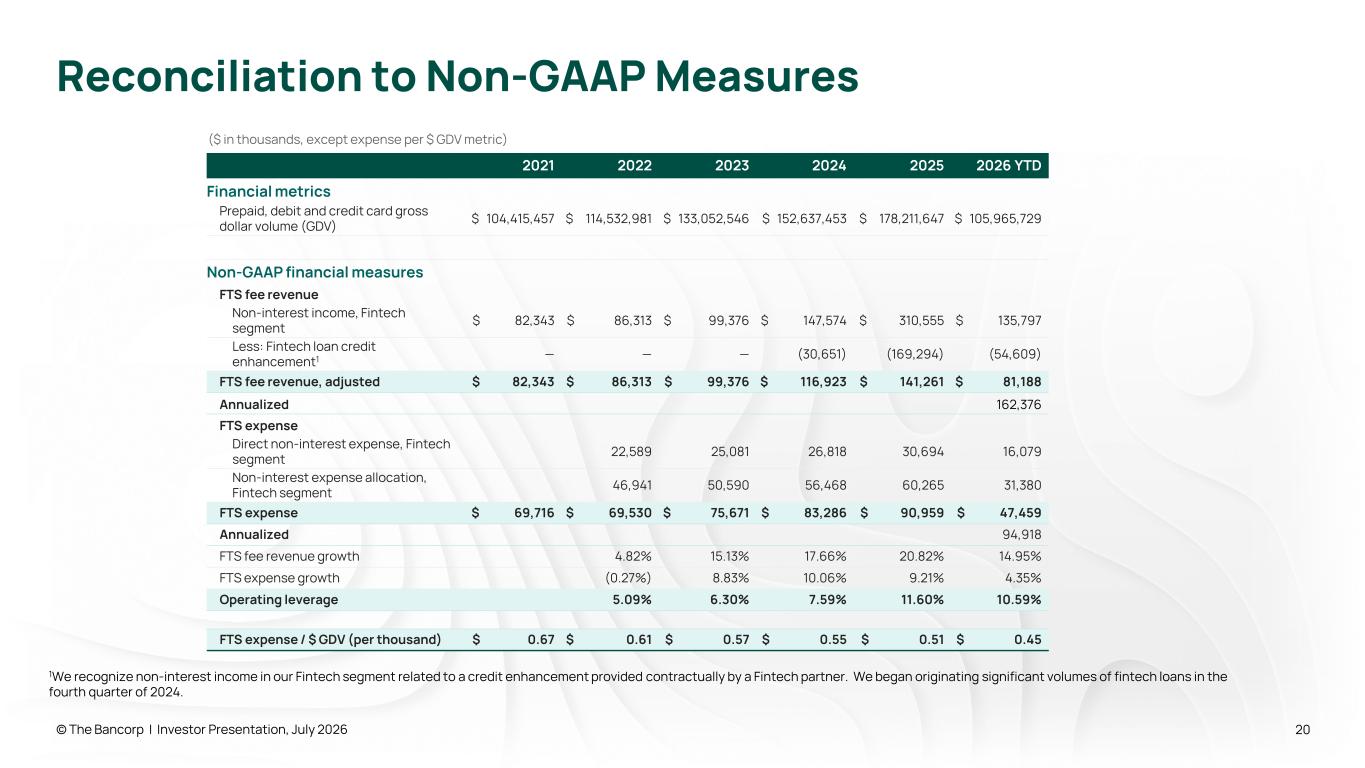
Reconciliation to Non-GAAP Measures © The Bancorp | Investor Presentation, July 2026 2021 2022 2023 2024 2025 2026 YTD Financial metrics Prepaid, debit and credit card gross dollar volume (GDV) $ 104,415,457 $ 114,532,981 $ 133,052,546 $ 152,637,453 $ 178,211,647 $ 105,965,729 Non-GAAP financial measures FTS fee revenue Non-interest income, Fintech segment $ 82,343 $ 86,313 $ 99,376 $ 147,574 $ 310,555 $ 135,797 Less: Fintech loan credit enhancement1 — — — (30,651) (169,294) (54,609) FTS fee revenue, adjusted $ 82,343 $ 86,313 $ 99,376 $ 116,923 $ 141,261 $ 81,188 Annualized 162,376 FTS expense Direct non-interest expense, Fintech segment 22,589 25,081 26,818 30,694 16,079 Non-interest expense allocation, Fintech segment 46,941 50,590 56,468 60,265 31,380 FTS expense $ 69,716 $ 69,530 $ 75,671 $ 83,286 $ 90,959 $ 47,459 Annualized 94,918 FTS fee revenue growth 4.82% 15.13% 17.66% 20.82% 14.95% FTS expense growth (0.27%) 8.83% 10.06% 9.21% 4.35% Operating leverage 5.09% 6.30% 7.59% 11.60% 10.59% FTS expense / $ GDV (per thousand) $ 0.67 $ 0.61 $ 0.57 $ 0.55 $ 0.51 $ 0.45 ($ in thousands, except expense per $ GDV metric) 1We recognize non-interest income in our Fintech segment related to a credit enhancement provided contractually by a Fintech partner. We began originating significant volumes of fintech loans in the fourth quarter of 2024. 20
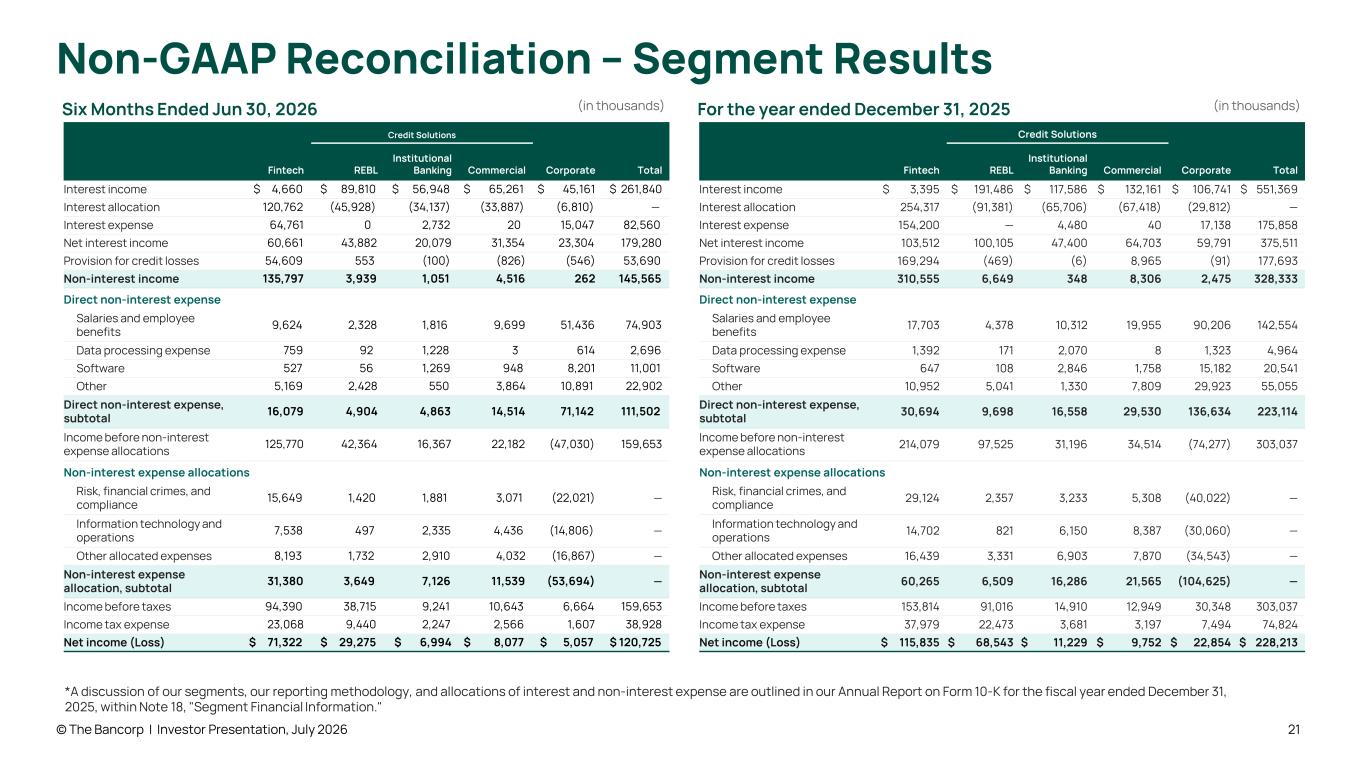
Six Months Ended Jun 30, 2026 Fintech Credit Solutions Corporate TotalREBL Institutional Banking Commercial Interest income $ 4,660 $ 89,810 $ 56,948 $ 65,261 $ 45,161 $ 261,840 Interest allocation 120,762 (45,928) (34,137) (33,887) (6,810) — Interest expense 64,761 0 2,732 20 15,047 82,560 Net interest income 60,661 43,882 20,079 31,354 23,304 179,280 Provision for credit losses 54,609 553 (100) (826) (546) 53,690 Non-interest income 135,797 3,939 1,051 4,516 262 145,565 Direct non-interest expense Salaries and employee benefits 9,624 2,328 1,816 9,699 51,436 74,903 Data processing expense 759 92 1,228 3 614 2,696 Software 527 56 1,269 948 8,201 11,001 Other 5,169 2,428 550 3,864 10,891 22,902 Direct non-interest expense, subtotal 16,079 4,904 4,863 14,514 71,142 111,502 Income before non-interest expense allocations 125,770 42,364 16,367 22,182 (47,030) 159,653 Non-interest expense allocations Risk, financial crimes, and compliance 15,649 1,420 1,881 3,071 (22,021) — Information technology and operations 7,538 497 2,335 4,436 (14,806) — Other allocated expenses 8,193 1,732 2,910 4,032 (16,867) — Non-interest expense allocation, subtotal 31,380 3,649 7,126 11,539 (53,694) — Income before taxes 94,390 38,715 9,241 10,643 6,664 159,653 Income tax expense 23,068 9,440 2,247 2,566 1,607 38,928 Net income (Loss) $ 71,322 $ 29,275 $ 6,994 $ 8,077 $ 5,057 $ 120,725 © The Bancorp | Investor Presentation, July 2026 (in thousands) For the year ended December 31, 2025 Fintech Credit Solutions Corporate TotalREBL Institutional Banking Commercial Interest income $ 3,395 $ 191,486 $ 117,586 $ 132,161 $ 106,741 $ 551,369 Interest allocation 254,317 (91,381) (65,706) (67,418) (29,812) — Interest expense 154,200 — 4,480 40 17,138 175,858 Net interest income 103,512 100,105 47,400 64,703 59,791 375,511 Provision for credit losses 169,294 (469) (6) 8,965 (91) 177,693 Non-interest income 310,555 6,649 348 8,306 2,475 328,333 Direct non-interest expense Salaries and employee benefits 17,703 4,378 10,312 19,955 90,206 142,554 Data processing expense 1,392 171 2,070 8 1,323 4,964 Software 647 108 2,846 1,758 15,182 20,541 Other 10,952 5,041 1,330 7,809 29,923 55,055 Direct non-interest expense, subtotal 30,694 9,698 16,558 29,530 136,634 223,114 Income before non-interest expense allocations 214,079 97,525 31,196 34,514 (74,277) 303,037 Non-interest expense allocations Risk, financial crimes, and compliance 29,124 2,357 3,233 5,308 (40,022) — Information technology and operations 14,702 821 6,150 8,387 (30,060) — Other allocated expenses 16,439 3,331 6,903 7,870 (34,543) — Non-interest expense allocation, subtotal 60,265 6,509 16,286 21,565 (104,625) — Income before taxes 153,814 91,016 14,910 12,949 30,348 303,037 Income tax expense 37,979 22,473 3,681 3,197 7,494 74,824 Net income (Loss) $ 115,835 $ 68,543 $ 11,229 $ 9,752 $ 22,854 $ 228,213 (in thousands) *A discussion of our segments, our reporting methodology, and allocations of interest and non-interest expense are outlined in our Annual Report on Form 10-K for the fiscal year ended December 31, 2025, within Note 18, "Segment Financial Information." 21 Non-GAAP Reconciliation – Segment Results
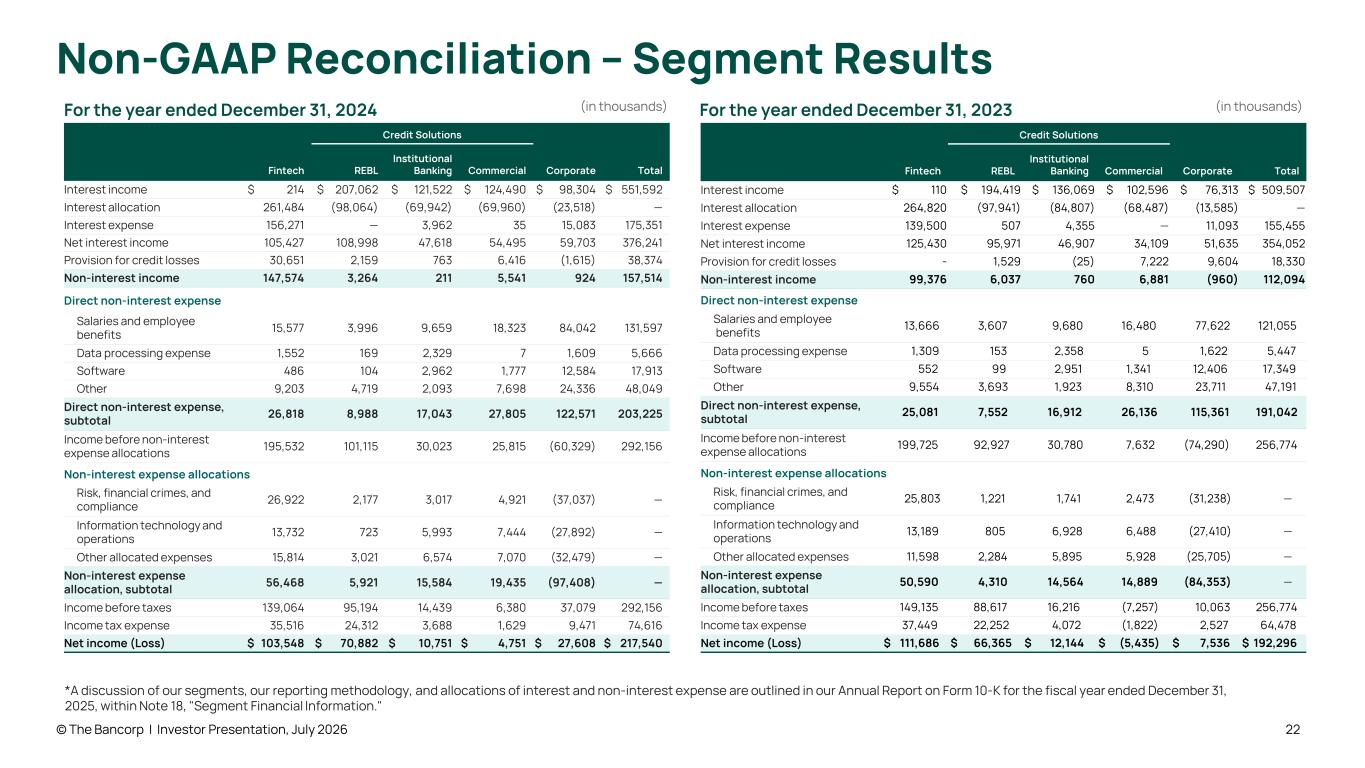
For the year ended December 31, 2024 Fintech Credit Solutions Corporate TotalREBL Institutional Banking Commercial Interest income $ 214 $ 207,062 $ 121,522 $ 124,490 $ 98,304 $ 551,592 Interest allocation 261,484 (98,064) (69,942) (69,960) (23,518) — Interest expense 156,271 — 3,962 35 15,083 175,351 Net interest income 105,427 108,998 47,618 54,495 59,703 376,241 Provision for credit losses 30,651 2,159 763 6,416 (1,615) 38,374 Non-interest income 147,574 3,264 211 5,541 924 157,514 Direct non-interest expense Salaries and employee benefits 15,577 3,996 9,659 18,323 84,042 131,597 Data processing expense 1,552 169 2,329 7 1,609 5,666 Software 486 104 2,962 1,777 12,584 17,913 Other 9,203 4,719 2,093 7,698 24,336 48,049 Direct non-interest expense, subtotal 26,818 8,988 17,043 27,805 122,571 203,225 Income before non-interest expense allocations 195,532 101,115 30,023 25,815 (60,329) 292,156 Non-interest expense allocations Risk, financial crimes, and compliance 26,922 2,177 3,017 4,921 (37,037) — Information technology and operations 13,732 723 5,993 7,444 (27,892) — Other allocated expenses 15,814 3,021 6,574 7,070 (32,479) — Non-interest expense allocation, subtotal 56,468 5,921 15,584 19,435 (97,408) — Income before taxes 139,064 95,194 14,439 6,380 37,079 292,156 Income tax expense 35,516 24,312 3,688 1,629 9,471 74,616 Net income (Loss) $ 103,548 $ 70,882 $ 10,751 $ 4,751 $ 27,608 $ 217,540 © The Bancorp | Investor Presentation, July 2026 (in thousands) *A discussion of our segments, our reporting methodology, and allocations of interest and non-interest expense are outlined in our Annual Report on Form 10-K for the fiscal year ended December 31, 2025, within Note 18, "Segment Financial Information." For the year ended December 31, 2023 Fintech Credit Solutions Corporate TotalREBL Institutional Banking Commercial Interest income $ 110 $ 194,419 $ 136,069 $ 102,596 $ 76,313 $ 509,507 Interest allocation 264,820 (97,941) (84,807) (68,487) (13,585) — Interest expense 139,500 507 4,355 — 11,093 155,455 Net interest income 125,430 95,971 46,907 34,109 51,635 354,052 Provision for credit losses - 1,529 (25) 7,222 9,604 18,330 Non-interest income 99,376 6,037 760 6,881 (960) 112,094 Direct non-interest expense Salaries and employee benefits 13,666 3,607 9,680 16,480 77,622 121,055 Data processing expense 1,309 153 2,358 5 1,622 5,447 Software 552 99 2,951 1,341 12,406 17,349 Other 9,554 3,693 1,923 8,310 23,711 47,191 Direct non-interest expense, subtotal 25,081 7,552 16,912 26,136 115,361 191,042 Income before non-interest expense allocations 199,725 92,927 30,780 7,632 (74,290) 256,774 Non-interest expense allocations Risk, financial crimes, and compliance 25,803 1,221 1,741 2,473 (31,238) — Information technology and operations 13,189 805 6,928 6,488 (27,410) — Other allocated expenses 11,598 2,284 5,895 5,928 (25,705) — Non-interest expense allocation, subtotal 50,590 4,310 14,564 14,889 (84,353) — Income before taxes 149,135 88,617 16,216 (7,257) 10,063 256,774 Income tax expense 37,449 22,252 4,072 (1,822) 2,527 64,478 Net income (Loss) $ 111,686 $ 66,365 $ 12,144 $ (5,435) $ 7,536 $ 192,296 (in thousands) 22 Non-GAAP Reconciliation – Segment Results
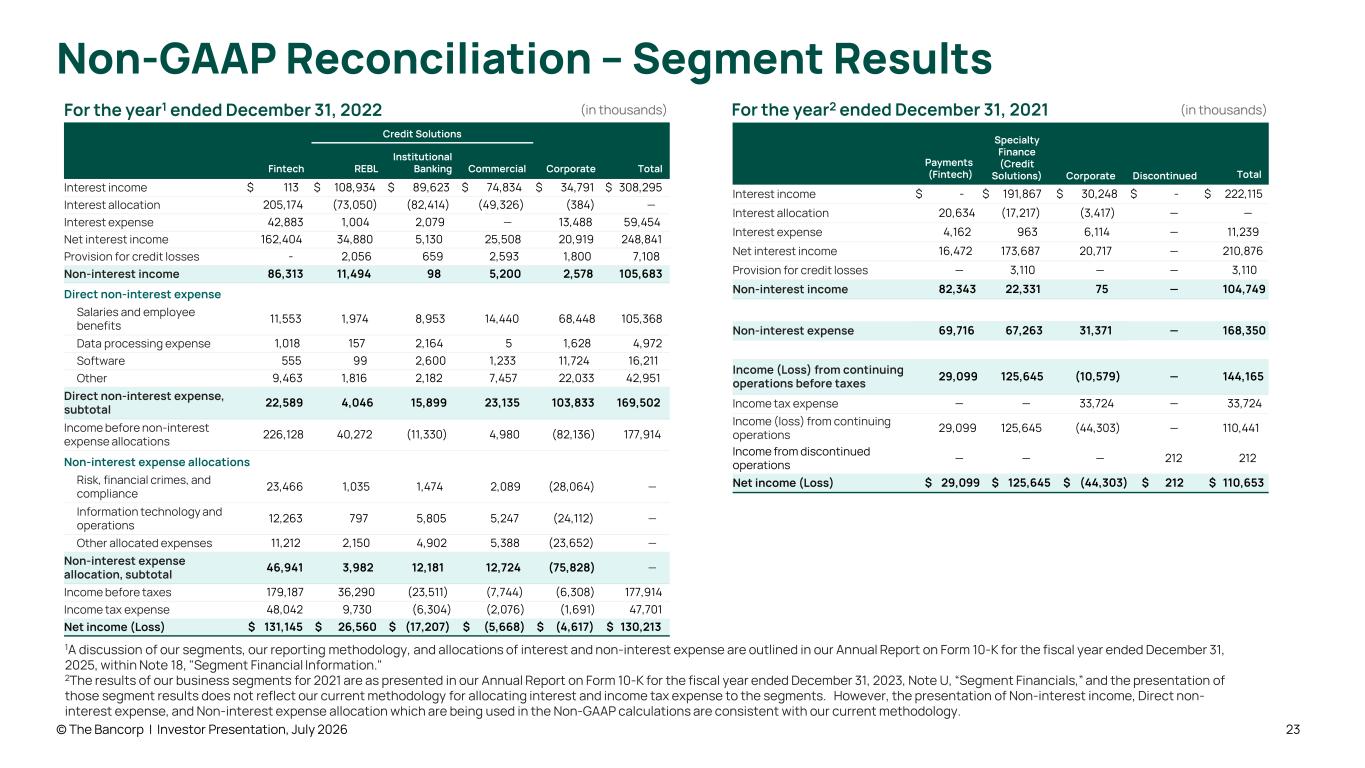
For the year1 ended December 31, 2022 Fintech Credit Solutions Corporate TotalREBL Institutional Banking Commercial Interest income $ 113 $ 108,934 $ 89,623 $ 74,834 $ 34,791 $ 308,295 Interest allocation 205,174 (73,050) (82,414) (49,326) (384) — Interest expense 42,883 1,004 2,079 — 13,488 59,454 Net interest income 162,404 34,880 5,130 25,508 20,919 248,841 Provision for credit losses - 2,056 659 2,593 1,800 7,108 Non-interest income 86,313 11,494 98 5,200 2,578 105,683 Direct non-interest expense Salaries and employee benefits 11,553 1,974 8,953 14,440 68,448 105,368 Data processing expense 1,018 157 2,164 5 1,628 4,972 Software 555 99 2,600 1,233 11,724 16,211 Other 9,463 1,816 2,182 7,457 22,033 42,951 Direct non-interest expense, subtotal 22,589 4,046 15,899 23,135 103,833 169,502 Income before non-interest expense allocations 226,128 40,272 (11,330) 4,980 (82,136) 177,914 Non-interest expense allocations Risk, financial crimes, and compliance 23,466 1,035 1,474 2,089 (28,064) — Information technology and operations 12,263 797 5,805 5,247 (24,112) — Other allocated expenses 11,212 2,150 4,902 5,388 (23,652) — Non-interest expense allocation, subtotal 46,941 3,982 12,181 12,724 (75,828) — Income before taxes 179,187 36,290 (23,511) (7,744) (6,308) 177,914 Income tax expense 48,042 9,730 (6,304) (2,076) (1,691) 47,701 Net income (Loss) $ 131,145 $ 26,560 $ (17,207) $ (5,668) $ (4,617) $ 130,213 © The Bancorp | Investor Presentation, July 2026 (in thousands) 1A discussion of our segments, our reporting methodology, and allocations of interest and non-interest expense are outlined in our Annual Report on Form 10-K for the fiscal year ended December 31, 2025, within Note 18, "Segment Financial Information." 2The results of our business segments for 2021 are as presented in our Annual Report on Form 10-K for the fiscal year ended December 31, 2023, Note U, “Segment Financials,” and the presentation of those segment results does not reflect our current methodology for allocating interest and income tax expense to the segments. However, the presentation of Non-interest income, Direct non- interest expense, and Non-interest expense allocation which are being used in the Non-GAAP calculations are consistent with our current methodology. For the year2 ended December 31, 2021 Payments (Fintech) Specialty Finance (Credit Solutions) Corporate Discontinued Total Interest income $ - $ 191,867 $ 30,248 $ - $ 222,115 Interest allocation 20,634 (17,217) (3,417) — — Interest expense 4,162 963 6,114 — 11,239 Net interest income 16,472 173,687 20,717 — 210,876 Provision for credit losses — 3,110 — — 3,110 Non-interest income 82,343 22,331 75 — 104,749 Non-interest expense 69,716 67,263 31,371 — 168,350 Income (Loss) from continuing operations before taxes 29,099 125,645 (10,579) — 144,165 Income tax expense — — 33,724 — 33,724 Income (loss) from continuing operations 29,099 125,645 (44,303) — 110,441 Income from discontinued operations — — — 212 212 Net income (Loss) $ 29,099 $ 125,645 $ (44,303) $ 212 $ 110,653 (in thousands) 23 Non-GAAP Reconciliation – Segment Results