
AROW 8-K
Arrow Financial Corp (AROW)
8-K
2026-07-23
For: 2026-07-22
View Original
Added on
July 23, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of The Securities Exchange Act of 1934
Date of Report: July 22, 2026
(Date of earliest event reported)
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||
| Registrant’s telephone number, including area code: | ||||||||||||||
(Former name or former address, if changed since last report)
| Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions: | |||||
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol | Name of each exchange on which registered | ||||||
| Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). | ||||||||
| Emerging growth company | ||||||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act | ☐ | |||||||
Item 2.02. Results of Operations and Financial Condition.
On July 23, 2026, Arrow Financial Corporation (the "Company") issued a press release containing unaudited financial information and accompanying discussion for the quarter ended June 30, 2026. A copy of this press release is furnished as Exhibit 99.1 to this report on Form 8-K.
Item 7.01. Regulation FD Disclosure.
On July 23, 2026, the Company made available certain presentation material (the "Second Quarter 2026 Investor Presentation"), which includes among other things, a review of financial results and trends through the period ended June 30, 2026. The furnished Second Quarter 2026 Investor Presentation should be read in conjunction with our Earnings Release for the quarter ended June 30, 2026.
A copy of the presentation material is included as Exhibit 99.2 to this current report on Form 8-K and is incorporated herein by reference.
The information furnished under this Report, including Exhibits 99.1 and 99.2, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or subject to the liabilities of that section. The information shall not be deemed incorporated by reference into any other filing with the Securities and Exchange Commission made by the Company, regardless of any general incorporation language in such filing.
Item 8.01. Other Events.
On July 22, 2026 , the Board of Directors (the “Board”) of the Company declared a quarterly cash dividend of $0.30 per share payable August 25, 2026 to shareholders of record on August 11, 2026.
Item 9.01. Financial Statements and Exhibits.
Exhibits:
Exhibit No. Description
Exhibit 99.2 Arrow Financial Corporation Second Quarter 2026 Investor Presentation dated July 23, 2026
104 Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| ARROW FINANCIAL CORPORATION | ||||||||
| Registrant | ||||||||
| Date: | July 23, 2026 | /s/ Penko Ivanov | ||||||
| Penko Ivanov | ||||||||
| Chief Financial Officer | ||||||||
 | 250 Glen Street | ||||
| Glens Falls, NY 12801 | |||||
| NASDAQ® Symbol: “AROW“ | |||||
| Website: arrowfinancial.com | |||||
| Media Contact: Rachael Murray | |||||
| P: (518) 742-6505 | |||||
| E: [email protected] | |||||
| FOR IMMEDIATE RELEASE | |||||
Arrow Reports 2nd Quarter Net Income of $11.0 Million, or $0.66 per Share, and Declares 3rd Quarter Dividend of $0.30 per Share
GLENS FALLS, N.Y. (July 23, 2026) – Arrow Financial Corporation (NasdaqGS® – AROW) ("Arrow" or the "Company") announced financial results for the three-month period ended June 30, 2026. Reported net income for the second quarter of 2026 was $11.0 million and fully diluted earnings per share ("EPS") was $0.66, versus net income of $13.5 million and EPS of $0.82 for the first quarter of 2026.
The Board of Directors of Arrow declared a quarterly cash dividend of $0.30 per share; payable August 25, 2026 to shareholders of record as of August 11, 2026.
This quarter's results include approximately $1.0 million ($0.05 per share) of merger-related expenses related to the July 1, 2026 acquisition of Adirondack Bancorp, Inc. and Adirondack Bank based in Utica, New York. Excluding the merger-related expenses, Arrow achieved EPS of $0.71 for the second quarter of 2026. The transaction added approximately $1.0 billion in assets and 19 new branch locations.
Second-quarter results were impacted by a specific reserve of $1.6 million ($0.08 per share) for an isolated commercial real estate credit due to a sudden personal and corporate bankruptcy declared in June 2026 (for more details on this credit, please refer to our Second Quarter Investor Presentation), as well as an elevated loan provision due to strong loan growth.
This earnings release and related commentary should be read in conjunction with the Company's July 23, 2026 Form 8-K and related Second Quarter 2026 Investor Presentation, which can also be found on Arrow's website: arrowfinancial.com/documents/investor-presentations.
Arrow President and CEO David S. DeMarco:
"The Arrow team delivered another quarter of strong operating results. While our results were negatively impacted by recognizing a reserve on one isolated commercial credit, the credit metrics of the loan portfolio remain strong with low charge-offs and low non-performing loan balances. The overall health and trajectory of the business continues to perform well. I am particularly excited about the return to significant loan growth and the closing of our acquisition of Adirondack Bank, which will provide us with increased growth opportunities. We look forward to expanding our market with this high-quality, low-cost deposit franchise, adding approximately $1.0 billion to our balance sheet. We expect the transaction to provide significant EPS accretion in 2027 and beyond. Arrow remains well-positioned to deliver shareholder value and execute on its strategic initiatives to build a premier banking franchise for its customers and the communities it serves."
1
Second-Quarter Highlights and Key Metrics
•Net Income of $11.0 million (EPS of $0.66; or $0.71 adjusted for merger-related expenses "MRE"1)
•Insurance revenue 1H26 versus 1H25 up 12.6%
•Wealth management revenue 1H26 versus 1H25 up 9.9%
•Loan growth of $57.6 million (6.7% annualized)
•Annualized charge-offs of 8bps and non-performing loans of 24bps
•Moved $3.8 million loan to non-performing (11bps) due to bankruptcy and recorded $1.6 million specific reserve ($0.08 per share)
•Efficiency ratio of 62.02%; 59.83% excluding MRE1
•Net Interest Income of $35.9 million
•Net Interest Margin of 3.42% (3.43% fully taxable equivalent ("FTE")2), versus 3.47% (3.48% FTE2) in the prior quarter
•Return on Average Assets (ROA) of 0.99%; 1.06% adjusted for MRE1
•Cost of retail deposits3 decreased to 1.61%
Income Statement
•Net Income: Net income for the second quarter of 2026 was $11.0 million, decreasing from $13.5 million in the first quarter of 2026.
◦Compared to the prior quarter, net income decreased primarily due to an increase in the provision for credit losses of $2.3 million, including $1.6 million related to a specific reserve for a commercial loan where the borrower and guarantors entered into bankruptcy during the quarter. Net income was also impacted by a decrease in non-interest income of $0.4 million, an increase in MRE of $0.2 million and lower net interest income of $0.2 million. The decreases were partially offset by lower income tax expenses of $0.9 million.
•Net Interest Income: Net interest income for the second quarter of 2026 was $35.9 million, decreasing 0.6% from the first quarter of 2026.
◦Total interest and dividend income was $53.6 million for the second quarter of 2026, a decrease from $53.8 million in the first quarter of 2026. The decrease was attributable to lower average earning assets throughout the quarter as well as the increase in non-performing loans. Interest expense for the second quarter of 2026 was $17.7 million, consistent with the first quarter of 2026 as lower deposit costs were offset by timing and a change in the mix of deposit balances toward higher cost deposits.
•Net Interest Margin: Net interest margin, on an FTE basis, for the second quarter of 2026 decreased to 3.43%, compared to 3.48% for the first quarter of 2026. The decrease in net interest margin compared to the first quarter of 2026 was primarily the result of a seasonal change in the deposit mix toward higher costing interest-bearing liabilities. Net interest margin was also impacted by the reversal of interest income related to the aforementioned commercial loan migrating to non-performing.
1 EPS, efficiency ratio and ROA excluding merger-related expenses are non-GAAP measures. See reconciliation in Note 5 to the Selected Quarterly Information
2 FTE Net interest margin is a non-GAAP measure. See reconciliation on Note 2 to the Selected Quarterly Information
3 Retail deposits exclude wholesale funding sources
2
| Three Months Ended | |||||||||||||||||
| (Dollars in Thousands) | |||||||||||||||||
| June 30, 2026 | December 31, 2025 | June 30, 2025 | |||||||||||||||
| Interest and Dividend Income | $ | 53,617 | $ | 54,610 | $ | 51,573 | |||||||||||
| Interest Expense | 17,686 | 19,467 | 19,040 | ||||||||||||||
| Net Interest Income | 35,931 | 35,143 | 32,533 | ||||||||||||||
Average Earning Assets(A) | 4,211,209 | 4,302,305 | 4,142,993 | ||||||||||||||
| Average Interest-Bearing Liabilities | 3,222,939 | 3,280,856 | 3,191,906 | ||||||||||||||
Average Yield on Earning Assets(A) | 5.11 | % | 5.04 | % | 4.99 | % | |||||||||||
| Average Cost of Interest-Bearing Liabilities | 2.20 | 2.35 | 2.39 | ||||||||||||||
| Net Interest Spread | 2.91 | 2.69 | 2.60 | ||||||||||||||
| Net Interest Margin | 3.42 | 3.24 | 3.15 | ||||||||||||||
| Net Interest Margin - FTE | 3.43 | 3.25 | 3.16 | ||||||||||||||
(A) Includes Nonaccrual Loans. | |||||||||||||||||
•Provision for Credit Losses: For the second quarter of 2026, the provision for credit losses was $2.8 million compared to $0.5 million in the first quarter of 2026, primarily driven by a $1.6 million specific reserve related to the non-performing commercial loan as well as an increase to the provision due to loan growth in the second quarter of 2026.
•Non-Interest Income: Non-interest income for the three months ended June 30, 2026, was $8.3 million, a decrease from $8.6 million in the first quarter of 2026. The decrease was the result of the season fluctuation of insurance premiums of $0.1 million as well as a $0.3 million charge related to the impairment of a property held for future use. This was partially offset by an increase in interchange fees from the linked quarter and a positive equity position valuation adjustment of approximately $0.2 million
•Non-Interest Expense: Non-interest expense for the second quarter of 2026 was $27.5 million, an increase from $26.9 million in the first quarter of 2026. The second quarter of 2026 included approximately $1.0 million of MRE versus $0.8 million in the first quarter of 2026.
•Provision for Income Taxes: The provision for income taxes and effective tax rate were $2.9 million and 21.1%, respectively for the second quarter of 2026, and $3.9 million and 22.3%, respectively for the first quarter of 2026. The lower tax expense was driven by lower pre-tax income and a lower effective tax rate. The effective tax rate for the second quarter of 2026 reflects the impact of tax credits recognized from energy production tax credit purchases made in June 2026 offset by nondeductible expenses related to the acquisition of Adirondack Bancorp, Inc. and Adirondack Bank.
Balance Sheet
•Total Assets: Total assets were $4.5 billion at June 30, 2026, a decrease of $39.7 million, or 0.9%, as compared to March 31, 2026. For the second quarter of 2026, the overall change in asset was driven by a decline in cash balances attributable to a net decrease in deposits.
•Investments: Total investments were $587.9 million as of June 30, 2026, a decrease of $6.6 million, or 1.1%, compared to March 31, 2026. The decrease from March 31, 2026 was driven primarily by paydowns and maturities. There were no material credit quality issues related to the investment portfolio.
•Loans: Total loans were $3.5 billion as of June 30, 2026. Loans outstanding increased in the second quarter of 2026 by $57.6 million, driven by growth in commercial loans. Please see the loan detail included in the Consolidated Financial Information table on page 14.
3
•Allowance for Credit Losses: The allowance for credit losses was $36.2 million as of June 30, 2026, which represented 1.03% of loans outstanding, as compared to $34.1 million, or 0.99% of loans outstanding, at March 31, 2026. The increase in the allowance was the result of a $1.6 million specific reserve related to the previously referenced non-performing commercial loan as well as an increase to the allowance for growth in the loan portfolio, partially offset by charge-offs. Net charge-offs, expressed as an annualized percentage of average loans outstanding, were 0.08% for the three-month period ended June 30, 2026, as compared to 0.10% for the three-month period ended March 31, 2026. Nonperforming assets were $8.7 million as of June 30, 2026, representing 0.19% of period-end assets, an increase from $4.9 million, or 0.11%, at March 31, 2026. Nonperforming assets increased due to the $3.8 million non-performing commercial loan previously referenced.
•Deposits: At June 30, 2026, deposit balances were $3.7 billion, a decrease of $358.7 million from March 31, 2026. The change from March 31, 2026 was primarily attributable to $300 million of brokered CDs, being replaced by lower costing FHLB borrowings. In addition, the seasonality of municipal deposits contributed to decreased deposits in the quarter. Please refer to page 7 for further details related to deposits.
•Capital: Total stockholders’ equity was $446.3 million at June 30, 2026, an increase of $6.2 million, or 1.4%, from March 31, 2026. The increase from March 31, 2026 was primarily attributable to net income of $11.0 million and other stock-based activity of $0.8 million offset by other comprehensive loss of $0.6 million and dividends of $5.0 million. Arrow's regulatory capital ratios remain strong. As of June 30, 2026, Arrow's Common Equity Tier 1 Capital Ratio was 13.21% and Total Risk-Based Capital Ratio was 14.98%. The capital ratios of Arrow and its subsidiary bank continued to exceed the “well capitalized” regulatory standards. Regulatory capital ratios are preliminary, subject to finalization as part of the current quarter Call Report.
Additional Commentary
•BauerFinancial Ratings: Arrow Bank National Association ("Arrow Bank") received a 5-Star Superior rating from BauerFinancial, Inc., the nation’s premier bank rating firm. Arrow Bank has earned this designation for 77 consecutive quarters, securing its prominent position as an “Exceptional Performance Bank.”
——————
About Arrow: Arrow Financial Corporation is a holding company headquartered in Glens Falls, New York, serving the financial needs of northeastern New York. The Company is the parent of Arrow Bank, a full-service commercial bank, and Upstate Agency, LLC, a comprehensive insurance agency.
Non-GAAP Financial Measures Reconciliation: In addition to presenting information in conformity with accounting principles generally accepted in the United States of America (GAAP), this news release contains financial information determined by methods other than GAAP (non-GAAP). The following measures used in this release, which are commonly utilized by financial institutions, have not been specifically exempted by the Securities and Exchange Commission ("SEC") and may constitute "non-GAAP financial measures" within the meaning of the SEC's rules: tangible book value, tangible equity, return on tangible equity, tax-equivalent adjustment and related net interest income, tax-equivalent net interest margin and the efficiency ratio. Management believes that the non-GAAP financial measures disclosed by Arrow from time to time are useful in evaluating Arrow's performance and that such information should be considered as supplemental in nature and not as a substitute for or superior to the related financial information prepared in accordance with GAAP. Non-GAAP financial measures may differ from similar measures presented by other companies. See the reconciliation of GAAP to non-GAAP measures in the section "Selected Quarterly Information."
4
Safe Harbor Statement: The information contained in this earnings release may contain statements that are not historical in nature but rather are based on management’s beliefs, assumptions, expectations, estimates and projections about the future. These statements can sometimes be identified by Arrow's use of forward-looking words such as "may," "will," "anticipate," "estimate," "expect," or "intend." These statements may be "forward-looking statements" within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended, involving a degree of uncertainty and attendant risk. In the case of all forward-looking statements, actual outcomes and results may differ materially from what the statements predict or forecast, explicitly or by implication because of various factors, including changes in economic conditions or interest rates, credit risk, inflation, tariffs, cybersecurity risks, changes in FDIC assessments, bank failures, geopolitical events, difficulties in managing Arrow’s growth, competition, changes in law or the regulatory environment, risks relating to the integration of Adirondack Bancorp, Inc. and Adirondack Bank, and changes in general business and economic trends. Arrow undertakes no obligation to revise or update these forward-looking statements to reflect the occurrence of unanticipated events. This earnings release should be read in conjunction with Arrow’s Annual Report on Form 10-K for the year ended December 31, 2025, and other filings with the SEC.
5
ARROW FINANCIAL CORPORATION AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
(In Thousands, Except Per Share Amounts - Unaudited)
| Three Months Ended June 30, | Six Months Ended June 30, | |||||||||||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||||||||
| INTEREST AND DIVIDEND INCOME | ||||||||||||||||||||||||||
| Interest and Fees on Loans | $ | 47,181 | $ | 45,600 | $ | 94,307 | $ | 90,150 | ||||||||||||||||||
| Interest on Deposits at Banks | 1,200 | 1,622 | 2,875 | 3,243 | ||||||||||||||||||||||
| Interest and Dividends on Investment Securities: | ||||||||||||||||||||||||||
| Fully Taxable | 4,717 | 3,790 | 9,246 | 7,398 | ||||||||||||||||||||||
| Exempt from Federal Taxes | 519 | 561 | 983 | 1,148 | ||||||||||||||||||||||
| Total Interest and Dividend Income | 53,617 | 51,573 | 107,411 | 101,939 | ||||||||||||||||||||||
| INTEREST EXPENSE | ||||||||||||||||||||||||||
| Interest-Bearing Checking Accounts | 2,162 | 1,941 | 4,262 | 3,744 | ||||||||||||||||||||||
| Savings Deposits | 8,933 | 9,367 | 17,649 | 18,850 | ||||||||||||||||||||||
| Time Deposits over $250,000 | 1,052 | 1,726 | 2,248 | 3,537 | ||||||||||||||||||||||
| Other Time Deposits | 4,304 | 5,793 | 9,740 | 11,322 | ||||||||||||||||||||||
| Borrowings | 1,019 | — | 1,019 | 167 | ||||||||||||||||||||||
| Junior Subordinated Obligations Issued to Unconsolidated Subsidiary Trusts | 171 | 171 | 340 | 340 | ||||||||||||||||||||||
| Interest on Financing Leases | 45 | 42 | 92 | 89 | ||||||||||||||||||||||
| Total Interest Expense | 17,686 | 19,040 | 35,350 | 38,049 | ||||||||||||||||||||||
| NET INTEREST INCOME | 35,931 | 32,533 | 72,061 | 63,890 | ||||||||||||||||||||||
| Provision for Credit Losses | 2,827 | 594 | 3,375 | 5,613 | ||||||||||||||||||||||
| NET INTEREST INCOME AFTER PROVISION FOR CREDIT LOSSES | 33,104 | 31,939 | 68,686 | 58,277 | ||||||||||||||||||||||
| NON-INTEREST INCOME | ||||||||||||||||||||||||||
| Income From Fiduciary Activities | 2,706 | 2,398 | 5,419 | 4,933 | ||||||||||||||||||||||
| Fees for Other Services to Customers | 2,969 | 2,787 | 5,696 | 5,387 | ||||||||||||||||||||||
| Insurance Commissions | 1,974 | 1,804 | 4,087 | 3,630 | ||||||||||||||||||||||
Net Gain (Loss) on Securities | 155 | (40) | 300 | 277 | ||||||||||||||||||||||
| Net Gain on Sales of Loans | 154 | 213 | 444 | 314 | ||||||||||||||||||||||
| Other Operating Income | 298 | 447 | 938 | 907 | ||||||||||||||||||||||
| Total Non-Interest Income | 8,256 | 7,609 | 16,884 | 15,448 | ||||||||||||||||||||||
| NON-INTEREST EXPENSE | ||||||||||||||||||||||||||
| Salaries and Employee Benefits | 15,097 | 14,086 | 30,019 | 27,641 | ||||||||||||||||||||||
| Occupancy Expenses, Net | 2,101 | 1,952 | 4,560 | 3,974 | ||||||||||||||||||||||
| Technology and Equipment Expense | 4,757 | 5,589 | 9,809 | 10,676 | ||||||||||||||||||||||
| FDIC Assessments | 441 | 649 | 1,026 | 1,319 | ||||||||||||||||||||||
| Other Operating Expense | 5,068 | 3,376 | 8,915 | 8,087 | ||||||||||||||||||||||
| Total Non-Interest Expense | 27,464 | 25,652 | 54,329 | 51,697 | ||||||||||||||||||||||
| INCOME BEFORE PROVISION FOR INCOME TAXES | 13,896 | 13,896 | 31,241 | 22,028 | ||||||||||||||||||||||
| Provision for Income Taxes | 2,934 | 3,091 | 6,794 | 4,913 | ||||||||||||||||||||||
| NET INCOME | $ | 10,962 | $ | 10,805 | $ | 24,447 | $ | 17,115 | ||||||||||||||||||
| Average Shares Outstanding: | ||||||||||||||||||||||||||
| Basic | 16,428 | 16,545 | 16,408 | 16,611 | ||||||||||||||||||||||
| Diluted | 16,467 | 16,551 | 16,438 | 16,618 | ||||||||||||||||||||||
| Per Common Share: | ||||||||||||||||||||||||||
| Basic Earnings | $ | 0.66 | $ | 0.65 | $ | 1.48 | $ | 1.03 | ||||||||||||||||||
| Diluted Earnings | 0.66 | 0.65 | 1.48 | 1.03 | ||||||||||||||||||||||
6
ARROW FINANCIAL CORPORATION AND SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS
(In Thousands, Except Share and Per Share Amounts - Unaudited)
| June 30, 2026 | December 31, 2025 | ||||||||||
| ASSETS | |||||||||||
| Cash and Due From Banks | $ | 30,881 | $ | 29,132 | |||||||
Interest-Earning Deposits at Banks | 155,907 | 185,051 | |||||||||
| Investment Securities: | |||||||||||
| Available-for-Sale at Fair Value | 498,202 | 495,868 | |||||||||
Held-to-Maturity (Fair Value of $65,270 at June 30, 2026 and $66,569 at December 31, 2025) | 65,490 | 66,975 | |||||||||
| Equity Securities | 5,897 | 5,597 | |||||||||
| Other Investments | 18,351 | 4,372 | |||||||||
| Loans | 3,496,541 | 3,453,093 | |||||||||
| Allowance for Credit Losses | (36,183) | (34,322) | |||||||||
| Net Loans | 3,460,358 | 3,418,771 | |||||||||
| Premises and Equipment, Net | 62,530 | 59,433 | |||||||||
| Goodwill | 23,789 | 23,789 | |||||||||
| Other Intangible Assets, Net | 1,612 | 1,741 | |||||||||
| Other Assets | 159,342 | 155,133 | |||||||||
| Total Assets | $ | 4,482,359 | $ | 4,445,862 | |||||||
| LIABILITIES | |||||||||||
| Noninterest-Bearing Deposits | 736,087 | 722,374 | |||||||||
| Interest-Bearing Checking Accounts | 871,965 | 862,192 | |||||||||
| Savings Deposits | 1,590,680 | 1,557,638 | |||||||||
| Time Deposits over $250,000 | 132,350 | 155,802 | |||||||||
| Other Time Deposits | 324,123 | 641,463 | |||||||||
| Total Deposits | 3,655,205 | 3,939,469 | |||||||||
| Borrowings | 310,190 | 4,265 | |||||||||
| Junior Subordinated Obligations Issued to Unconsolidated Subsidiary Trusts | 20,000 | 20,000 | |||||||||
| Finance Leases | 4,887 | 4,929 | |||||||||
| Other Liabilities | 45,771 | 45,347 | |||||||||
| Total Liabilities | 4,036,053 | 4,014,010 | |||||||||
| STOCKHOLDERS’ EQUITY | |||||||||||
Preferred Stock, $1 Par Value; 1,000,000 Shares Authorized at June 30, 2026 and December 31, 2025 (none issued) | — | — | |||||||||
Common Stock, $1 Par Value: 30,000,000 Shares Authorized; 22,066,559 Shares Issued; 16,545,170 and 16,445,342 Shares Outstanding at June 30, 2026 and December 31, 2025) | 22,067 | 22,067 | |||||||||
| Additional Paid-in Capital | 415,357 | 414,506 | |||||||||
| Retained Earnings | 116,806 | 102,271 | |||||||||
| Accumulated Other Comprehensive Loss | (5,390) | (4,037) | |||||||||
Treasury Stock, at Cost (5,521,389 Shares at June 30, 2026 and 5,621,217 Shares at December 31, 2025) | (102,534) | (102,955) | |||||||||
| Total Stockholders’ Equity | 446,306 | 431,852 | |||||||||
| Total Liabilities and Stockholders’ Equity | $ | 4,482,359 | $ | 4,445,862 | |||||||
7
Arrow Financial Corporation
Selected Quarterly Information
(Dollars In Thousands, Except Per Share Amounts - Unaudited)
| Quarter Ended | 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | ||||||||||||||||||||||||
| Net Income | $ | 10,962 | $ | 13,485 | $ | 14,013 | $ | 12,825 | $ | 10,805 | |||||||||||||||||||
| Share and Per Share Data: | |||||||||||||||||||||||||||||
| Period End Shares Outstanding | 16,545 | 16,527 | 16,445 | 16,438 | 16,484 | ||||||||||||||||||||||||
| Basic Average Shares Outstanding | 16,428 | 16,382 | 16,390 | 16,402 | 16,545 | ||||||||||||||||||||||||
| Diluted Average Shares Outstanding | 16,467 | 16,403 | 16,413 | 16,406 | 16,551 | ||||||||||||||||||||||||
| Basic Earnings Per Share | $ | 0.66 | $ | 0.82 | $ | 0.85 | $ | 0.77 | $ | 0.65 | |||||||||||||||||||
| Diluted Earnings Per Share | 0.66 | 0.82 | 0.85 | 0.77 | 0.65 | ||||||||||||||||||||||||
| Cash Dividend Per Share | 0.30 | 0.30 | 0.29 | 0.29 | 0.28 | ||||||||||||||||||||||||
| Selected Quarterly Average Balances: | |||||||||||||||||||||||||||||
| Interest-Earning Deposits at Banks | $ | 129,628 | $ | 183,252 | $ | 260,806 | $ | 200,251 | $ | 145,473 | |||||||||||||||||||
| Investment Securities | 614,771 | 598,817 | 596,994 | 574,080 | 582,380 | ||||||||||||||||||||||||
| Loans | 3,466,810 | 3,440,505 | 3,444,505 | 3,424,784 | 3,415,140 | ||||||||||||||||||||||||
| Deposits | 3,788,961 | 3,928,761 | 4,002,221 | 3,913,721 | 3,849,093 | ||||||||||||||||||||||||
| Other Borrowed Funds | 149,307 | 29,181 | 29,203 | 30,539 | 33,579 | ||||||||||||||||||||||||
| Stockholders' Equity | 445,887 | 438,846 | 425,042 | 413,058 | 406,529 | ||||||||||||||||||||||||
| Total Assets | 4,425,821 | 4,439,833 | 4,499,195 | 4,399,815 | 4,332,339 | ||||||||||||||||||||||||
| Return on Average Assets, annualized | 0.99 | % | 1.23 | % | 1.24 | % | 1.16 | % | 1.00 | % | |||||||||||||||||||
| Return on Average Equity, annualized | 9.86 | % | 12.46 | % | 13.08 | % | 12.32 | % | 10.66 | % | |||||||||||||||||||
Return on Average Tangible Equity, annualized 1 | 10.46 | % | 13.23 | % | 13.92 | % | 13.13 | % | 11.38 | % | |||||||||||||||||||
| Average Earning Assets | $ | 4,211,209 | $ | 4,222,574 | $ | 4,302,305 | $ | 4,199,115 | $ | 4,142,993 | |||||||||||||||||||
| Average Paying Liabilities | 3,222,939 | 3,244,709 | 3,280,856 | 3,193,789 | 3,191,906 | ||||||||||||||||||||||||
| Interest Income | 53,617 | 53,794 | 54,610 | 53,598 | 51,573 | ||||||||||||||||||||||||
Tax-Equivalent Adjustment 2 | 133 | 123 | 114 | 121 | 148 | ||||||||||||||||||||||||
Interest Income, Tax-Equivalent 2 | 53,750 | 53,917 | 54,724 | 53,719 | 51,721 | ||||||||||||||||||||||||
| Interest Expense | 17,686 | 17,664 | 19,467 | 19,467 | 19,040 | ||||||||||||||||||||||||
| Net Interest Income | 35,931 | 36,130 | 35,143 | 34,131 | 32,533 | ||||||||||||||||||||||||
Net Interest Income, Tax-Equivalent 2 | 36,064 | 36,253 | 35,258 | 34,252 | 32,681 | ||||||||||||||||||||||||
| Net Interest Margin, annualized | 3.42 | % | 3.47 | % | 3.24 | % | 3.22 | % | 3.15 | % | |||||||||||||||||||
Net Interest Margin, Tax-Equivalent, annualized 2 | 3.43 | % | 3.48 | % | 3.25 | % | 3.24 | % | 3.16 | % | |||||||||||||||||||
Efficiency Ratio Calculation: 3 | |||||||||||||||||||||||||||||
| Non-Interest Expense | $ | 27,464 | $ | 26,865 | $ | 25,804 | $ | 25,433 | $ | 25,652 | |||||||||||||||||||
| Less: Intangible Asset Amortization | 71 | 72 | 74 | 76 | 80 | ||||||||||||||||||||||||
| Net Non-Interest Expense | $ | 27,393 | $ | 26,793 | $ | 25,730 | $ | 25,357 | $ | 25,572 | |||||||||||||||||||
| Net Interest Income, Tax-Equivalent | $ | 36,064 | $ | 36,253 | $ | 35,257 | $ | 34,252 | $ | 32,681 | |||||||||||||||||||
| Non-Interest Income | 8,256 | 8,628 | 8,268 | 8,716 | 7,609 | ||||||||||||||||||||||||
| Less: Net Gain (Loss) on Securities | 155 | 145 | (127) | 392 | (40) | ||||||||||||||||||||||||
| Net Gross Income | $ | 44,165 | $ | 44,736 | $ | 43,652 | $ | 42,576 | $ | 40,330 | |||||||||||||||||||
| Efficiency Ratio | 62.02 | % | 59.89 | % | 58.94 | % | 59.56 | % | 63.41 | % | |||||||||||||||||||
| Period-End Capital Information: | |||||||||||||||||||||||||||||
| Total Stockholders' Equity (i.e. Book Value) | $ | 446,306 | $ | 440,143 | $ | 431,852 | $ | 417,687 | $ | 408,506 | |||||||||||||||||||
Book Value per Share | 26.98 | 26.63 | 26.26 | 25.41 | 24.78 | ||||||||||||||||||||||||
| Goodwill and Other Intangible Assets, net | 25,401 | 25,481 | 25,530 | 25,594 | 25,659 | ||||||||||||||||||||||||
Tangible Book Value per Share 1 | 25.44 | 25.09 | 24.71 | 23.85 | 23.23 | ||||||||||||||||||||||||
Capital Ratios:4 | |||||||||||||||||||||||||||||
| Tier 1 Leverage Ratio | 10.19 | % | 10.02 | % | 9.68 | % | 9.66 | % | 9.64 | % | |||||||||||||||||||
Common Equity Tier 1 Capital Ratio | 13.21 | % | 13.30 | % | 13.01 | % | 13.07 | % | 12.73 | % | |||||||||||||||||||
| Tier 1 Risk-Based Capital Ratio | 13.83 | % | 13.93 | % | 13.64 | % | 13.71 | % | 13.37 | % | |||||||||||||||||||
| Total Risk-Based Capital Ratio | 14.98 | % | 15.04 | % | 14.76 | % | 14.86 | % | 14.51 | % | |||||||||||||||||||
8
| Arrow Financial Corporation | ||||||||||||||||||||||||||||||||||||||
| Selected Quarterly Information | ||||||||||||||||||||||||||||||||||||||
| (Dollars In Thousands, Except Per Share Amounts - Unaudited) | ||||||||||||||||||||||||||||||||||||||
| Footnotes: | ||||||||||||||||||||||||||||||||||||||
| 1. | Non-GAAP Financial Measure Reconciliation: Tangible Book Value, Tangible Equity, and Return on Tangible Equity exclude goodwill and other intangible assets, net from total equity. These are non-GAAP financial measures, which Arrow believes provide investors with information that is useful in understanding its financial performance. | |||||||||||||||||||||||||||||||||||||
| 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | ||||||||||||||||||||||||||||||||||
| Total Stockholders' Equity (GAAP) | $ | 446,306 | $ | 440,143 | $ | 431,852 | $ | 417,687 | $ | 408,506 | ||||||||||||||||||||||||||||
| Less: Goodwill and Other Intangible assets, net | 25,401 | 25,481 | 25,530 | 25,594 | 25,659 | |||||||||||||||||||||||||||||||||
| Tangible Equity (Non-GAAP) | $ | 420,905 | $ | 414,662 | $ | 406,322 | $ | 392,093 | $ | 382,847 | ||||||||||||||||||||||||||||
| Period End Shares Outstanding | 16,545 | 16,527 | 16,445 | 16,438 | 16,484 | |||||||||||||||||||||||||||||||||
| Tangible Book Value per Share (Non-GAAP) | $ | 25.44 | $ | 25.09 | $ | 24.71 | $ | 23.85 | $ | 23.23 | ||||||||||||||||||||||||||||
| Net Income | 10,962 | 13,485 | 14,013 | 12,825 | 10,805 | |||||||||||||||||||||||||||||||||
| Return on Tangible Equity (Net Income/Tangible Equity - Annualized) | 10.46 | % | 13.23 | % | 13.92 | % | 13.13 | % | 11.38 | % | ||||||||||||||||||||||||||||
| 2. | Non-GAAP Financial Measure Reconciliation: Net Interest Margin is the ratio of annualized tax-equivalent net interest income to average earning assets. This is also a non-GAAP financial measure, which Arrow believes provides investors with information that is useful in understanding its financial performance. | |||||||||||||||||||||||||||||||||||||
| 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | ||||||||||||||||||||||||||||||||||
| Interest Income (GAAP) | $ | 53,617 | $ | 53,794 | $ | 54,610 | $ | 53,598 | $ | 51,573 | ||||||||||||||||||||||||||||
| Add: Tax-Equivalent adjustment (Non-GAAP) | 133 | 123 | 114 | 121 | 148 | |||||||||||||||||||||||||||||||||
| Interest Income - Tax Equivalent (Non-GAAP) | $ | 53,750 | $ | 53,917 | $ | 54,724 | $ | 53,719 | $ | 51,721 | ||||||||||||||||||||||||||||
| Net Interest Income (GAAP) | $ | 35,931 | $ | 36,130 | $ | 35,143 | $ | 34,131 | $ | 32,533 | ||||||||||||||||||||||||||||
| Add: Tax-Equivalent adjustment (Non-GAAP) | 133 | 123 | 114 | 121 | 148 | |||||||||||||||||||||||||||||||||
| Net Interest Income - Tax Equivalent (Non-GAAP) | $ | 36,064 | $ | 36,253 | $ | 35,257 | $ | 34,252 | $ | 32,681 | ||||||||||||||||||||||||||||
| Average Earning Assets | $ | 4,211,209 | $ | 4,222,574 | $ | 4,302,305 | $ | 4,199,115 | $ | 4,142,993 | ||||||||||||||||||||||||||||
| Net Interest Margin (Non-GAAP)* | 3.43 | % | 3.48 | % | 3.25 | % | 3.24 | % | 3.16 | % | ||||||||||||||||||||||||||||
| 3. | Non-GAAP Financial Measure Reconciliation: Financial Institutions often use the "efficiency ratio", a non-GAAP ratio, as a measure of expense control. Arrow believes the efficiency ratio provides investors with information that is useful in understanding its financial performance. Arrow defines efficiency ratio as the ratio of non-interest expense to net gross income (which equals tax-equivalent net interest income plus non-interest income, as adjusted). | |||||||||||||||||||||||||||||||||||||
9
| Arrow Financial Corporation | ||||||||||||||||||||||||||||||||||||||
| Selected Quarterly Information | ||||||||||||||||||||||||||||||||||||||
| (Dollars In Thousands, Except Per Share Amounts - Unaudited) | ||||||||||||||||||||||||||||||||||||||
| 4. | For the current quarter, all of the regulatory capital ratios as well as the Total Risk-Weighted Assets are calculated in accordance with bank regulatory capital rules. The June 30, 2026 CET1 ratio listed in the tables (i.e., 13.21%) exceeds the sum of the required minimum CET1 ratio plus the fully phased-in Capital Conservation Buffer (i.e., 7.00%). Regulatory capital ratios are estimated, subject to finalization as part of the current quarter Call Report. | |||||||||||||||||||||||||||||||||||||
| 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | ||||||||||||||||||||||||||||||||||
| Total Risk Weighted Assets | $ | 3,253,881 | $ | 3,180,782 | $ | 3,182,240 | $ | 3,095,225 | $ | 3,121,451 | ||||||||||||||||||||||||||||
| Common Equity Tier 1 Capital | 429,971 | 423,139 | 414,050 | 404,426 | 397,432 | |||||||||||||||||||||||||||||||||
| Common Equity Tier 1 Ratio | 13.21 | % | 13.30 | % | 13.01 | % | 13.07 | % | 12.73 | % | ||||||||||||||||||||||||||||
| 5. | Non-GAAP Financial Measure Reconciliation: Net Income and Net Non-Interest Expense adjusted for non-core expenses. Non-core expenses include merger-related expenses, which are related to the announced acquisition of Adirondack Bancorp, Inc., and unification expenses, which are related to the system conversion and operational merger of the Company's two banking subsidiaries during the year ended December 31, 2025. EPS, efficiency ratio, and ROA are presented on an adjusted basis to reflect these exclusions. These are non-GAAP financial measures, which Arrow believes provides investors with information that is useful in understanding its financial performance. | |||||||||||||||||||||||||||||||||||||
| 6/30/2026 | 3/31/2026 | 12/31/2025 | 9/30/2025 | 6/30/2025 | ||||||||||||||||||||||||||||||||||
| Net Income | $ | 10,962 | $ | 13,485 | $ | 14,013 | $ | 12,825 | $ | 10,805 | ||||||||||||||||||||||||||||
| Non-Core Expenses: | ||||||||||||||||||||||||||||||||||||||
| Merger-Related Expenses | 971 | 790 | — | — | — | |||||||||||||||||||||||||||||||||
| Unification Expenses | — | — | — | 543 | 1,134 | |||||||||||||||||||||||||||||||||
| Less: Tax Benefit | (214) | (174) | — | (119) | (249) | |||||||||||||||||||||||||||||||||
| Net Non-Core Expenses (Non-GAAP) | 757 | 616 | — | 424 | 885 | |||||||||||||||||||||||||||||||||
| Core Net Income (Non-GAAP) | $ | 11,719 | $ | 14,101 | $ | 14,013 | $ | 13,249 | $ | 11,690 | ||||||||||||||||||||||||||||
| Net Non-Interest Expense | $ | 27,393 | $ | 26,793 | $ | 25,730 | $ | 25,357 | $ | 25,572 | ||||||||||||||||||||||||||||
| Non-Core Expenses: | ||||||||||||||||||||||||||||||||||||||
| Merger-Related Expenses | 971 | 790 | — | — | — | |||||||||||||||||||||||||||||||||
| Unification Expenses | — | — | — | 543 | 1,134 | |||||||||||||||||||||||||||||||||
| Core Net Non-Interest Expense (Non-GAAP) | $ | 26,422 | $ | 26,003 | $ | 25,730 | $ | 24,814 | $ | 24,438 | ||||||||||||||||||||||||||||
| Core Earnings Per Share (Non-GAAP) | $ | 0.71 | $ | 0.85 | $ | 0.85 | $ | 0.80 | $ | 0.70 | ||||||||||||||||||||||||||||
| Core Return on Average Assets (Non-GAAP) | 1.06 | % | 1.29 | % | 1.24 | % | 1.20 | % | 1.08 | % | ||||||||||||||||||||||||||||
| Core Efficiency Ratio (Non-GAAP) | 59.83 | % | 58.13 | % | 58.94 | % | 58.28 | % | 60.60 | % | ||||||||||||||||||||||||||||
| * Quarterly ratios have been annualized. | ||||||||||||||||||||||||||||||||||||||
10
Arrow Financial Corporation
Average Consolidated Balance Sheets and Net Interest Income Analysis
(Dollars in Thousands - Unaudited)
| Quarter Ended: | June 30, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||
| Interest | Rate | Interest | Rate | ||||||||||||||||||||||||||||||||
| Average | Income/ | Earned/ | Average | Income/ | Earned/ | ||||||||||||||||||||||||||||||
| Balance | Expense | Paid | Balance | Expense | Paid | ||||||||||||||||||||||||||||||
| Interest-Earning Deposits at Banks | $ | 129,628 | $ | 1,200 | 3.71 | % | $ | 145,473 | $ | 1,622 | 4.47 | % | |||||||||||||||||||||||
| Investment Securities: | |||||||||||||||||||||||||||||||||||
| Fully Taxable | 548,084 | 4,717 | 3.45 | 496,614 | 3,790 | 3.06 | |||||||||||||||||||||||||||||
| Exempt from Federal Taxes | 66,687 | 519 | 3.12 | 85,766 | 561 | 2.62 | |||||||||||||||||||||||||||||
Loans (1) | 3,466,810 | 47,181 | 5.46 | 3,415,140 | 45,600 | 5.36 | |||||||||||||||||||||||||||||
Total Earning Assets (1) | 4,211,209 | 53,617 | 5.11 | 4,142,993 | 51,573 | 4.99 | |||||||||||||||||||||||||||||
| Allowance for Credit Losses | (34,305) | (35,238) | |||||||||||||||||||||||||||||||||
| Cash and Due From Banks | 29,874 | 29,267 | |||||||||||||||||||||||||||||||||
| Other Assets | 219,043 | 195,317 | |||||||||||||||||||||||||||||||||
| Total Assets | $ | 4,425,821 | $ | 4,332,339 | |||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
| Interest-Bearing Checking Accounts | $ | 827,385 | 2,162 | 1.05 | $ | 845,041 | 1,941 | 0.92 | |||||||||||||||||||||||||||
| Savings Deposits | 1,596,055 | 8,933 | 2.24 | 1,494,930 | 9,367 | 2.51 | |||||||||||||||||||||||||||||
| Time Deposits over $250,000 | 139,256 | 1,052 | 3.03 | 179,980 | 1,726 | 3.85 | |||||||||||||||||||||||||||||
| Other Time Deposits | 510,936 | 4,304 | 3.38 | 638,376 | 5,793 | 3.64 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 3,073,632 | 16,451 | 2.15 | 3,158,327 | 18,827 | 2.39 | |||||||||||||||||||||||||||||
| Borrowings | 124,411 | 1,019 | 3.29 | 8,601 | — | — | |||||||||||||||||||||||||||||
| Junior Subordinated Obligations Issued to Unconsolidated Subsidiary Trusts | 20,000 | 171 | 3.43 | 20,000 | 171 | 3.43 | |||||||||||||||||||||||||||||
| Finance Leases | 4,896 | 45 | 3.69 | 4,978 | 42 | 3.38 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Liabilities | 3,222,939 | 17,686 | 2.20 | 3,191,906 | 19,040 | 2.39 | |||||||||||||||||||||||||||||
| Noninterest-Bearing Deposits | 715,329 | 690,766 | |||||||||||||||||||||||||||||||||
| Other Liabilities | 41,666 | 43,138 | |||||||||||||||||||||||||||||||||
| Total Liabilities | 3,979,934 | 3,925,810 | |||||||||||||||||||||||||||||||||
| Stockholders’ Equity | 445,887 | 406,529 | |||||||||||||||||||||||||||||||||
| Total Liabilities and Stockholders’ Equity | $ | 4,425,821 | $ | 4,332,339 | |||||||||||||||||||||||||||||||
| Net Interest Income | $ | 35,931 | $ | 32,533 | |||||||||||||||||||||||||||||||
| Net Interest Spread | 2.91 | % | 2.60 | % | |||||||||||||||||||||||||||||||
| Net Interest Margin | 3.42 | % | 3.15 | % | |||||||||||||||||||||||||||||||
(1) Includes Nonaccrual Loans.
11
Arrow Financial Corporation
Average Consolidated Balance Sheets and Net Interest Income Analysis
(Dollars in Thousands - Unaudited)
| Quarter Ended: | June 30, 2026 | March 31, 2026 | |||||||||||||||||||||||||||||||||
| Interest | Rate | Interest | Rate | ||||||||||||||||||||||||||||||||
| Average | Income/ | Earned/ | Average | Income/ | Earned/ | ||||||||||||||||||||||||||||||
| Balance | Expense | Paid | Balance | Expense | Paid | ||||||||||||||||||||||||||||||
| Interest-Earning Deposits at Banks | $ | 129,628 | $ | 1,200 | 3.71 | % | $ | 183,252 | $ | 1,675 | 3.71 | % | |||||||||||||||||||||||
| Investment Securities: | |||||||||||||||||||||||||||||||||||
| Fully Taxable | 548,084 | 4,717 | 3.45 | 536,293 | 4,529 | 3.42 | |||||||||||||||||||||||||||||
| Exempt from Federal Taxes | 66,687 | 519 | 3.12 | 62,524 | 464 | 3.01 | |||||||||||||||||||||||||||||
Loans (1) | 3,466,810 | 47,181 | 5.46 | 3,440,505 | 47,126 | 5.56 | |||||||||||||||||||||||||||||
Total Earning Assets (1) | 4,211,209 | 53,617 | 5.11 | 4,222,574 | 53,794 | 5.17 | |||||||||||||||||||||||||||||
| Allowance for Credit Losses | (34,305) | (34,370) | |||||||||||||||||||||||||||||||||
| Cash and Due From Banks | 29,874 | 30,253 | |||||||||||||||||||||||||||||||||
| Other Assets | 219,043 | 221,376 | |||||||||||||||||||||||||||||||||
| Total Assets | $ | 4,425,821 | $ | 4,439,833 | |||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
| Interest-Bearing Checking Accounts | $ | 827,385 | 2,162 | 1.05 | $ | 859,054 | 2,100 | 0.99 | |||||||||||||||||||||||||||
| Savings Deposits | 1,596,055 | 8,933 | 2.24 | 1,570,598 | 8,716 | 2.25 | |||||||||||||||||||||||||||||
| Time Deposits over $250,000 | 139,256 | 1,052 | 3.03 | 147,425 | 1,196 | 3.29 | |||||||||||||||||||||||||||||
| Other Time Deposits | 510,936 | 4,304 | 3.38 | 638,451 | 5,436 | 3.45 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 3,073,632 | 16,451 | 2.15 | 3,215,528 | 17,448 | 2.20 | |||||||||||||||||||||||||||||
| Borrowings | 124,411 | 1,019 | 3.29 | 4,265 | — | — | |||||||||||||||||||||||||||||
| Junior Subordinated Obligations Issued to Unconsolidated Subsidiary Trusts | 20,000 | 171 | 3.43 | 20,000 | 169 | 3.43 | |||||||||||||||||||||||||||||
| Finance Leases | 4,896 | 45 | 3.69 | 4,916 | 47 | 3.88 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Liabilities | 3,222,939 | 17,686 | 2.20 | 3,244,709 | 17,664 | 2.21 | |||||||||||||||||||||||||||||
| Noninterest-Bearing Deposits | 715,329 | 713,233 | |||||||||||||||||||||||||||||||||
| Other Liabilities | 41,666 | 43,045 | |||||||||||||||||||||||||||||||||
| Total Liabilities | 3,979,934 | 4,000,987 | |||||||||||||||||||||||||||||||||
| Stockholders’ Equity | 445,887 | 438,846 | |||||||||||||||||||||||||||||||||
| Total Liabilities and Stockholders’ Equity | $ | 4,425,821 | $ | 4,439,833 | |||||||||||||||||||||||||||||||
| Net Interest Income | $ | 35,931 | $ | 36,130 | |||||||||||||||||||||||||||||||
| Net Interest Spread | 2.91 | % | 2.96 | % | |||||||||||||||||||||||||||||||
| Net Interest Margin | 3.42 | % | 3.47 | % | |||||||||||||||||||||||||||||||
(1) Includes Nonaccrual Loans.
12
Arrow Financial Corporation
Average Consolidated Balance Sheets and Net Interest Income Analysis
(Dollars in Thousands - Unaudited)
| Year to Date Period Ended: | June 30, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||
| Interest | Rate | Interest | Rate | ||||||||||||||||||||||||||||||||
| Average | Income/ | Earned/ | Average | Income/ | Earned/ | ||||||||||||||||||||||||||||||
| Balance | Expense | Paid | Balance | Expense | Paid | ||||||||||||||||||||||||||||||
| Interest-Earning Deposits at Banks | $ | 156,292 | $ | 2,875 | 3.71 | % | $ | 145,746 | $ | 3,243 | 4.49 | % | |||||||||||||||||||||||
| Investment Securities: | |||||||||||||||||||||||||||||||||||
| Fully Taxable | 542,221 | 9,246 | 3.44 | 498,250 | 7,398 | 2.99 | |||||||||||||||||||||||||||||
| Exempt from Federal Taxes | 64,617 | 983 | 3.07 | 88,835 | 1,148 | 2.61 | |||||||||||||||||||||||||||||
Loans (1) | 3,453,730 | 94,307 | 5.51 | 3,410,632 | 90,150 | 5.33 | |||||||||||||||||||||||||||||
Total Earning Assets (1) | 4,216,860 | 107,411 | 5.14 | 4,143,463 | 101,939 | 4.96 | |||||||||||||||||||||||||||||
| Allowance for Credit Losses | (34,338) | (34,469) | |||||||||||||||||||||||||||||||||
| Cash and Due From Banks | 30,062 | 30,385 | |||||||||||||||||||||||||||||||||
| Other Assets | 220,117 | 189,269 | |||||||||||||||||||||||||||||||||
| Total Assets | $ | 4,432,701 | $ | 4,328,648 | |||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||
| Interest-Bearing Checking Accounts | $ | 843,132 | 4,262 | 1.02 | $ | 842,818 | 3,744 | 0.90 | |||||||||||||||||||||||||||
| Savings Deposits | 1,583,396 | 17,649 | 2.25 | 1,505,387 | 18,850 | 2.53 | |||||||||||||||||||||||||||||
| Time Deposits over $250,000 | 143,318 | 2,248 | 3.16 | 183,053 | 3,537 | 3.90 | |||||||||||||||||||||||||||||
| Other Time Deposits | 574,341 | 9,740 | 3.42 | 615,878 | 11,322 | 3.71 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 3,144,187 | 33,899 | 2.17 | 3,147,136 | 37,453 | 2.40 | |||||||||||||||||||||||||||||
| Borrowings | 64,671 | 1,019 | 3.18 | 15,949 | 167 | 2.11 | |||||||||||||||||||||||||||||
| Junior Subordinated Obligations Issued to Unconsolidated Subsidiary Trusts | 20,000 | 340 | 3.43 | 20,000 | 340 | 3.43 | |||||||||||||||||||||||||||||
| Finance Leases | 4,905 | 92 | 3.78 | 4,987 | 89 | 3.60 | |||||||||||||||||||||||||||||
| Total Interest-Bearing Liabilities | 3,233,763 | 35,350 | 2.20 | 3,188,072 | 38,049 | 2.41 | |||||||||||||||||||||||||||||
| Noninterest-Bearing Deposits | 714,287 | 690,039 | |||||||||||||||||||||||||||||||||
| Other Liabilities | 42,264 | 45,069 | |||||||||||||||||||||||||||||||||
| Total Liabilities | 3,990,314 | 3,923,180 | |||||||||||||||||||||||||||||||||
| Stockholders’ Equity | 442,387 | 405,468 | |||||||||||||||||||||||||||||||||
| Total Liabilities and Stockholders’ Equity | $ | 4,432,701 | $ | 4,328,648 | |||||||||||||||||||||||||||||||
| Net Interest Income | $ | 72,061 | $ | 63,890 | |||||||||||||||||||||||||||||||
| Net Interest Spread | 2.94 | % | 2.55 | % | |||||||||||||||||||||||||||||||
| Net Interest Margin | 3.45 | % | 3.11 | % | |||||||||||||||||||||||||||||||
| (1) Includes Nonaccrual Loans. | |||||||||||||||||||||||||||||||||||
13
Arrow Financial Corporation
Consolidated Financial Information
(Dollars in Thousands - Unaudited)
| Quarter Ended: | 6/30/2026 | 12/31/2025 | |||||||||
| Loan Portfolio | |||||||||||
| Commercial Loans | $ | 173,057 | $ | 165,729 | |||||||
| Commercial Real Estate Loans | 837,461 | 818,259 | |||||||||
| Subtotal Commercial Loan Portfolio | 1,010,518 | 983,988 | |||||||||
| Consumer Loans | 1,083,169 | 1,076,007 | |||||||||
| Residential Real Estate Loans | 1,402,854 | 1,393,098 | |||||||||
| Total Loans | $ | 3,496,541 | $ | 3,453,093 | |||||||
| Allowance for Credit Losses | |||||||||||
| Allowance for Credit Losses, Beginning of Quarter | $ | 34,055 | $ | 34,176 | |||||||
| Loans Charged-off | (1,770) | (1,477) | |||||||||
| Less Recoveries of Loans Previously Charged-off | 1,071 | 777 | |||||||||
| Net Loans Charged-off | (699) | (700) | |||||||||
| Provision for Credit Losses | 2,827 | 846 | |||||||||
| Allowance for Credit Losses, End of Quarter | $ | 36,183 | $ | 34,322 | |||||||
| Nonperforming Assets | |||||||||||
| Nonaccrual Loans | $ | 6,814 | $ | 6,415 | |||||||
| Loans Past Due 90 or More Days and Accruing | 1,487 | 2,040 | |||||||||
| Loans Restructured and in Compliance with Modified Terms | — | — | |||||||||
| Total Nonperforming Loans | 8,301 | 8,455 | |||||||||
| Repossessed Assets | 363 | 280 | |||||||||
| Other Real Estate Owned | — | — | |||||||||
| Total Nonperforming Assets | $ | 8,664 | $ | 8,735 | |||||||
| Key Asset Quality Ratios | |||||||||||
| Net Loans Charged-off to Average Loans, Quarter-to-date Annualized | 0.08 | % | 0.08 | % | |||||||
| Provision for Credit Losses to Average Loans, Quarter-to-date Annualized | 0.33 | % | 0.10 | % | |||||||
| Allowance for Credit Losses to Period-End Loans | 1.03 | % | 0.99 | % | |||||||
| Allowance for Credit Losses to Period-End Nonperforming Loans | 435.89 | % | 405.94 | % | |||||||
| Nonperforming Loans to Period-End Loans | 0.24 | % | 0.24 | % | |||||||
| Nonperforming Assets to Period-End Assets | 0.19 | % | 0.20 | % | |||||||
| Year-to-Date Period Ended: | 6/30/2026 | 12/31/2025 | |||||||||
| Allowance for Credit Losses | |||||||||||
| Allowance for Credit Losses, Beginning of Year | $ | 34,322 | $ | 33,598 | |||||||
| Loans Charged-off | (3,344) | (9,554) | |||||||||
| Less Recoveries of Loans Previously Charged-off | 1,830 | 3,004 | |||||||||
| Net Loans Charged-off | (1,514) | (6,550) | |||||||||
| Provision for Credit Losses | 3,375 | 7,274 | |||||||||
| Allowance for Credit Losses, End of Period | $ | 36,183 | $ | 34,322 | |||||||
| Key Asset Quality Ratios | |||||||||||
| Net Loans Charged-off to Average Loans, Annualized | 0.09 | % | 0.19 | % | |||||||
| Provision for Loan Losses to Average Loans, Annualized | 0.20 | % | 0.21 | % | |||||||
14
2Q 2026 July 23, 2026 1
The information contained in this investor presentation may contain statements that are not historical in nature but rather are based on management’s beliefs, assumptions, expectations, estimates and projections about the future. These statements can sometimes be identified by Arrow’s use of forward- looking words such as “may,” “will,” “anticipate,” “estimate,” “expect,” or “intend.” These statements may be “forward-looking statements” within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended, involving a degree of uncertainty and attendant risk. In the case of all forward- looking statements, actual outcomes and results may differ materially from what the statements predict or forecast, explicitly or by implication, because of various factors, including changes in economic conditions or interest rates, credit risk, inflation, tariffs, cybersecurity risks, changes in FDIC assessments, bank failures, geopolitical events, difficulties in managing Arrow’s growth, competition, changes in law or the regulatory environment, risks related to the integration of Adirondack Bancorp, Inc. and changes in general business and economic trends. Arrow undertakes no obligation to revise or update these forward-looking statements to reflect the occurrence of unanticipated events. This document should be read in conjunction with the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 (the “2025 10-K”), other filings with the SEC and the second quarter 2026 earnings release issued July 23, 2026. This presentation makes use of certain non-GAAP terms and metrics commonly accepted and widely used within the banking industry, including, but not limited to, Tangible Book Value per Share (TBV/Share), Full Tax Equivalent (FTE), Tangible Common Equity (TCE), and Efficiency Ratio. Please refer to the Appendix to this presentation for a reconciliation of any non-GAAP measures. 2 Safe Harbor
This presentation makes use of certain financial terms and non-GAAP measures, described below, commonly accepted and widely used within the banking industry. Please refer to the Appendix to this presentation for a reconciliation of any non-GAAP measures. • Tangible Book Value per Share (TBV/Share) • Full Tax Equivalent (FTE) • Tangible Common Equity (TCE) • Efficiency Ratio • Net Interest Margin (NIM) • Effective Tax Rate (ETR) • Merger-Related Expenses (MRE) • Return on Average Assets (ROA) • Return on Average Equity (ROE) • Allowance for Credit Losses (ACL) • Assets Under Management (AUM) • Available for Sale (AFS) • Held-to-Maturity (HTM) • Non-Performing Loans (NPL) 3 Glossary of Terms and Non-GAAP Measures
• 2Q26 Results and Performance Metrics • Non-Interest Income/Expense • Loans • Deposits/Funding Sources • Credit Quality & Provision for Credit Losses • Investments • Capital • M&A Update (Acquisition of Adirondack Bancorp, Inc.) • Overview and History 4 Table of Contents
RESULTS 5
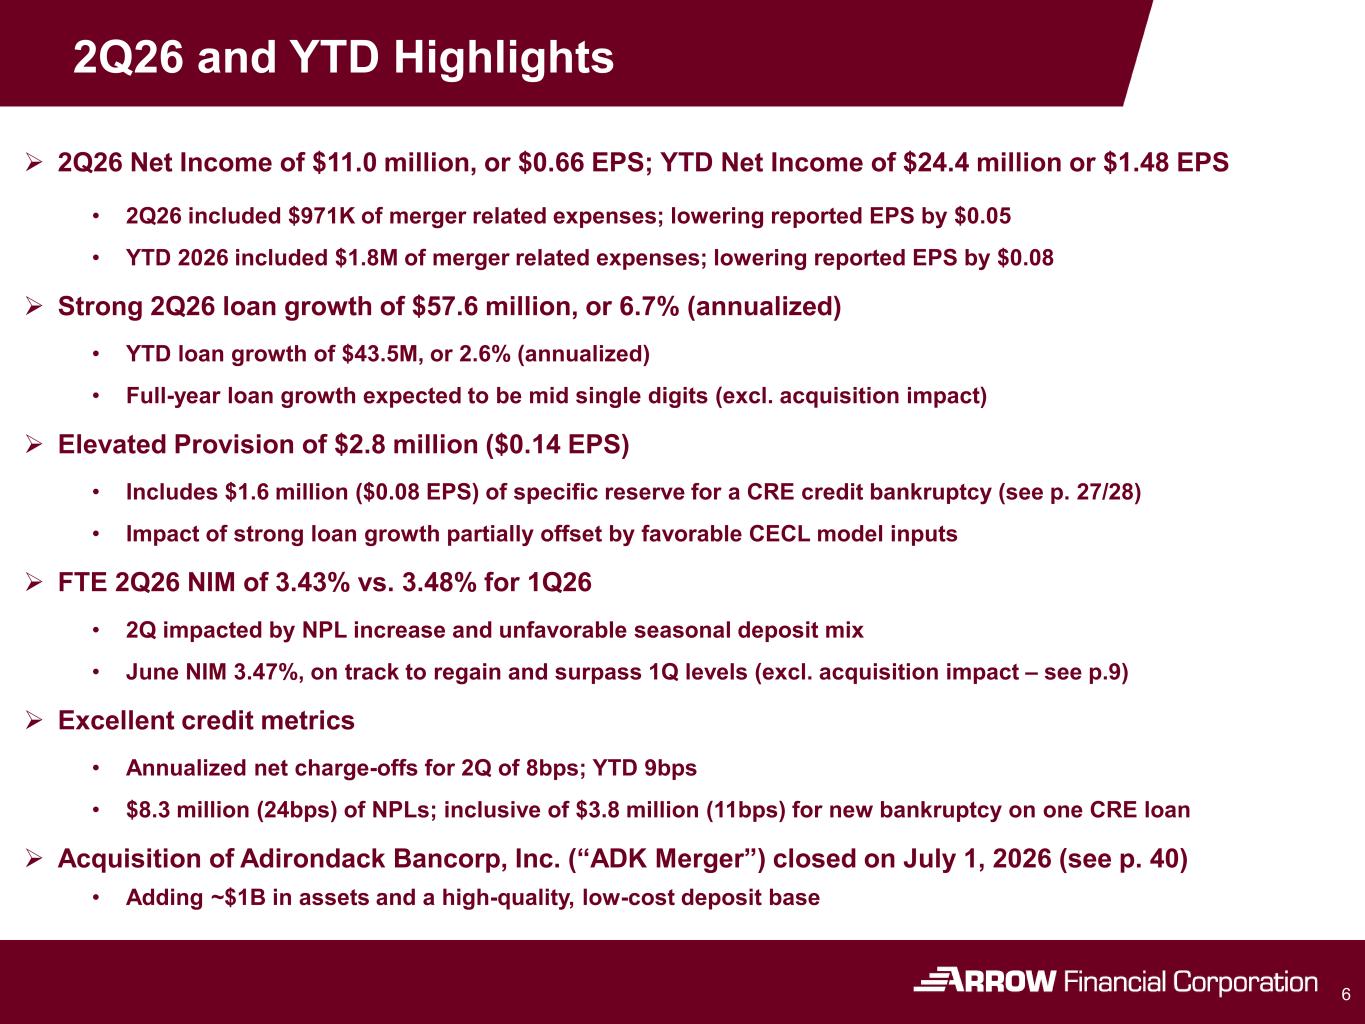
2Q26 and YTD Highlights 2Q26 Net Income of $11.0 million, or $0.66 EPS; YTD Net Income of $24.4 million or $1.48 EPS • 2Q26 included $971K of merger related expenses; lowering reported EPS by $0.05 • YTD 2026 included $1.8M of merger related expenses; lowering reported EPS by $0.08 Strong 2Q26 loan growth of $57.6 million, or 6.7% (annualized) • YTD loan growth of $43.5M, or 2.6% (annualized) • Full-year loan growth expected to be mid single digits (excl. acquisition impact) Elevated Provision of $2.8 million ($0.14 EPS) • Includes $1.6 million ($0.08 EPS) of specific reserve for a CRE credit bankruptcy (see p. 27/28) • Impact of strong loan growth partially offset by favorable CECL model inputs FTE 2Q26 NIM of 3.43% vs. 3.48% for 1Q26 • 2Q impacted by NPL increase and unfavorable seasonal deposit mix • June NIM 3.47%, on track to regain and surpass 1Q levels (excl. acquisition impact – see p.9) Excellent credit metrics • Annualized net charge-offs for 2Q of 8bps; YTD 9bps • $8.3 million (24bps) of NPLs; inclusive of $3.8 million (11bps) for new bankruptcy on one CRE loan Acquisition of Adirondack Bancorp, Inc. (“ADK Merger”) closed on July 1, 2026 (see p. 40) • Adding ~$1B in assets and a high-quality, low-cost deposit base 6
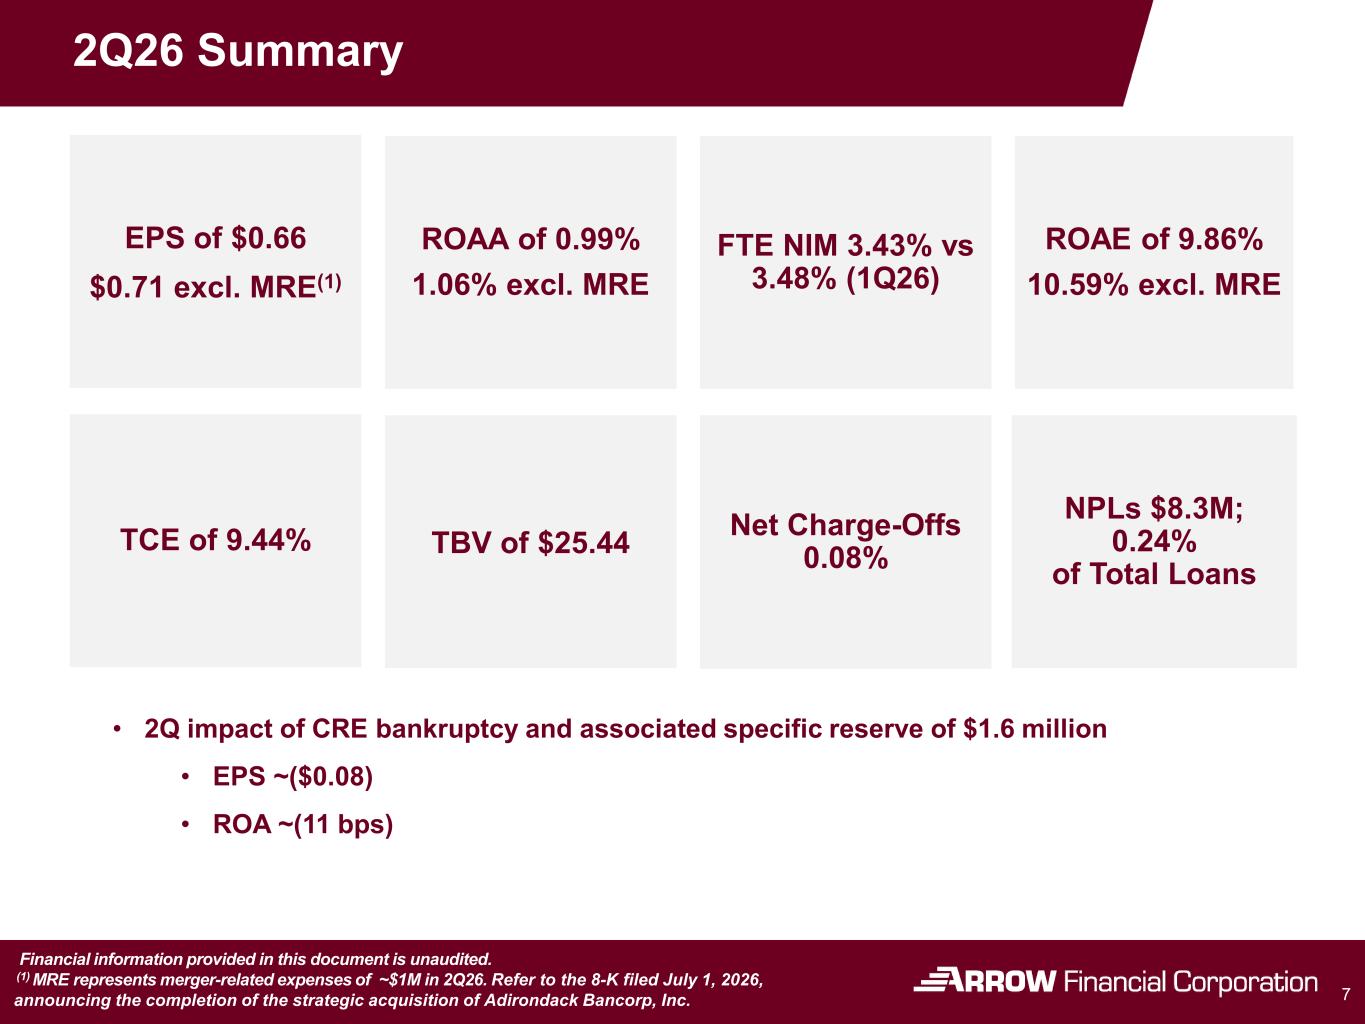
2Q26 Summary 7 EPS of $0.66 $0.71 excl. MRE(1) ROAA of 0.99% 1.06% excl. MRE FTE NIM 3.43% vs 3.48% (1Q26) TBV of $25.44 Net Charge-Offs 0.08% ROAE of 9.86% 10.59% excl. MRE NPLs $8.3M; 0.24% of Total Loans TCE of 9.44% Financial information provided in this document is unaudited. (1) MRE represents merger-related expenses of ~$1M in 2Q26. Refer to the 8-K filed July 1, 2026, announcing the completion of the strategic acquisition of Adirondack Bancorp, Inc. • 2Q impact of CRE bankruptcy and associated specific reserve of $1.6 million • EPS ~($0.08) • ROA ~(11 bps)
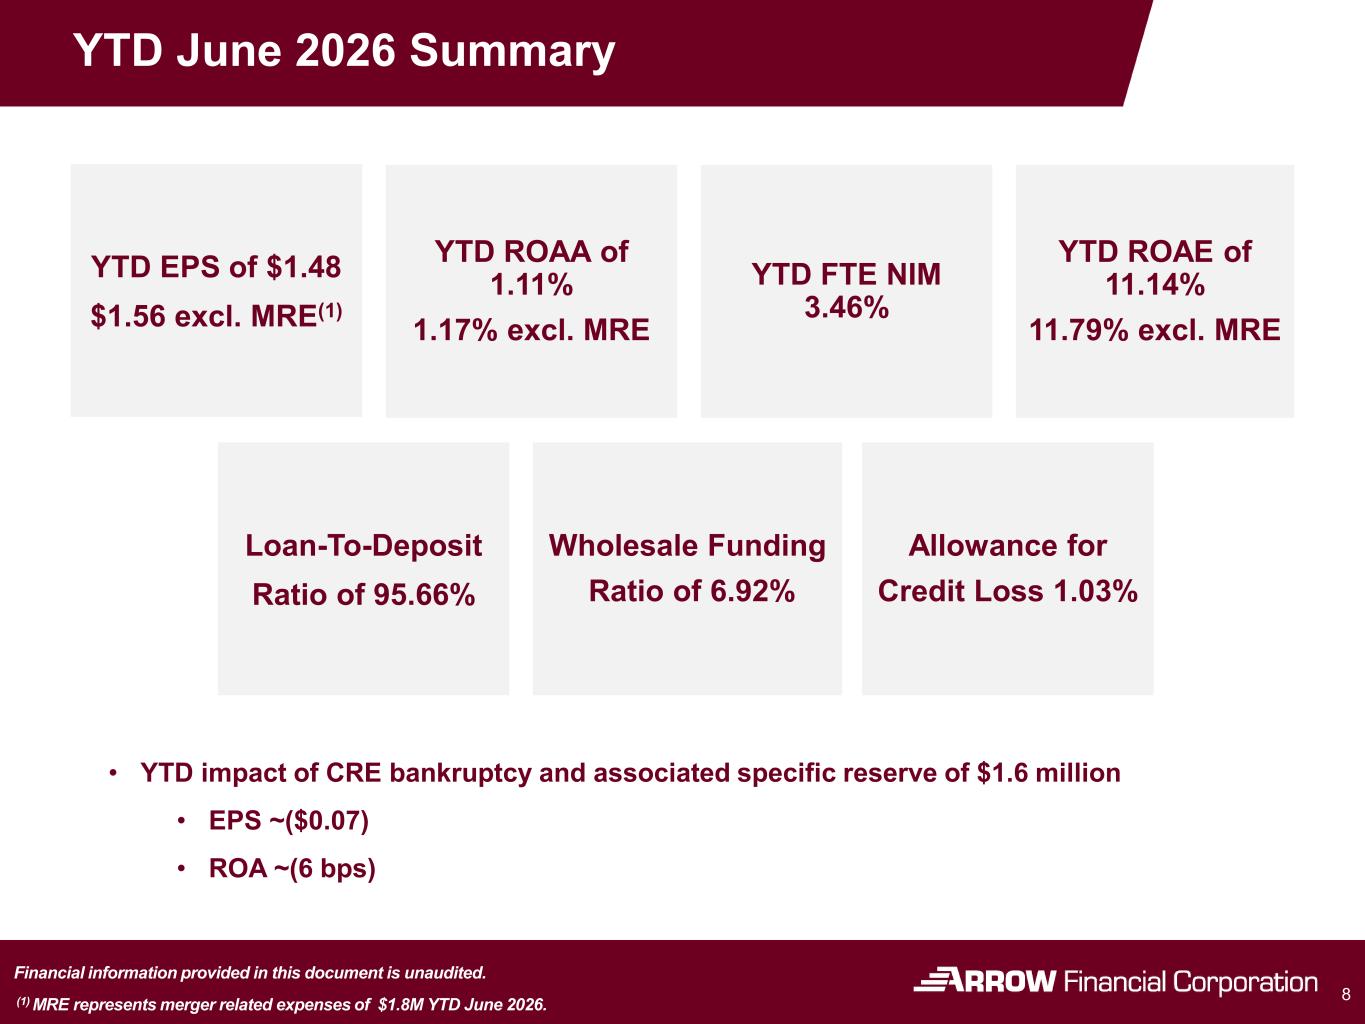
YTD June 2026 Summary 8 Financial information provided in this document is unaudited. (1) MRE represents merger related expenses of $1.8M YTD June 2026. YTD EPS of $1.48 $1.56 excl. MRE(1) YTD ROAA of 1.11% 1.17% excl. MRE YTD FTE NIM 3.46% YTD ROAE of 11.14% 11.79% excl. MRE • YTD impact of CRE bankruptcy and associated specific reserve of $1.6 million • EPS ~($0.07) • ROA ~(6 bps) Loan-To-Deposit Ratio of 95.66% Wholesale Funding Ratio of 6.92% Allowance for Credit Loss 1.03%
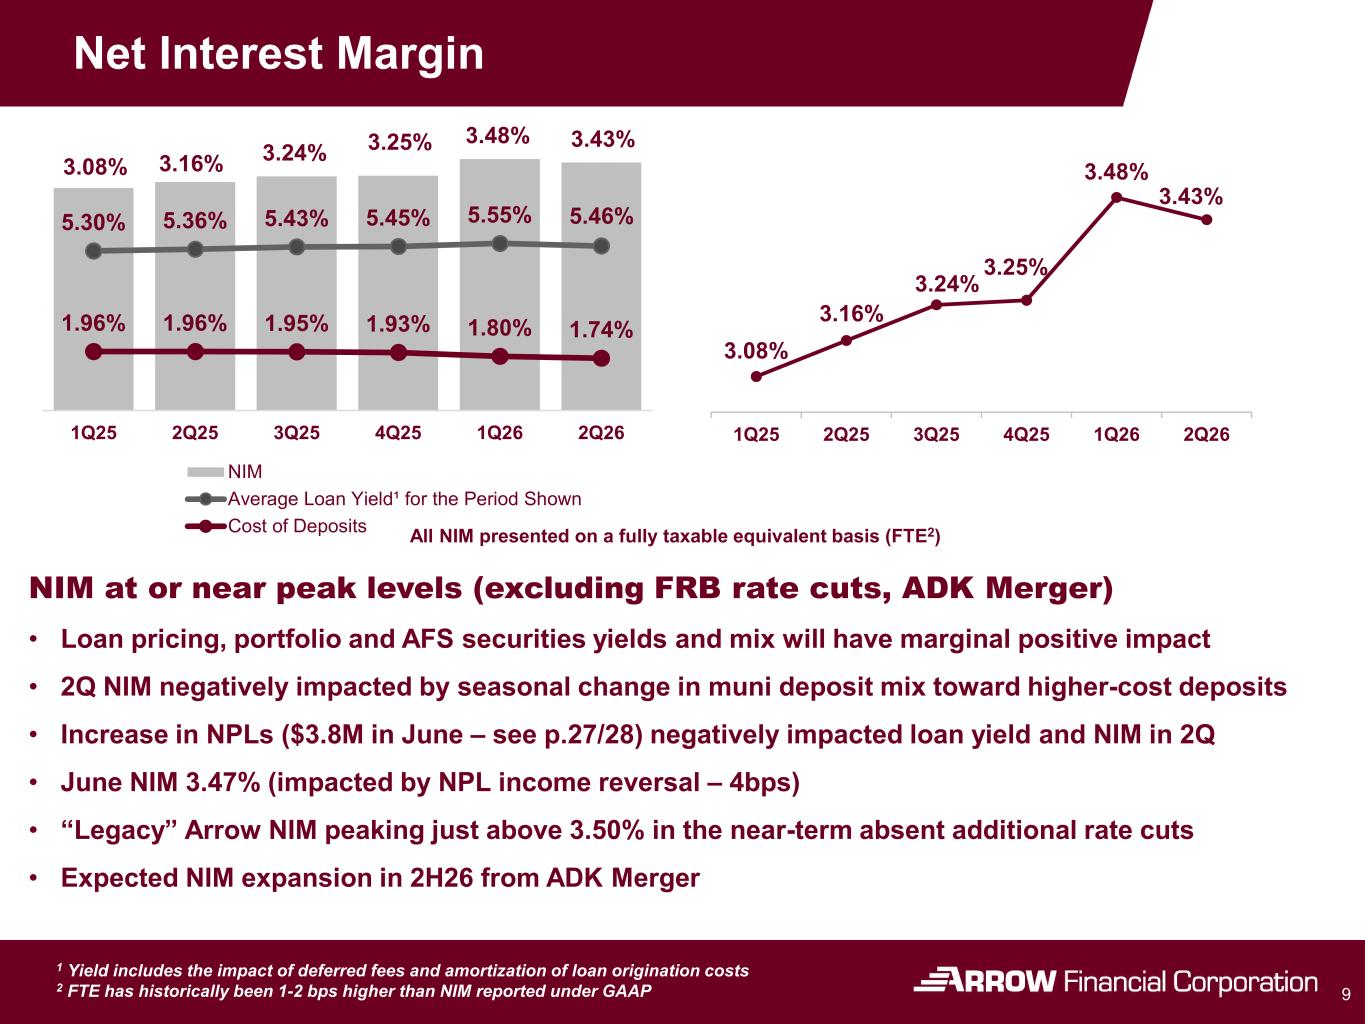
Net Interest Margin 9 1 Yield includes the impact of deferred fees and amortization of loan origination costs 2 FTE has historically been 1-2 bps higher than NIM reported under GAAP 3.08% 3.16% 3.24% 3.25% 3.48% 3.43% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3.08% 3.16% 3.24% 3.25% 3.48% 3.43% 5.30% 5.36% 5.43% 5.45% 5.55% 5.46% 1.96% 1.96% 1.95% 1.93% 1.80% 1.74% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 NIM Average Loan Yield¹ for the Period Shown Cost of Deposits NIM at or near peak levels (excluding FRB rate cuts, ADK Merger) • Loan pricing, portfolio and AFS securities yields and mix will have marginal positive impact • 2Q NIM negatively impacted by seasonal change in muni deposit mix toward higher-cost deposits • Increase in NPLs ($3.8M in June – see p.27/28) negatively impacted loan yield and NIM in 2Q • June NIM 3.47% (impacted by NPL income reversal – 4bps) • “Legacy” Arrow NIM peaking just above 3.50% in the near-term absent additional rate cuts • Expected NIM expansion in 2H26 from ADK Merger All NIM presented on a fully taxable equivalent basis (FTE2)
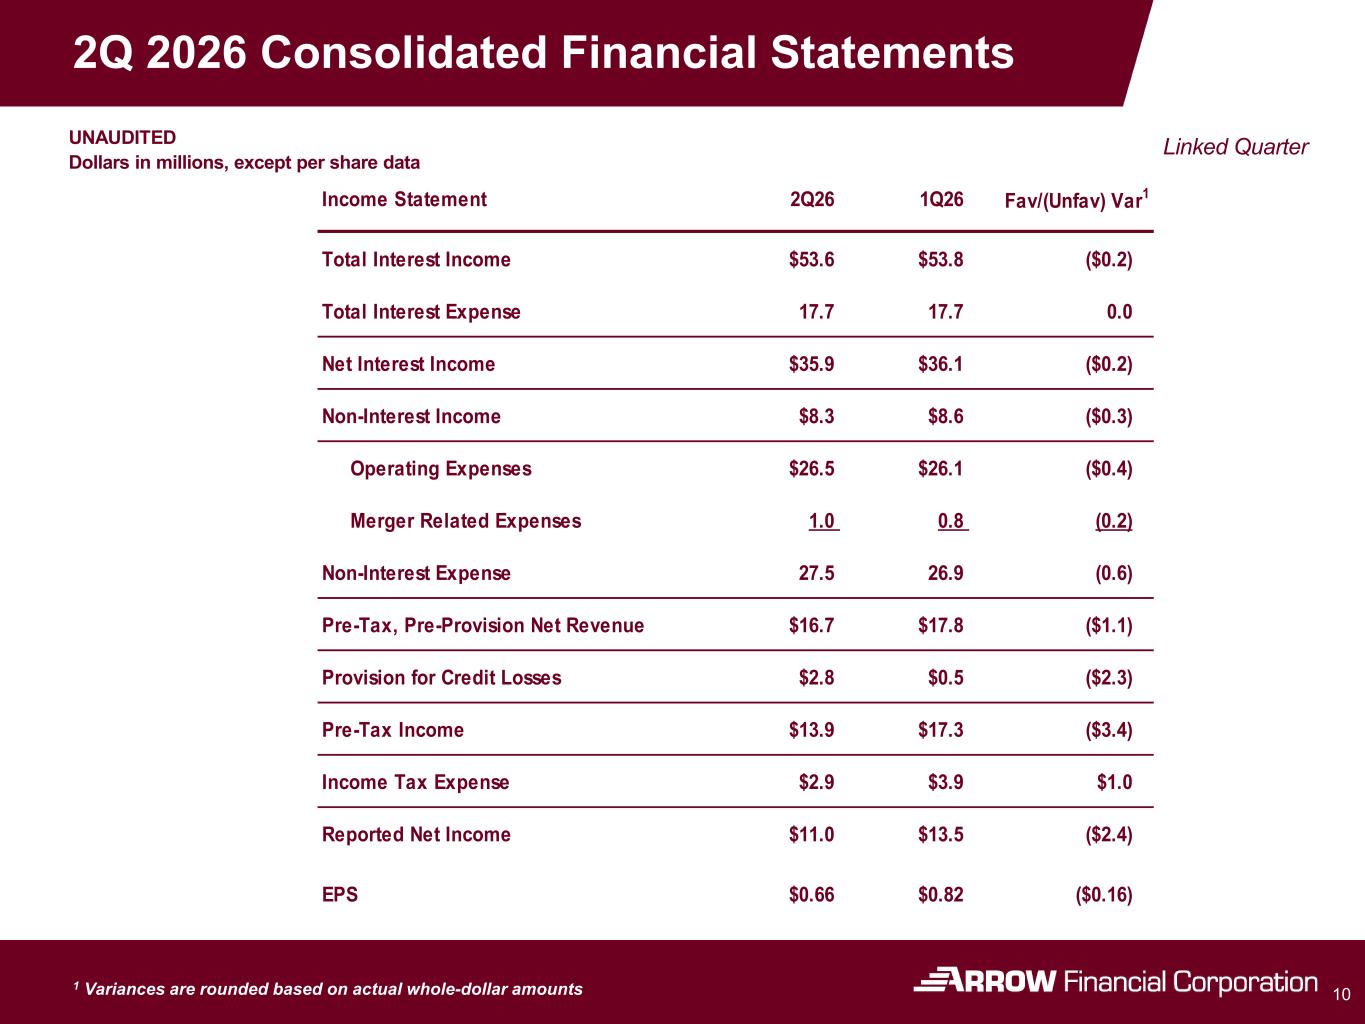
2Q 2026 Consolidated Financial Statements 101 Variances are rounded based on actual whole-dollar amounts UNAUDITED Dollars in millions, except per share data Linked Quarter Income Statement 2Q26 1Q26 Fav/(Unfav) Var1 Total Interest Income $53.6 $53.8 ($0.2) Total Interest Expense 17.7 17.7 0.0 Net Interest Income $35.9 $36.1 ($0.2) Non-Interest Income $8.3 $8.6 ($0.3) Operating Expenses $26.5 $26.1 ($0.4) Merger Related Expenses 1.0 0.8 (0.2) Non-Interest Expense 27.5 26.9 (0.6) Pre-Tax, Pre-Provision Net Revenue $16.7 $17.8 ($1.1) Provision for Credit Losses $2.8 $0.5 ($2.3) Pre-Tax Income $13.9 $17.3 ($3.4) Income Tax Expense $2.9 $3.9 $1.0 Reported Net Income $11.0 $13.5 ($2.4) EPS $0.66 $0.82 ($0.16)
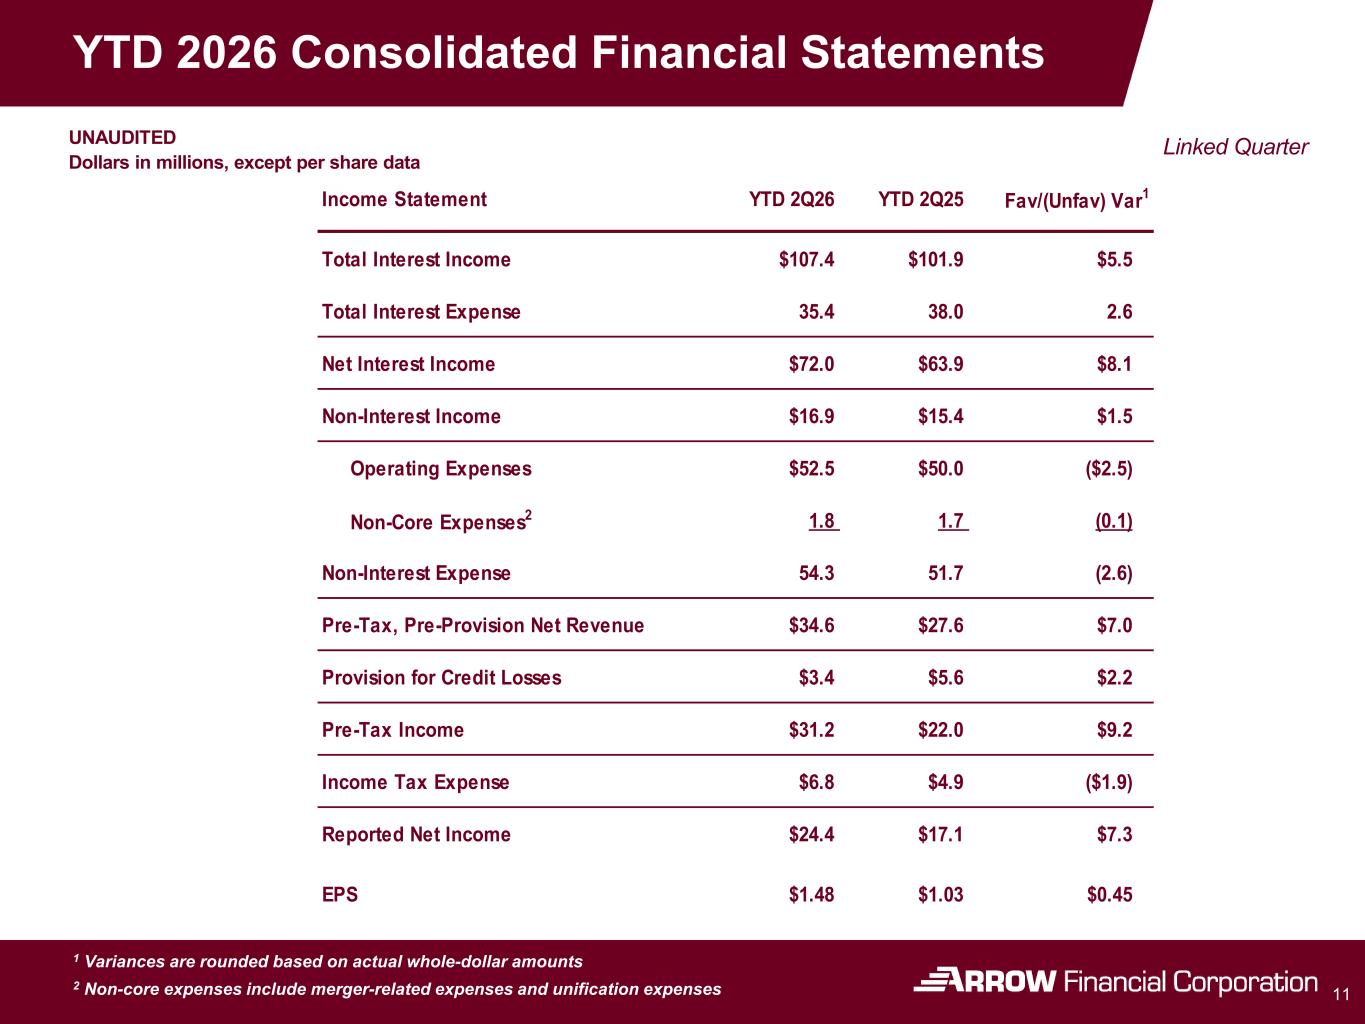
YTD 2026 Consolidated Financial Statements 11 1 Variances are rounded based on actual whole-dollar amounts 2 Non-core expenses include merger-related expenses and unification expenses UNAUDITED Dollars in millions, except per share data Linked Quarter Income Statement YTD 2Q26 YTD 2Q25 Fav/(Unfav) Var1 Total Interest Income $107.4 $101.9 $5.5 Total Interest Expense 35.4 38.0 2.6 Net Interest Income $72.0 $63.9 $8.1 Non-Interest Income $16.9 $15.4 $1.5 Operating Expenses $52.5 $50.0 ($2.5) Non-Core Expenses2 1.8 1.7 (0.1) Non-Interest Expense 54.3 51.7 (2.6) Pre-Tax, Pre-Provision Net Revenue $34.6 $27.6 $7.0 Provision for Credit Losses $3.4 $5.6 $2.2 Pre-Tax Income $31.2 $22.0 $9.2 Income Tax Expense $6.8 $4.9 ($1.9) Reported Net Income $24.4 $17.1 $7.3 EPS $1.48 $1.03 $0.45
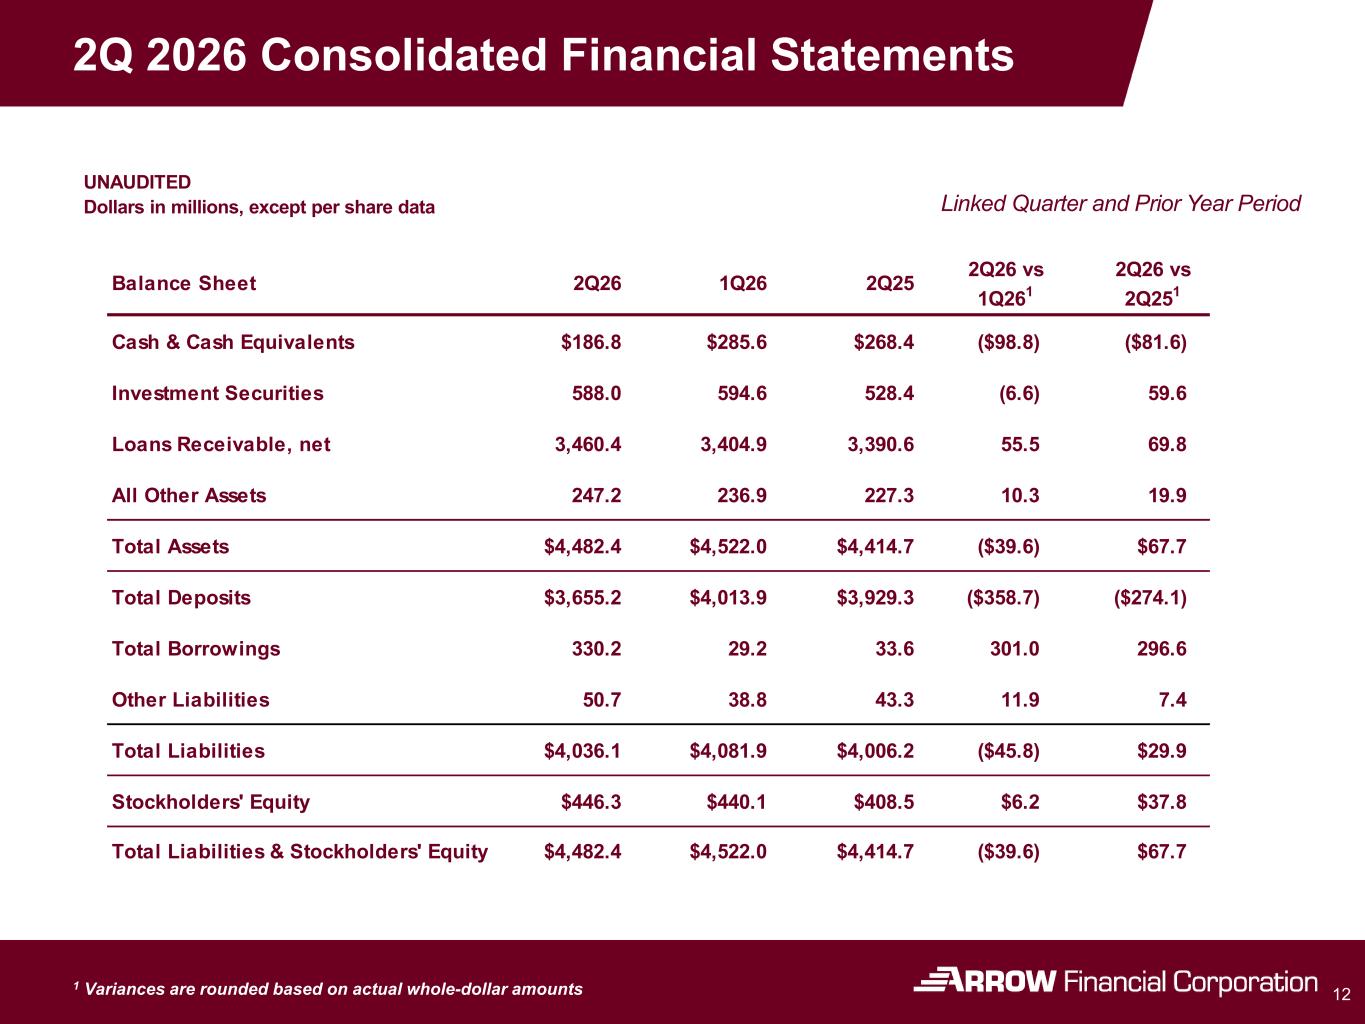
2Q 2026 Consolidated Financial Statements 121 Variances are rounded based on actual whole-dollar amounts 1 Variances are rounded based on actual whole-dollar amounts Linked Quarter and Prior Year Period UNAUDITED Dollars in millions, except per share data Balance Sheet 2Q26 1Q26 2Q25 2Q26 vs 1Q261 2Q26 vs 2Q251 Cash & Cash Equivalents $186.8 $285.6 $268.4 ($98.8) ($81.6) Investment Securities 588.0 594.6 528.4 (6.6) 59.6 Loans Receivable, net 3,460.4 3,404.9 3,390.6 55.5 69.8 All Other Assets 247.2 236.9 227.3 10.3 19.9 Total Assets $4,482.4 $4,522.0 $4,414.7 ($39.6) $67.7 Total Deposits $3,655.2 $4,013.9 $3,929.3 ($358.7) ($274.1) Total Borrowings 330.2 29.2 33.6 301.0 296.6 Other Liabilities 50.7 38.8 43.3 11.9 7.4 Total Liabilities $4,036.1 $4,081.9 $4,006.2 ($45.8) $29.9 Stockholders' Equity $446.3 $440.1 $408.5 $6.2 $37.8 Total Liabilitie & Stockholders' Equity $4,482.4 $4,522.0 $4,414.7 ($39.6) $67.7
NON-INTEREST INCOME/EXPENSE 13
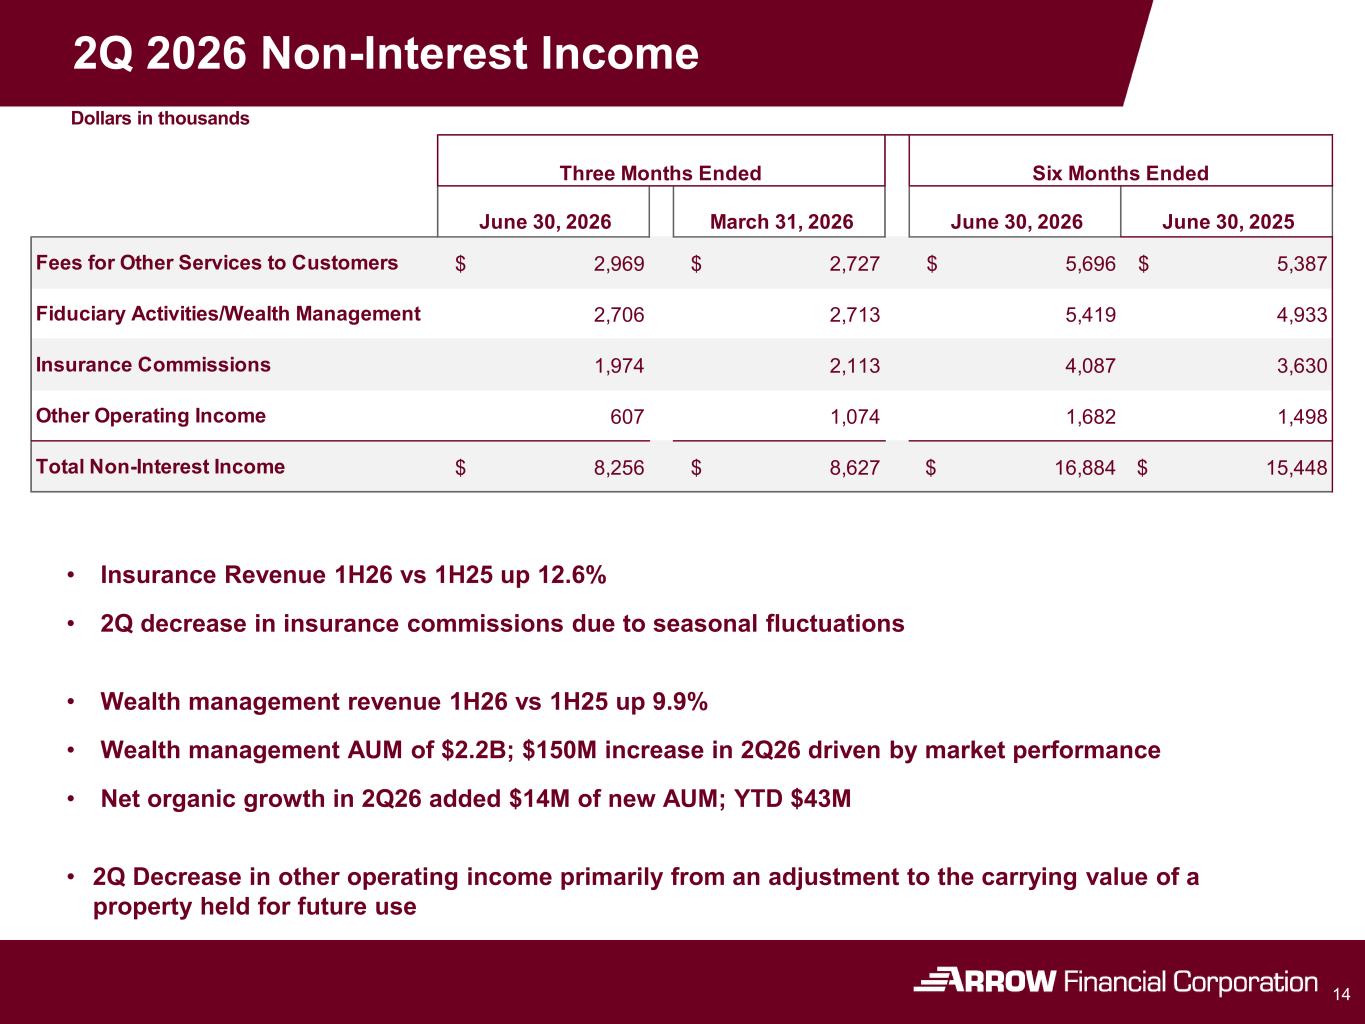
2Q 2026 Non-Interest Income 14 Dollars in thousands • Insurance Revenue 1H26 vs 1H25 up 12.6% • 2Q decrease in insurance commissions due to seasonal fluctuations • Wealth management revenue 1H26 vs 1H25 up 9.9% • Wealth management AUM of $2.2B; $150M increase in 2Q26 driven by market performance • Net organic growth in 2Q26 added $14M of new AUM; YTD $43M • 2Q Decrease in other operating income primarily from an adjustment to the carrying value of a property held for future use June 30, 2026 March 31, 2026 June 30, 2026 June 30, 2025 Fees for Other Services to Customers $ 2,969 $ 2,727 $ 5,696 $ 5,387 Fiduciary Activities/Wealth Management 2,706 2,713 5,419 4,933 Insurance Commissions 1,974 2,113 4,087 3,630 Other Operating Income 607 1,074 1,682 1,498 Total Non-Interest Income $ 8,256 $ 8,627 $ 16,884 $ 15,448 Three Months Ended Six Months Ended
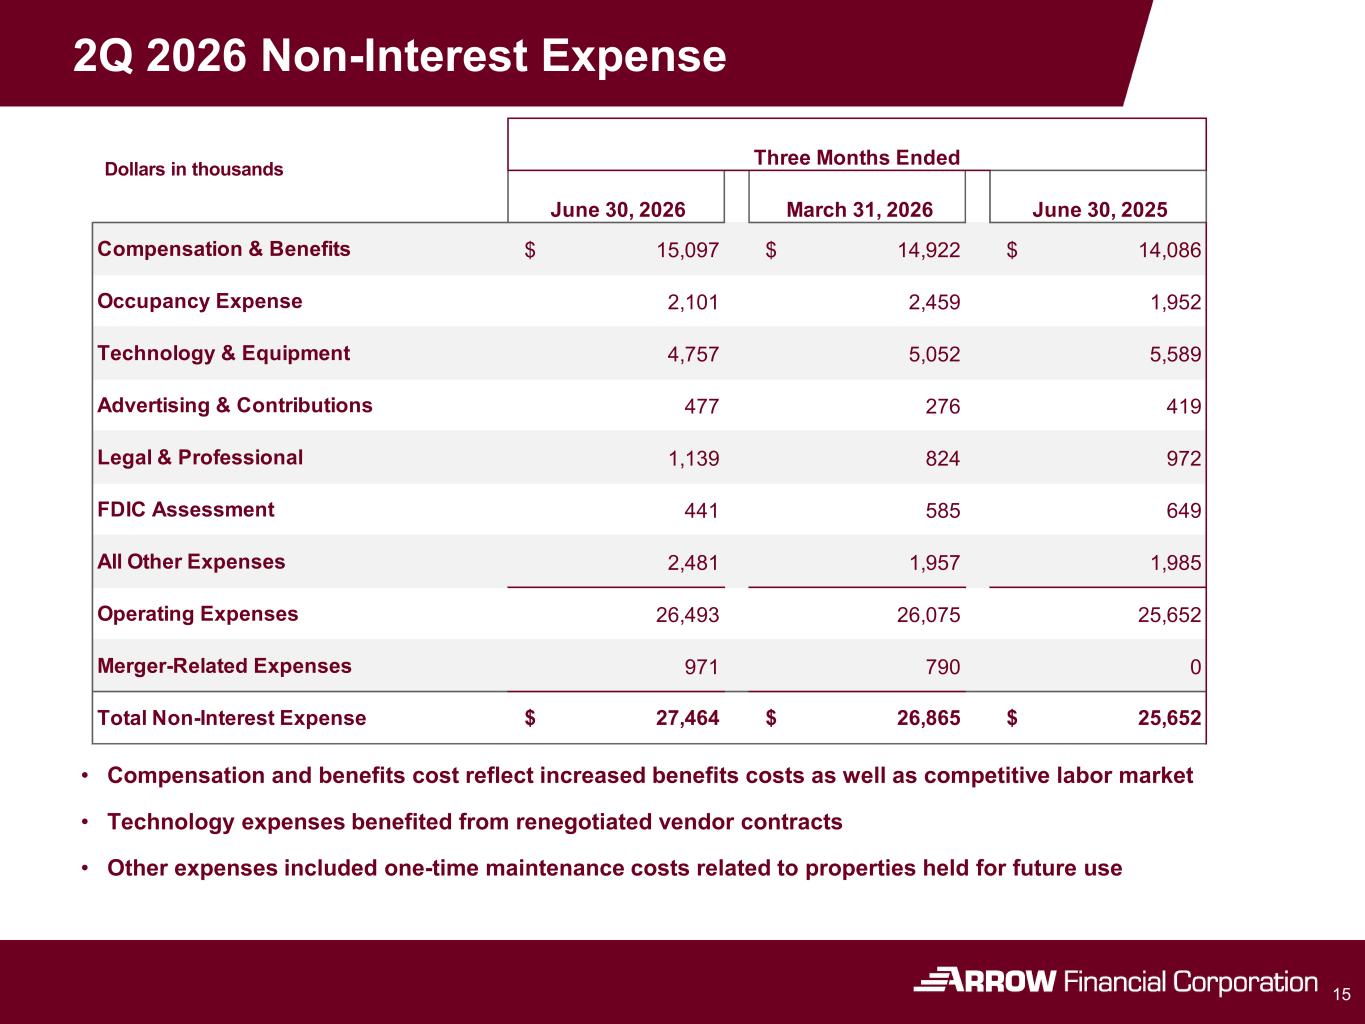
2Q 2026 Non-Interest Expense 15 • Compensation and benefits cost reflect increased benefits costs as well as competitive labor market • Technology expenses benefited from renegotiated vendor contracts • Other expenses included one-time maintenance costs related to properties held for future use Dollars in thousands June 30, 2026 March 31, 2026 June 30, 2025 Compensation & Benefits $ 15,097 $ 14,922 $ 14,086 Occupancy Expense 2,101 2,459 1,952 Technology & Equipment 4,757 5,052 5,589 Advertising & Contributions 477 276 419 Legal & Professional 1,139 824 972 FDIC Assessment 441 585 649 All Other Expenses 2,481 1,957 1,985 Operating Expenses 26,493 26,075 25,652 Merger-Related Expenses 971 790 0 Total Non-Interest Expense $ 27,464 $ 26,865 $ 25,652 Three Months Ended
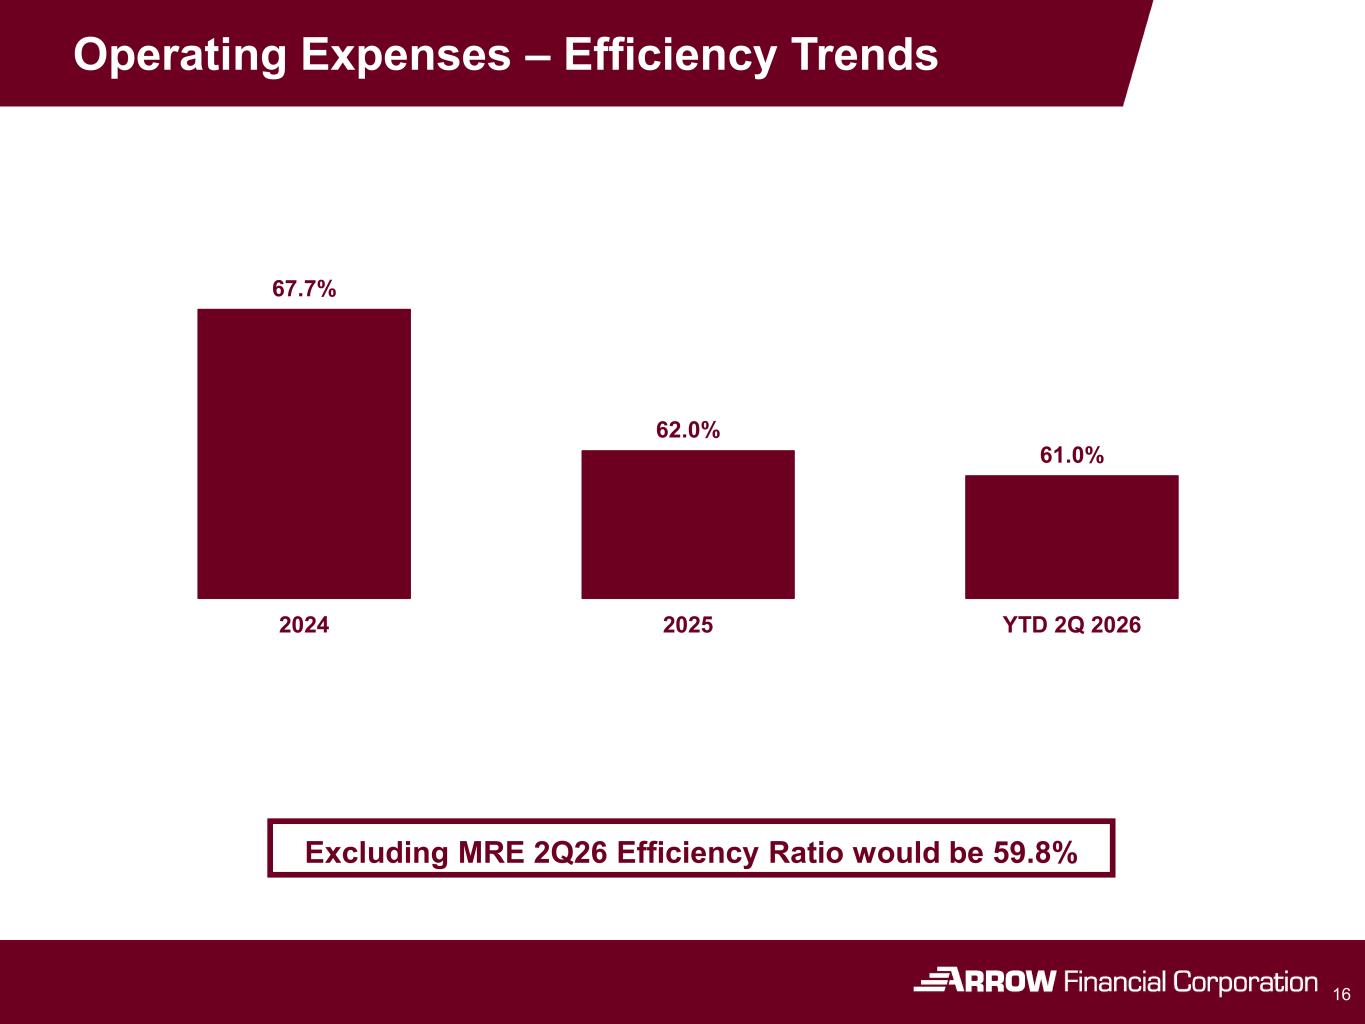
Operating Expenses – Efficiency Trends 16 67.7% 62.0% 61.0% 2024 2025 YTD 2Q 2026 Excluding MRE 2Q26 Efficiency Ratio would be 59.8%
LOANS 17
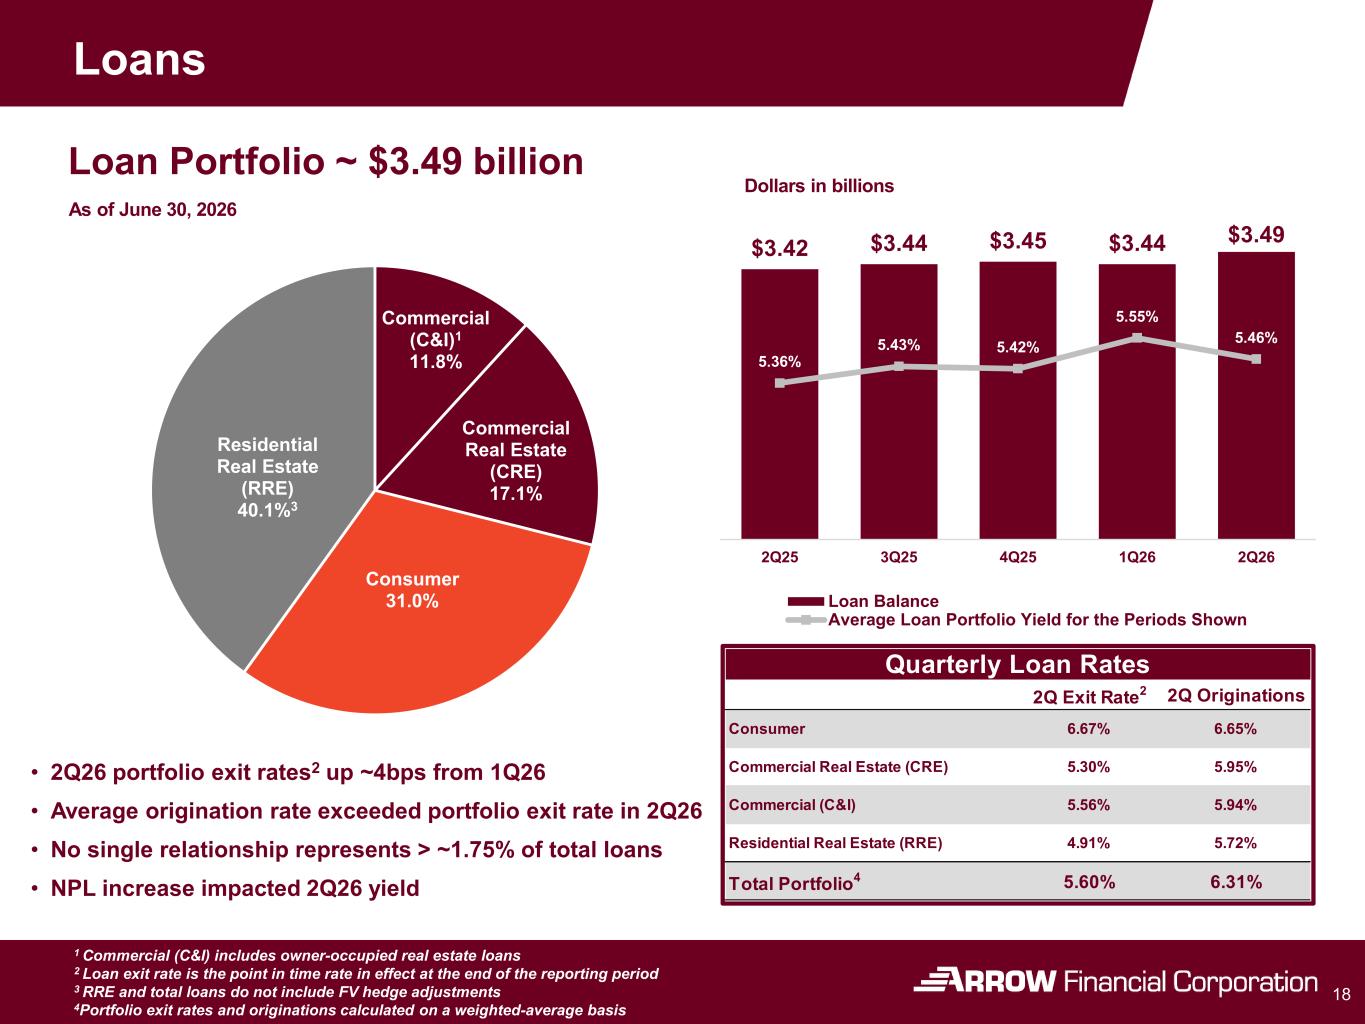
Commercial (C&I)1 11.8% Commercial Real Estate (CRE) 17.1% Consumer 31.0% Residential Real Estate (RRE) 40.1%3 Loans 18 Loan Portfolio ~ $3.49 billion As of June 30, 2026 • 2Q26 portfolio exit rates2 up ~4bps from 1Q26 • Average origination rate exceeded portfolio exit rate in 2Q26 • No single relationship represents > ~1.75% of total loans • NPL increase impacted 2Q26 yield $3.42 $3.44 $3.45 $3.44 $3.49 5.36% 5.43% 5.42% 5.55% 5.46% 2Q25 3Q25 4Q25 1Q26 2Q26 Loan Balance Average Loan Portfolio Yield for the Periods Shown Dollars in billions 1 Commercial (C&I) includes owner-occupied real estate loans 2 Loan exit rate is the point in time rate in effect at the end of the reporting period 3 RRE and total loans do not include FV hedge adjustments 4Portfolio exit rates and originations calculated on a weighted-average basis 2Q Exit Rate2 2Q Originations Consumer 6.67% 6.65% Commercial Real Estate (CRE) 5.30% 5.95% Commercial (C&I) 5.56% 5.94% Residential Real Estate (RRE) 4.91% 5.72% Total Portfolio4 5.60% 6.31% Quarterly Loan Rates
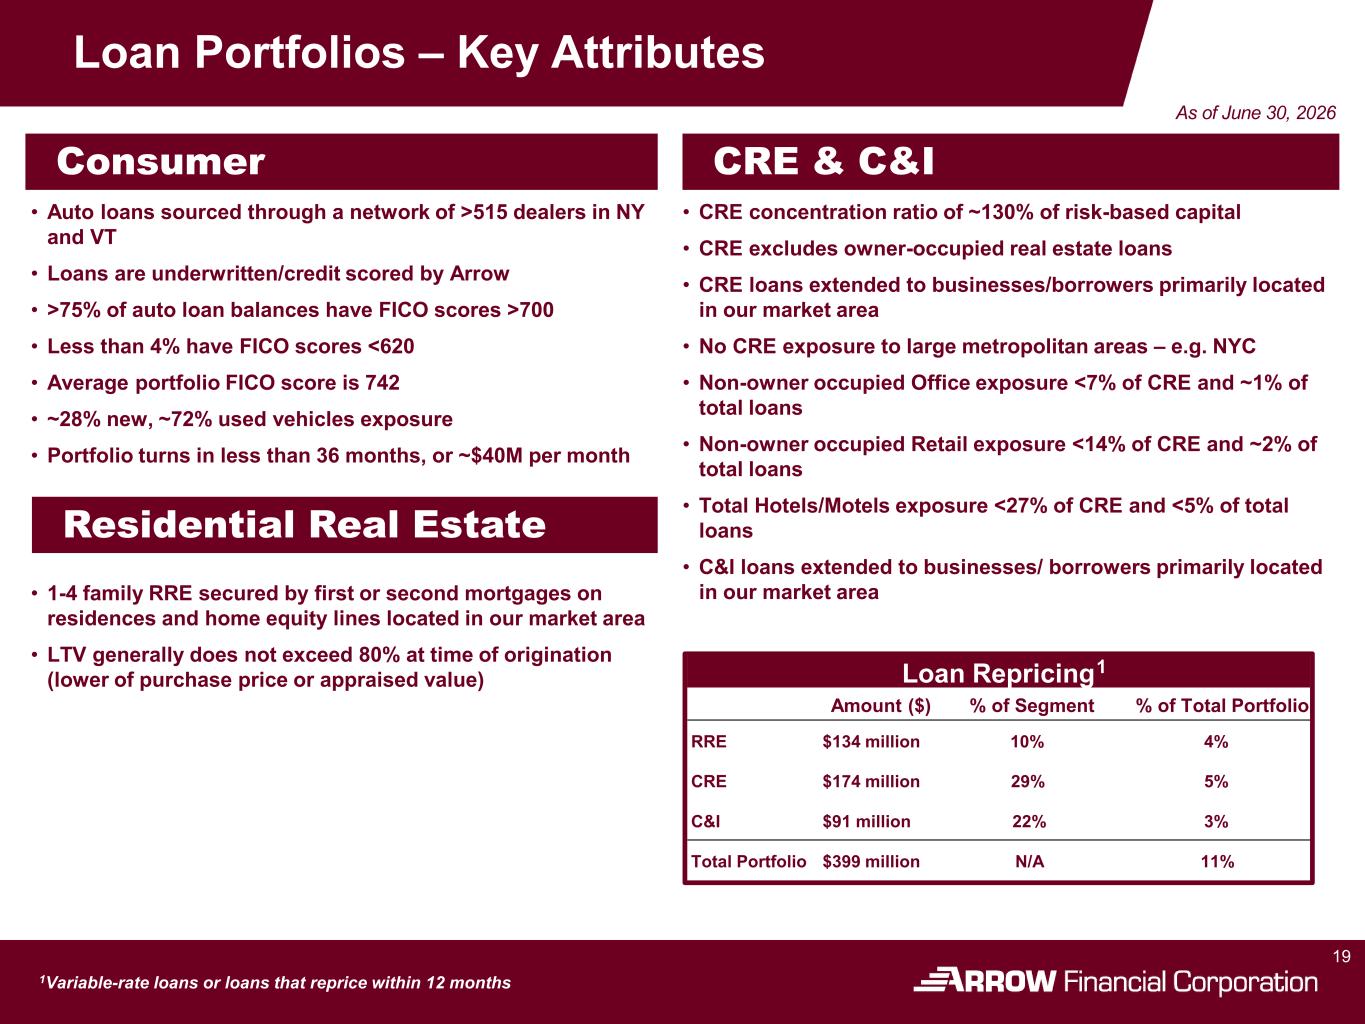
Loan Portfolios – Key Attributes 19 As of June 30, 2026 Consumer Residential Real Estate CRE & C&I • Auto loans sourced through a network of >515 dealers in NY and VT • Loans are underwritten/credit scored by Arrow • >75% of auto loan balances have FICO scores >700 • Less than 4% have FICO scores <620 • Average portfolio FICO score is 742 • ~28% new, ~72% used vehicles exposure • Portfolio turns in less than 36 months, or ~$40M per month • CRE concentration ratio of ~130% of risk-based capital • CRE excludes owner-occupied real estate loans • CRE loans extended to businesses/borrowers primarily located in our market area • No CRE exposure to large metropolitan areas – e.g. NYC • Non-owner occupied Office exposure <7% of CRE and ~1% of total loans • Non-owner occupied Retail exposure <14% of CRE and ~2% of total loans • Total Hotels/Motels exposure <27% of CRE and <5% of total loans • C&I loans extended to businesses/ borrowers primarily located in our market area• 1-4 family RRE secured by first or second mortgages on residences and home equity lines located in our market area • LTV generally does not exceed 80% at time of origination (lower of purchase price or appraised value) 1Variable-rate loans or loans that reprice within 12 months Amount ($) % of Segment % of Total Portfolio RRE $134 million 10% 4% CRE $174 million 29% 5% C&I $91 million 22% 3% Total Portfolio $399 million N/A 11% Loan Repricing1
DEPOSITS/FUNDING SOURCES 20
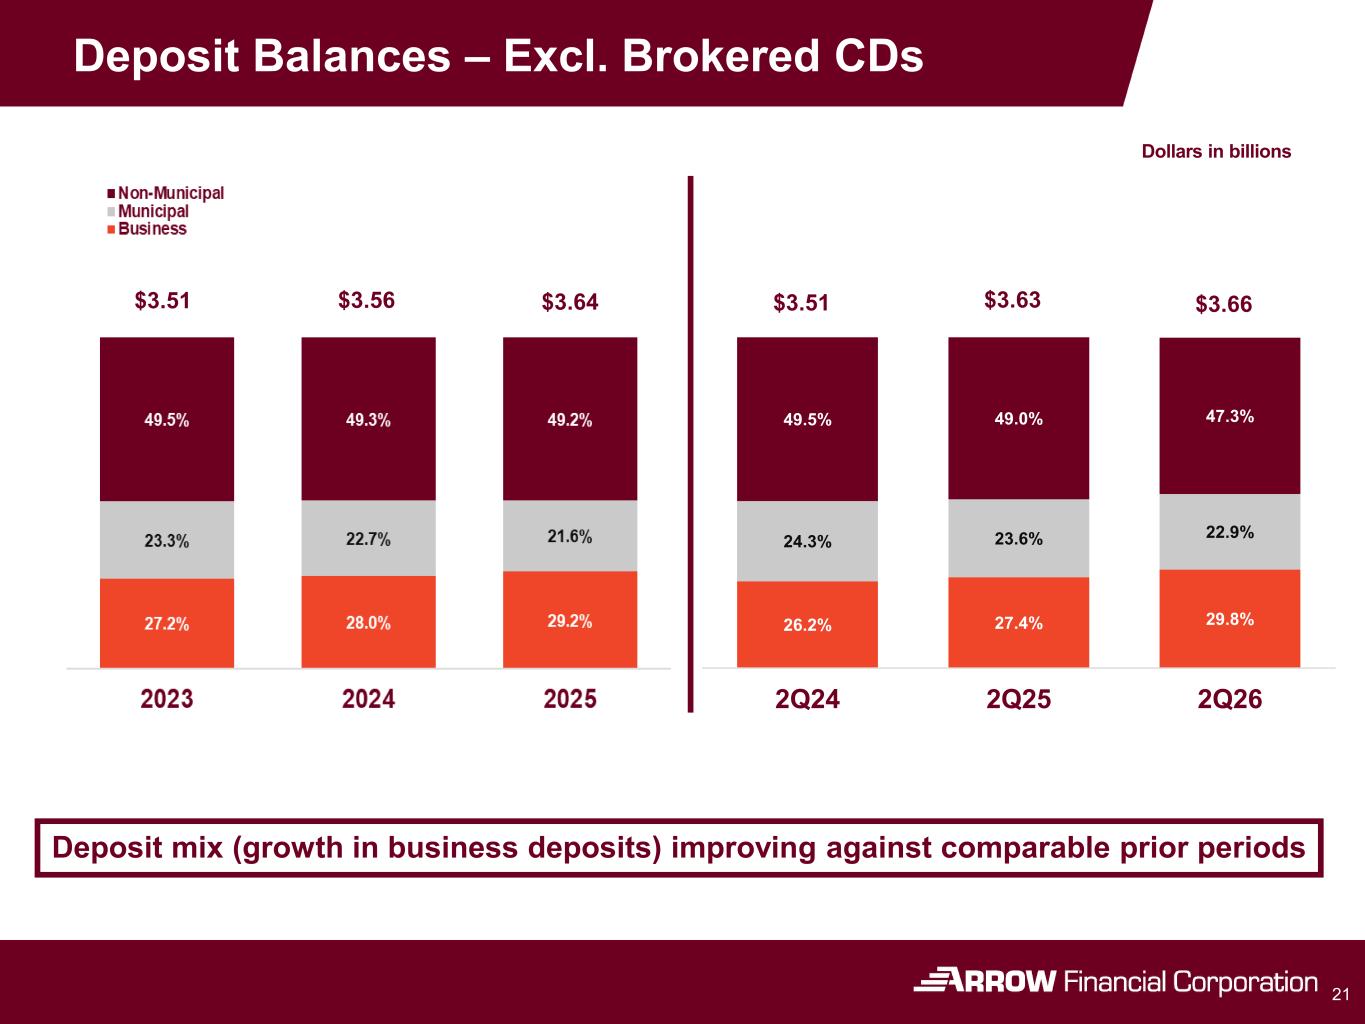
Deposit Balances – Excl. Brokered CDs 21 Deposit mix (growth in business deposits) improving against comparable prior periods Dollars in billions $3.51 $3.56 $3.64 26.2% 27.4% 29.8% 24.3% 23.6% 22.9% 49.5% 49.0% 47.3% 2Q24 2Q25 2Q26 $3.51 $3.63 $3.66
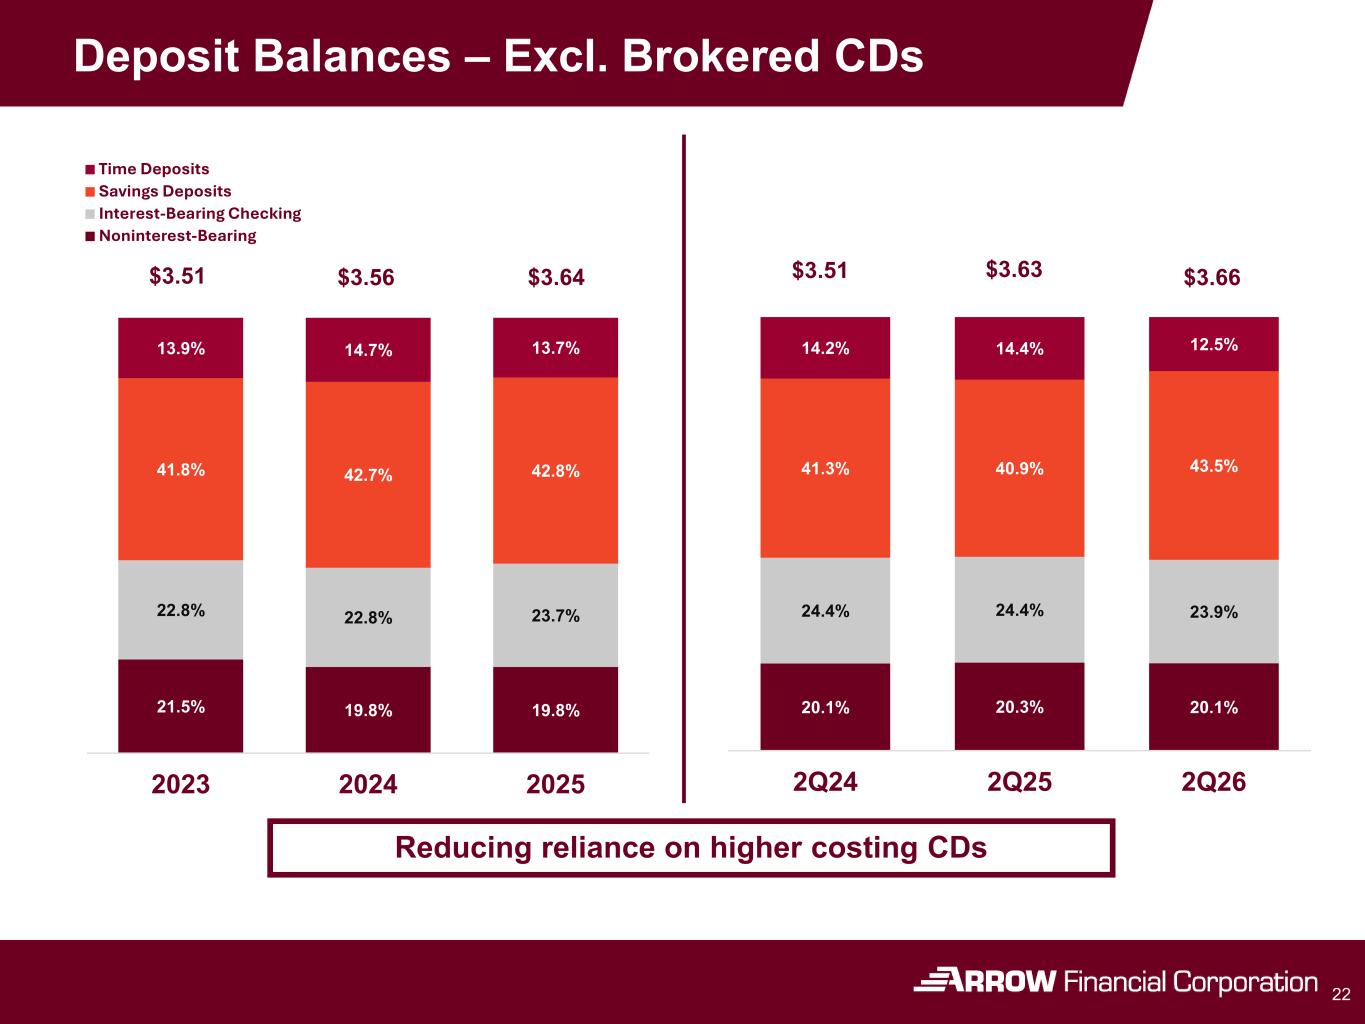
Deposit Balances – Excl. Brokered CDs 22 21.5% 19.8% 19.8% 22.8% 22.8% 23.7% 41.8% 42.7% 42.8% 13.9% 14.7% 13.7% 2023 2024 2025 Time Deposits Savings Deposits Interest-Bearing Checking Noninterest-Bearing 20.1% 20.3% 20.1% 24.4% 24.4% 23.9% 41.3% 40.9% 43.5% 14.2% 14.4% 12.5% 2Q24 2Q25 2Q26 Reducing reliance on higher costing CDs $3.51 $3.56 $3.64 $3.51 $3.63 $3.66
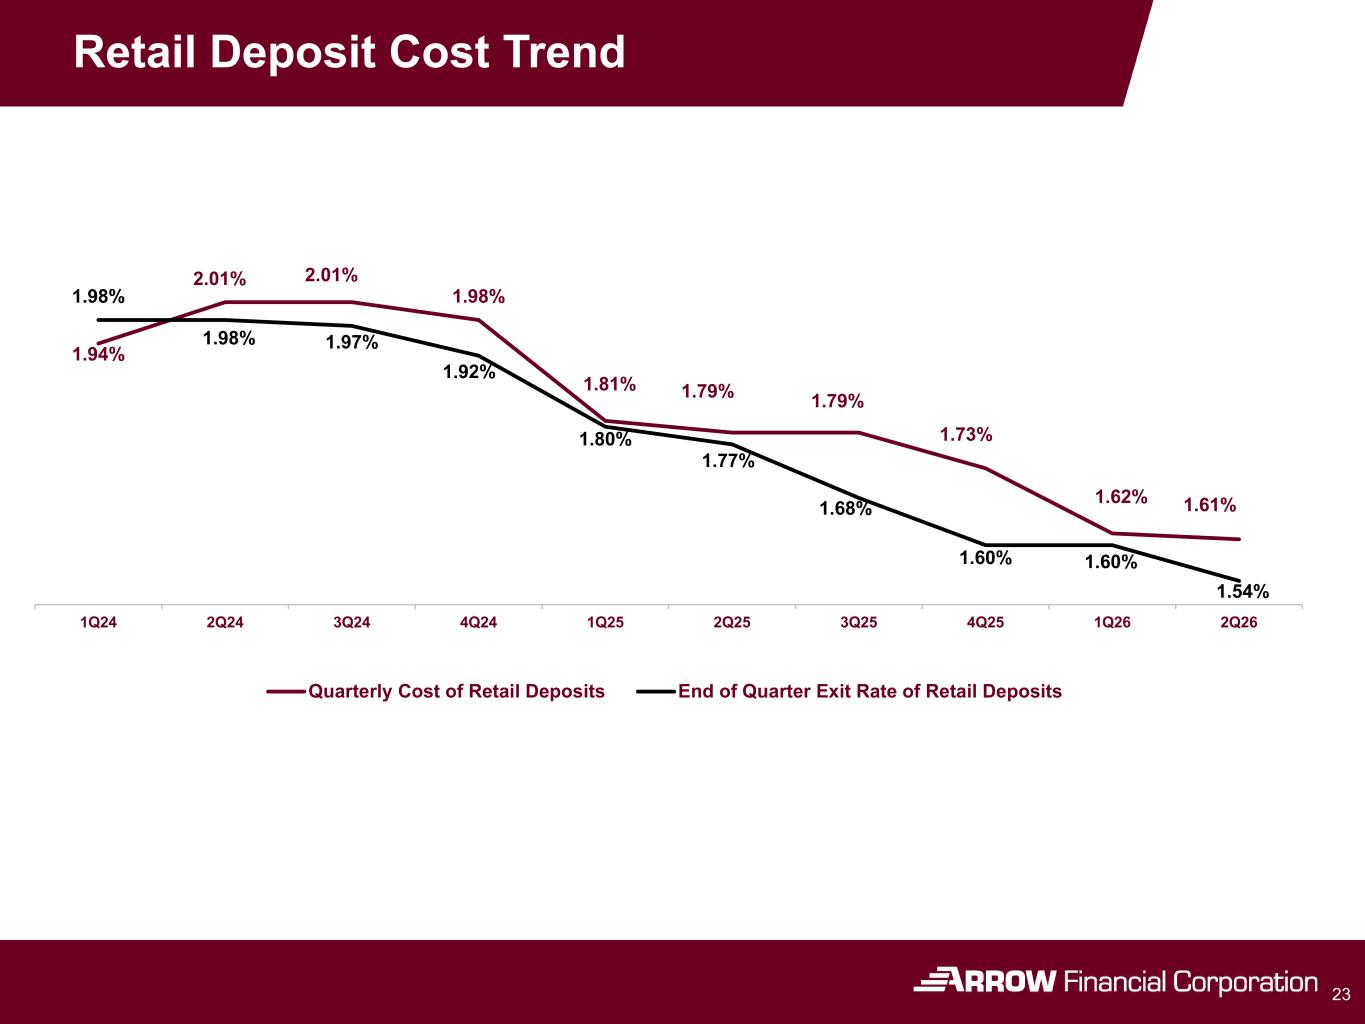
Retail Deposit Cost Trend 23 1.94% 2.01% 2.01% 1.98% 1.81% 1.79% 1.79% 1.73% 1.62% 1.61% 1.98% 1.98% 1.97% 1.92% 1.80% 1.77% 1.68% 1.60% 1.60% 1.54% 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Quarterly Cost of Retail Deposits End of Quarter Exit Rate of Retail Deposits
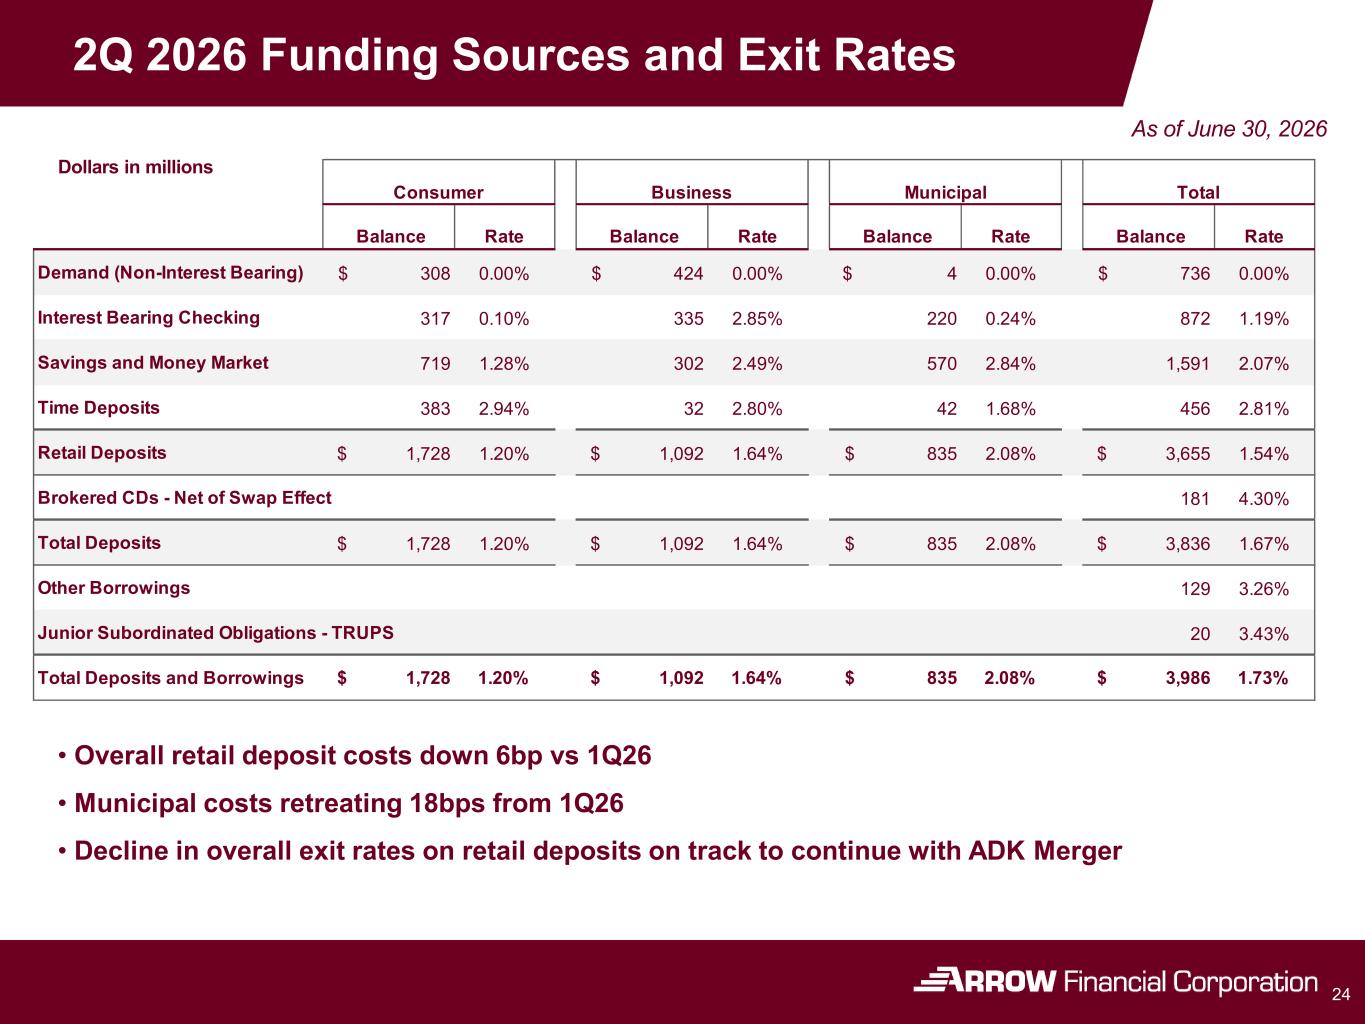
2Q 2026 Funding Sources and Exit Rates 24 As of June 30, 2026 Dollars in millions • Overall retail deposit costs down 6bp vs 1Q26 • Municipal costs retreating 18bps from 1Q26 • Decline in overall exit rates on retail deposits on track to continue with ADK Merger Balance Rate Balance Rate Balance Rate Balance Rate Demand (Non-Interest Bearing) $ 308 0.00% $ 424 0.00% $ 4 0.00% $ 736 0.00% Interest Bearing Checking 317 0.10% 335 2.85% 220 0.24% 872 1.19% Savings and Money Market 719 1.28% 302 2.49% 570 2.84% 1,591 2.07% Time Deposits 383 2.94% 32 2.80% 42 1.68% 456 2.81% Retail Deposits $ 1,728 1.20% $ 1,092 1.64% $ 835 2.08% $ 3,655 1.54% Brokered CDs - Net of Swap Effect 181 4.30% Total Deposits $ 1,728 1.20% $ 1,092 1.64% $ 835 2.08% $ 3,836 1.67% Other Borrowings 129 3.26% Junior Subordinated Obligations - TRUPS 20 3.43% Total Deposits and Borrowings $ 1,728 1.20% $ 1,092 1.64% $ 835 2.08% $ 3,986 1.73% Consumer Business Municipal Total
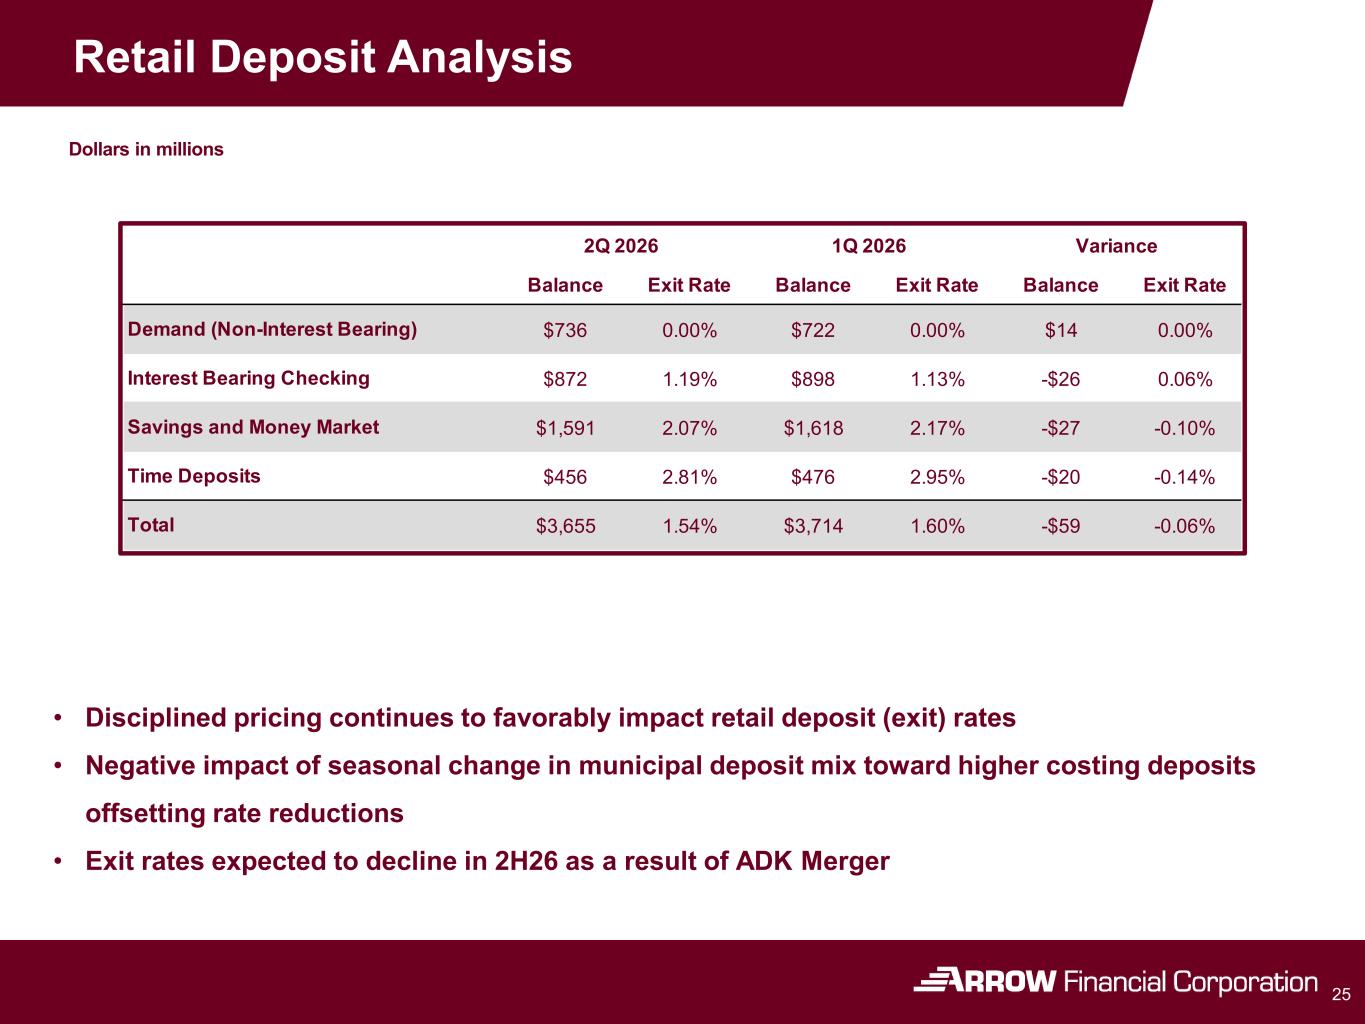
Retail Deposit Analysis 25 • Disciplined pricing continues to favorably impact retail deposit (exit) rates • Negative impact of seasonal change in municipal deposit mix toward higher costing deposits offsetting rate reductions • Exit rates expected to decline in 2H26 as a result of ADK Merger Dollars in millions Balance Exit Rate Balance Exit Rate Balance Exit Rate Demand (Non-Interest Bearing) $736 0.00% $722 0.00% $14 0.00% Interest Bearing Checking $872 1.19% $898 1.13% -$26 0.06% Savings and Money Market $1,591 2.07% $1,618 2.17% -$27 -0.10% Time Deposits $456 2.81% $476 2.95% -$20 -0.14% Total $3,655 1.54% $3,714 1.60% -$59 -0.06% 2Q 2026 1Q 2026 Variance
CREDIT QUALITY & PROVISION FOR CREDIT LOSSES 26
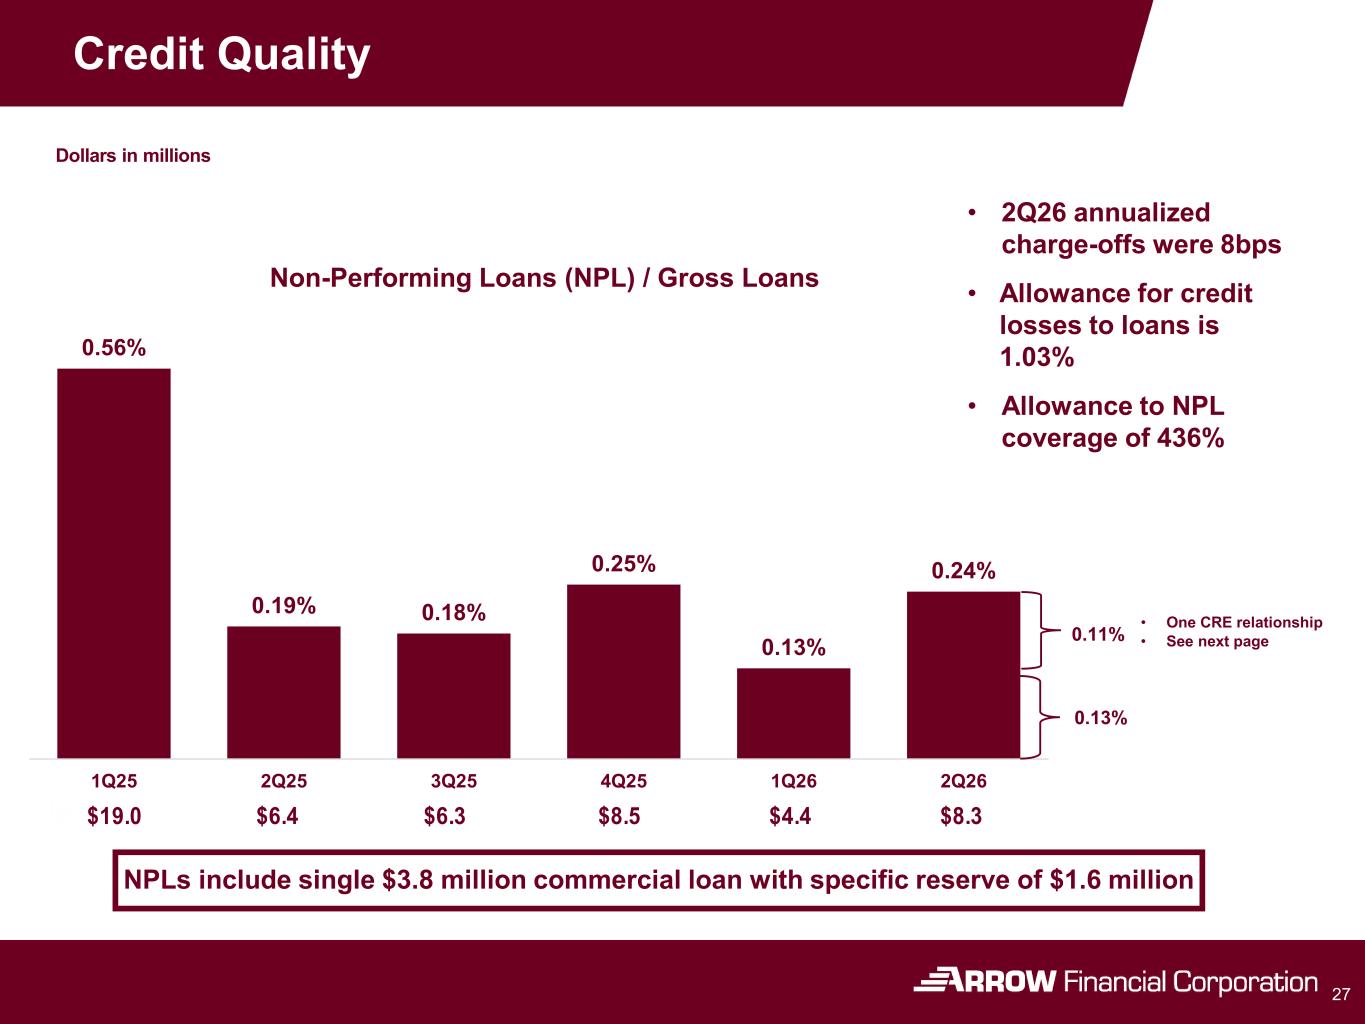
Credit Quality 27 Dollars in millions 0.56% 0.19% 0.18% 0.25% 0.13% 0.24% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Non-Performing Loans (NPL) / Gross Loans $19.0 $6.4 $6.3 $8.5 $4.4 $8.3 • 2Q26 annualized charge-offs were 8bps • Allowance for credit losses to loans is 1.03% • Allowance to NPL coverage of 436% NPLs include single $3.8 million commercial loan with specific reserve of $1.6 million 0.11% 0.13% • One CRE relationship • See next page
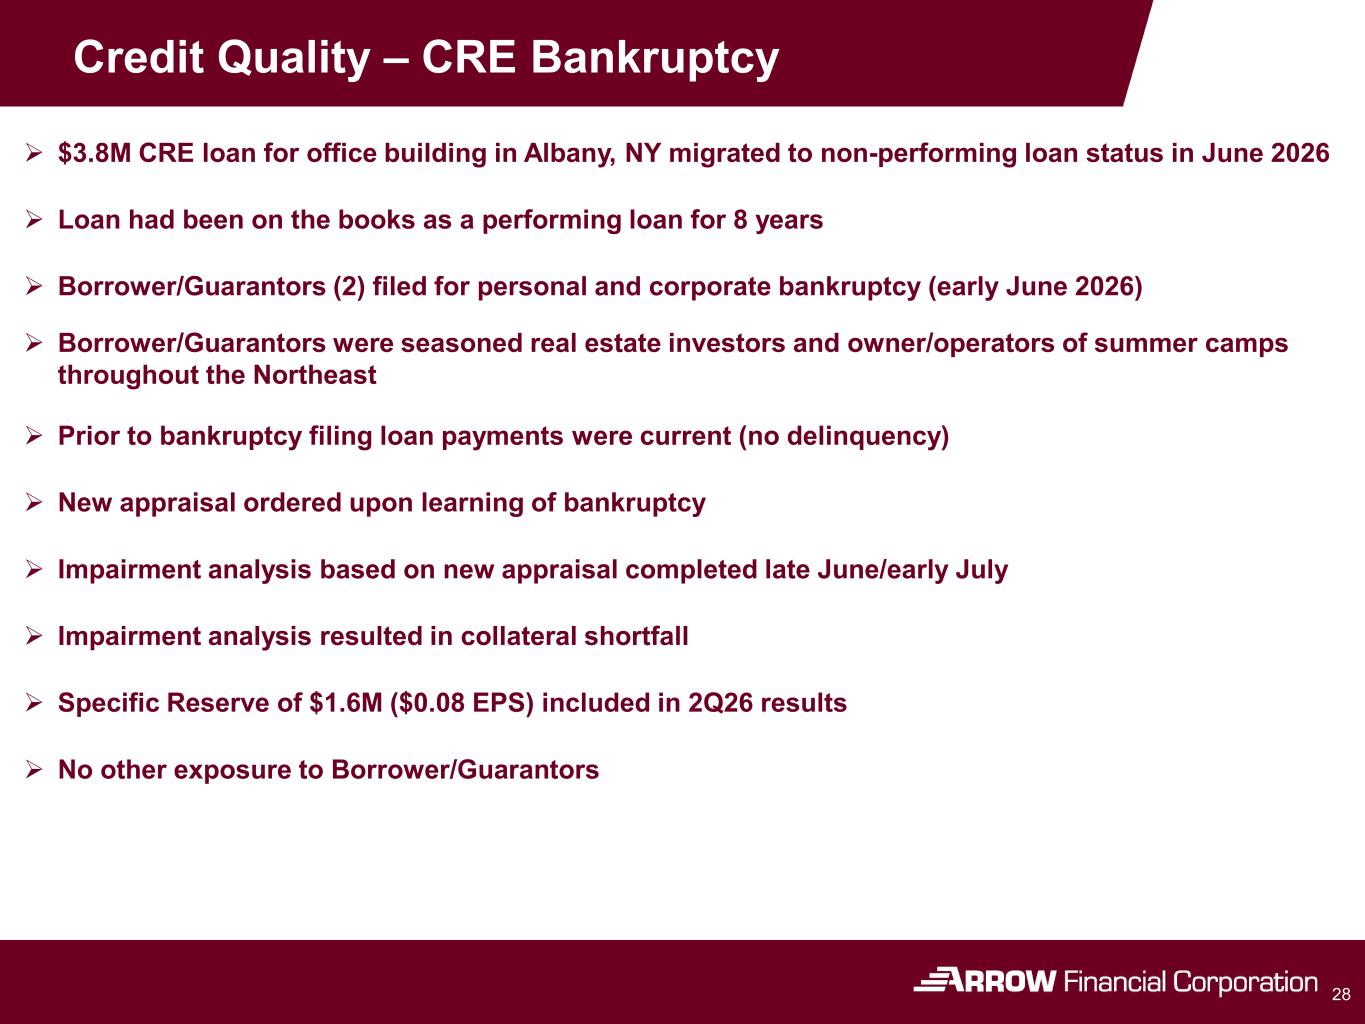
Credit Quality – CRE Bankruptcy $3.8M CRE loan for office building in Albany, NY migrated to non-performing loan status in June 2026 Loan had been on the books as a performing loan for 8 years Borrower/Guarantors (2) filed for personal and corporate bankruptcy (early June 2026) Borrower/Guarantors were seasoned real estate investors and owner/operators of summer camps throughout the Northeast Prior to bankruptcy filing loan payments were current (no delinquency) New appraisal ordered upon learning of bankruptcy Impairment analysis based on new appraisal completed late June/early July Impairment analysis resulted in collateral shortfall Specific Reserve of $1.6M ($0.08 EPS) included in 2Q26 results No other exposure to Borrower/Guarantors 28
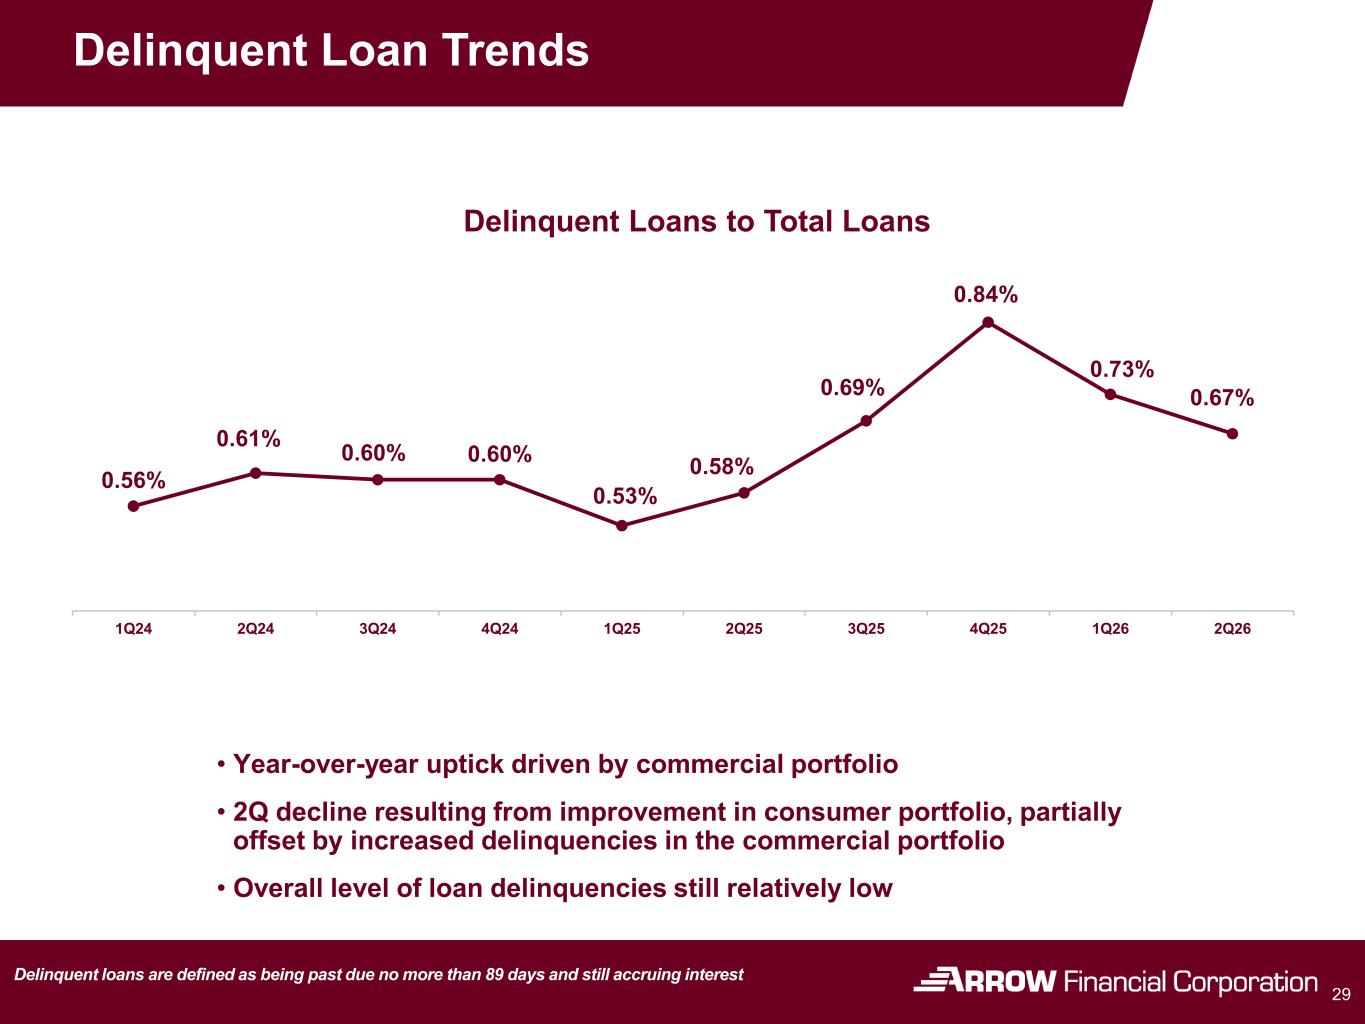
Delinquent Loan Trends 29 Delinquent loans are defined as being past due no more than 89 days and still accruing interest 0.56% 0.61% 0.60% 0.60% 0.53% 0.58% 0.69% 0.84% 0.73% 0.67% 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Delinquent Loans to Total Loans • Year-over-year uptick driven by commercial portfolio • 2Q decline resulting from improvement in consumer portfolio, partially offset by increased delinquencies in the commercial portfolio • Overall level of loan delinquencies still relatively low
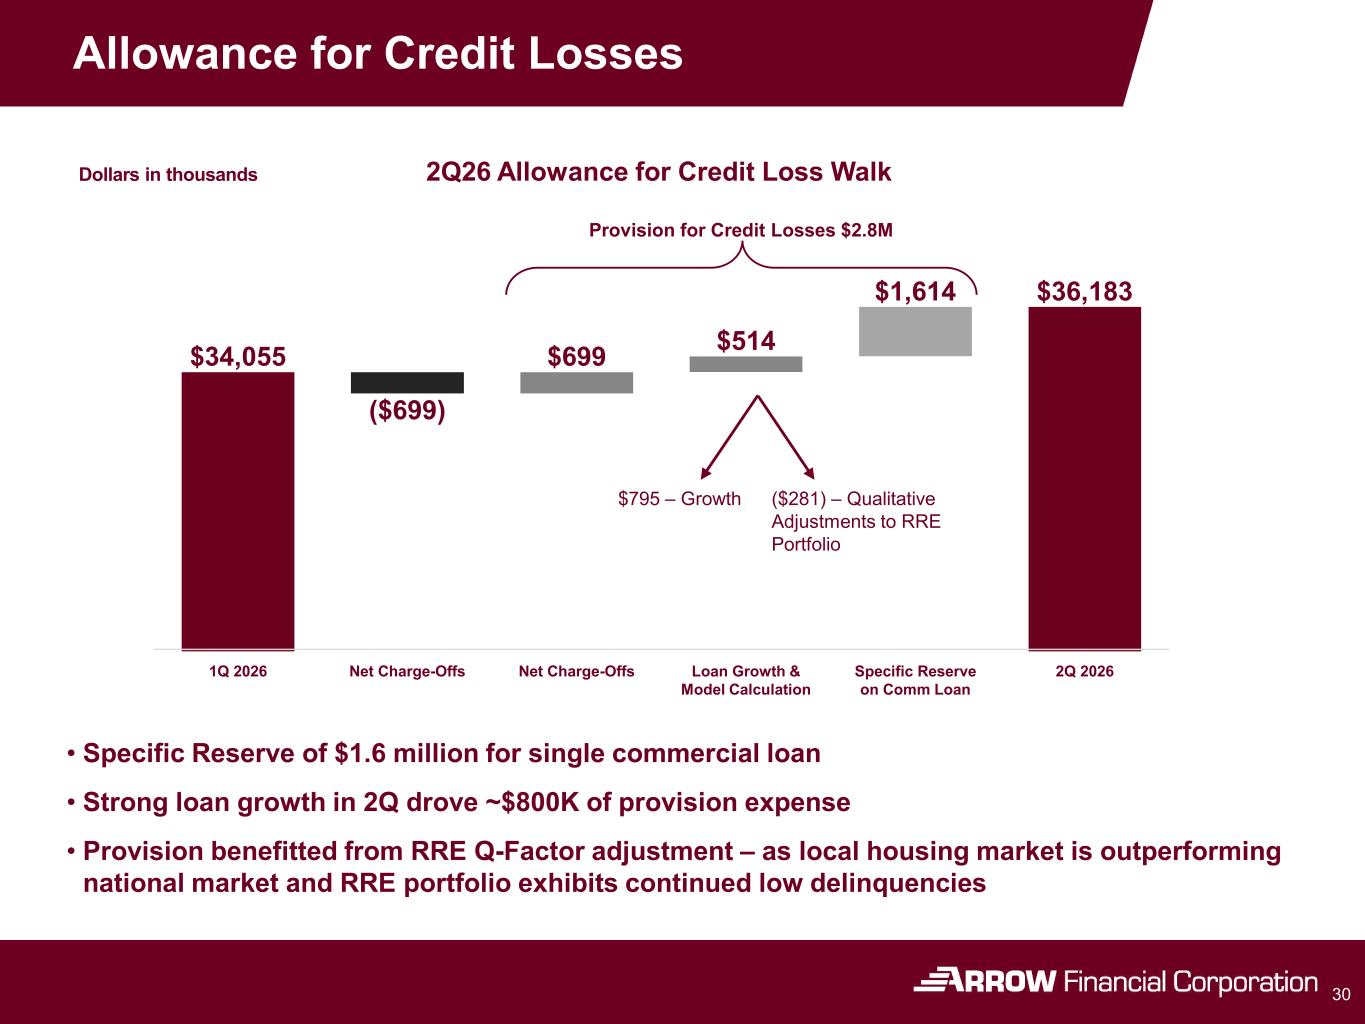
Allowance for Credit Losses 30 $34,055 ($699) $699 $514 $1,614 $36,183 1Q 2026 Net Charge-Offs Net Charge-Offs Loan Growth & Model Calculation Specific Reserve on Comm Loan 2Q 2026 Provision for Credit Losses $2.8M Dollars in thousands 2Q26 Allowance for Credit Loss Walk • Specific Reserve of $1.6 million for single commercial loan • Strong loan growth in 2Q drove ~$800K of provision expense • Provision benefitted from RRE Q-Factor adjustment – as local housing market is outperforming national market and RRE portfolio exhibits continued low delinquencies $795 – Growth ($281) – Qualitative Adjustments to RRE Portfolio
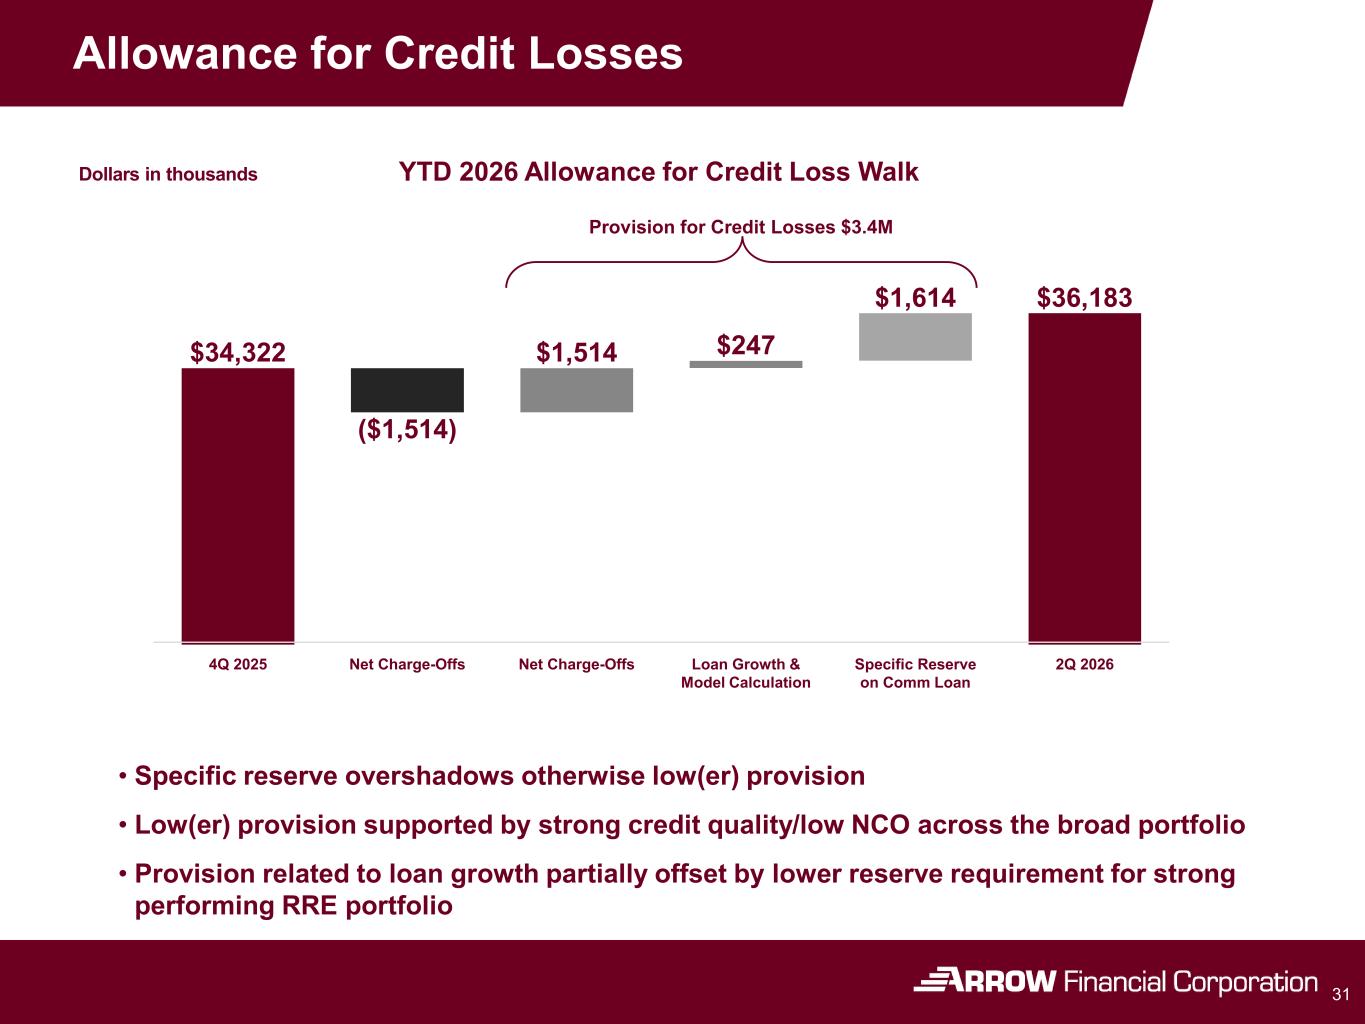
Allowance for Credit Losses 31 $34,322 ($1,514) $1,514 $247 $1,614 $36,183 4Q 2025 Net Charge-Offs Net Charge-Offs Loan Growth & Model Calculation Specific Reserve on Comm Loan 2Q 2026 Provision for Credit Losses $3.4M Dollars in thousands YTD 2026 Allowance for Credit Loss Walk • Specific reserve overshadows otherwise low(er) provision • Low(er) provision supported by strong credit quality/low NCO across the broad portfolio • Provision related to loan growth partially offset by lower reserve requirement for strong performing RRE portfolio
INVESTMENTS 32
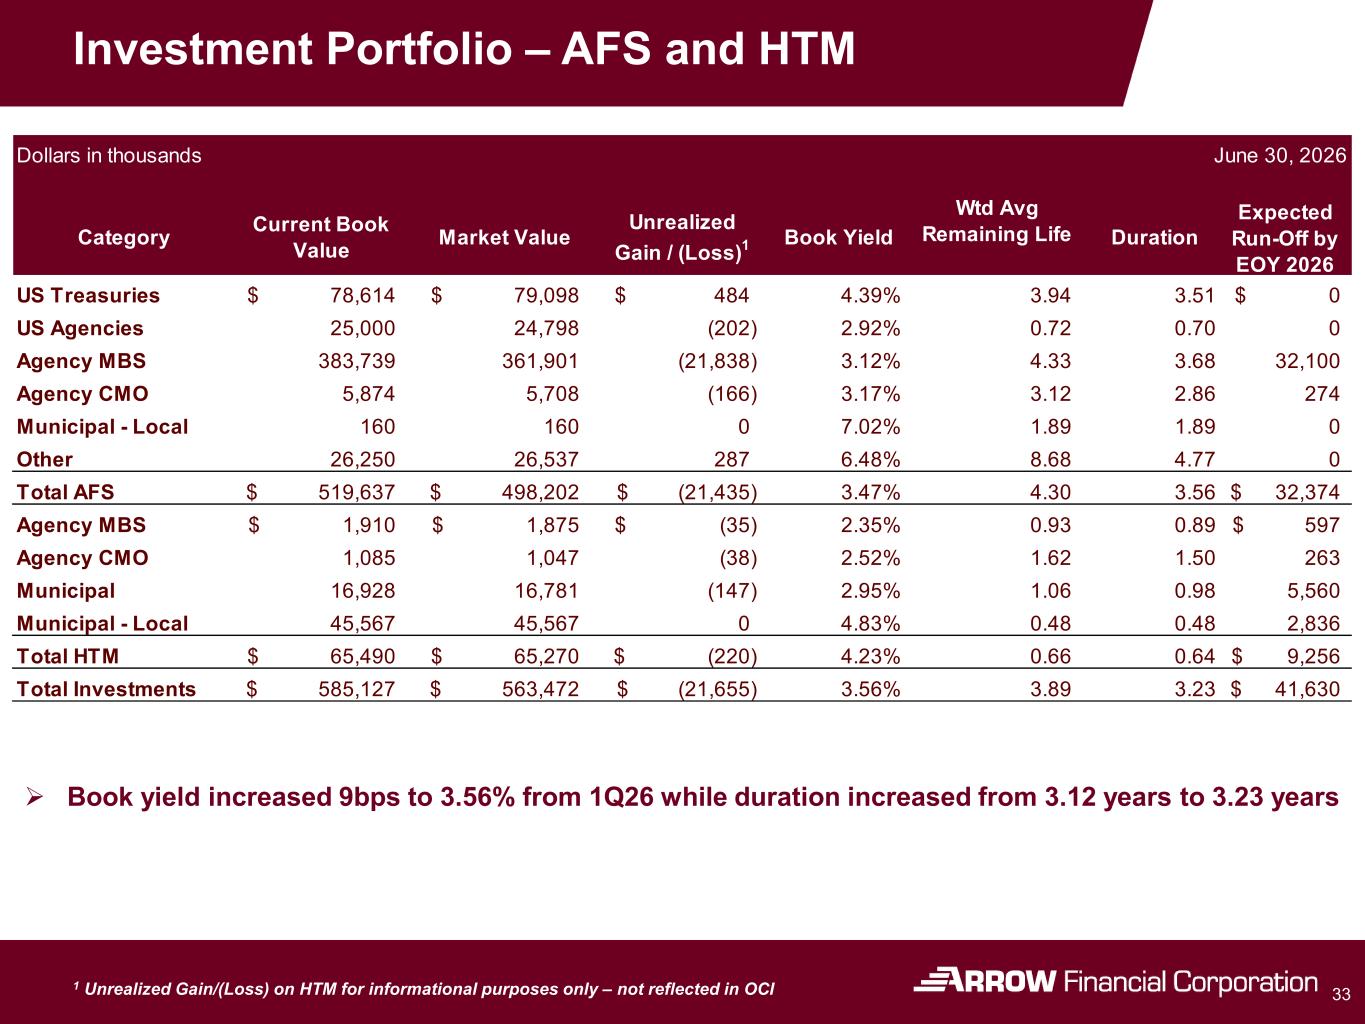
Investment Portfolio – AFS and HTM 331 Unrealized Gain/(Loss) on HTM for informational purposes only – not reflected in OCI Book yield increased 9bps to 3.56% from 1Q26 while duration increased from 3.12 years to 3.23 years Dollars in thousands June 30, 2026 263 585,127$ 563,472$ 2.95% 4.83% 4.23% 3.56% (147) 0 (220)$ Expected Run-Off by EOY 2026 0 32,100 274 3.89 Wtd Avg Remaining Life 0.72 4.33 3.12 5,560 2,836 9,256$ 1.89 8.68 4.30 0.93 1.62 1.06 0.48 0.66 0 0 32,374$ 597$ 2.35% 2.52% 65,270$ Agency MBS Agency CMO Municipal Municipal - Local Total HTM 16,781 65,490$ (35)$ (38) Category 41,630$ 5,874 5,708 (166) 3.17% 383,739 361,901 (21,838) 3.12% Unrealized Gain / (Loss)1 Book Yield 2.92% Current Book Value 25,000 Total Investments US Agencies 160 26,250 519,637$ 1,910$ Agency MBS (21,655)$ Market Value 24,798 16,928 45,567 1,085 1,047 45,567 160 26,537 498,202$ 1,875$ 78,614$ 79,098$ 484$ 4.39% 3.94 0$ (202) Agency CMO Municipal - Local Other Total AFS US Treasuries 7.02% 6.48% 3.47% 0 287 (21,435)$ 1.50 0.98 0.48 0.64 3.23 Duration 3.51 0.70 3.68 2.86 1.89 4.77 3.56 0.89
CAPITAL 34
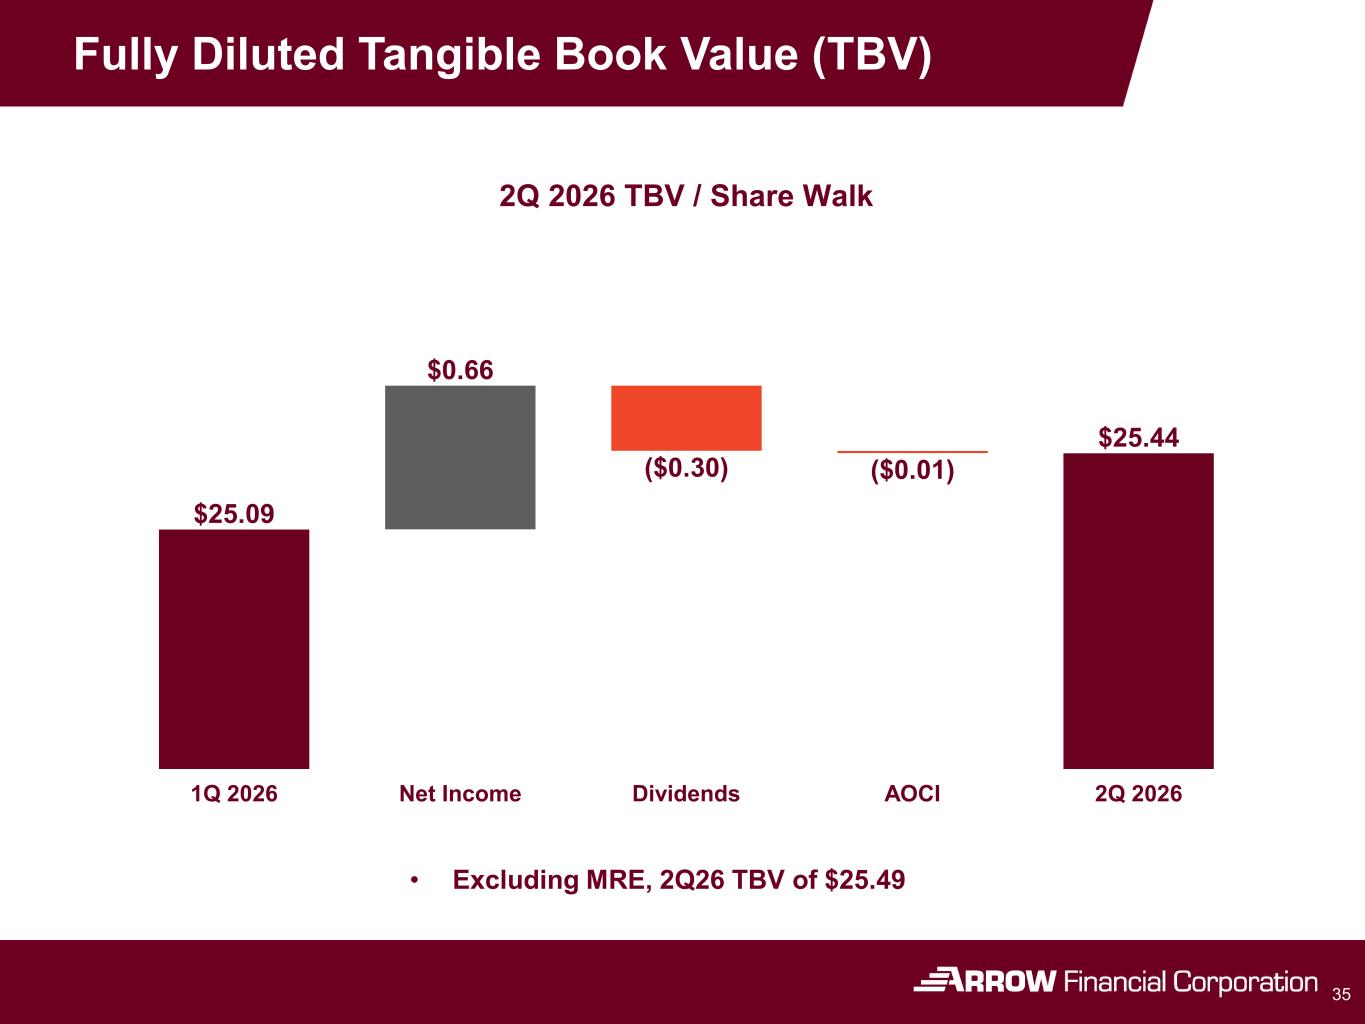
Fully Diluted Tangible Book Value (TBV) 35 $25.09 $0.66 ($0.30) ($0.01) $25.44 1Q 2026 Net Income Dividends AOCI 2Q 2026 2Q 2026 TBV / Share Walk • Excluding MRE, 2Q26 TBV of $25.49
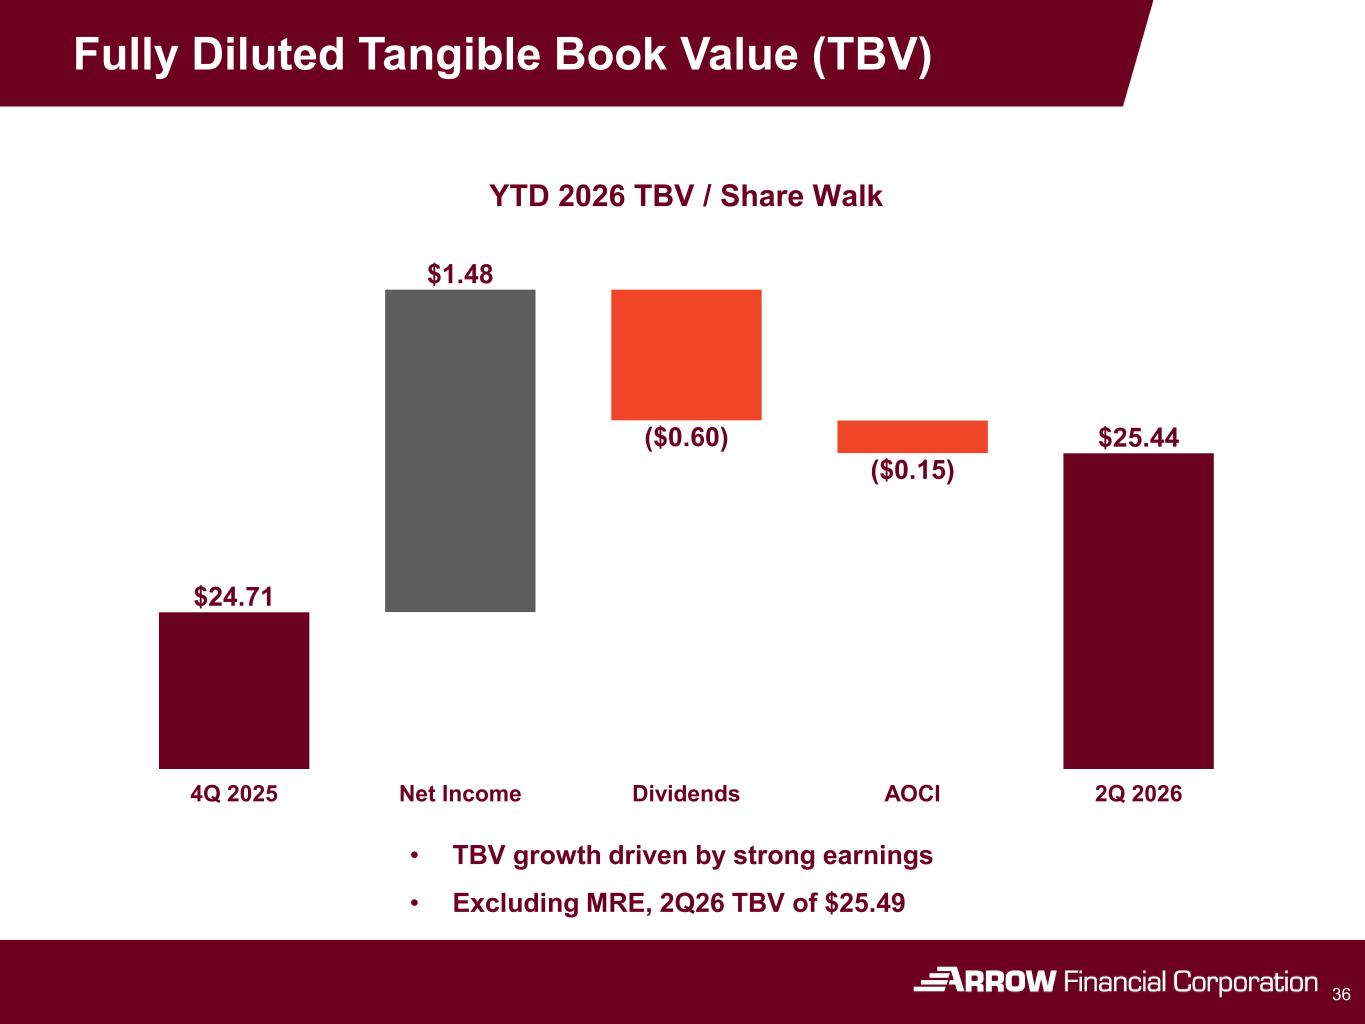
Fully Diluted Tangible Book Value (TBV) 36 $24.71 $1.48 ($0.60) ($0.15) $25.44 4Q 2025 Net Income Dividends AOCI 2Q 2026 YTD 2026 TBV / Share Walk • TBV growth driven by strong earnings • Excluding MRE, 2Q26 TBV of $25.49
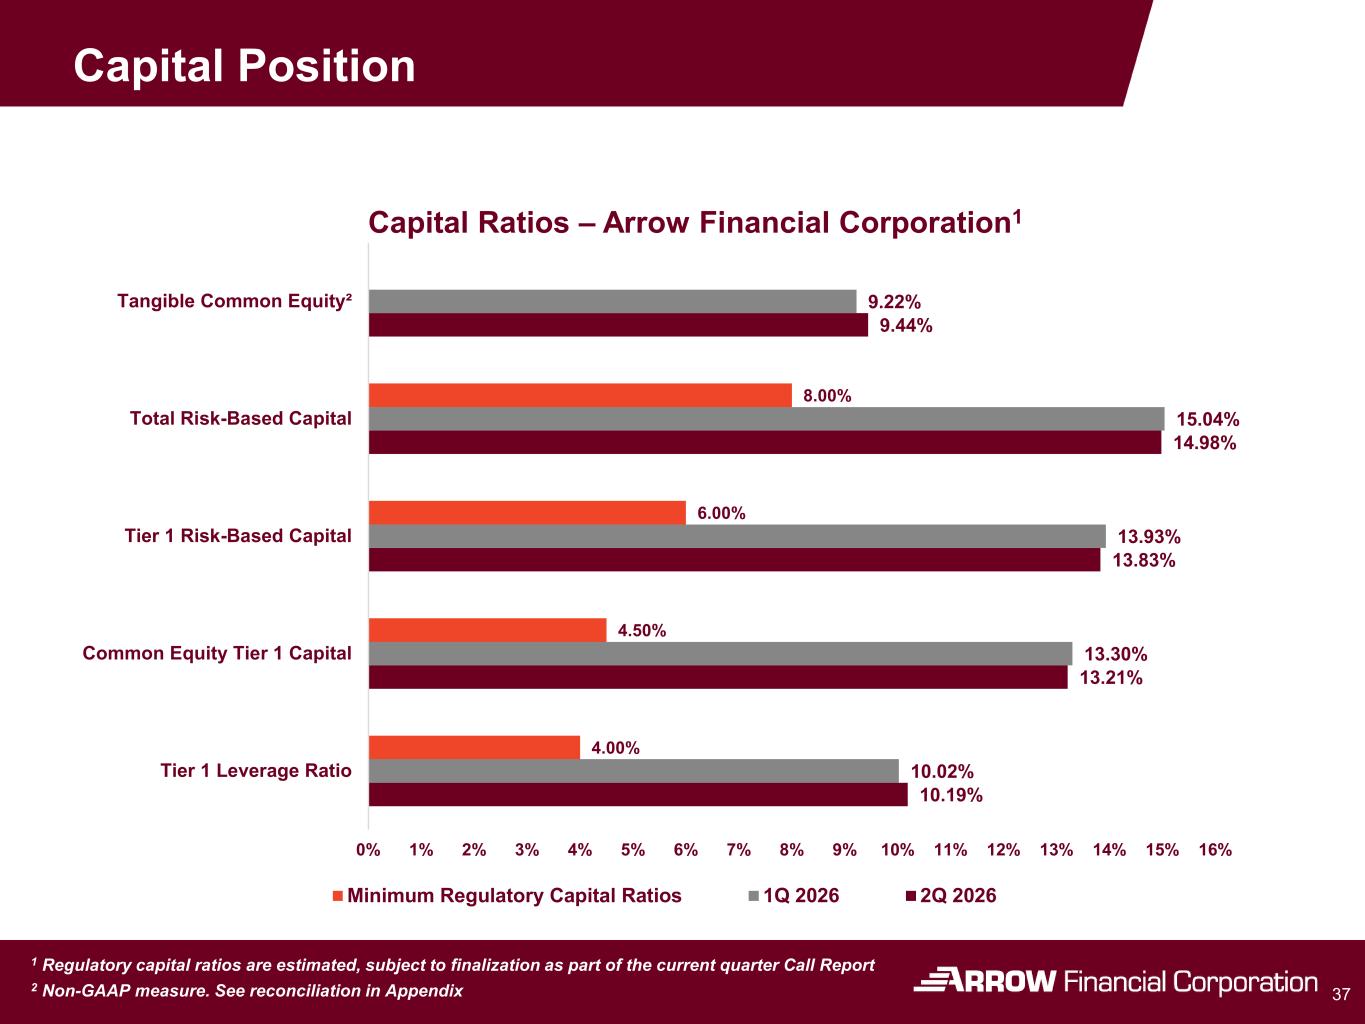
Capital Position 37 1 Regulatory capital ratios are estimated, subject to finalization as part of the current quarter Call Report 2 Non-GAAP measure. See reconciliation in Appendix 10.19% 13.21% 13.83% 14.98% 9.44% 10.02% 13.30% 13.93% 15.04% 9.22% 4.00% 4.50% 6.00% 8.00% 0% 1% 2% 3% 4% 5% 6% 7% 8% 9% 10% 11% 12% 13% 14% 15% 16% Tier 1 Leverage Ratio Common Equity Tier 1 Capital Tier 1 Risk-Based Capital Total Risk-Based Capital Tangible Common Equity² Capital Ratios – Arrow Financial Corporation1 Minimum Regulatory Capital Ratios 1Q 2026 2Q 2026
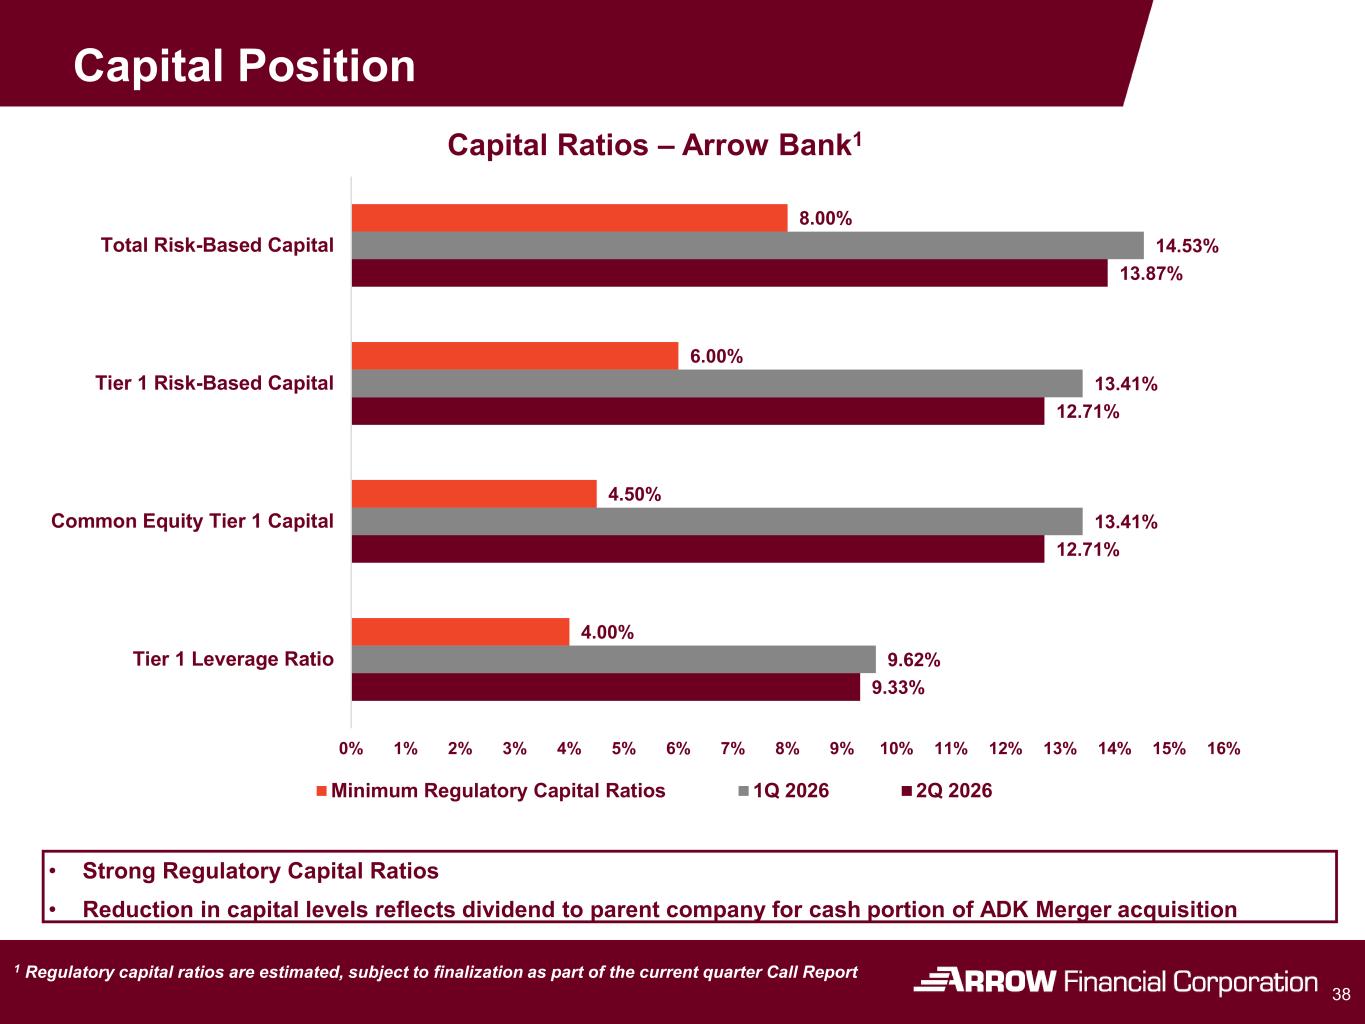
Capital Position 38 1 Regulatory capital ratios are estimated, subject to finalization as part of the current quarter Call Report • Strong Regulatory Capital Ratios • Reduction in capital levels reflects dividend to parent company for cash portion of ADK Merger acquisition 9.33% 12.71% 12.71% 13.87% 9.62% 13.41% 13.41% 14.53% 4.00% 4.50% 6.00% 8.00% 0% 1% 2% 3% 4% 5% 6% 7% 8% 9% 10% 11% 12% 13% 14% 15% 16% Tier 1 Leverage Ratio Common Equity Tier 1 Capital Tier 1 Risk-Based Capital Total Risk-Based Capital Capital Ratios – Arrow Bank1 Minimum Regulatory Capital Ratios 1Q 2026 2Q 2026
M&A Acquisition of Adirondack Bancorp, Inc. 39
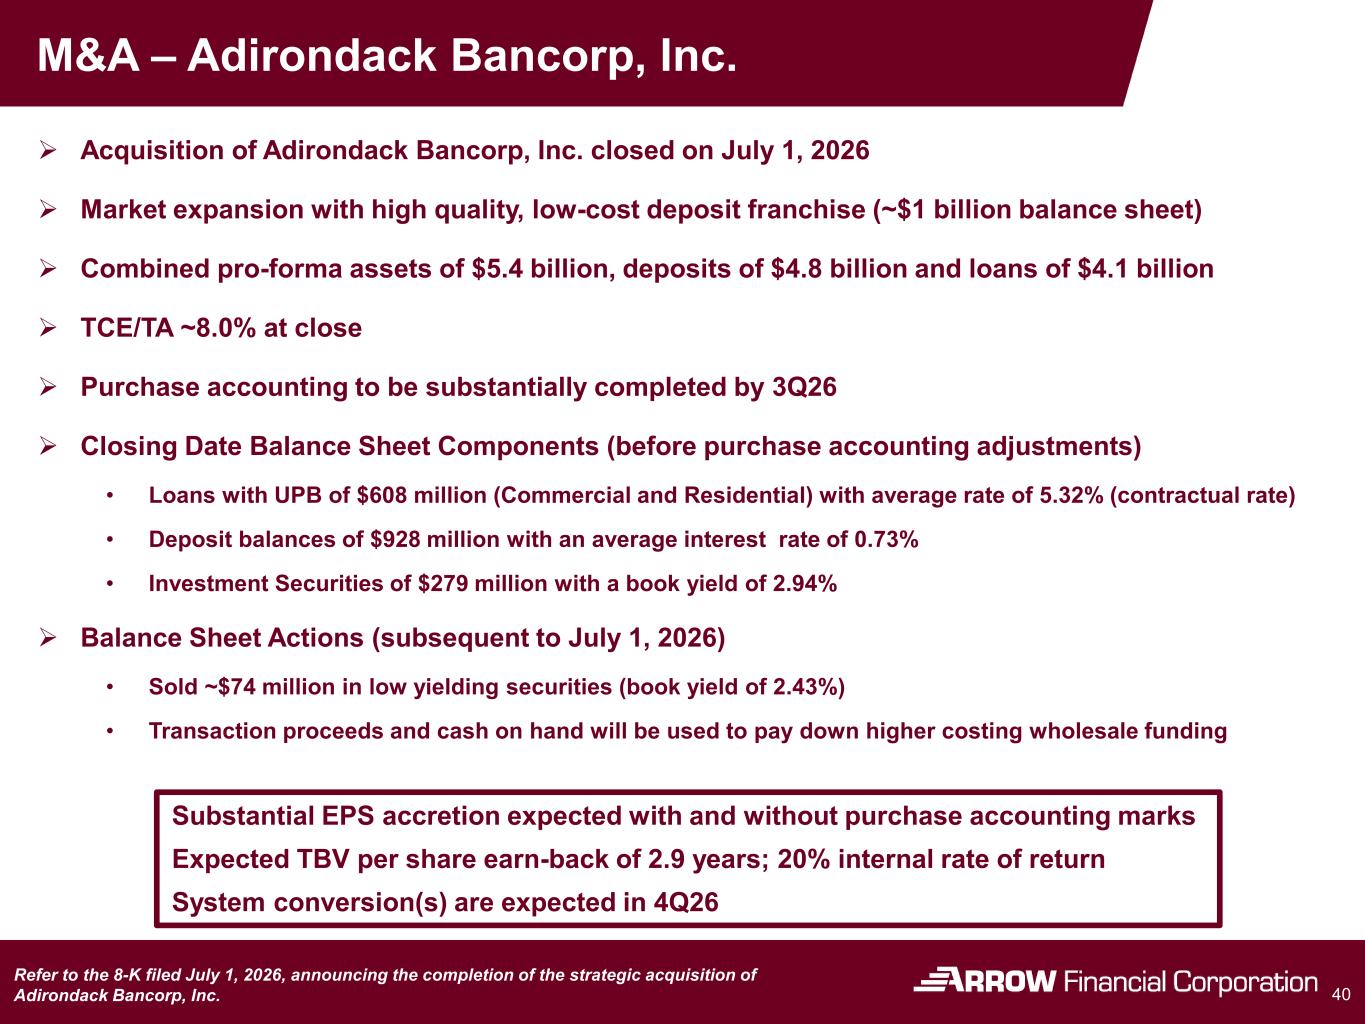
M&A – Adirondack Bancorp, Inc. Acquisition of Adirondack Bancorp, Inc. closed on July 1, 2026 Market expansion with high quality, low-cost deposit franchise (~$1 billion balance sheet) Combined pro-forma assets of $5.4 billion, deposits of $4.8 billion and loans of $4.1 billion TCE/TA ~8.0% at close Purchase accounting to be substantially completed by 3Q26 Closing Date Balance Sheet Components (before purchase accounting adjustments) • Loans with UPB of $608 million (Commercial and Residential) with average rate of 5.32% (contractual rate) • Deposit balances of $928 million with an average interest rate of 0.73% • Investment Securities of $279 million with a book yield of 2.94% Balance Sheet Actions (subsequent to July 1, 2026) • Sold ~$74 million in low yielding securities (book yield of 2.43%) • Transaction proceeds and cash on hand will be used to pay down higher costing wholesale funding 40 Refer to the 8-K filed July 1, 2026, announcing the completion of the strategic acquisition of Adirondack Bancorp, Inc. Substantial EPS accretion expected with and without purchase accounting marks Expected TBV per share earn-back of 2.9 years; 20% internal rate of return System conversion(s) are expected in 4Q26
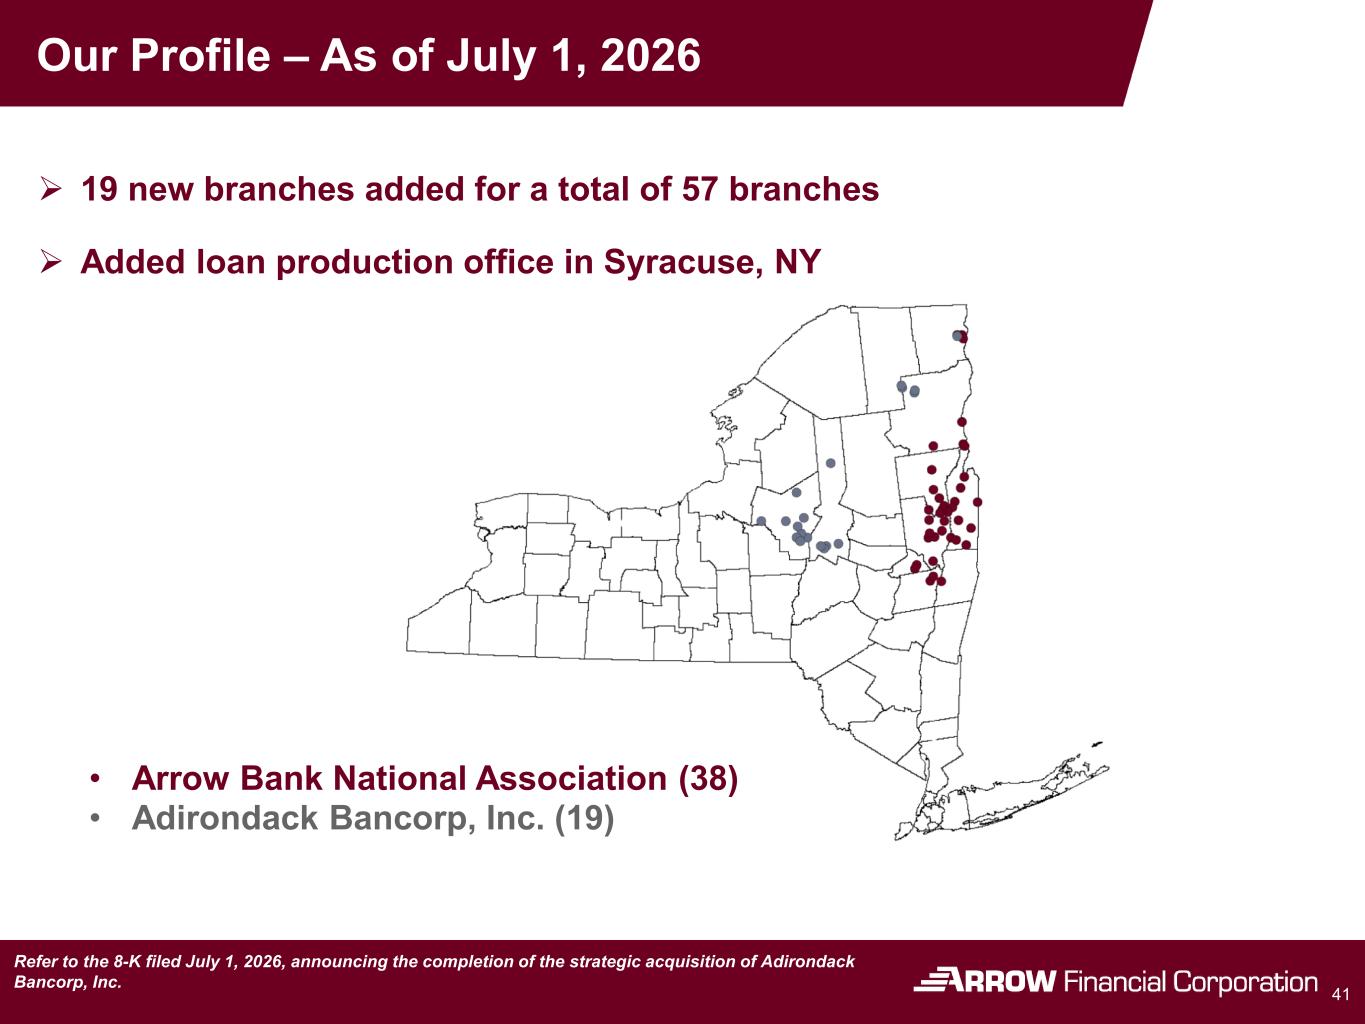
Our Profile – As of July 1, 2026 19 new branches added for a total of 57 branches Added loan production office in Syracuse, NY 41 Refer to the 8-K filed July 1, 2026, announcing the completion of the strategic acquisition of Adirondack Bancorp, Inc. • Arrow Bank National Association (38) • Adirondack Bancorp, Inc. (19)
OVERVIEW AND HISTORY 42
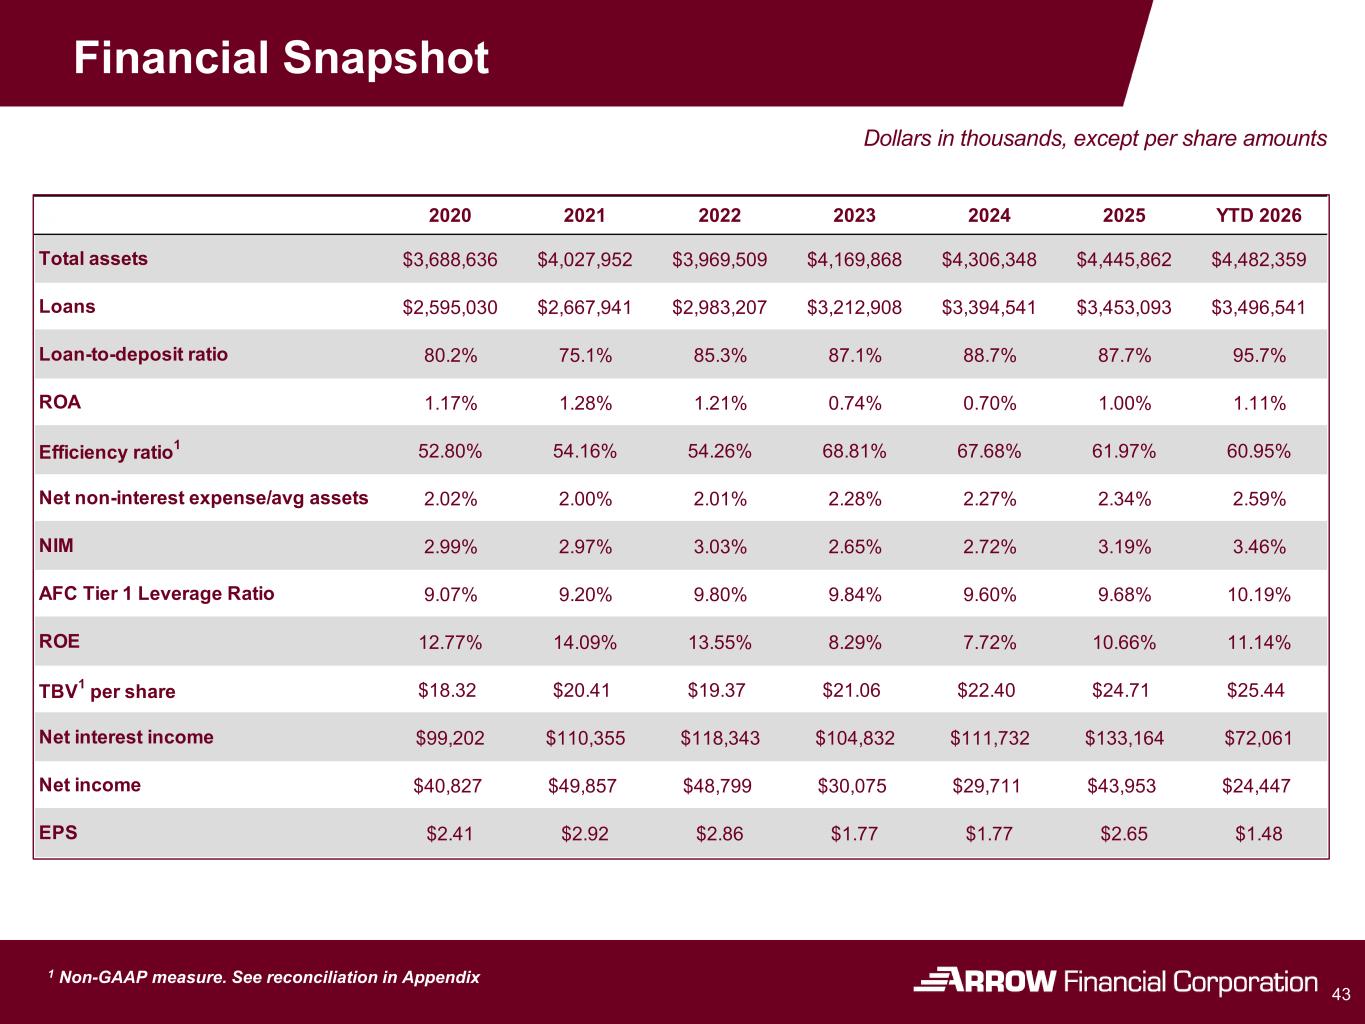
Financial Snapshot 43 1 Non-GAAP measure. See reconciliation in Appendix Dollars in thousands, except per share amounts 2020 2021 2022 2023 2024 2025 YTD 2026 Total assets $3,688,636 $4,027,952 $3,969,509 $4,169,868 $4,306,348 $4,445,862 $4,482,359 Loans $2,595,030 $2,667,941 $2,983,207 $3,212,908 $3,394,541 $3,453,093 $3,496,541 Loan-to-deposit ratio 80.2% 75.1% 85.3% 87.1% 88.7% 87.7% 95.7% ROA 1.17% 1.28% 1.21% 0.74% 0.70% 1.00% 1.11% Efficiency ratio1 52.80% 54.16% 54.26% 68.81% 67.68% 61.97% 60.95% Net non-interest expense/avg assets 2.02% 2.00% 2.01% 2.28% 2.27% 2.34% 2.59% NIM 2.99% 2.97% 3.03% 2.65% 2.72% 3.19% 3.46% AFC Tier 1 Leverage Ratio 9.07% 9.20% 9.80% 9.84% 9.60% 9.68% 10.19% ROE 12.77% 14.09% 13.55% 8.29% 7.72% 10.66% 11.14% TBV1 per share $18.32 $20.41 $19.37 $21.06 $22.40 $24.71 $25.44 Net interest income $99,202 $110,355 $118,343 $104,832 $111,732 $133,164 $72,061 Net income $40,827 $49,857 $48,799 $30,075 $29,711 $43,953 $24,447 EPS $2.41 $2.92 $2.86 $1.77 $1.77 $2.65 $1.48
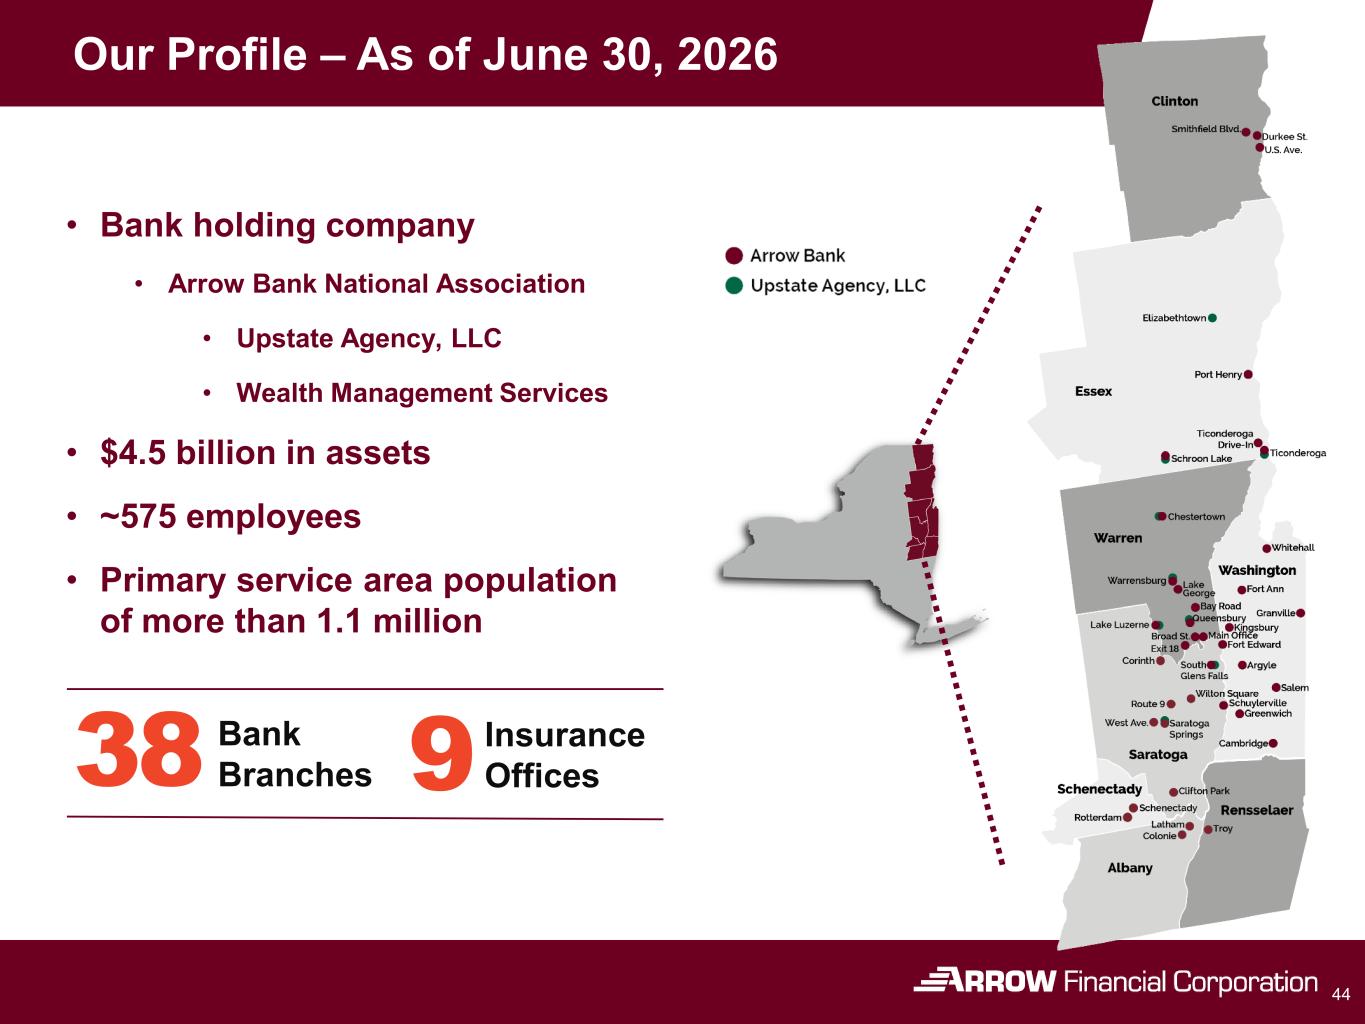
Our Profile – As of June 30, 2026 • Bank holding company • Arrow Bank National Association • Upstate Agency, LLC • Wealth Management Services • $4.5 billion in assets • ~575 employees • Primary service area population of more than 1.1 million 44 Insurance Offices Bank Branches 938
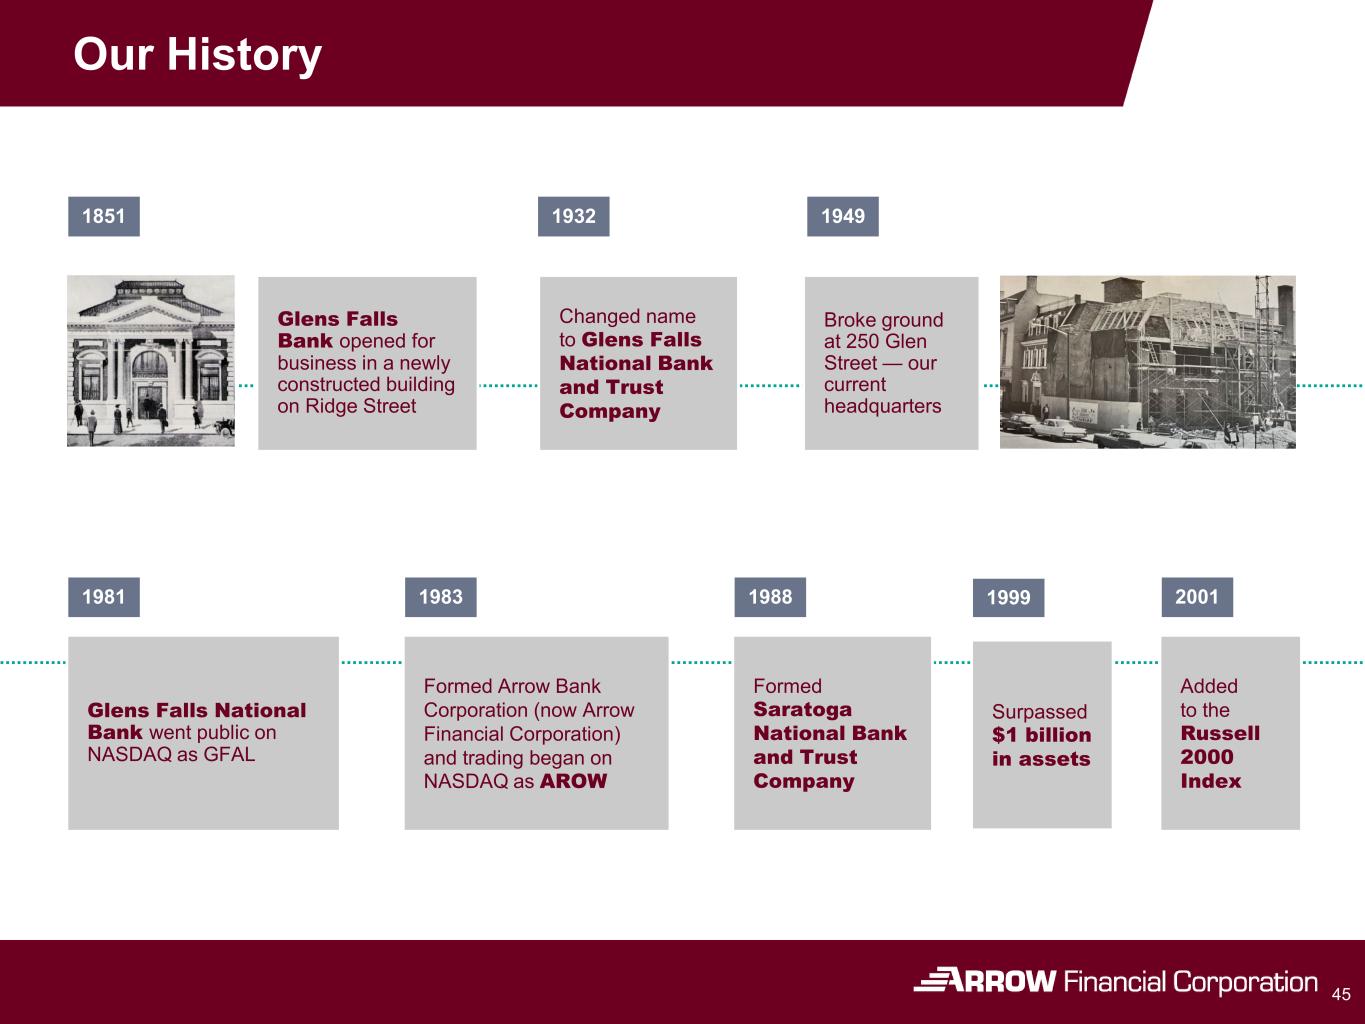
Our History 45 Glens Falls Bank opened for business in a newly constructed building on Ridge Street 1851 1932 Changed name to Glens Falls National Bank and Trust Company 1949 Broke ground at 250 Glen Street — our current headquarters 1981 Glens Falls National Bank went public on NASDAQ as GFAL 1983 Formed Arrow Bank Corporation (now Arrow Financial Corporation) and trading began on NASDAQ as AROW 1988 Formed Saratoga National Bank and Trust Company 1999 Surpassed $1 billion in assets 2001 Added to the Russell 2000 Index
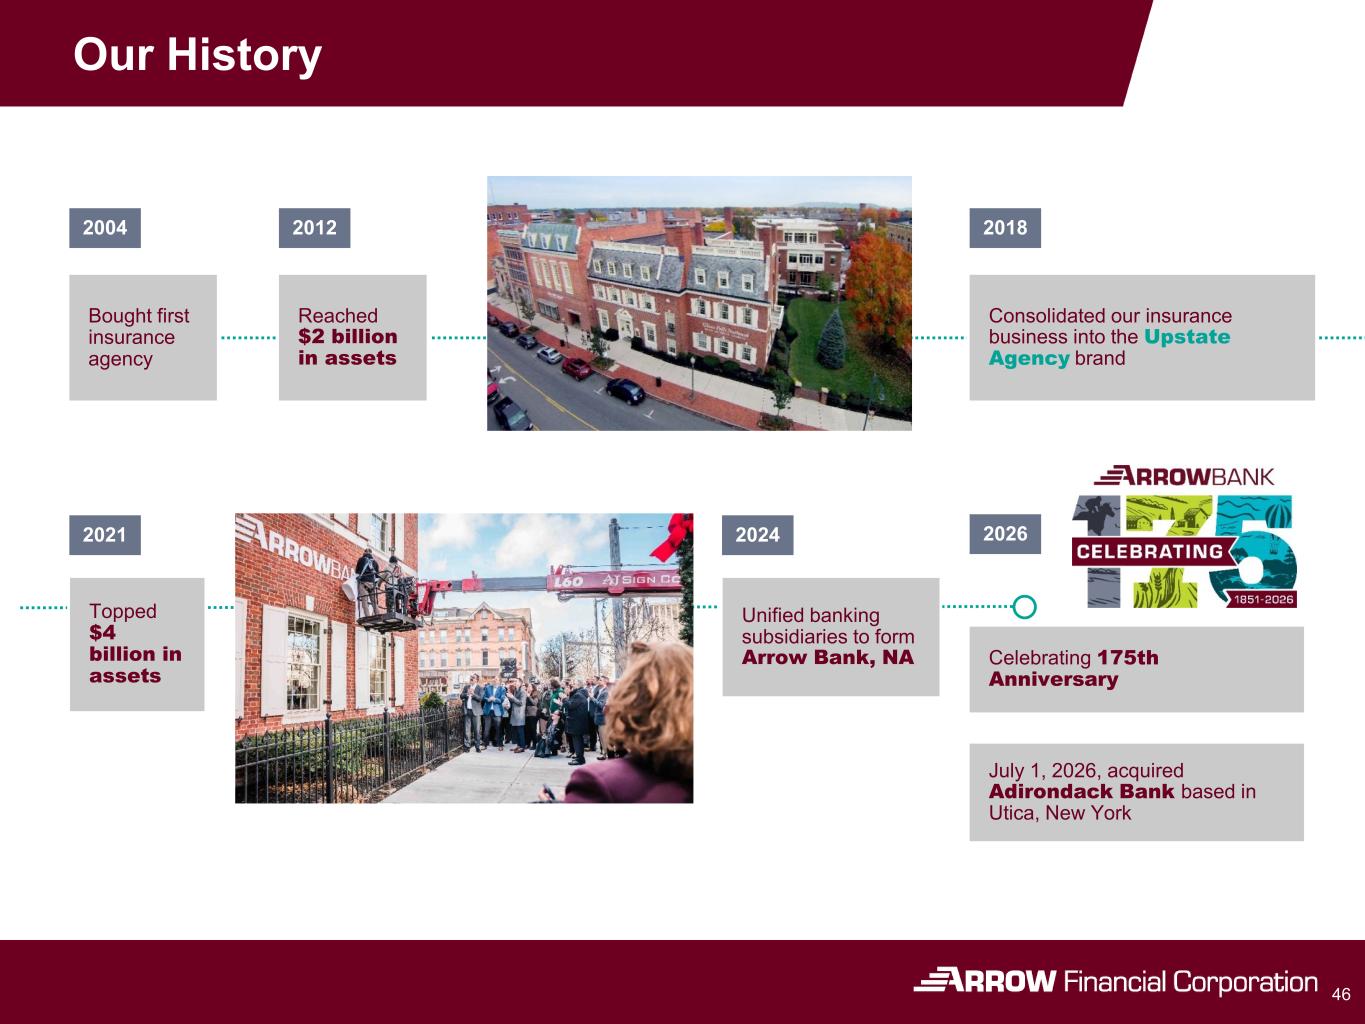
Our History 46 Bought first insurance agency 2004 Reached $2 billion in assets 2012 Consolidated our insurance business into the Upstate Agency brand 2018 2021 Topped $4 billion in assets 2024 Unified banking subsidiaries to form Arrow Bank, NA 2026 Celebrating 175th Anniversary v July 1, 2026, acquired Adirondack Bank based in Utica, New York
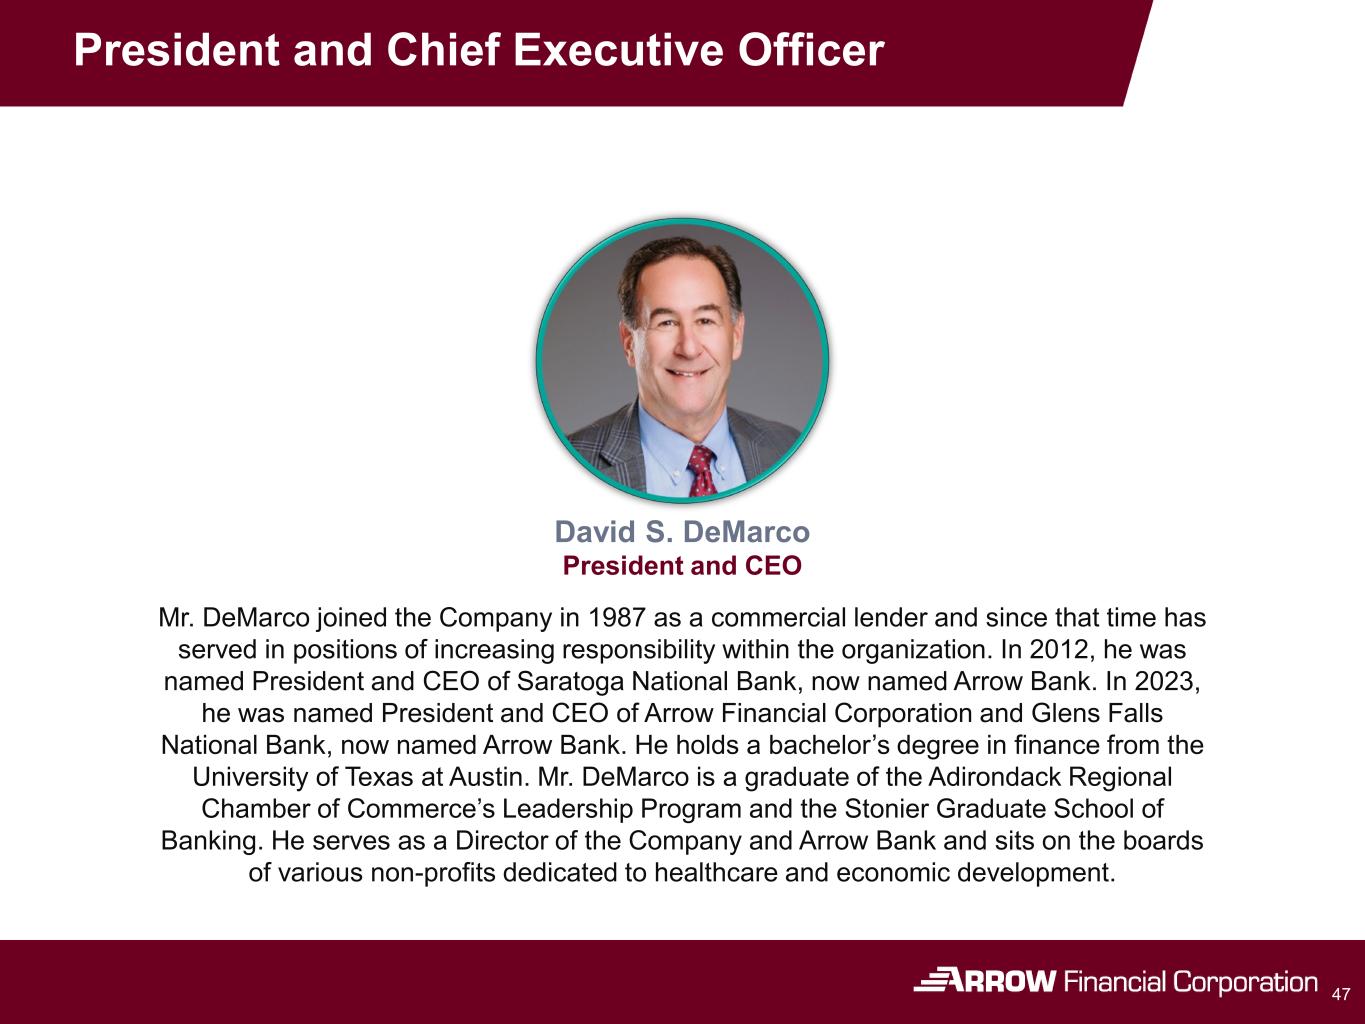
President and Chief Executive Officer 47 Mr. DeMarco joined the Company in 1987 as a commercial lender and since that time has served in positions of increasing responsibility within the organization. In 2012, he was named President and CEO of Saratoga National Bank, now named Arrow Bank. In 2023, he was named President and CEO of Arrow Financial Corporation and Glens Falls National Bank, now named Arrow Bank. He holds a bachelor’s degree in finance from the University of Texas at Austin. Mr. DeMarco is a graduate of the Adirondack Regional Chamber of Commerce’s Leadership Program and the Stonier Graduate School of Banking. He serves as a Director of the Company and Arrow Bank and sits on the boards of various non-profits dedicated to healthcare and economic development. David S. DeMarco President and CEO
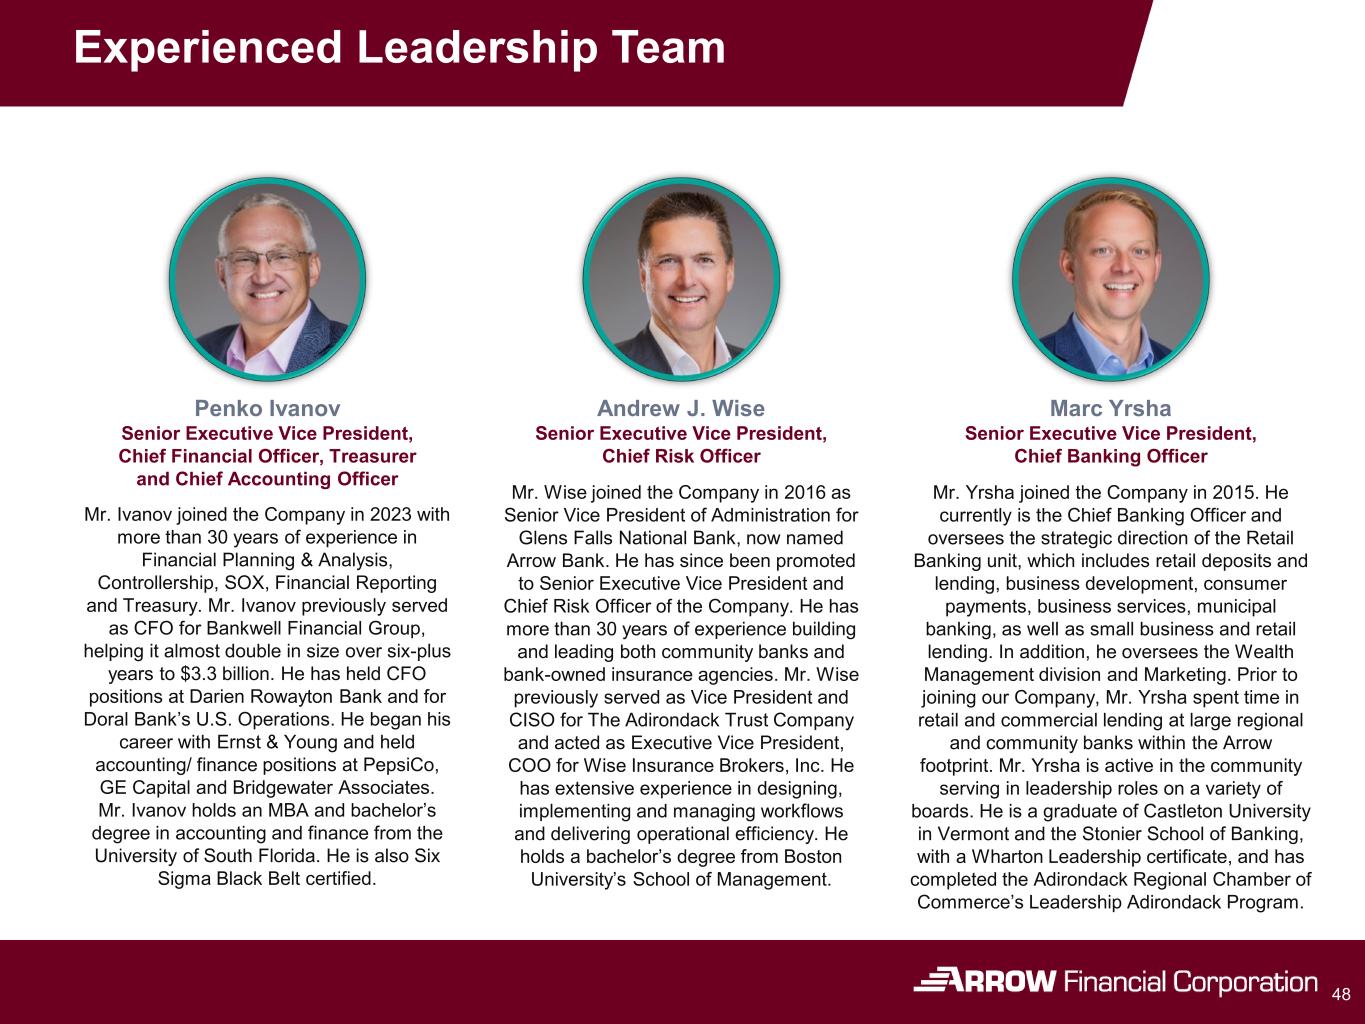
Experienced Leadership Team 48 Penko Ivanov Senior Executive Vice President, Chief Financial Officer, Treasurer and Chief Accounting Officer Andrew J. Wise Senior Executive Vice President, Chief Risk Officer Marc Yrsha Senior Executive Vice President, Chief Banking Officer Mr. Ivanov joined the Company in 2023 with more than 30 years of experience in Financial Planning & Analysis, Controllership, SOX, Financial Reporting and Treasury. Mr. Ivanov previously served as CFO for Bankwell Financial Group, helping it almost double in size over six-plus years to $3.3 billion. He has held CFO positions at Darien Rowayton Bank and for Doral Bank’s U.S. Operations. He began his career with Ernst & Young and held accounting/ finance positions at PepsiCo, GE Capital and Bridgewater Associates. Mr. Ivanov holds an MBA and bachelor’s degree in accounting and finance from the University of South Florida. He is also Six Sigma Black Belt certified. Mr. Wise joined the Company in 2016 as Senior Vice President of Administration for Glens Falls National Bank, now named Arrow Bank. He has since been promoted to Senior Executive Vice President and Chief Risk Officer of the Company. He has more than 30 years of experience building and leading both community banks and bank-owned insurance agencies. Mr. Wise previously served as Vice President and CISO for The Adirondack Trust Company and acted as Executive Vice President, COO for Wise Insurance Brokers, Inc. He has extensive experience in designing, implementing and managing workflows and delivering operational efficiency. He holds a bachelor’s degree from Boston University’s School of Management. Mr. Yrsha joined the Company in 2015. He currently is the Chief Banking Officer and oversees the strategic direction of the Retail Banking unit, which includes retail deposits and lending, business development, consumer payments, business services, municipal banking, as well as small business and retail lending. In addition, he oversees the Wealth Management division and Marketing. Prior to joining our Company, Mr. Yrsha spent time in retail and commercial lending at large regional and community banks within the Arrow footprint. Mr. Yrsha is active in the community serving in leadership roles on a variety of boards. He is a graduate of Castleton University in Vermont and the Stonier School of Banking, with a Wharton Leadership certificate, and has completed the Adirondack Regional Chamber of Commerce’s Leadership Adirondack Program.
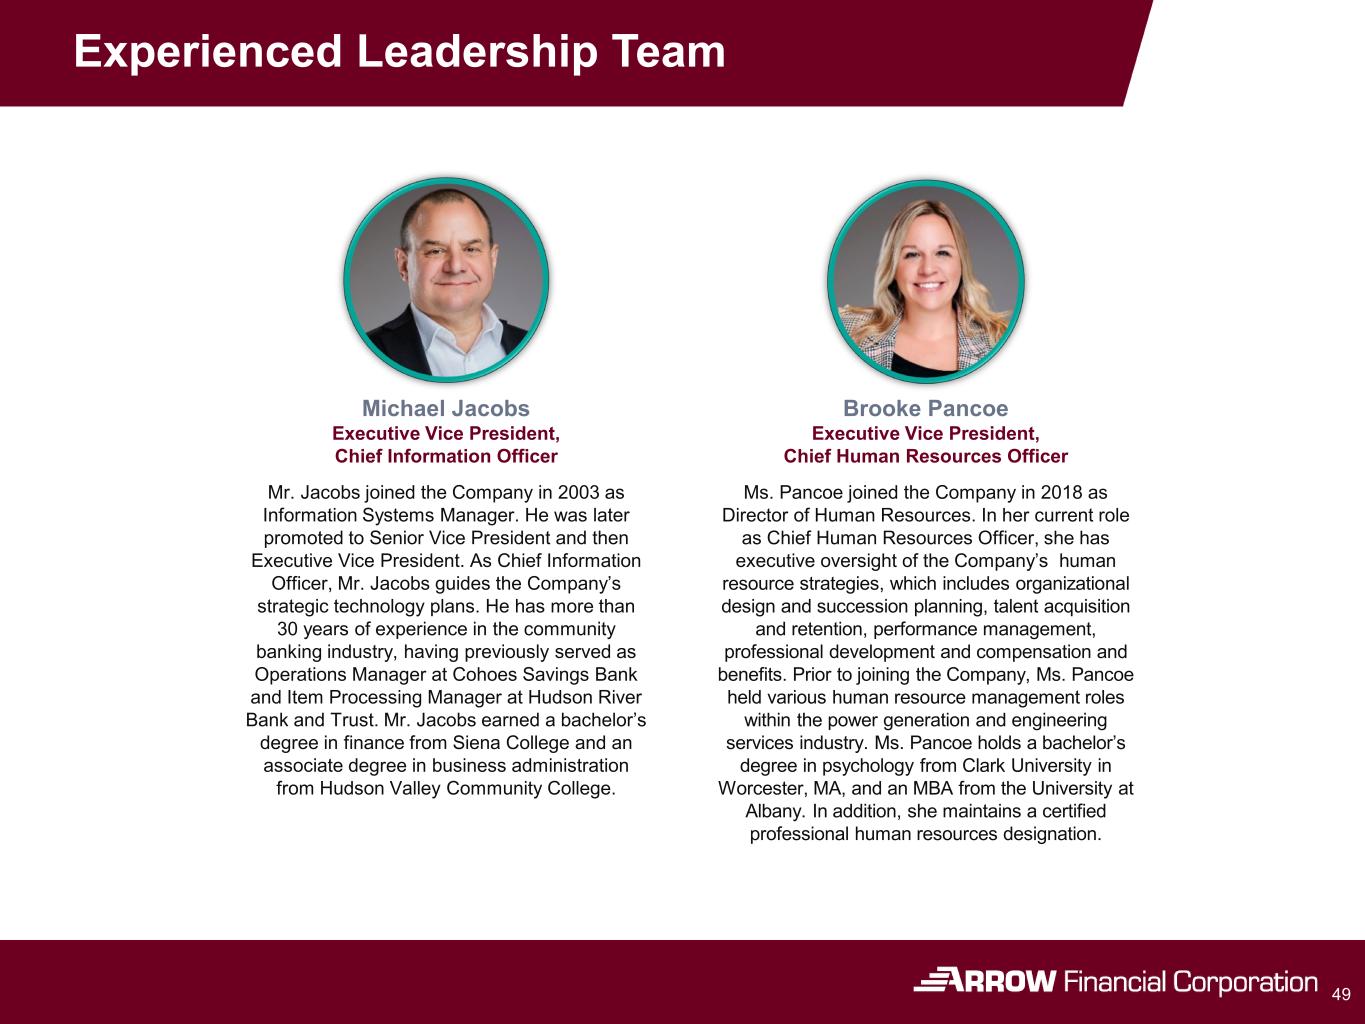
49 Michael Jacobs Executive Vice President, Chief Information Officer Brooke Pancoe Executive Vice President, Chief Human Resources Officer Mr. Jacobs joined the Company in 2003 as Information Systems Manager. He was later promoted to Senior Vice President and then Executive Vice President. As Chief Information Officer, Mr. Jacobs guides the Company’s strategic technology plans. He has more than 30 years of experience in the community banking industry, having previously served as Operations Manager at Cohoes Savings Bank and Item Processing Manager at Hudson River Bank and Trust. Mr. Jacobs earned a bachelor’s degree in finance from Siena College and an associate degree in business administration from Hudson Valley Community College. Ms. Pancoe joined the Company in 2018 as Director of Human Resources. In her current role as Chief Human Resources Officer, she has executive oversight of the Company’s human resource strategies, which includes organizational design and succession planning, talent acquisition and retention, performance management, professional development and compensation and benefits. Prior to joining the Company, Ms. Pancoe held various human resource management roles within the power generation and engineering services industry. Ms. Pancoe holds a bachelor’s degree in psychology from Clark University in Worcester, MA, and an MBA from the University at Albany. In addition, she maintains a certified professional human resources designation. Experienced Leadership Team
APPENDIX 50
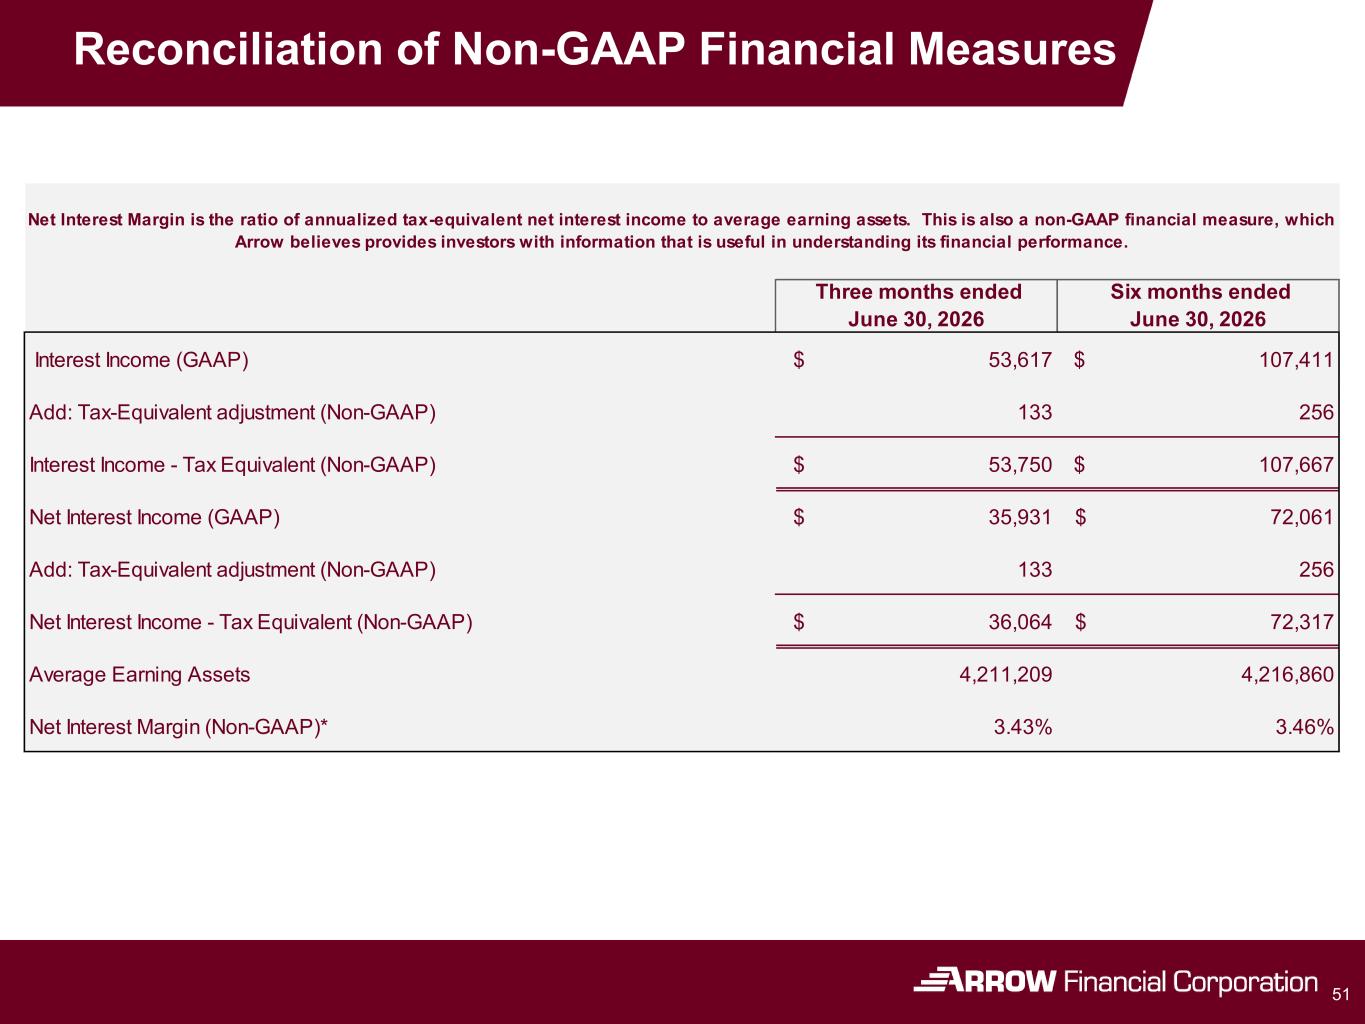
Reconciliation of Non-GAAP Financial Measures 51 Three months ended June 30, 2026 Six months ended June 30, 2026 Interest Income (GAAP) $ 53,617 $ 107,411 Add: Tax-Equivalent adjustment (Non-GAAP) 133 256 Interest Income - Tax Equivalent (Non-GAAP) $ 53,750 $ 107,667 Net Interest Income (GAAP) $ 35,931 $ 72,061 Add: Tax-Equivalent adjustment (Non-GAAP) 133 256 Net Interest Income - Tax Equivalent (Non-GAAP) $ 36,064 $ 72,317 Average Earning Assets 4,211,209 4,216,860 Net Interest Margin (Non-GAAP)* 3.43% 3.46% Net Interest Margin is the ratio of annualized tax-equivalent net interest income to average earning assets. This is also a non-GAAP financial measure, which Arrow believes provides investors with information that is useful in understanding its financial performance.
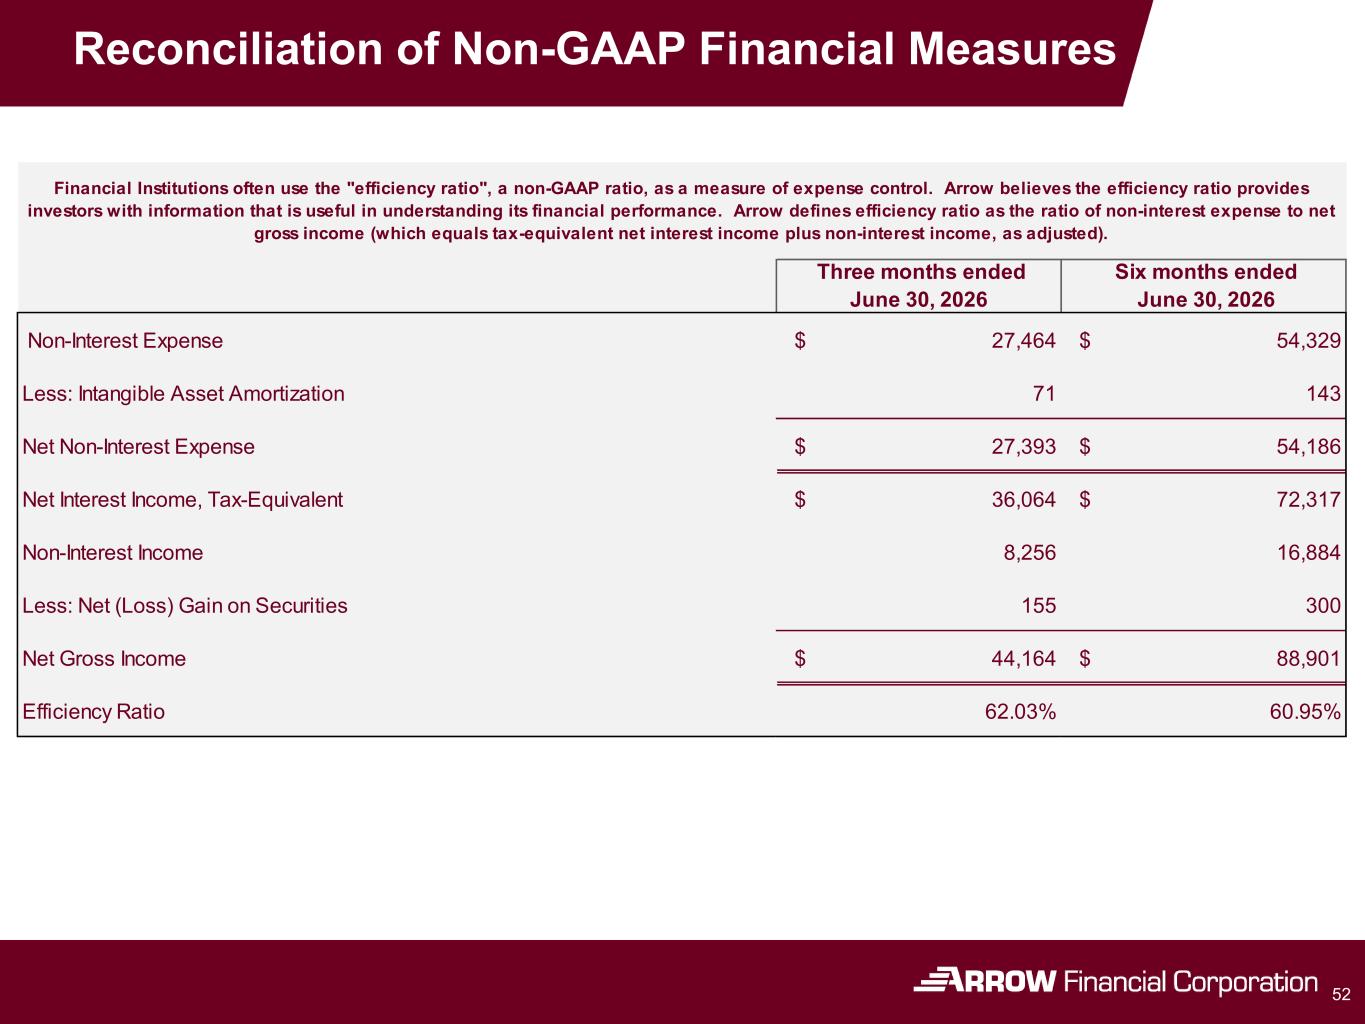
Reconciliation of Non-GAAP Financial Measures 52 Three months ended June 30, 2026 Six months ended June 30, 2026 Non-Interest Expense $ 27,464 $ 54,329 Less: Intangible Asset Amortization 71 143 Net Non-Interest Expense $ 27,393 $ 54,186 Net Interest Income, Tax-Equivalent $ 36,064 $ 72,317 Non-Interest Income 8,256 16,884 Less: Net (Loss) Gain on Securities 155 300 Net Gross Income $ 44,164 $ 88,901 Efficiency Ratio 62.03% 60.95% Financial Institutions often use the "efficiency ratio", a non-GAAP ratio, as a measure of expense control. Arrow believes the efficiency ratio provides investors with information that is useful in understanding its financial performance. Arrow defines efficiency ratio as the ratio of non-interest expense to net gross income (which equals tax-equivalent net interest income plus non-interest income, as adjusted).
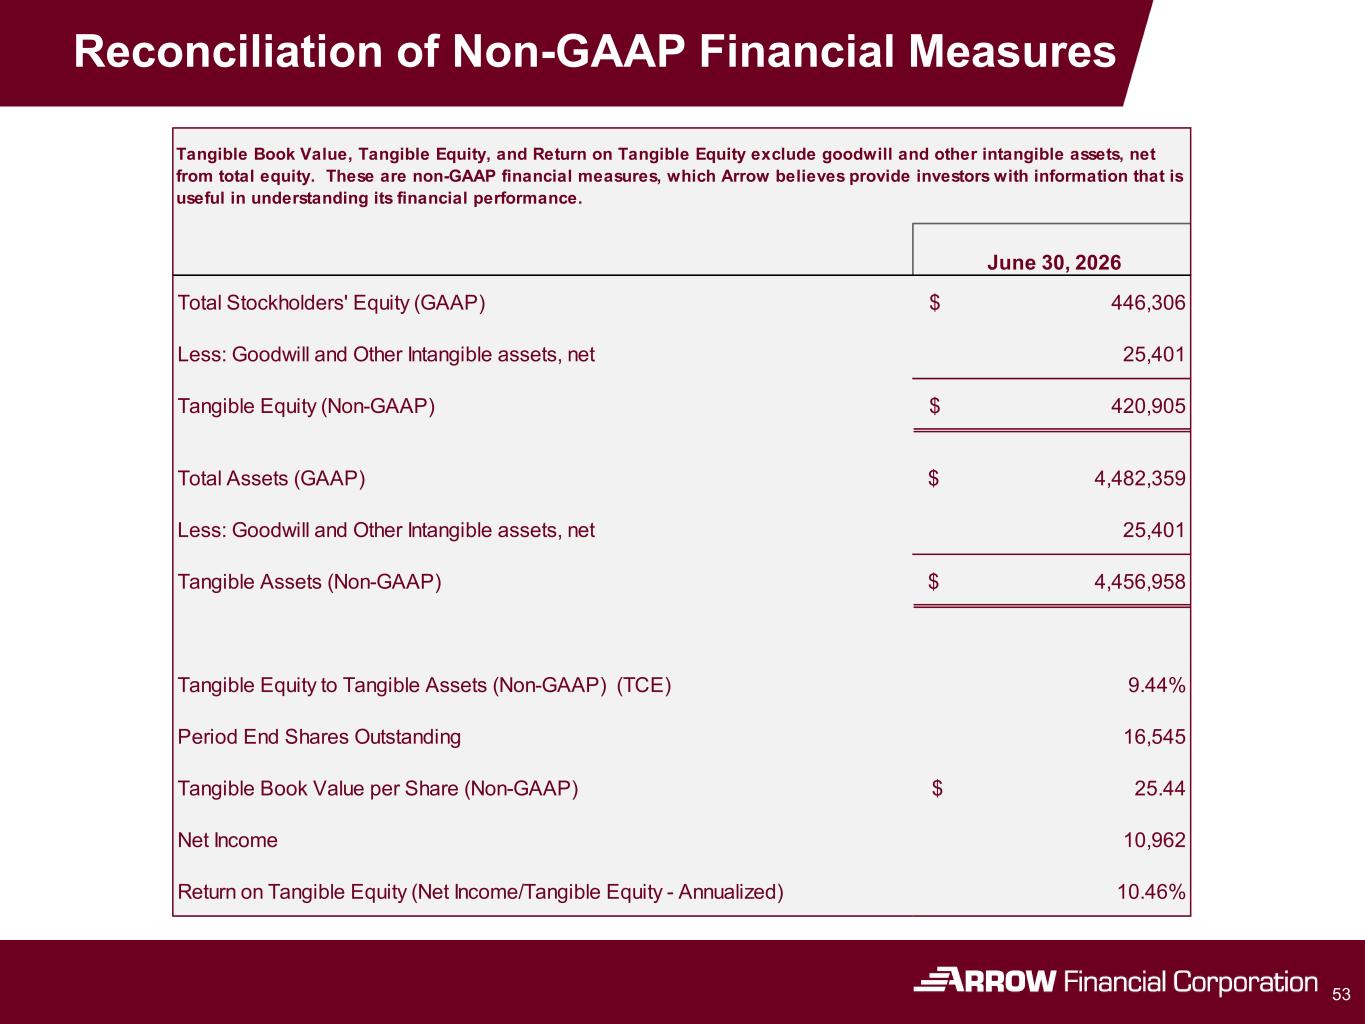
Reconciliation of Non-GAAP Financial Measures 53 June 30, 2026 Total Stockholders' Equity (GAAP) $ 446,306 Less: Goodwill and Other Intangible assets, net 25,401 Tangible Equity (Non-GAAP) $ 420,905 Total Assets (GAAP) $ 4,482,359 Less: Goodwill and Other Intangible assets, net 25,401 Tangible Assets (Non-GAAP) $ 4,456,958 Tangible Equity to Tangible Assets (Non-GAAP) (TCE) 9.44% Period End Shares Outstanding 16,545 Tangible Book Value per Share (Non-GAAP) $ 25.44 Net Income 10,962 Return on Tangible Equity (Net Income/Tangible Equity - Annualized) 10.46% Tangible Book Value, Tangible Equity, and Return on Tangible Equity exclude goodwill and other intangible assets, net from total equity. These are non-GAAP financial measures, which Arrow believes provide investors with information that is useful in understanding its financial performance.
THANK YOU! 54