Operator
Thank you for standing by. My name is Kate and I will be your conference operator today. At this time, I would like to welcome everyone to the AH Realty Trust AHRT 2Q26 earnings call. All lines have been placed on you to prevent any background noise. After the speaker's remark, there will be a question and answer session. If you would like to ask a question during this time, simply press start followed by the number one on your telephone keypad. If you would like to rejoin your question, press star 1 again. Thank you. I would now like to turn the call over to Chelsea Forrest, EVP of Investor Relations. Please go ahead.
Good morning, and thank you for joining AH Reality Trust's second quarter 2026 earnings conference call and webcast. On the call this morning, in addition to myself, is Sean Tibbetts, Chairman, President, and CEO, Matthew Barnes-Smith, CFO, and Craig Romero, EVP of Asset Management. The press release announcing our second quarter earnings along with our supplemental package were distributed yesterday afternoon. A telephonic replay will be available shortly after the conclusion of the call through Thursday, September 3, 2026. These numbers to access the replay are provided in the earnings press release. For those who listened to the rebroadcast of this presentation, we remind you that the remarks made herein are as of today, August 4, 2026, and will not be updated subsequent to this initial earnings call. During this call, we may make forward-looking statements, including statements related to the future performance of our portfolio, transactions involving our multifamily portfolio, our real estate financing program, and our construction business, and the use of proceeds from such transactions, our rebranding and the efforts thereof, the consequences of our strategic transformation, our liquidity position, as well as comments on our outlook. Listeners are cautioned that any forward-looking statements are based upon management's beliefs, assumptions, and expectations, taking into account information that is currently available. These beliefs, assumptions, and expectations may change as a result of possible events or factors, not all of which are known, and many of which are difficult to predict and generally beyond our control. These risks and uncertainties can cause actual results to differ materially from our current expectations, and we advise listeners to review the forward-looking statement disclosure in our press release that we distributed yesterday, and the risk factors disclosed in documents we have filed with or furnished to the SEC. We will also discuss certain non-GAAP financial measures, including but not limited to FFO, normalized FFO, and FFO as adjusted. Definitions of these non-GAAP measures, as well as reconciliations to the most comparable GAAP measures, are included in the quarterly supplemental package, which is available on our website at ahrealitytrust.com. I will now turn the call over to Sean.
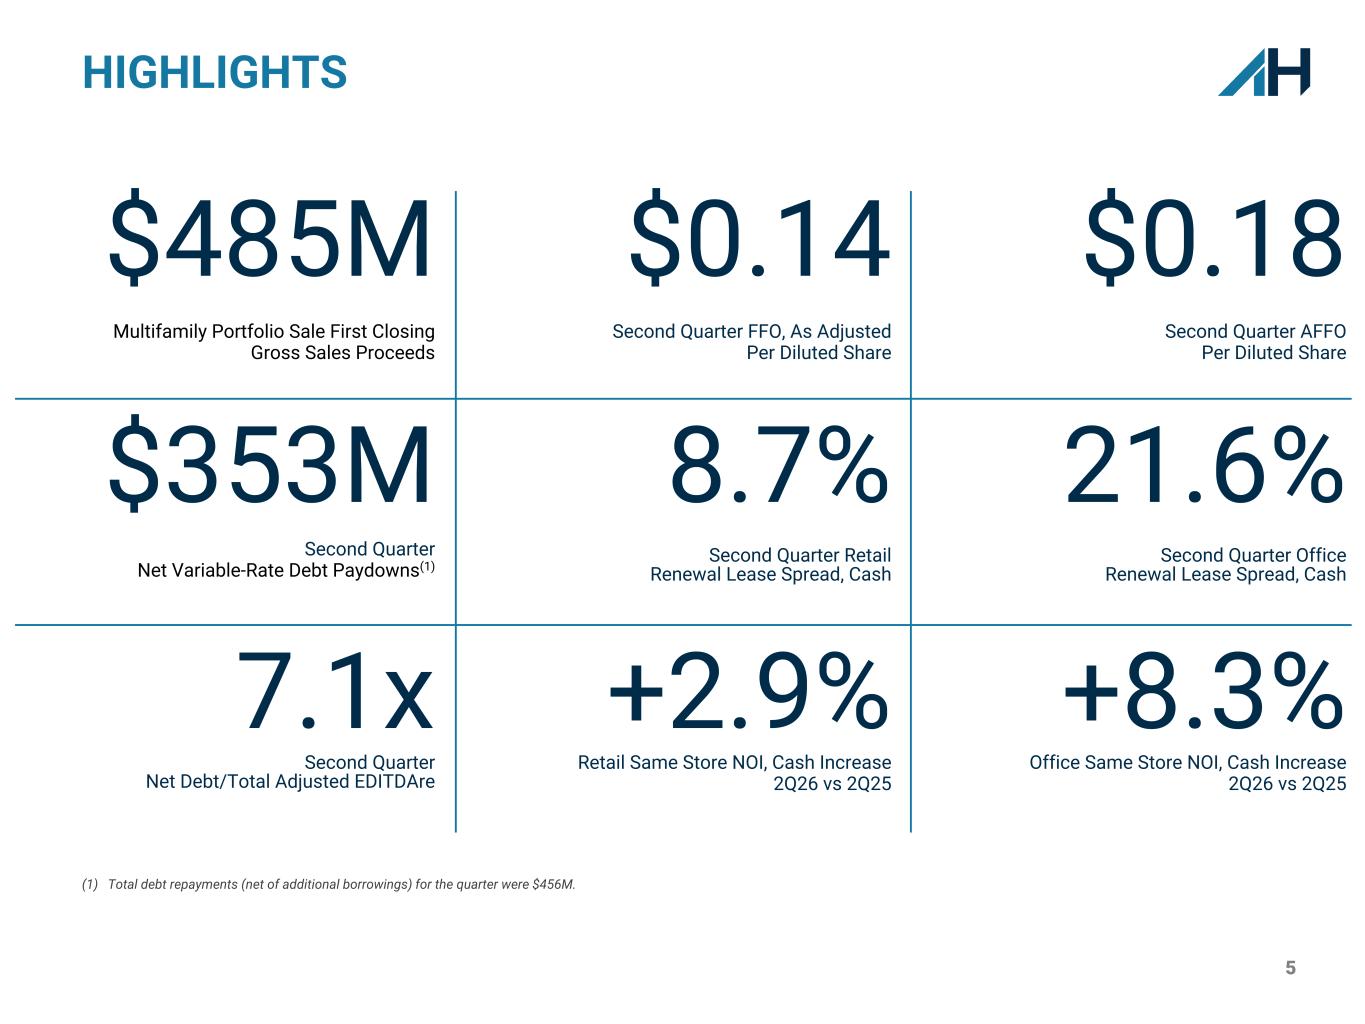
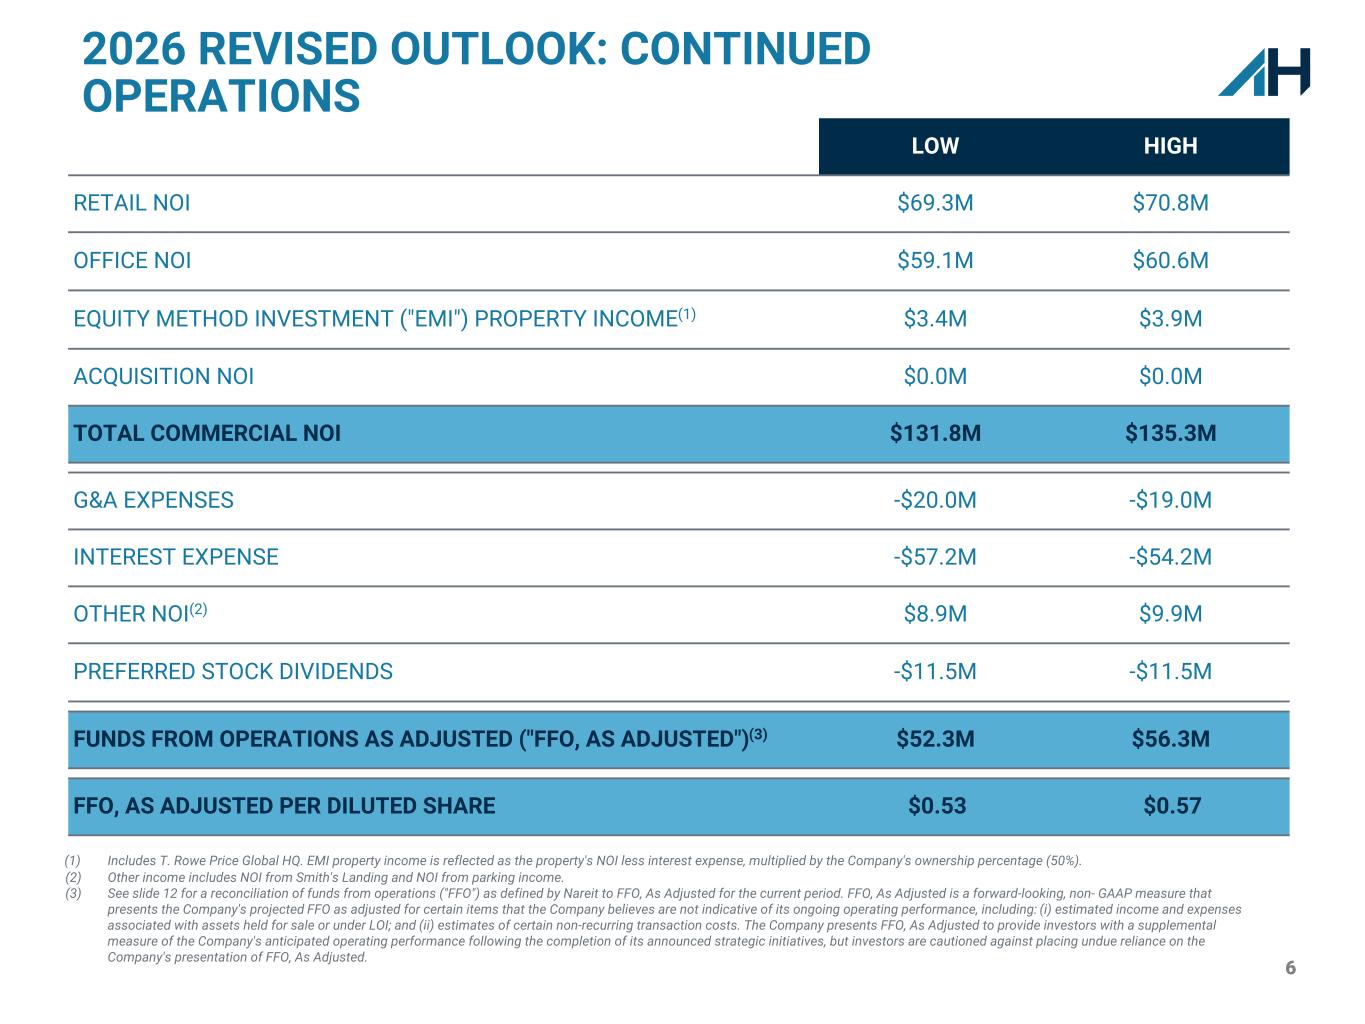
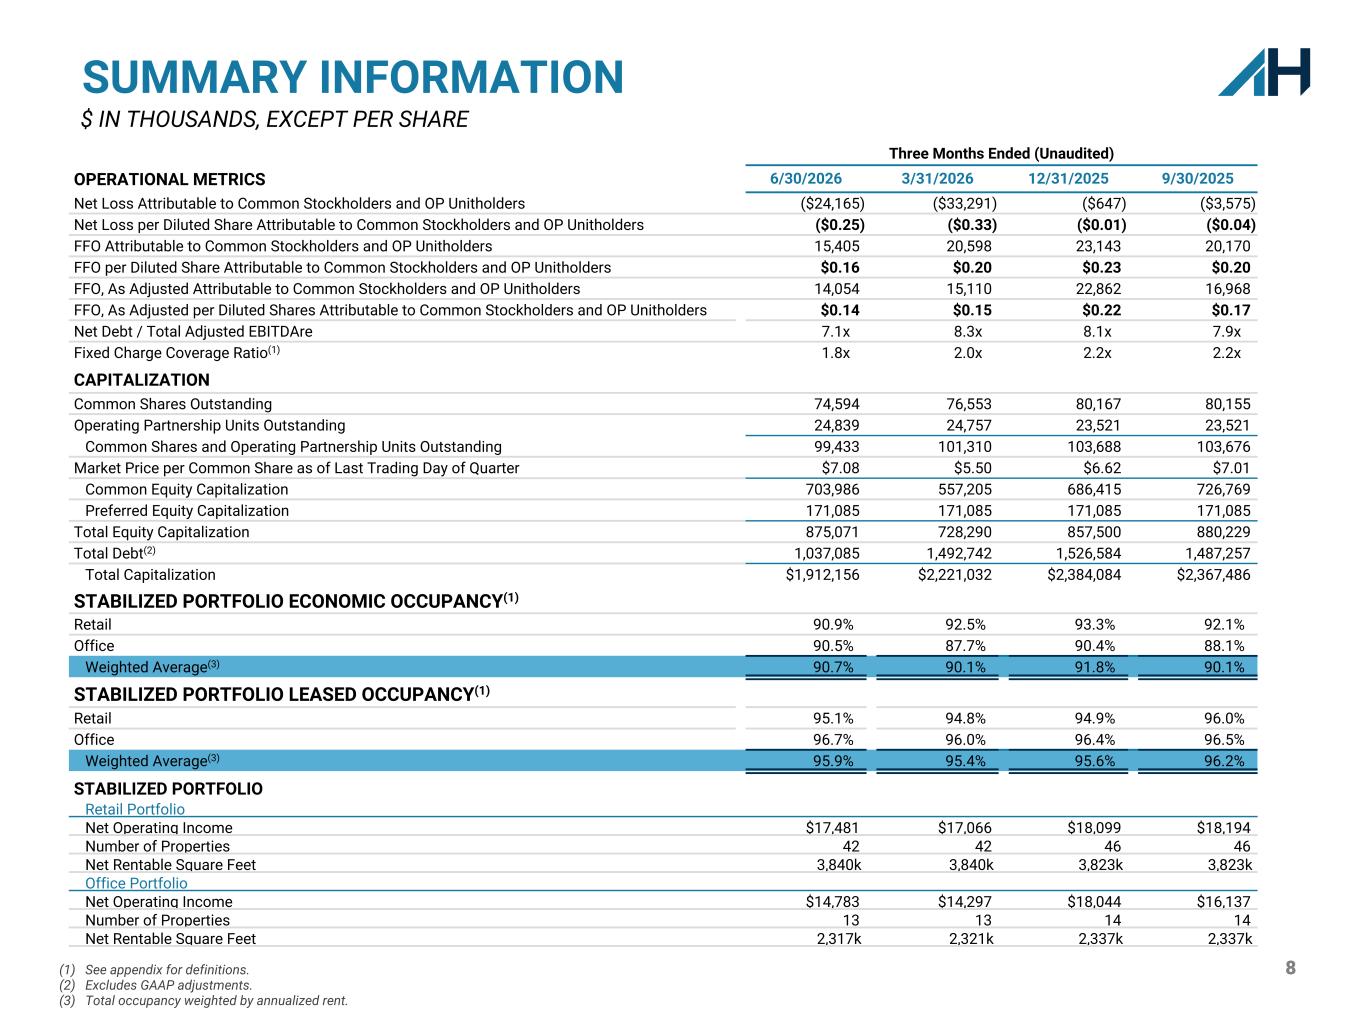
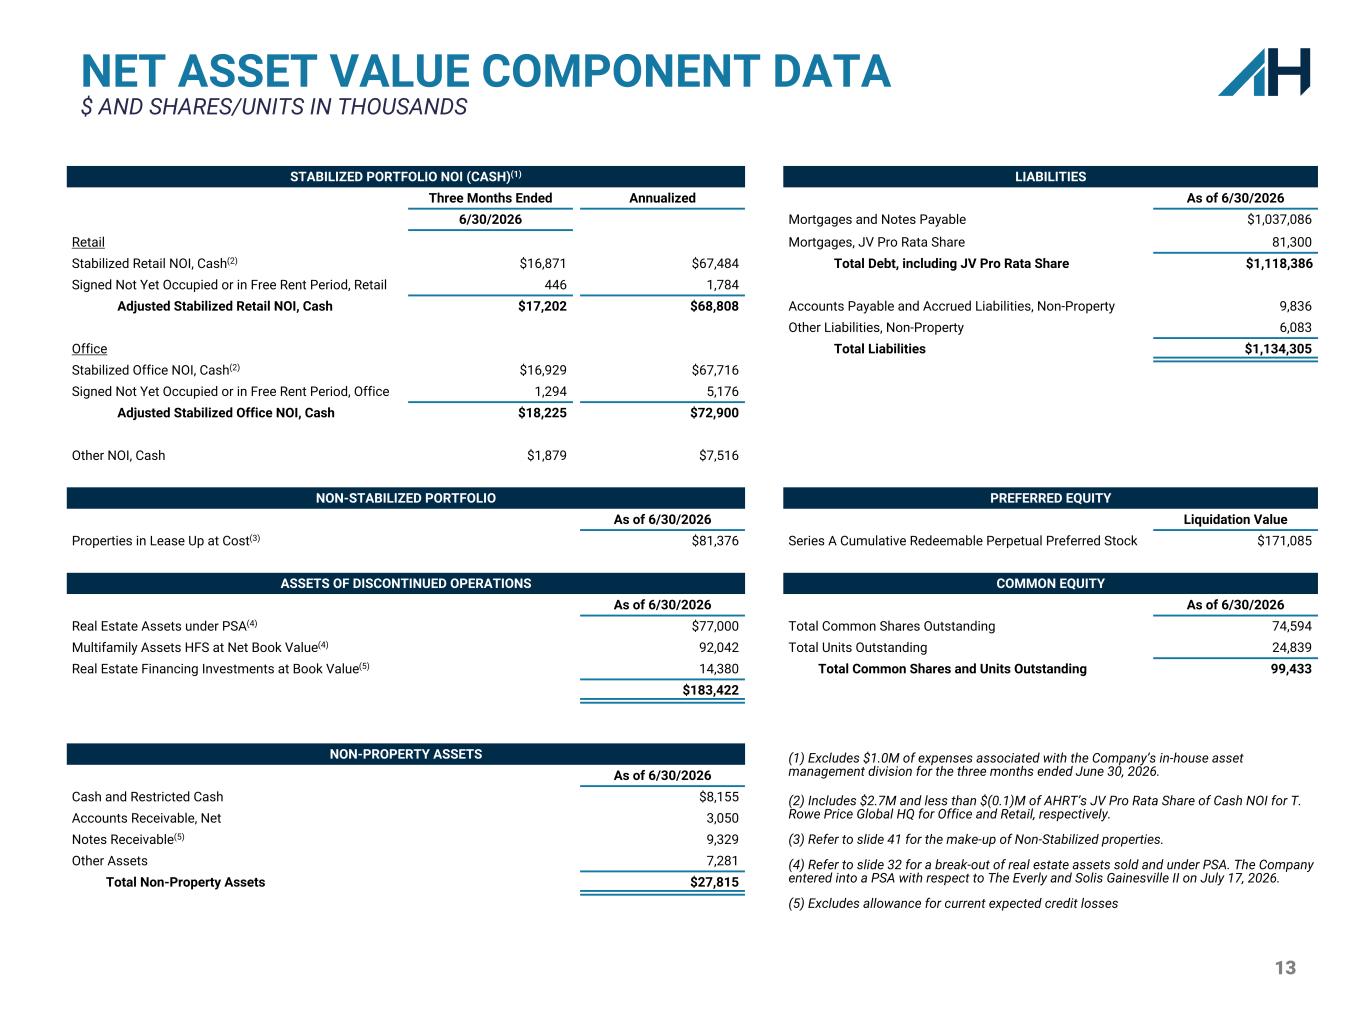
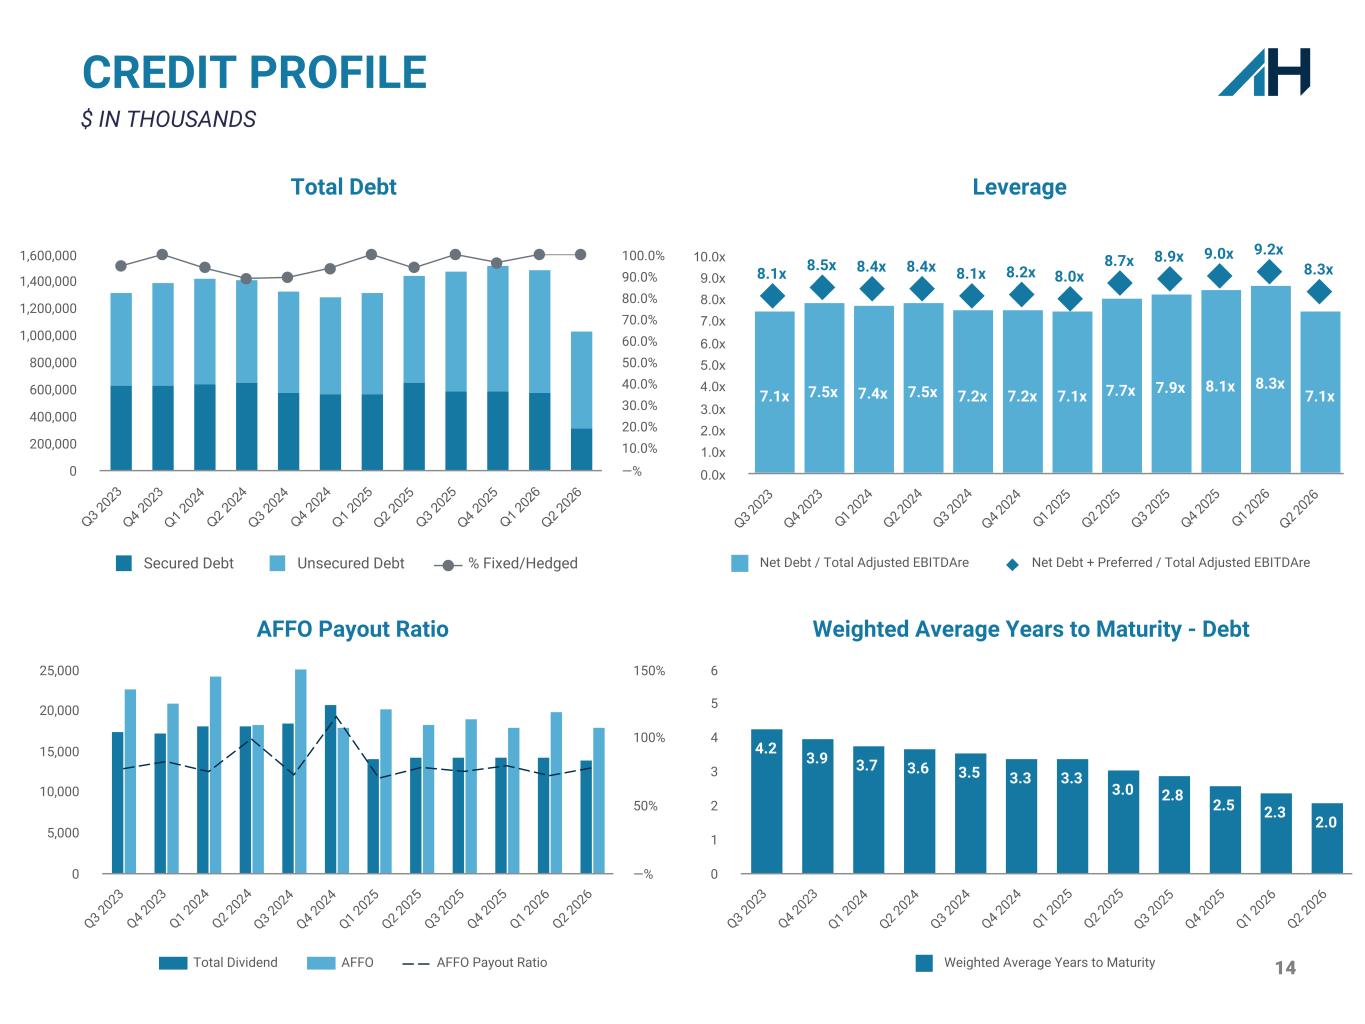
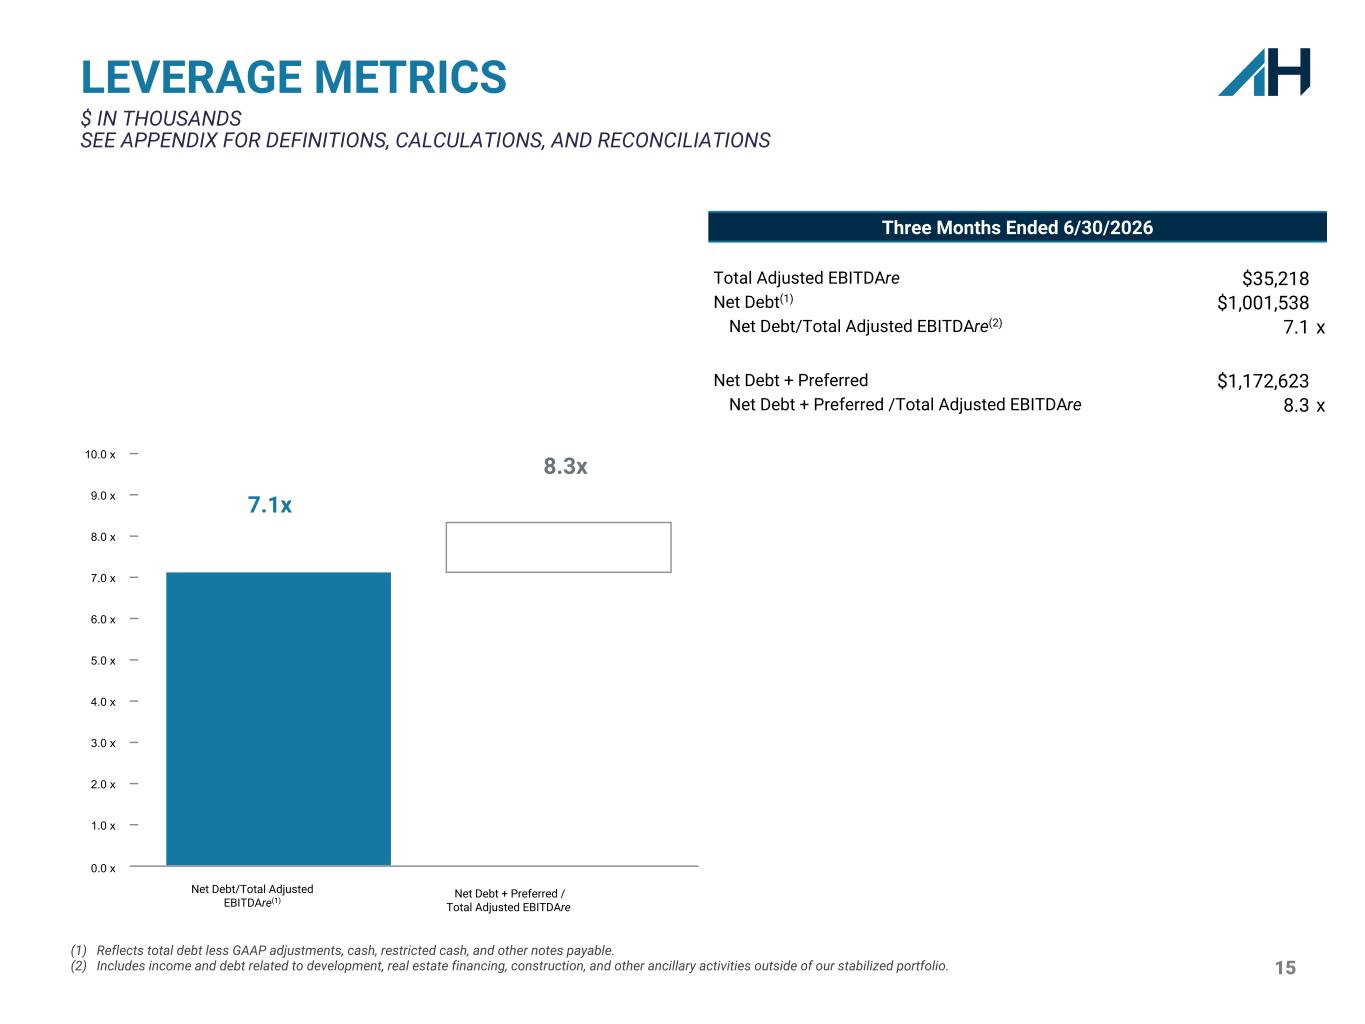
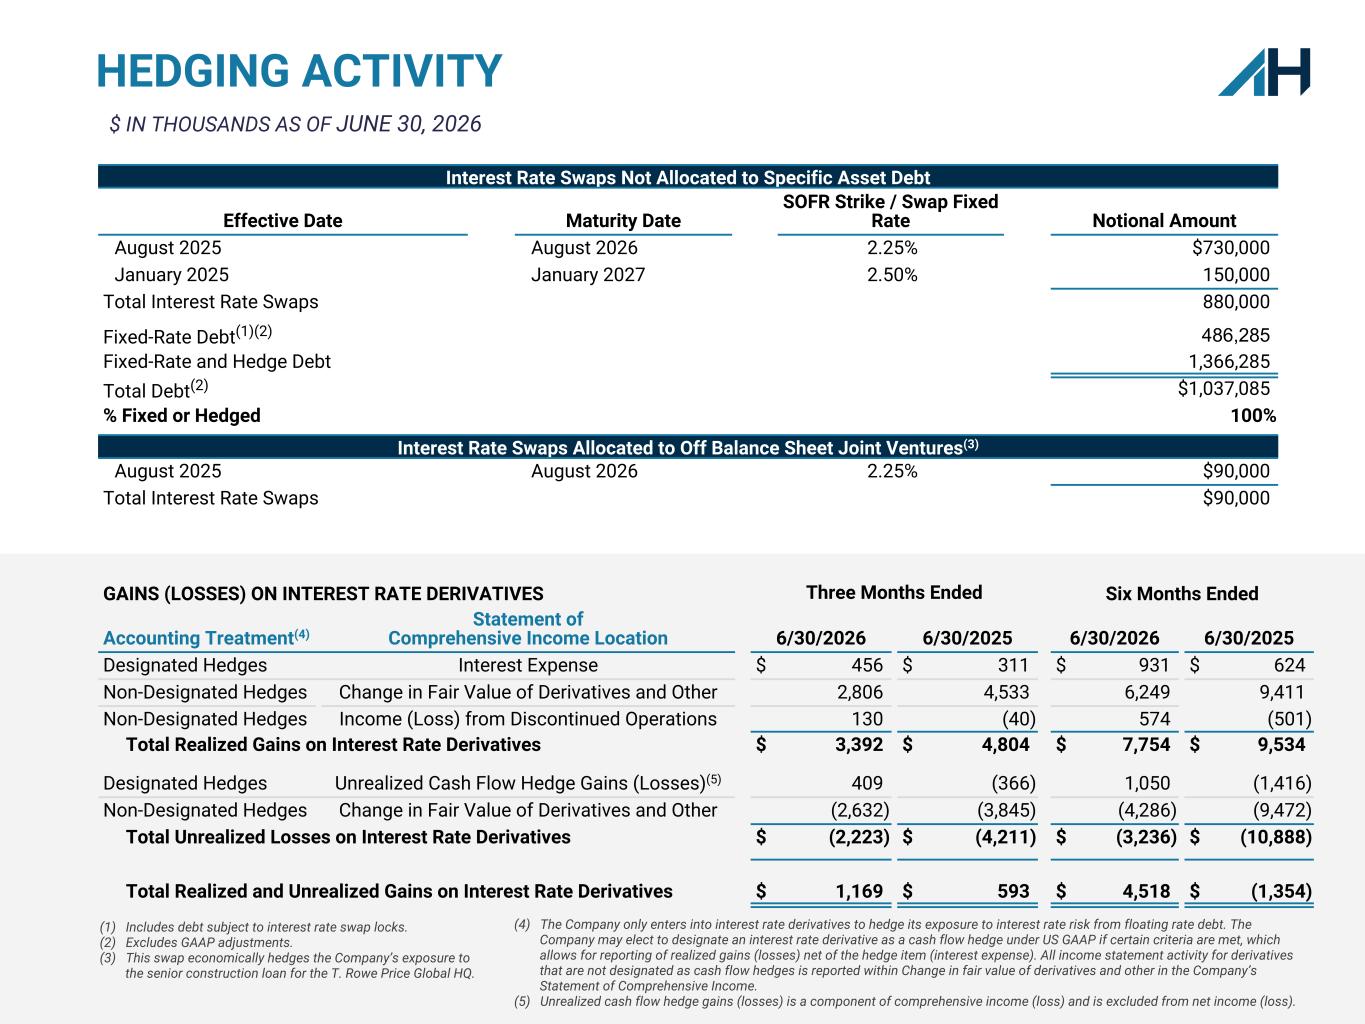
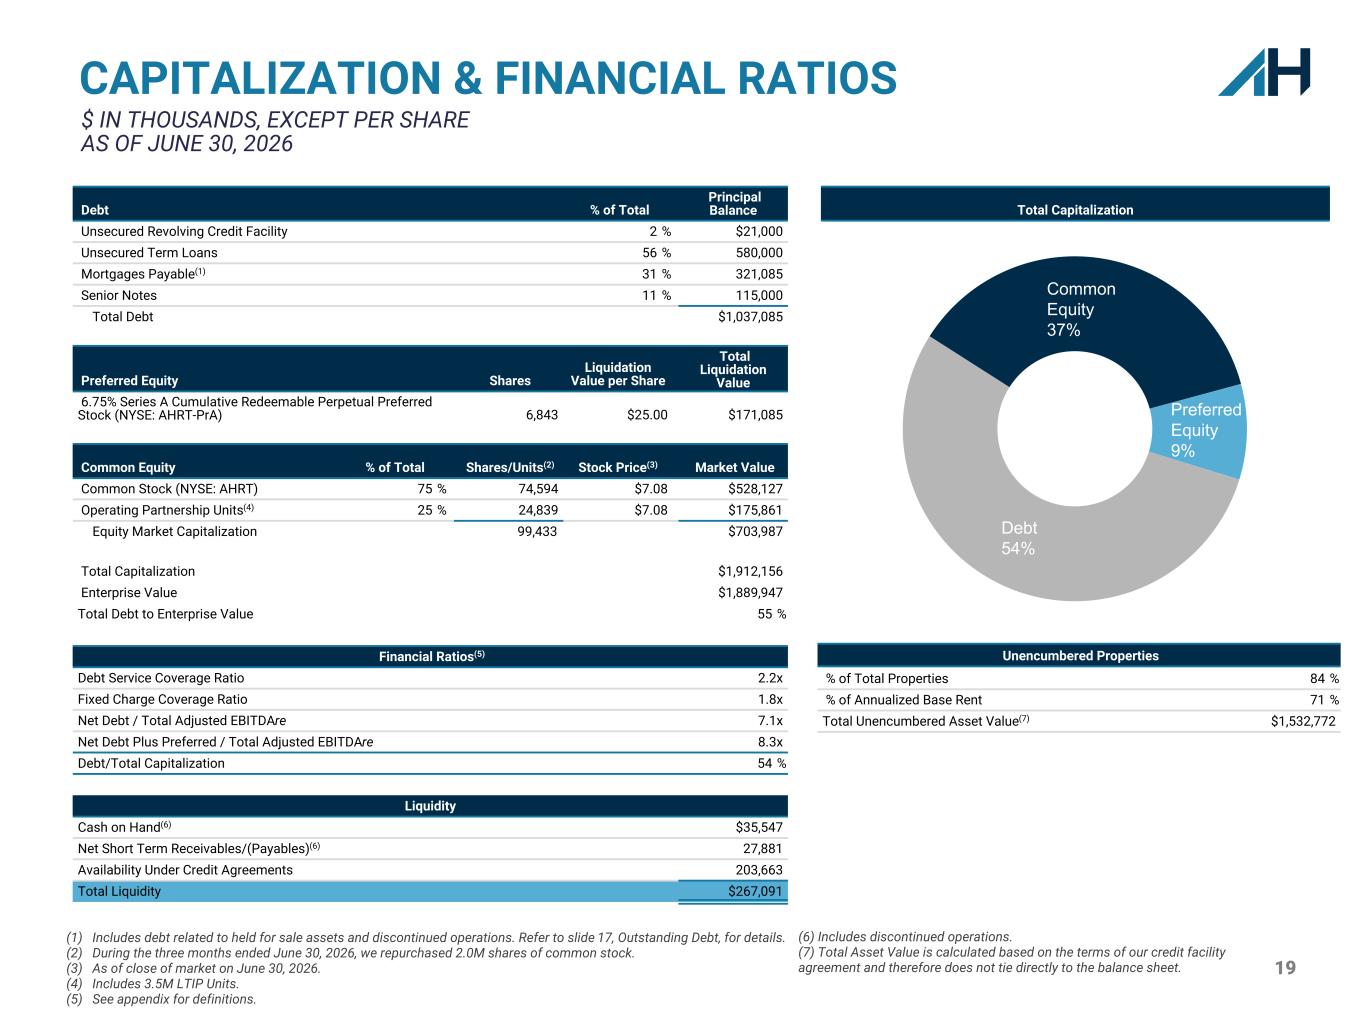
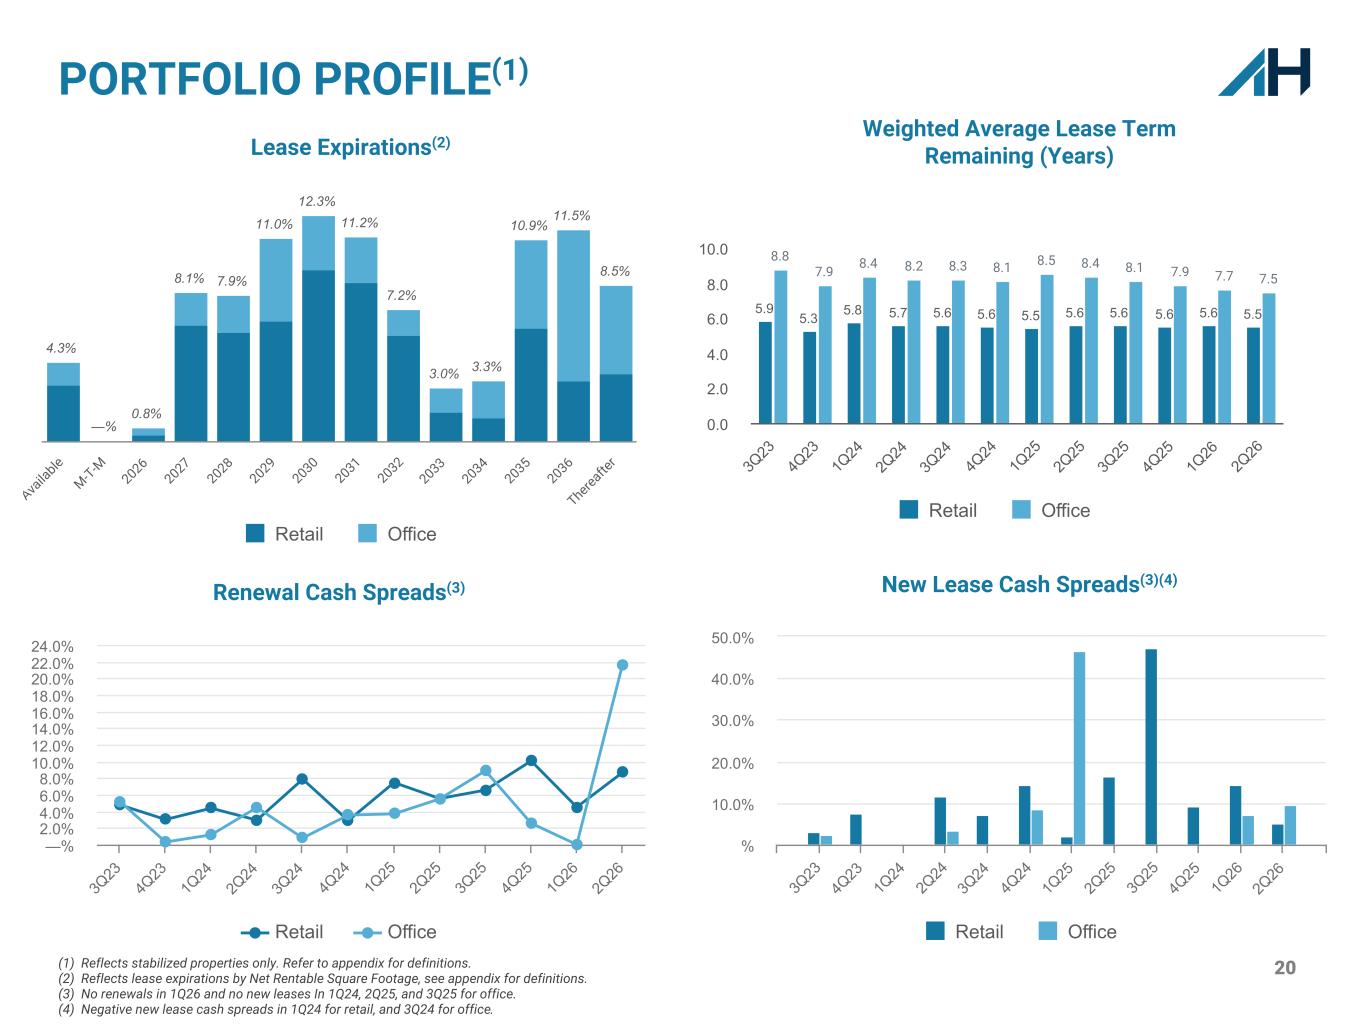
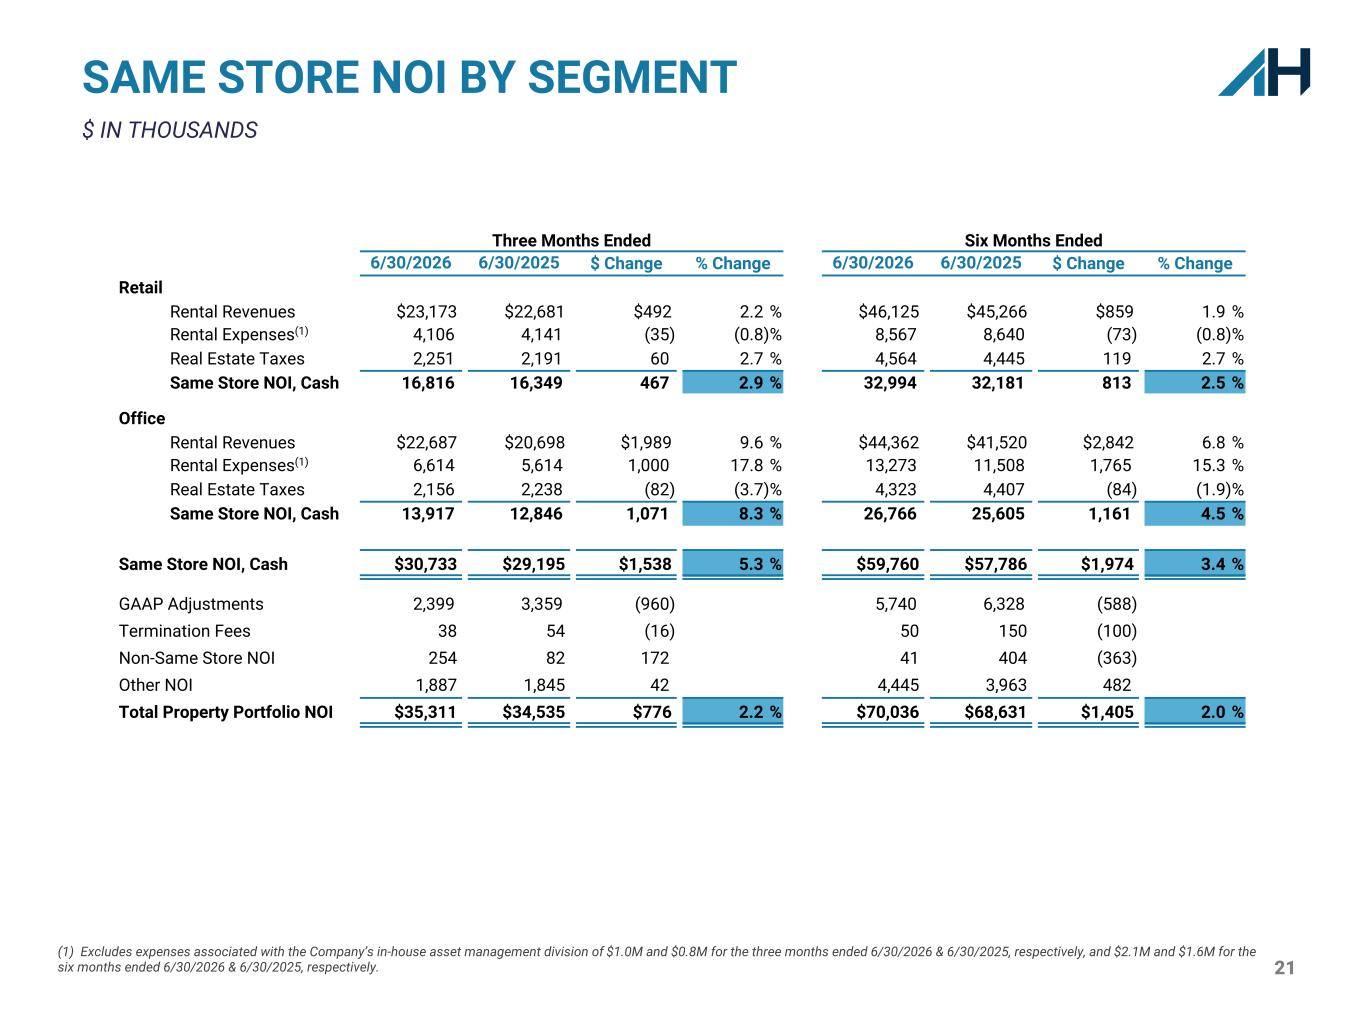
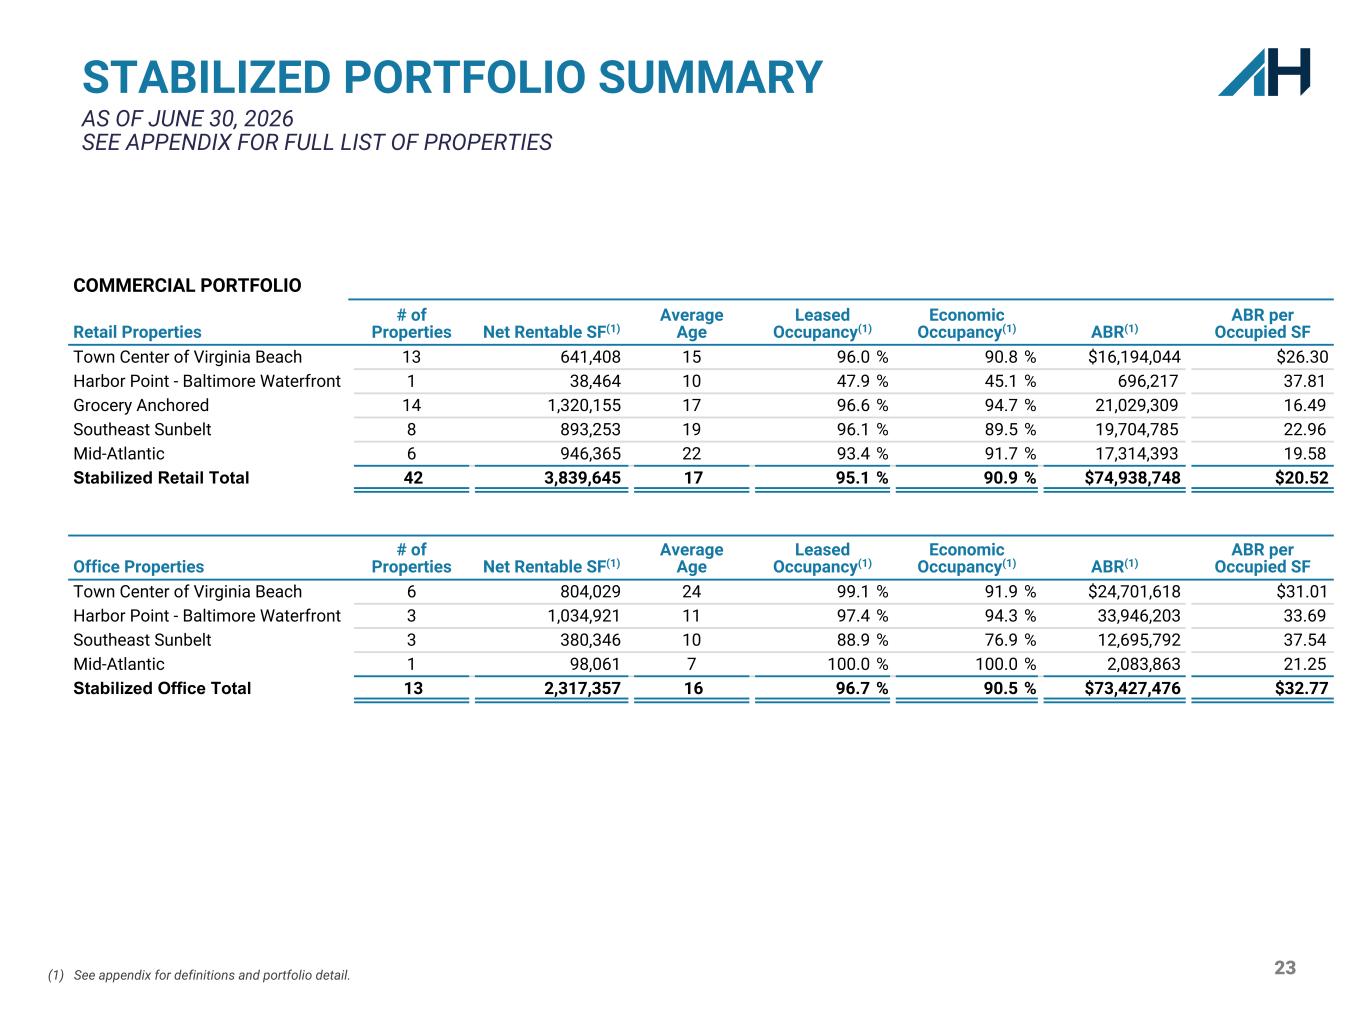
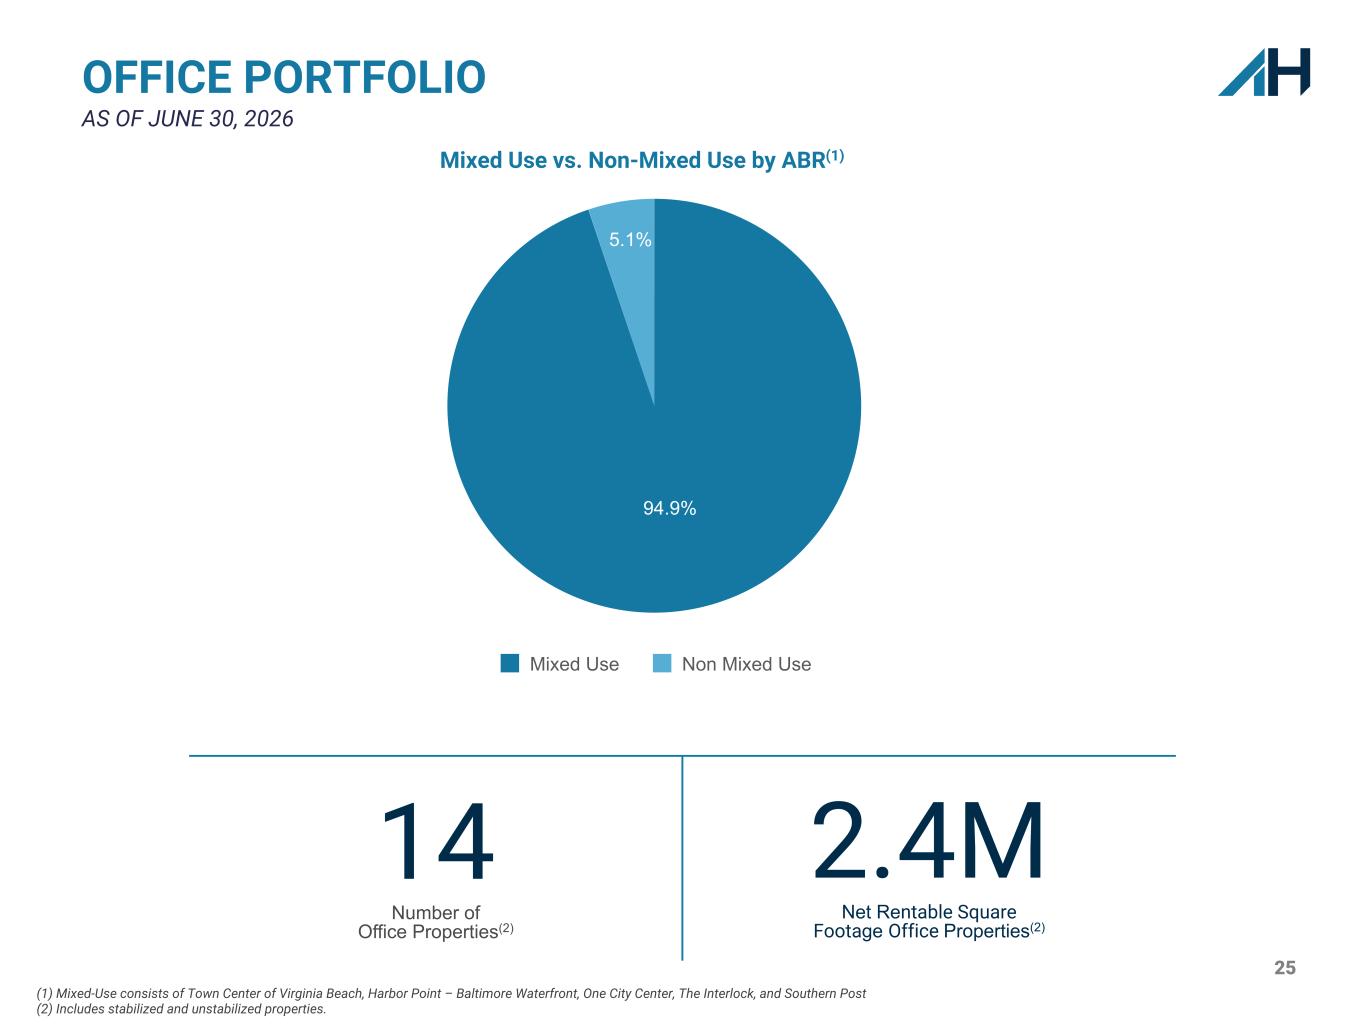
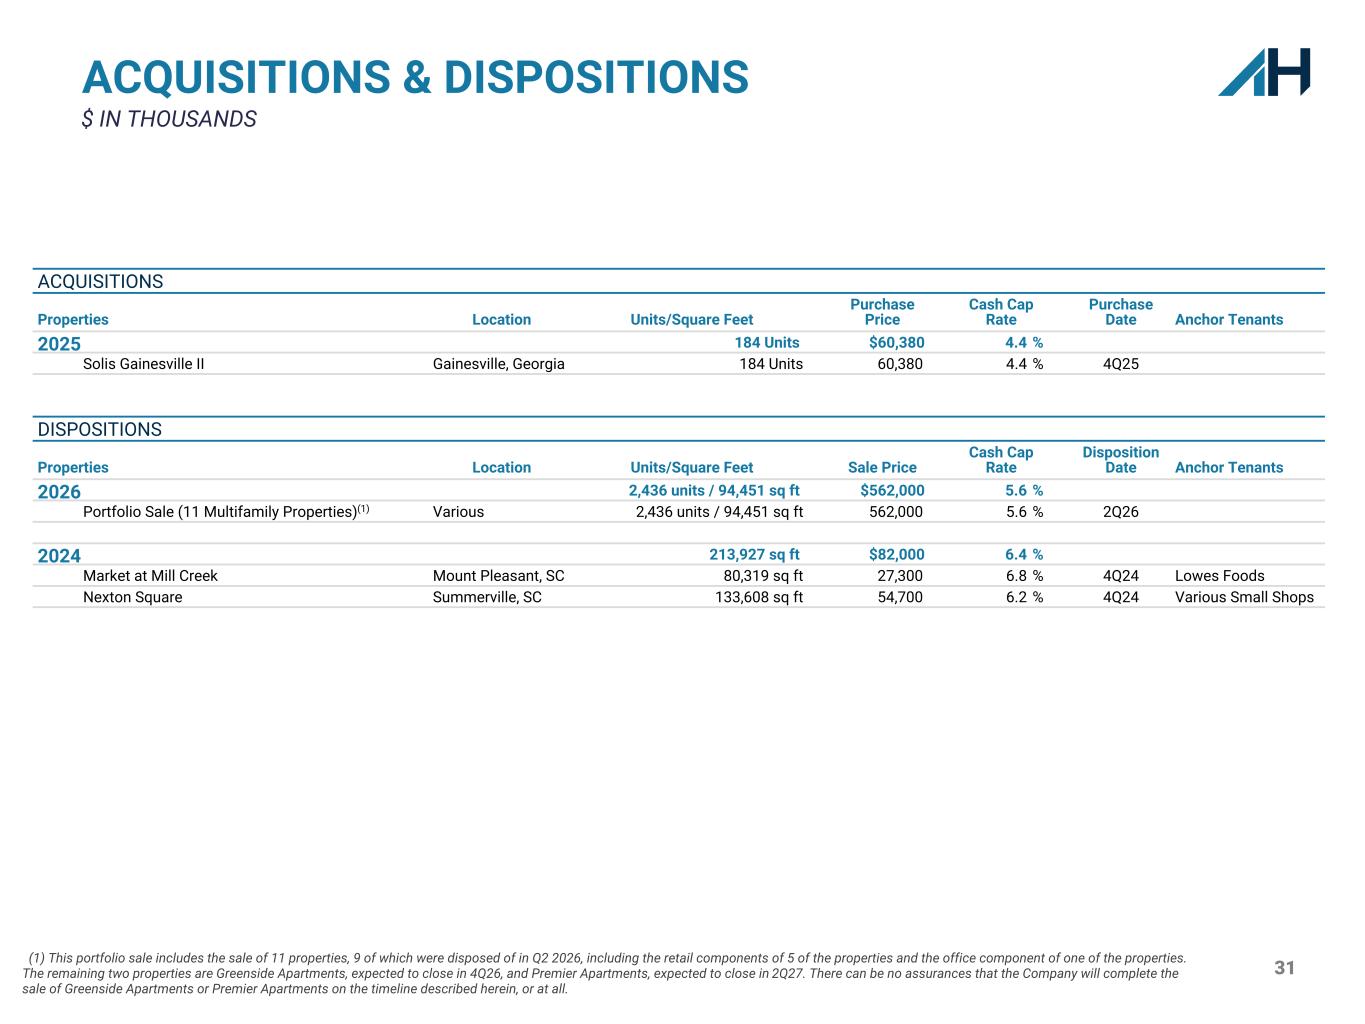
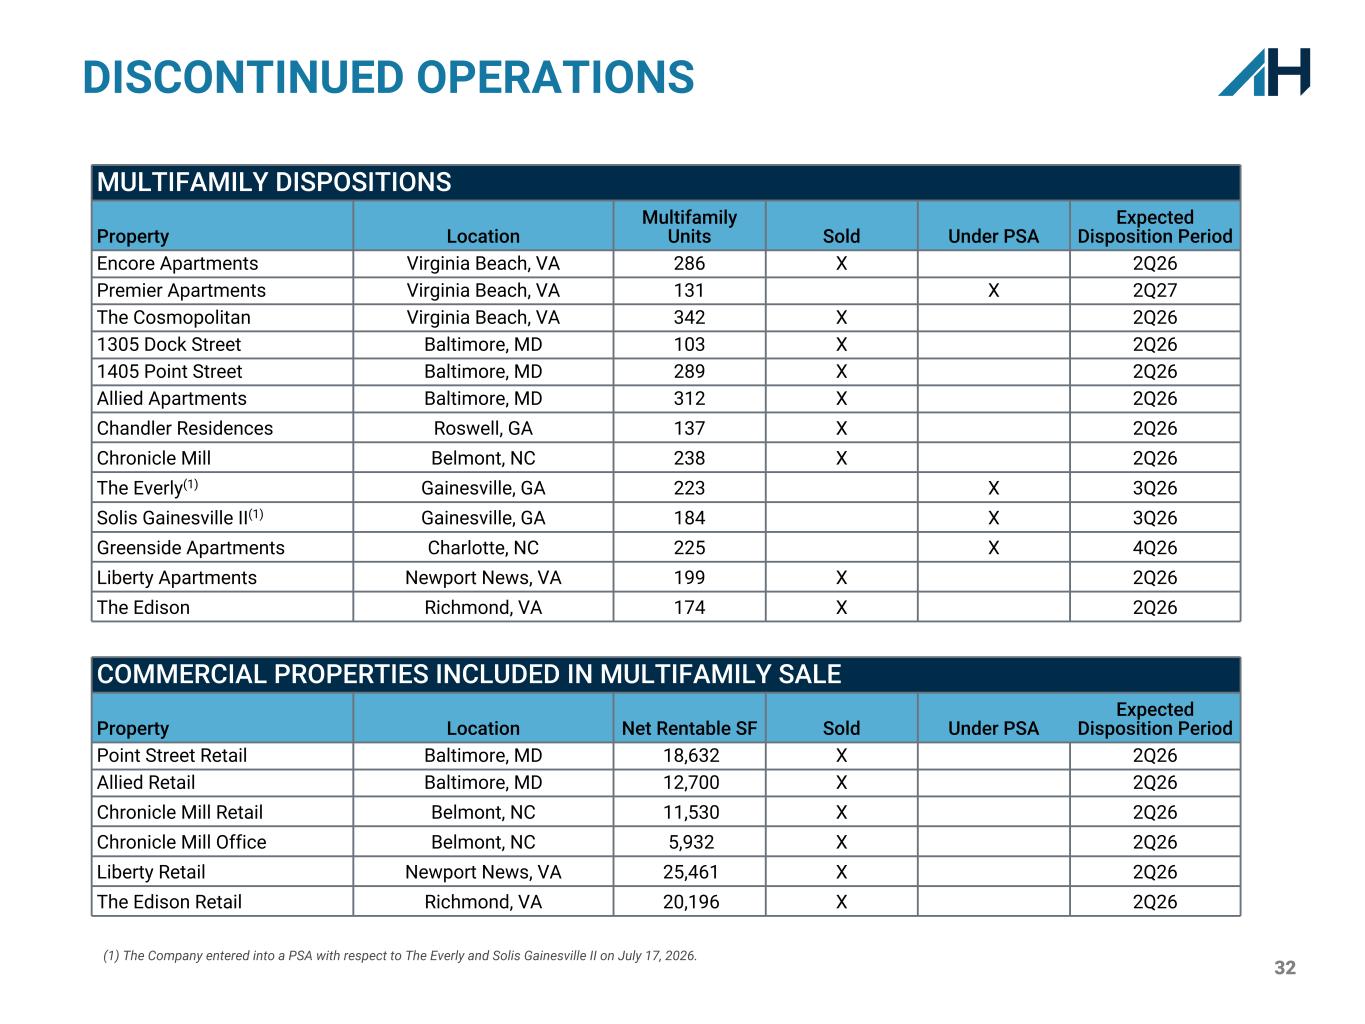
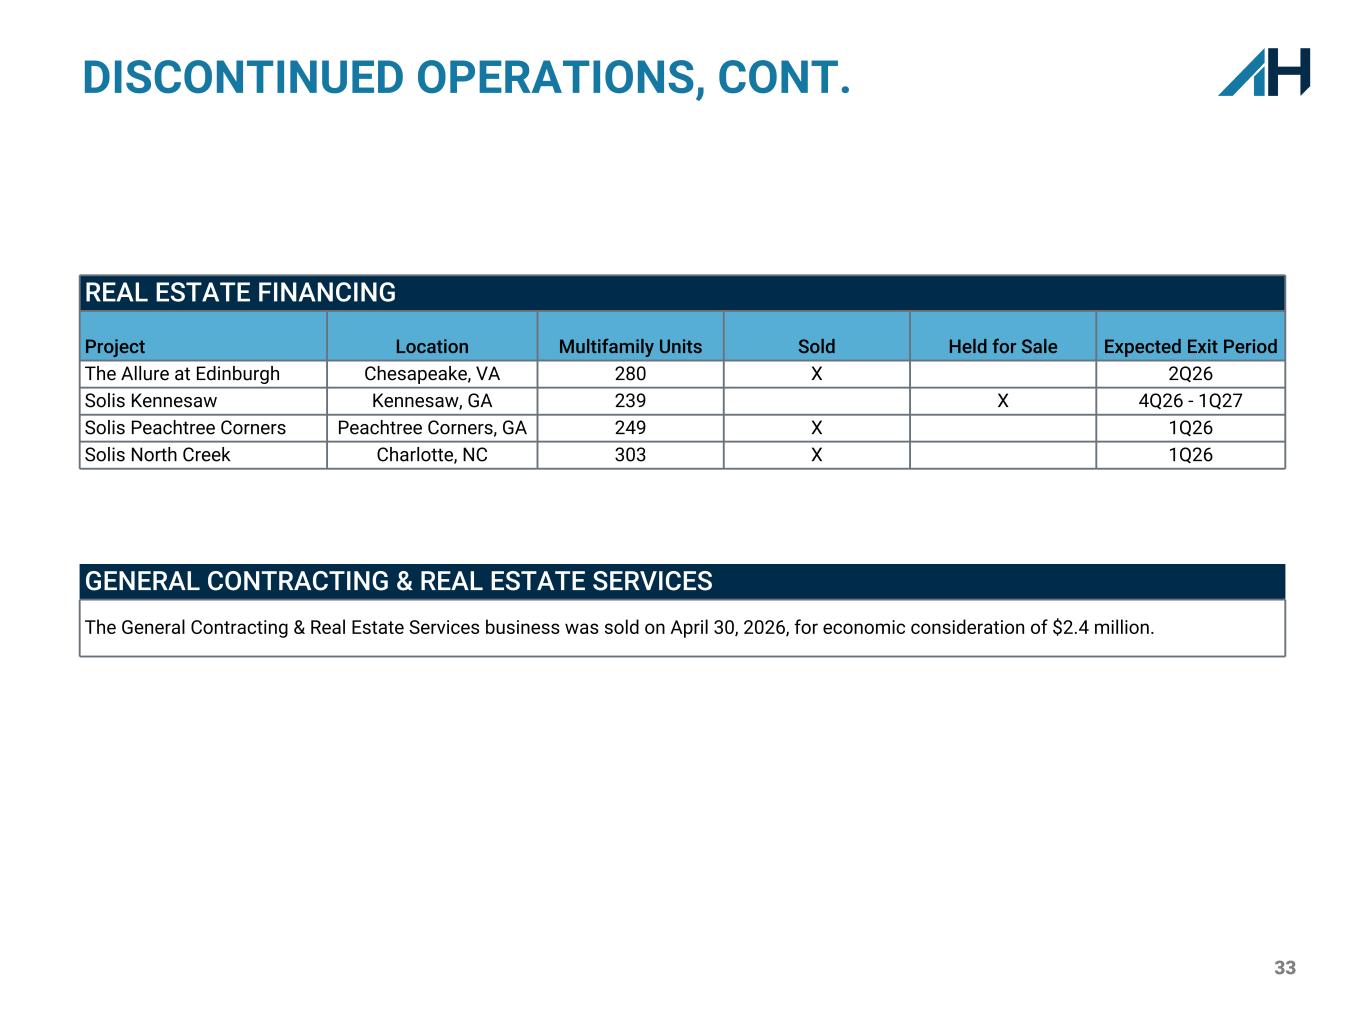
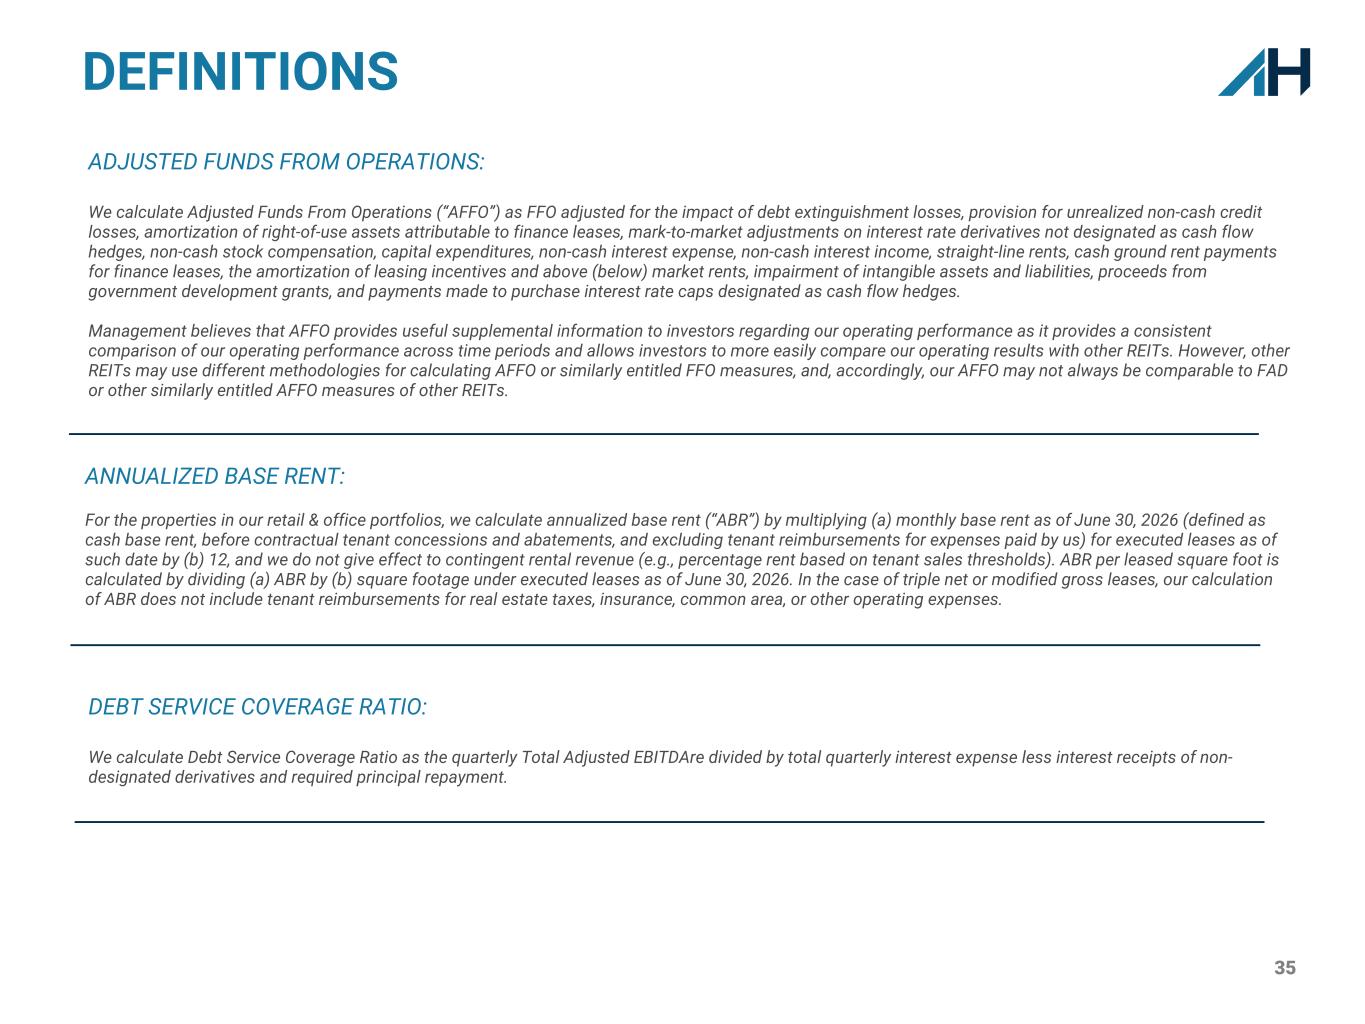
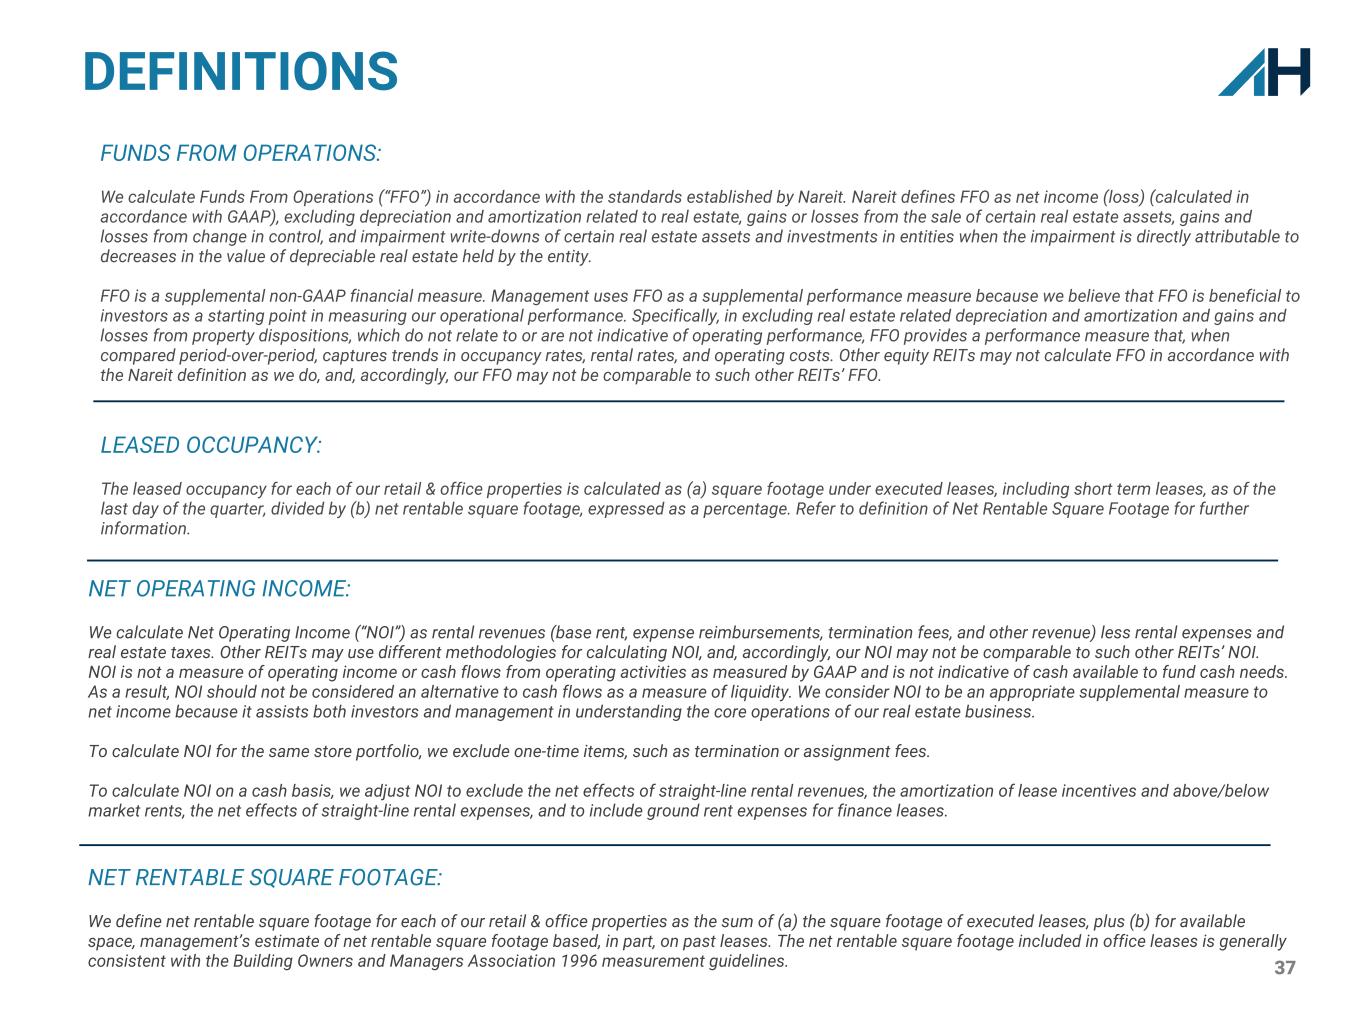
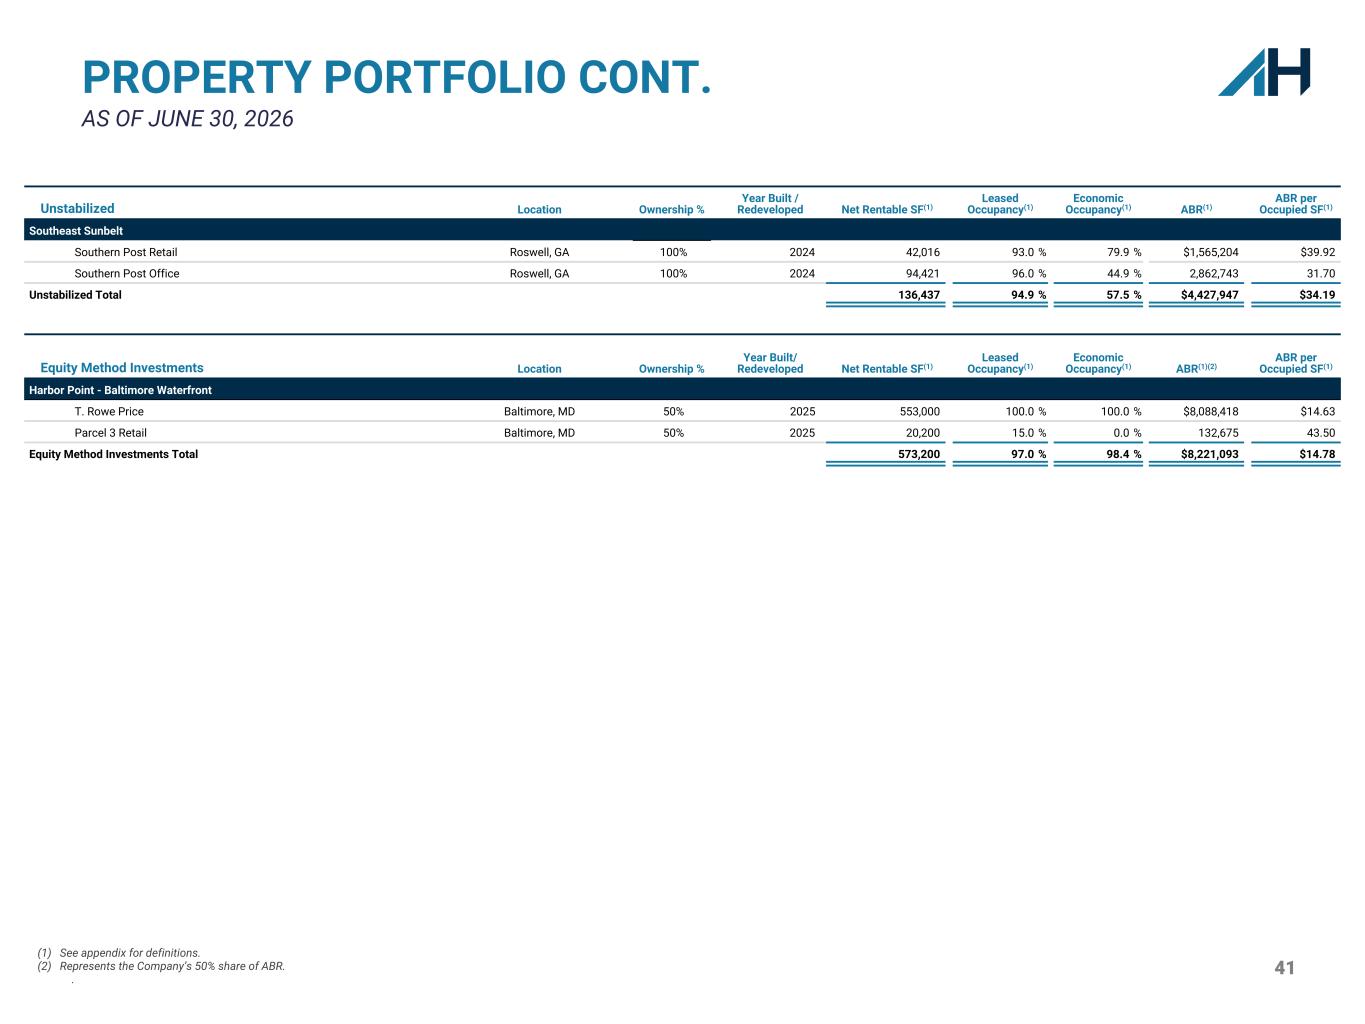
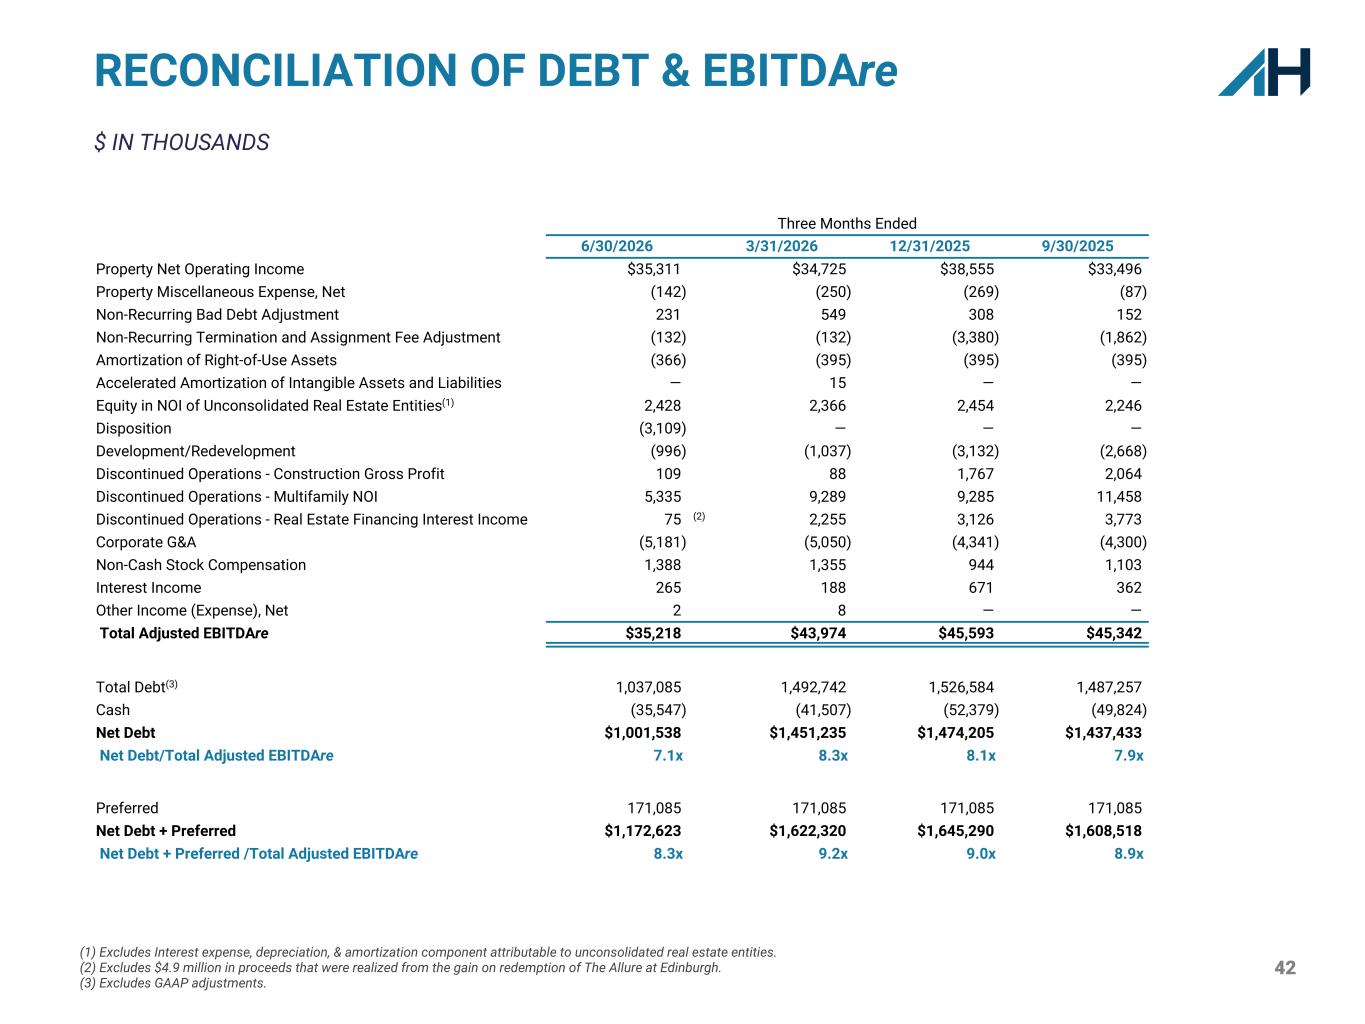
Good morning. and thank you for joining us today. Given our year-to-date results, we are raising our full year 2026 FFO as adjusted guidance range to $0.53 to $0.57 per diluted share. I will discuss where AH Realty Trust stands today, the milestones we achieved this quarter, and portfolio highlights before closing with a look at our current capital allocation strategy and outlook. Let me be direct. This has been the most consequential and productive quarter in AH Realty Trust's history. When we announced our restructuring plan just over five months ago, we made key commitments to our shareholders. Today, I am proud to report that we have delivered on every one of them, even faster than expected, resulting in significant, accelerated value creation. In recent months, we have fundamentally transformed this company. We sold nearly all of the multifamily portfolio, exited the majority of the real estate financing positions, paid down debt, executing the most significant balance sheet deleveraging in the company's history. And lastly, we exited the construction business. Today, our refresh board has new directors with the skills and experience to oversee our new company as we move forward. We did all of this while continuing to operate our retail and mixed-use office portfolio with excellence and increasing occupancy. When we announced our strategic pivot, we stated our intention to exit multifamily and real estate financing for a total gross proceeds of approximately $750 million. We have become a pure-play, high-quality retail and mixed-use office reed. We are now, in every meaningful way, that company, AH Realty Trust. In May, we completed the sale of nine of the 11 multifamily properties in our original portfolio sale agreement to affiliates of Harbor Group International for $485 million. dollars. At the strong valuations we received for these assets, which exceeded the value the market assigned them within our REACH structure, is a clear validation of our thesis that substantial embedded value existed and continues to exist in the portfolio. Greenside and Premier are under contract with HGI for an additional 77 million dollars in combined proceeds. We anticipate state closing on Greenside by year-end, 2026, and Premier by mid-2027. We have also executed a purchase and sale agreement on the Everly and Gainesville 2 for an aggregate gross sales price of $95.5 million, with the buyer's deposit now non-refundable, and we expect to close by the end of the third quarter of 2026. As committed, we intend to retain Smith's Landing, given its unique ground lease structure and stable cash flow. The proceeds from the nine asset Harbor Group sales were redeployed. Approximately $460 million went directly to debt reduction, materially reshaping our capital structure. As of quarter end, Age Realty Trust's net debt to total adjusted EBITDA stood at approximately 7.1 times, And our leverage trajectory is exactly where we said it would be. We remain on a clear path to our target leverage range of five and a half to six and a half times net debt to total adjusted EBITDA. AH Realty Trust continues to hold a triple B credit rating from Morningstar DBRS, underscoring the strength of the balance sheet we are fortifying. In the second quarter alone, we paid down $353 million of variable rate debt, further improving our debt profile. As of quarter end, our debt was 100% fixed or economically hedged. Beyond multifamily, we have fully exited the construction business and substantially wound down our real estate financing platform. The result is a company that is dramatically simpler, with far less earnings volatility, far less balance sheet complexity, and far greater focus on what we do best—owning and operating high-quality, open-air retail and mixed-use ecosystems in strong Sunbelt, Mid-Atlantic, and Southeast markets. Another defining element of our successful transformation is governance. We have made purposeful, strategic changes to the composition of our board to ensure that we have the right leadership in place for this next chapter. At our 2026 annual meeting, shareholders elected Theodore Bigman and Lori Whitman as independent directors. The skills and expertise they bring are directly relevant to our business and transformation, as well as our focus on closing the gap between AH Realty Trust's share price and its asset value. As previously announced, Dennis Gartman and George Allen completed their board service at the annual meeting, and we thank them again for their years of contribution. This board refresh reflects a deliberate and ongoing alignment of governance with strategy, and we are confident AH Realty Trust is well positioned for shareholder value creation. I want to shift gears and discuss our capital allocation framework, which is built around one principle, deploying capital where it creates the most value for shareholders. In May, our board of directors increased the total authorized repurchase capacity to $100 million, doubling the original authorization and reflecting the board's conviction in the intrinsic value of this company. Through June 30, 2026, we repurchased approximately $33.2 million for 5.6 million shares at a weighted average price of $5.92 per share. We believe this was among the most compelling uses of capital. After giving effect to the increased authorization, approximately $54.1 million remains available for future repurchases. As we work to continue closing the gap between our current share price and intrinsic value, we will continue to evaluate a range of capital allocation options, including targeted redevelopment and out-parcel development within the existing portfolio, where we see near-term accretive opportunities. We will also selectively evaluate acquisitions in our target market, but only at terms that are accretive to shareholders. We will not pursue acquisitions only for the sake of growth. Shareholder value creation is our North Star, and it is through that lens that we will continually reassess capital allocation opportunities. It is worth touching on the broader retail landscape. According to CoStar's most recent data, the sector's fundamentals are stabilizing and, in key pockets, tightening further. Net absorption rebounded to positive 9.8 million square feet in the second quarter. after a negative first quarter. Vacancy held flat and announced store openings continue to outpace closures. Available retail space remains near a multi-decade low, roughly 12 percent below the 10-year average, while new construction is still well below pre-pandemic level, keeping a lid on new supply. Grocery anchored space, which underpins our portfolio, is tighter still than the broader market, and landlords continue to capture meaningful rent gains on new leases, even as growth moderates. Investor demand for retail real estate remains strong as well, with sales volume up 26% year over year and cap rates stabilizing after peaking in 2025. We believe all of this plays directly to the strength of the portfolio we have built. Against the backdrop of executing our transformation, our retail and mixed-use office portfolio continued to perform at a high level. Greg will take you through the details shortly. A few highlights worth noting up front, our retail portfolio ended the quarter at 95.1% lease. Second quarter retail cash same-store NOI was up 2.9% year-over-year, driven by a cash renewal lease spread of 8.7%. Rent commencements from prior leasing activity and a tenant base anchored by proven high traffic national retailers. Trader Joe's at Columbus Village continues to outpace the only other nearby market location by nearly two times in visit. Golf Galaxy at Columbus Village ranks in the top three of all Golf Galaxy stores nationally. Chartway Federal Credit Union recently opened at an out parcel at Columbus Village, another example of the redevelopment and NOI enhancement opportunities we continue to execute across the portfolio. Looking ahead, we expect full-year 2026 same-store NOI growth of approximately 2.5% to 3.5%, and we expect our retail lease percentage to continue building as our sign-not-occupied pipeline commences, with the bulk of that activity weighted toward 2027. Our office portfolio ended the quarter at 96.7% leased occupancy, with economic occupancy gains continuing to build as new tenants began paying rent. Last quarter, we completed the consolidation, downsizing, and relocation of AH Realty Trust's own corporate offices, moving from the main tower at Town Center into the least desirable retail space elsewhere in the town center portfolio that has been vacant for three years. That intentional move freed up our previous space, and we recently leased 38,000 square feet at 222 Central Park at top of market rent, creating $1.3 million of new ABR. It's an example of the same discipline running through this entire transformation. We lowered our own occupancy costs and, in turn, are capturing premium rent on the space we vacated. Second quarter office same-store NOI was up 8.3 percent year-over-year with a cash renewal lease spread of 21.6 percent. We expect full-year 2026 office same-store NOI growth of approximately 2.75 percent to 3.75 percent. These metrics reflect the quality and differentiation of our mixed-use platform. Elsewhere in the office portfolio, Southern Post ended the quarter at 96 percent lease with 44.9 percent economic occupancy, and we expect that gap to narrow as free rent periods burn off. We expect office economic occupancy to continue to build as 222 Central Park and other recently signed leases begin paying rent, representing a share of the 4.6 million of signed not occupied ABR across our office portfolio, more than half of which we expect to realize this year. One point worth underscoring, 95% of our office square footage sits inside walkable, amenity-driven, mixed-use environments. We do not own standalone suburban office assets. That distinction is what drives leasing momentum and tenant demand you're seeing in our numbers, and it's why we believe the valuation gap between our office platform and the broader publicly traded office sector, should continue to close. Our tenant roster backs that up. Morgan Stanley, T. Rowe Price, EY, KPMG, and Constellation Energy anchor our largest office assets. Our office leases carry a weighted average term of seven and a half years, giving us strong visibility into future cash flow. And the traffic data tells the same story. The interlock in Atlanta, Georgia alone grew roughly 820,000 visits last year, with an average dwell time approaching three hours, and a community with an average walk score of 90. Given the continued strength of our retail and mixed-use office portfolio, the transformational actions we've completed, and our visibility into the coming quarters, we are raising our full year 2026 FFO as adjusted guidance range to 53 cents to 57 cents per diluted share. For the second quarter, FFO as adjusted was 14 cents per diluted share, reflecting both the outperformance of our operating portfolio and the impact of our share repurchase program. AFFO for the quarter was 18 cents per diluted share. Our dividend is comfortably covered with an AFFO payout ratio of approximately 77%. Every action we've taken this year points to the same outcome, a simpler, more focused AH Realty Trust with a strong balance sheet, durable earnings, and a clear path to delivering outsized returns for our shareholders. We have more work to do, but we're further along and faster than we expected. That is a direct reflection of the team's talent, discipline, and results. I want to acknowledge our people executing a transformation of this scale, including over $565 million in executed transactions, with all remaining assets under contract, one real estate financing position remaining to exit, a complete business model repositioning, a balance sheet overhaul, while maintaining sector-leading portfolio performance in under two fiscal quarters is extraordinary. It requires people who operate with urgency, precision, and an ownership mentality.
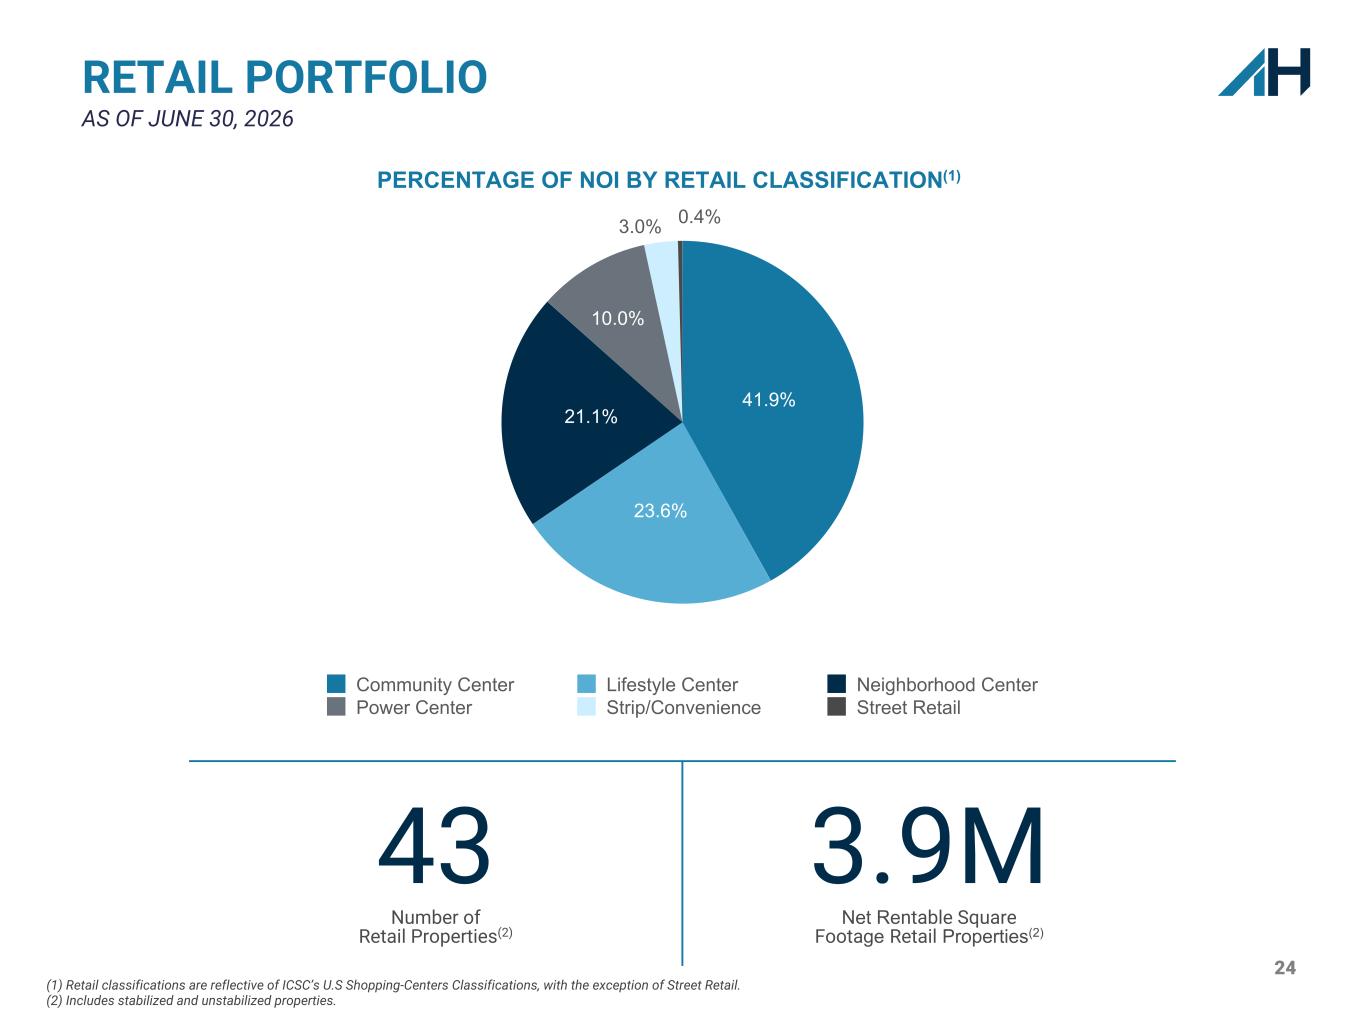
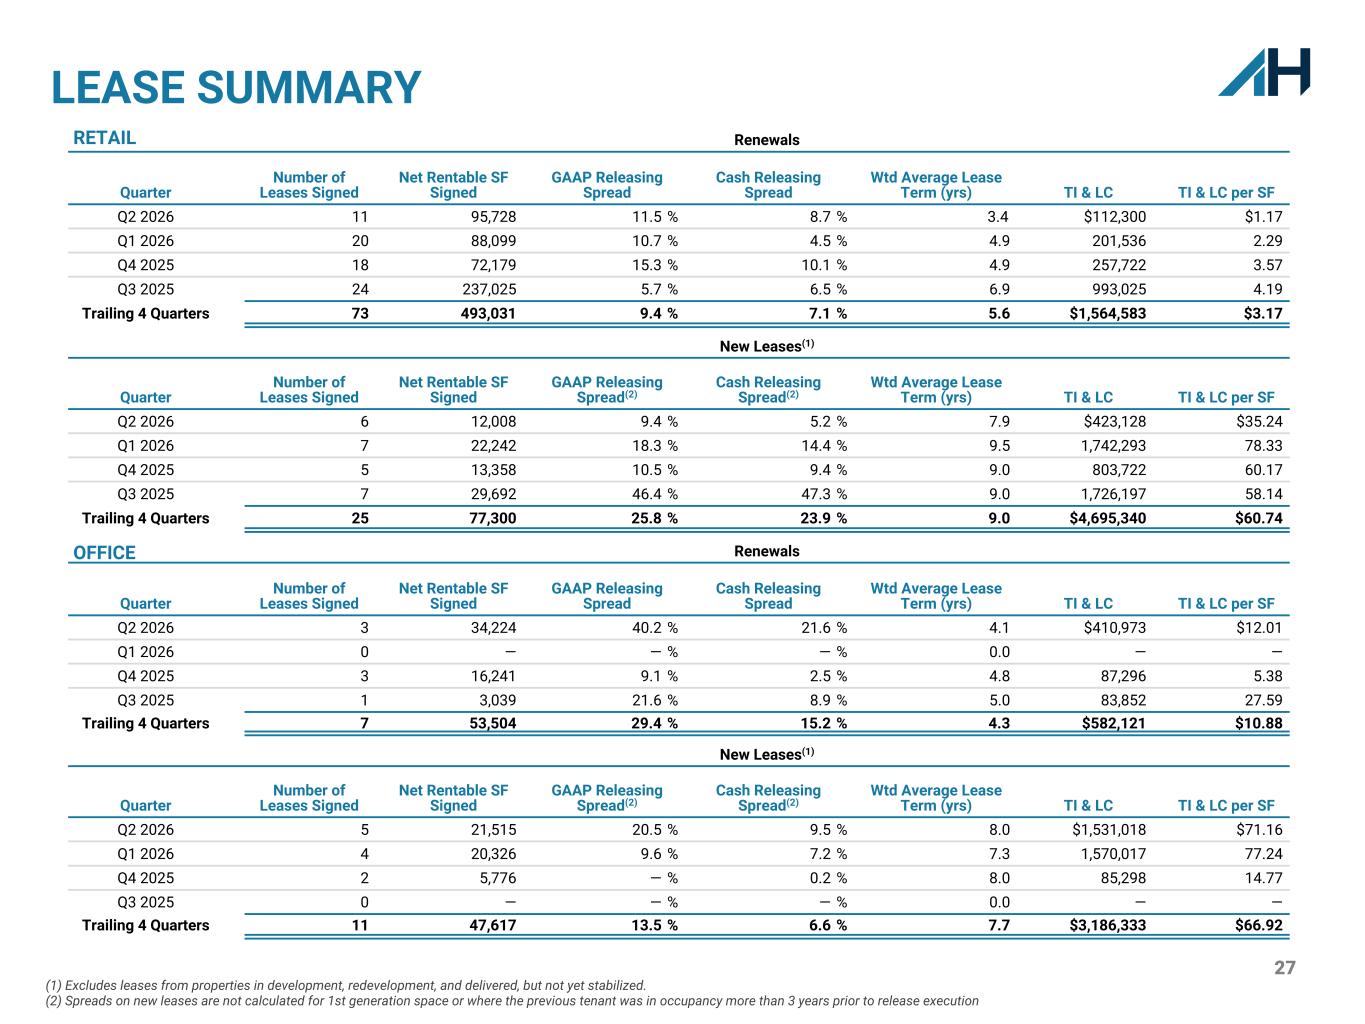
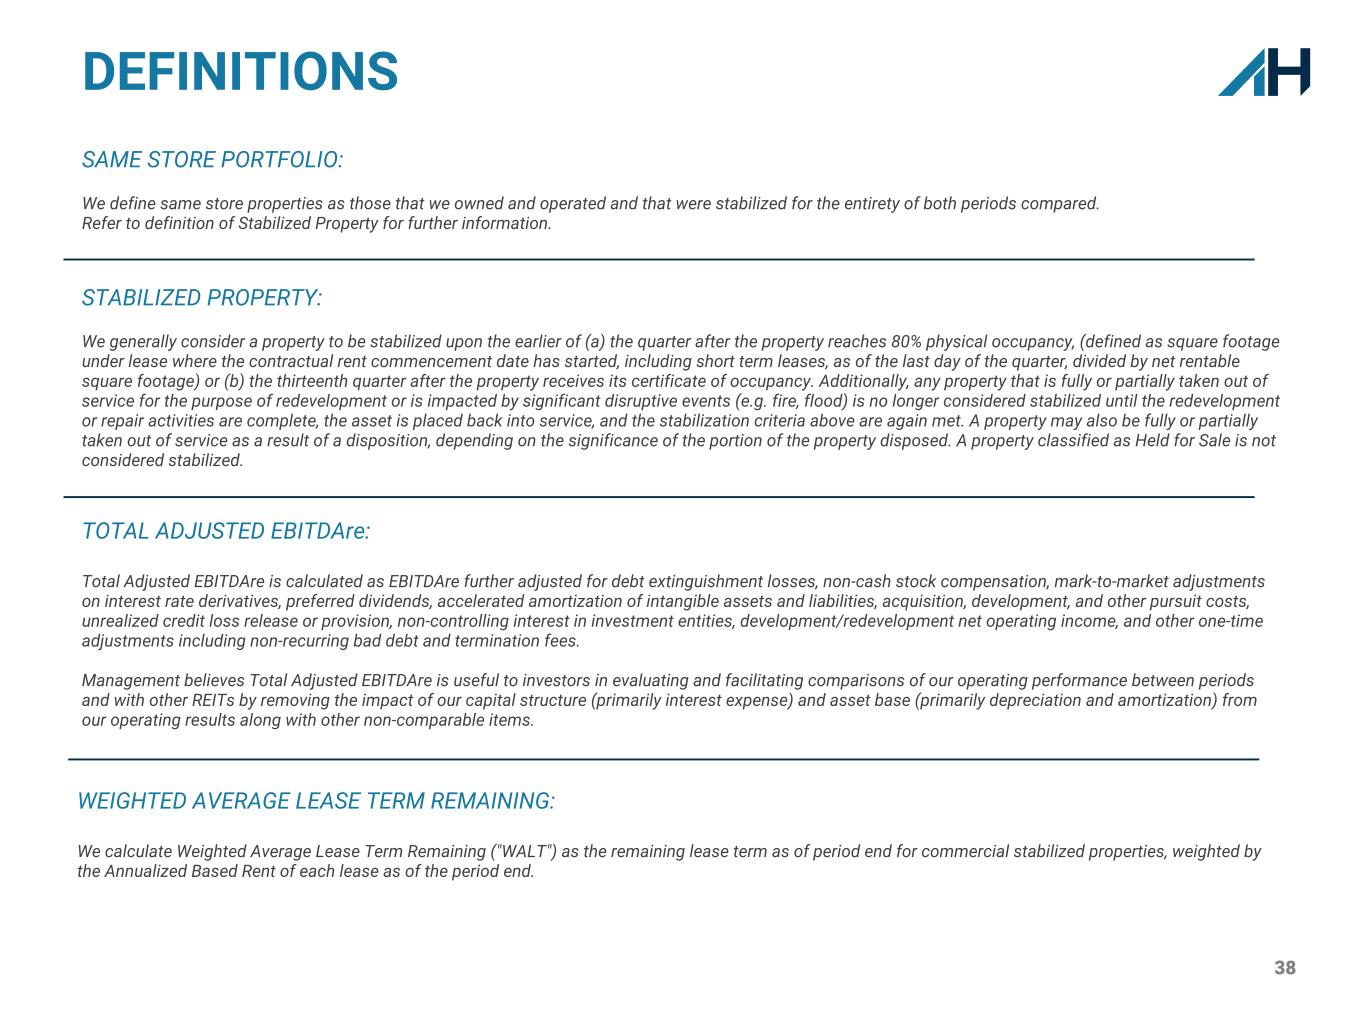
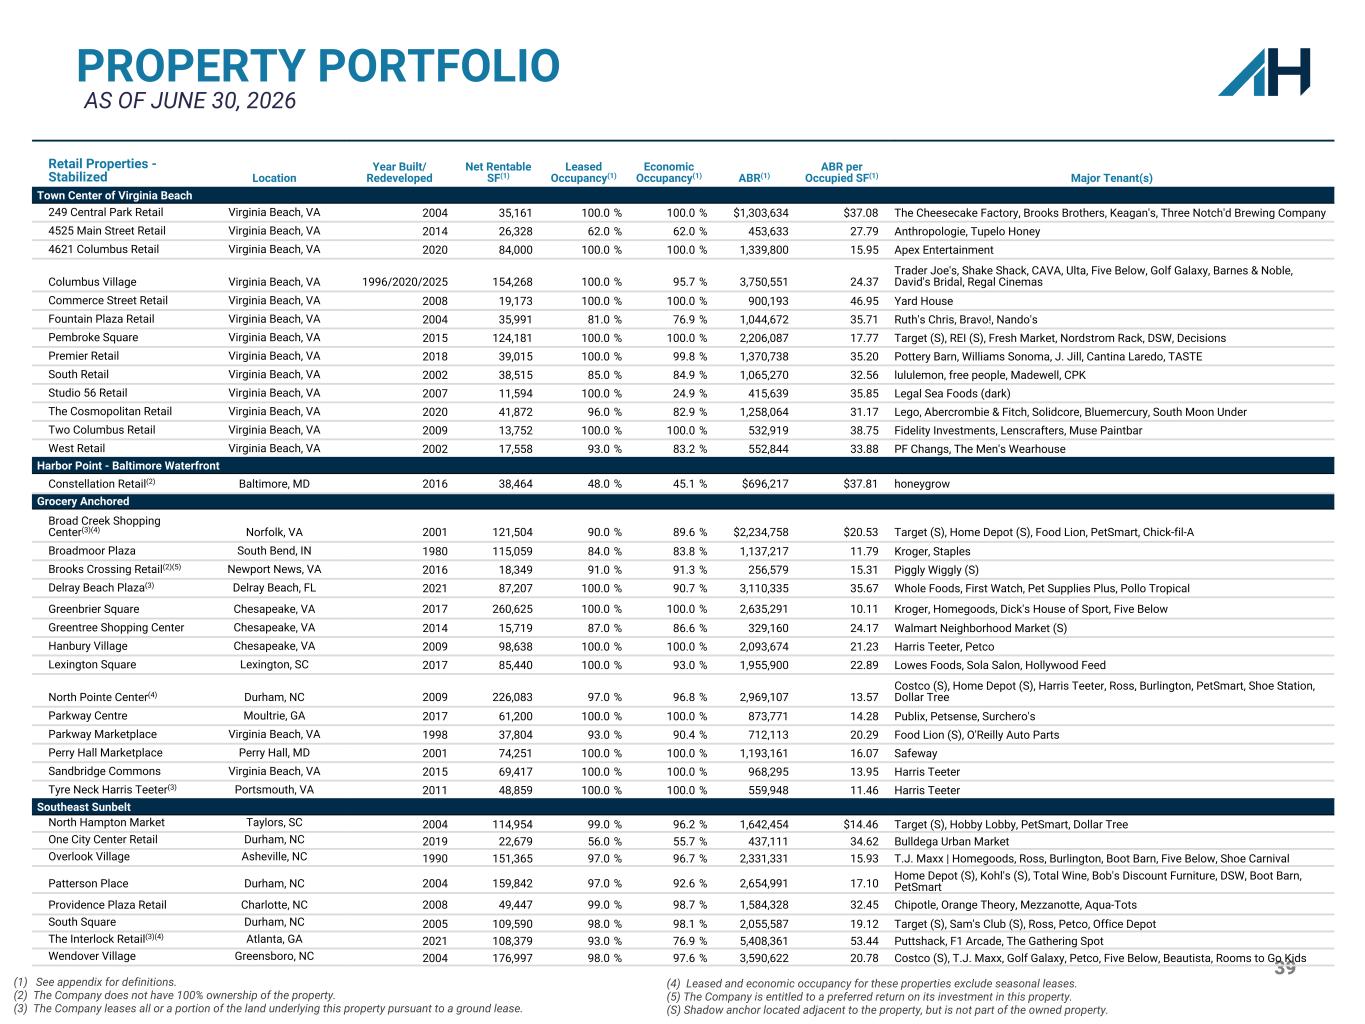
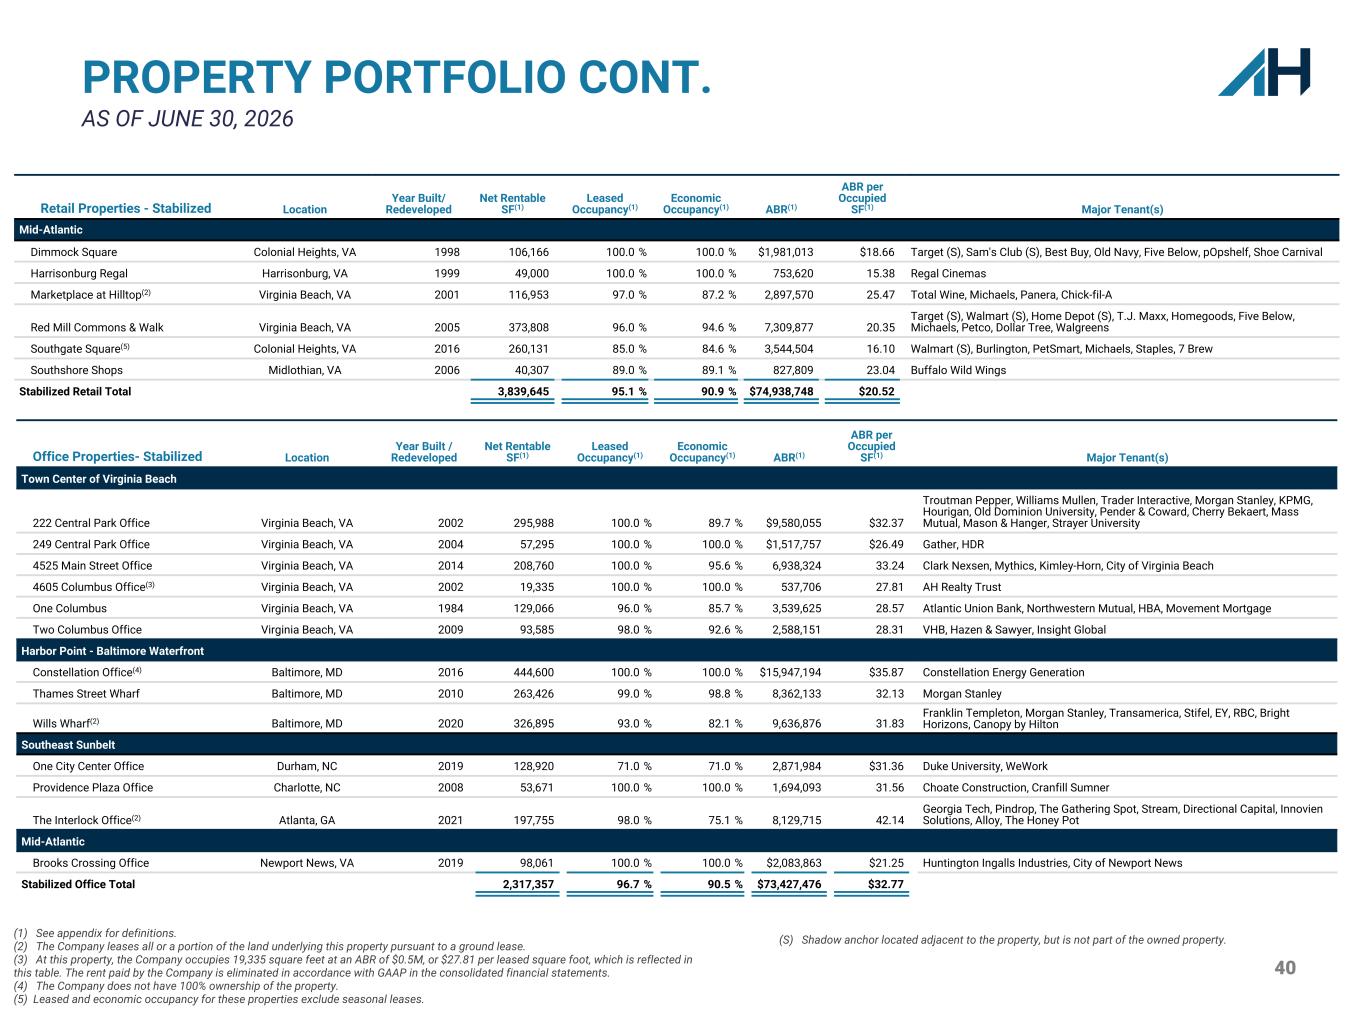
We have that team, and I could not be more proud of what they have accomplished with that i'll turn it over to craig to discuss portfolio highlights in detail thank you sean and good morning everyone i'll briefly cover second quarter operating performance as well as expectations for the portfolio for the remainder of the year with portfolio noi split between retail and office i'll spend a few minutes covering both segments starting with retail approximately 75 percent of retail noi comes from open-air shopping centers with traffic driving anchors like Whole Foods, Trader Joe's, Publix, Kroger, TJX, and Ross, or shadow anchors like Costco, Target, and Walmart. The remaining 25% of retail NOI comes from mixed use ecosystems with ground level retail integrated with office, residential, hospitality, or public space components like we have in the Town Center of Virginia Beach and the interlock in West Midtown, Atlanta. Retail same-store NOI for the quarter was up 2.9%, driven by economic occupancy gains across the shopping center portfolio and at the interlock, which more than offset anticipated vacancy and bad death at town center. Same-store NOI from the shopping center portfolio increased 5.7% year-over-year, driven by economic occupancy from the backfill over 120 000 square feet of anchor space and a combined 35 positive cash spread anchor spaces previously leased to bed bath and beyond party city and joanne are now occupied by burlington boot barn bob's this town furniture golf galaxy and trader joe's successful anchor tenants drive traffic to our shopping centers supporting sales for small shop tenants thereby driving overall rent growth. I'll highlight two specific examples. With the opening of Trader Joe's and Gulf Galaxy, year-to-date visits to the redeveloped Columbus Village grew more than six folds compared to last year. An inline shop and out parcel rents have doubled. At Southgate Square, the backfill restaurant tenant for the Joanne Anchor Space opened for business earlier this year, And late last year, we leased a previously undeveloped area of the parking lot to Seven Brew Coffee. A prime example of our team's ability to find ways to incrementally increase NOI and create value. As a result, year-to-date visits to Southgate Square have increased 54% compared to last year. Second quarter renewal spreads on inline shop space at Southgate Square were 33% positive and we're currently at least with a leading national fast casual restaurant for space at a 55% positive cash spread. Shopping center portfolio visits during the second quarter increased 6.6% year over year and are up over 11% compared to the second quarter of 2019. Anchor space vacancy in the shopping center portfolio is down to just 3%. And while we negotiate terms with long-term backfill tenants, we intend to monetize the available space for temporary short-term seasonal uses to incrementally bolster third and fourth quarter retail NOI. At the end of the second quarter, small shop vacancy in the shopping center portfolio stands at around 8 percent, presenting growth opportunities as we intend to capitalize on the success of anchor tenants, increase in foot traffic, and demand for retail space in a supply-constrained environment. As I mentioned last quarter, we expected town center retail to weigh on current year same store NOI due to vacancy and store closures on 30,000 square feet of space. however i'm pleased to report that 5 000 square feet has already been released to abercrombie and fitch with an anticipated store opening this fall we look forward to abercrombie joining town center's best in market retail lineup that includes lululemon lego anthropology madewell free people williams sonoma and pottery mars the remaining retail vacancy and town center presents tremendous opportunity to thoughtfully curate the overall merchandising mix to best serve all of town center's residents and visitors from the daytime weekday office population to nighttime and weekend guests in order to increase visits prolonged dwell time and create an environment that supports rent growth at the interlock in west midtown atlanta retail NOI increased 32% year-over-year, reflecting full economic occupancy of the rooftop space that was released at a 64% positive cash spread. Second quarter visits to the interlock increased 33% year-over-year, and parking transactions are up 36%, driven primarily by the success of the new rooftop operator, World Cup events and activations, and the opening of Atlanta's first F1 Arcade. We expect further cash NOI gains from the interlock during the remainder of the year with anticipated rent commencement from F1 Arcade in the third quarter. Portfolio-wide, second quarter cash spreads on new retail leases and renewals were positive 5.2 percent and 8.7 percent. At the end of the second quarter, the retail portfolio was 95 percent leased with just under 91 percent economic occupancy sign not occupied abr was 1.8 million dollars the majority of which we expect to realize in 2027 year to date retail same star noi increased 2.5 percent over last year looking ahead to the second half of the year we expect consistent noi contribution from the shopping center portfolio with accelerating growth from the interlock more than offsetting sustained declines at Town Center, all of which has been reflected in our revised Same-Store guidance range for 2026. Turning to the office segment, Office Same-Store NOI was up 8% for the quarter, driven by significant cash NOI increases at Harper Point in Baltimore, Town Center, and the Interlox. Harper Point accounted for over 55% of Office Same-Store NOI, with Townsend are contributing roughly 25% in the interlock, about 8%. Second quarter office NOI at Harbor Point increased over 10% driven by economic occupancy gains at Thames Street Wharf, resulting from free rent burn-off on Morgan Stanley's expanded premises, accounting for the sequential increase in economic occupancy to nearly 99%. Looking ahead, economic occupancy and cash NOI at Thames Street Wharf is expected to reflect contractual future free rent periods in the third quarter of 2026 and the first quarter of 2027 with full economic occupancy in the fourth quarter of 2026 the second quarter of 2027 and thereafter at wills wharf we expect third quarter leased occupancy to increase approximately 275 basis points after releasing the 9 000 square feet recaptured at the end of last year town center office noi increased two and a half percent driven primarily by contractual rent increases at the end of the second quarter town center office space was over 99 percent leased given the limited supply and sustained market demand leasing spreads on town center office space for positive 9.5% on new leases and 13.6% on renewals. As expected, during the second quarter, we successfully released the 8,000 square feet recaptured at 4525 Main and over half of the 12,000 square feet that expired at 1 Columbus. Looking ahead, we expect the gap between leased and economic occupancy of town centers to tighten in the third quarter, as rent commences on signed leases at 1 Columbus, to Columbus, and the top floor of 222 Central Park, which we vacated in order to release as the highest office rent in the market. Second quarter office NOI at the interlock increased 23%, driven by rent commencements and free rent burn-off, resulting in a sequential increase in economic occupancy of 430 basis We expect further economic occupancy increases in the fourth quarter, coinciding with anticipated future recommencements on signed leases. At one city center in Durham, we anticipate both leased and economic occupancy to decline to around 65 percent in the third quarter because of lease expiration, but we remain optimistic given the quality of our asset and position in the market. Portfolio-wide cash spreads on office renewals were positive 22 percent, including a 32 percent positive cash spread at Providence Plaza in Charlotte, indicating the significant mark-to-market rent potential in that asset. Office lease occupancy at the end of the second quarter was 97%, and economic occupancy was 90%. Sign-on-occupied ABR was $4.6 million, over half of which we expect to begin realizing this year, and the rest throughout 2027. Year-to-date, office same-story NOI increased 4.5% over last year. Looking ahead to the second half of the year, we expect accelerating growth from the Interlochen Town Center to partially offset moderating growth from Harbor Point, all of which has been reflected in our revised same-store guidance range for 2026. We continue to see organic growth opportunity across both our retail and office portfolios through our sign-on-occupied pipeline, proactive leasing of vacant or soon-to-be-vacant space, marked market adjustments on new leases, positive renewal spreads, disciplined expense management, and targeted redevelopment and capital investment where returns justify it. This operational focus is central to how we intend to drive consistent NOI growth and deliver long-term value going forward. With that, I'll turn it over to Matt for more details on our second quarter financial results and an update to our fiscal year 2026 guidance.
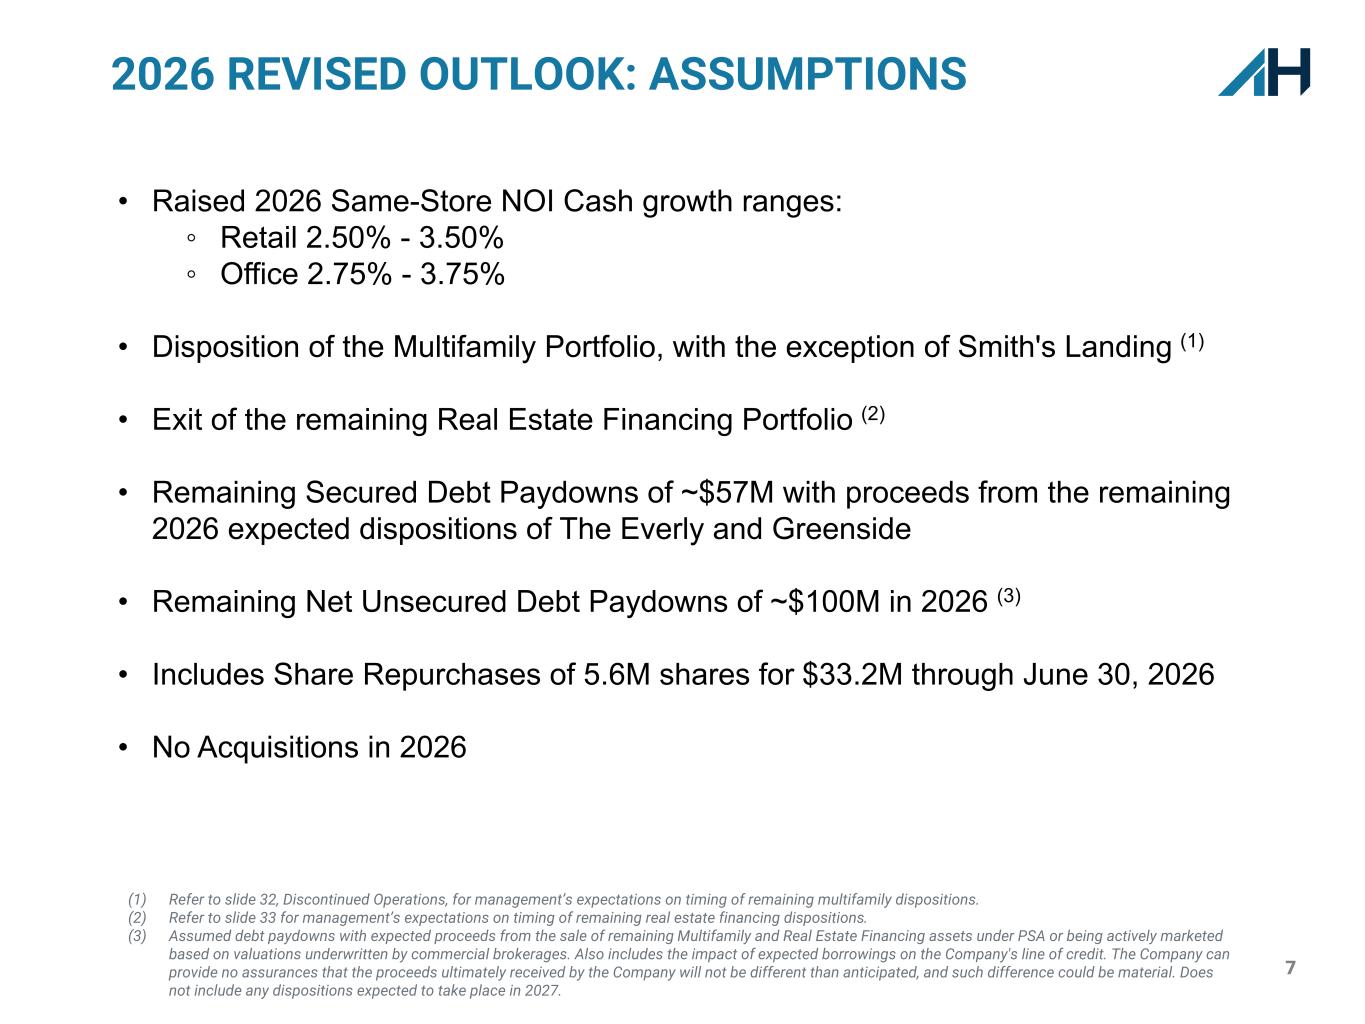
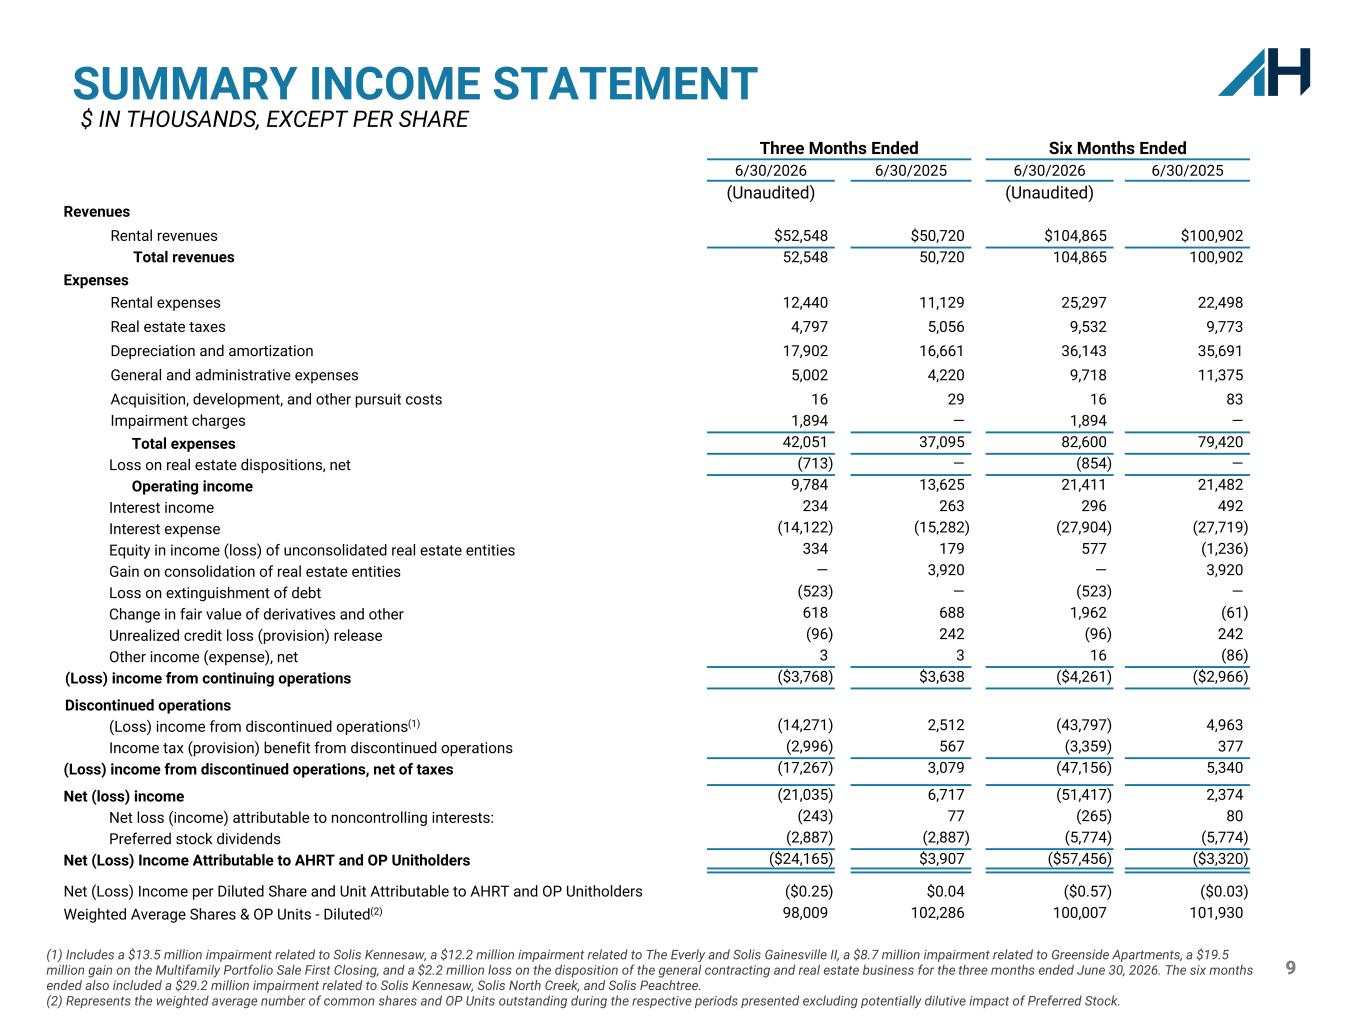
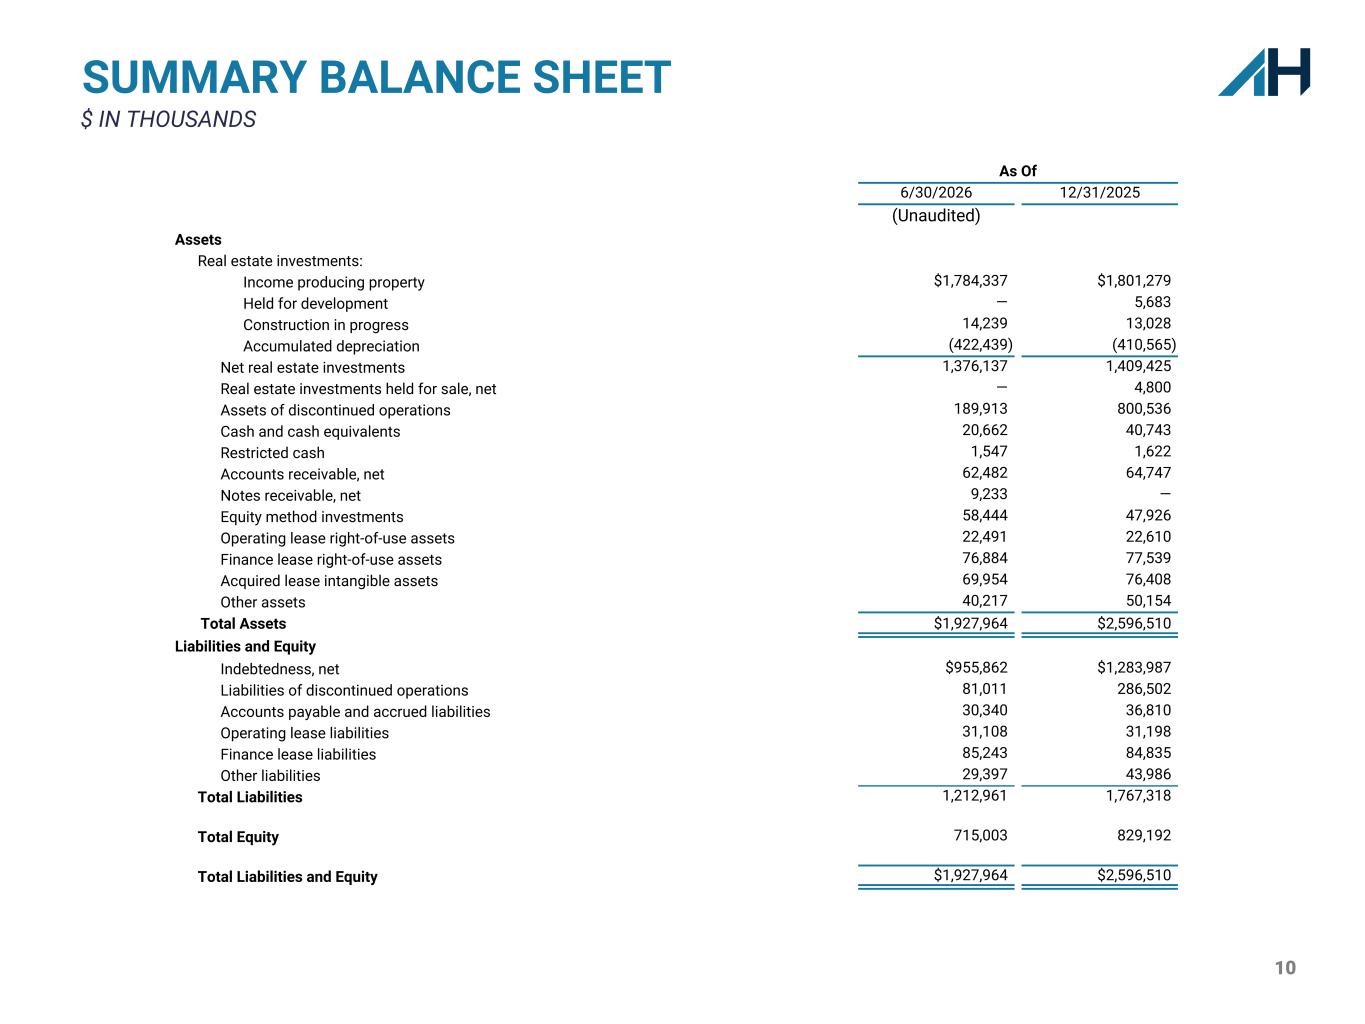
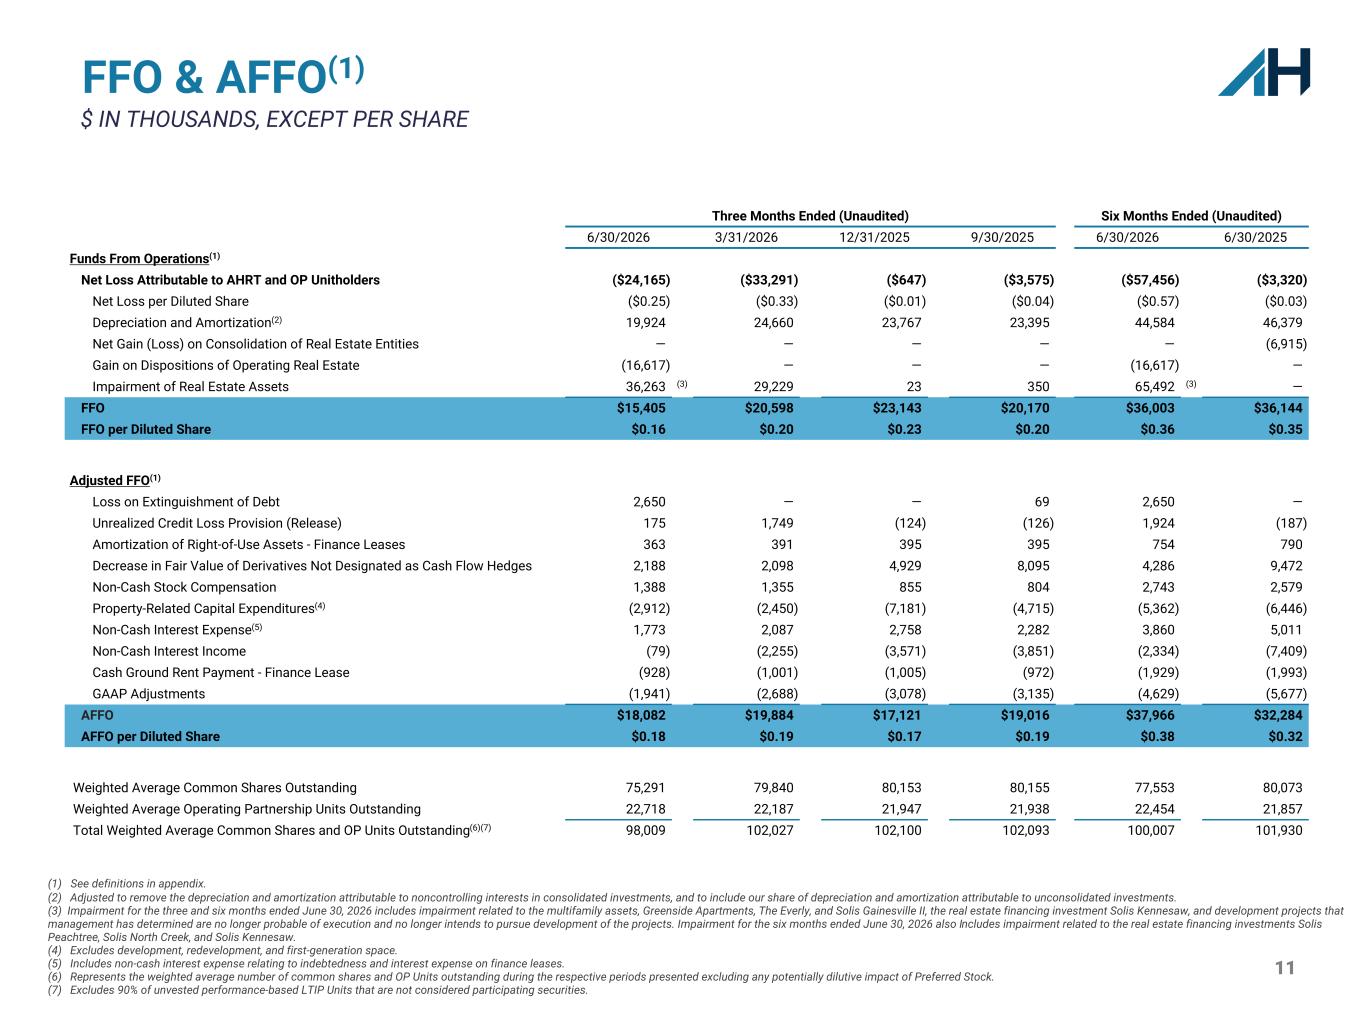
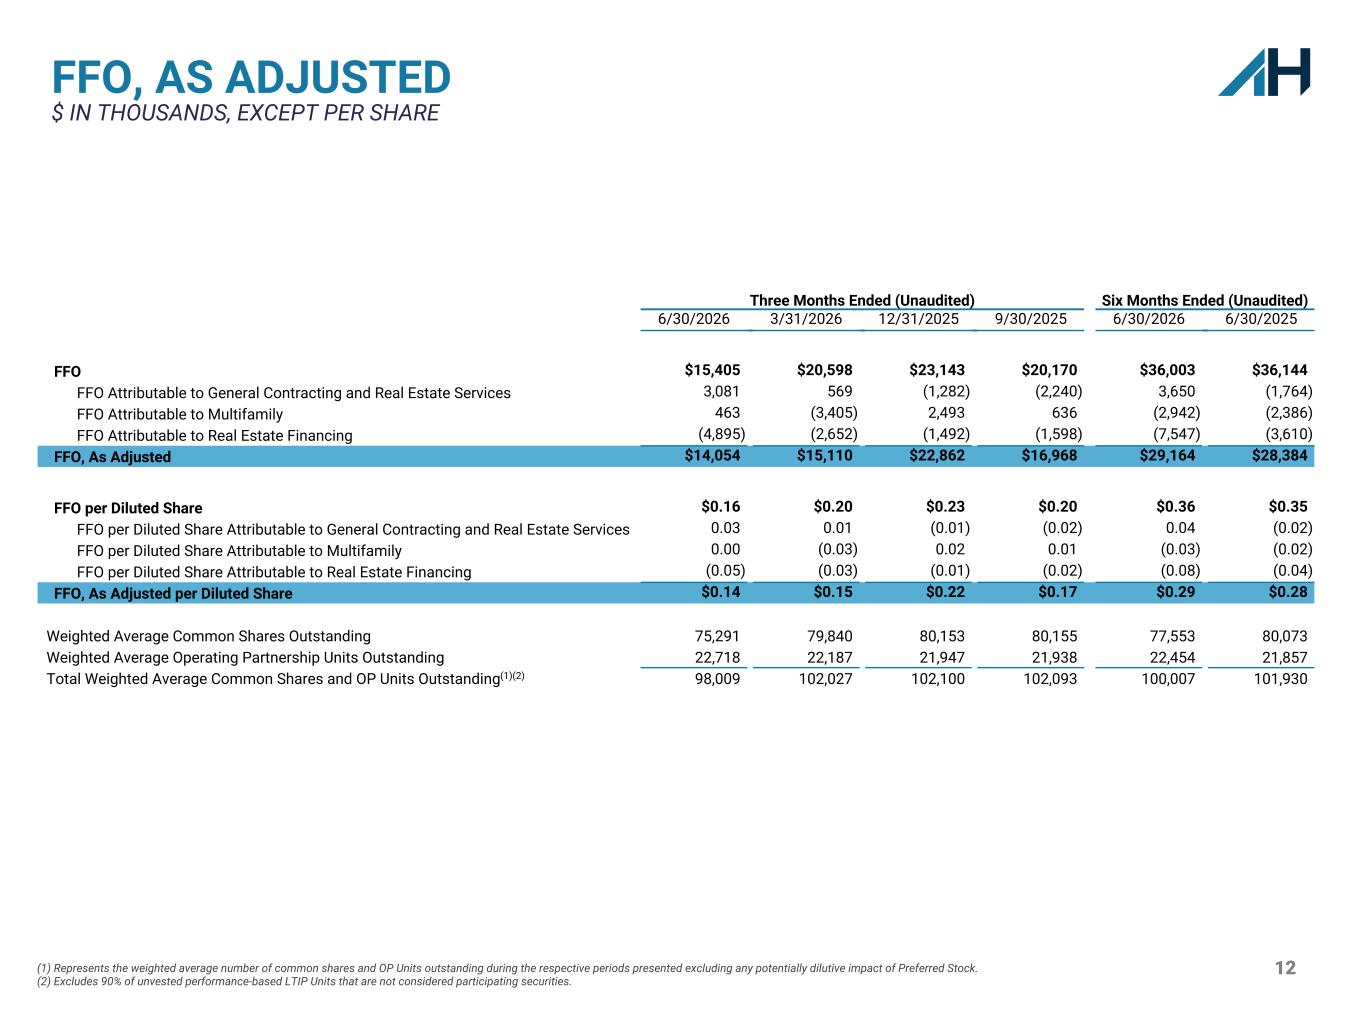
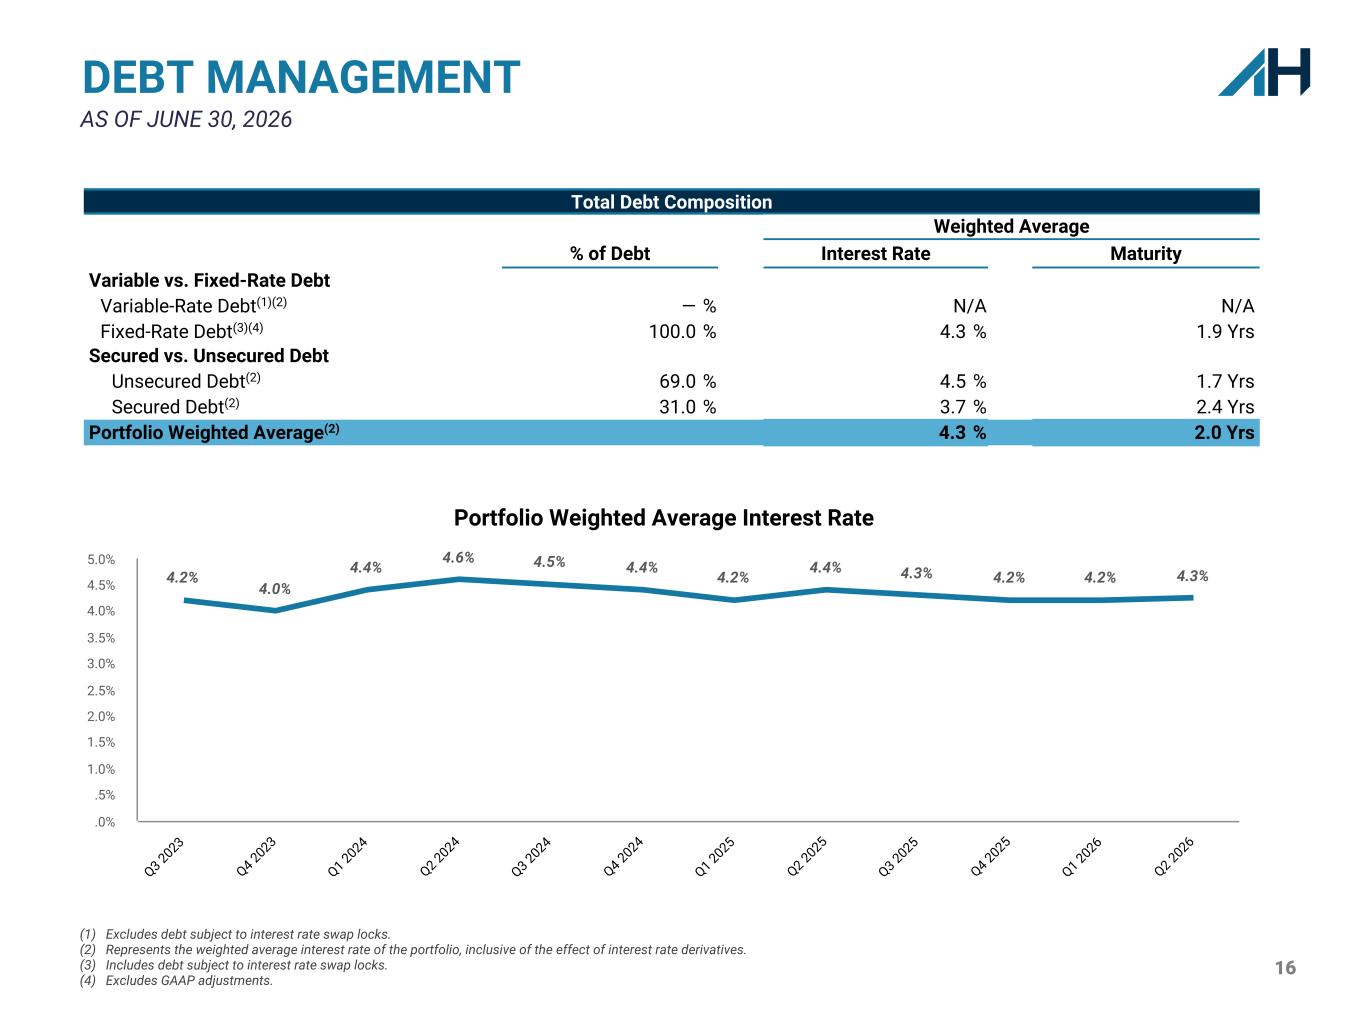
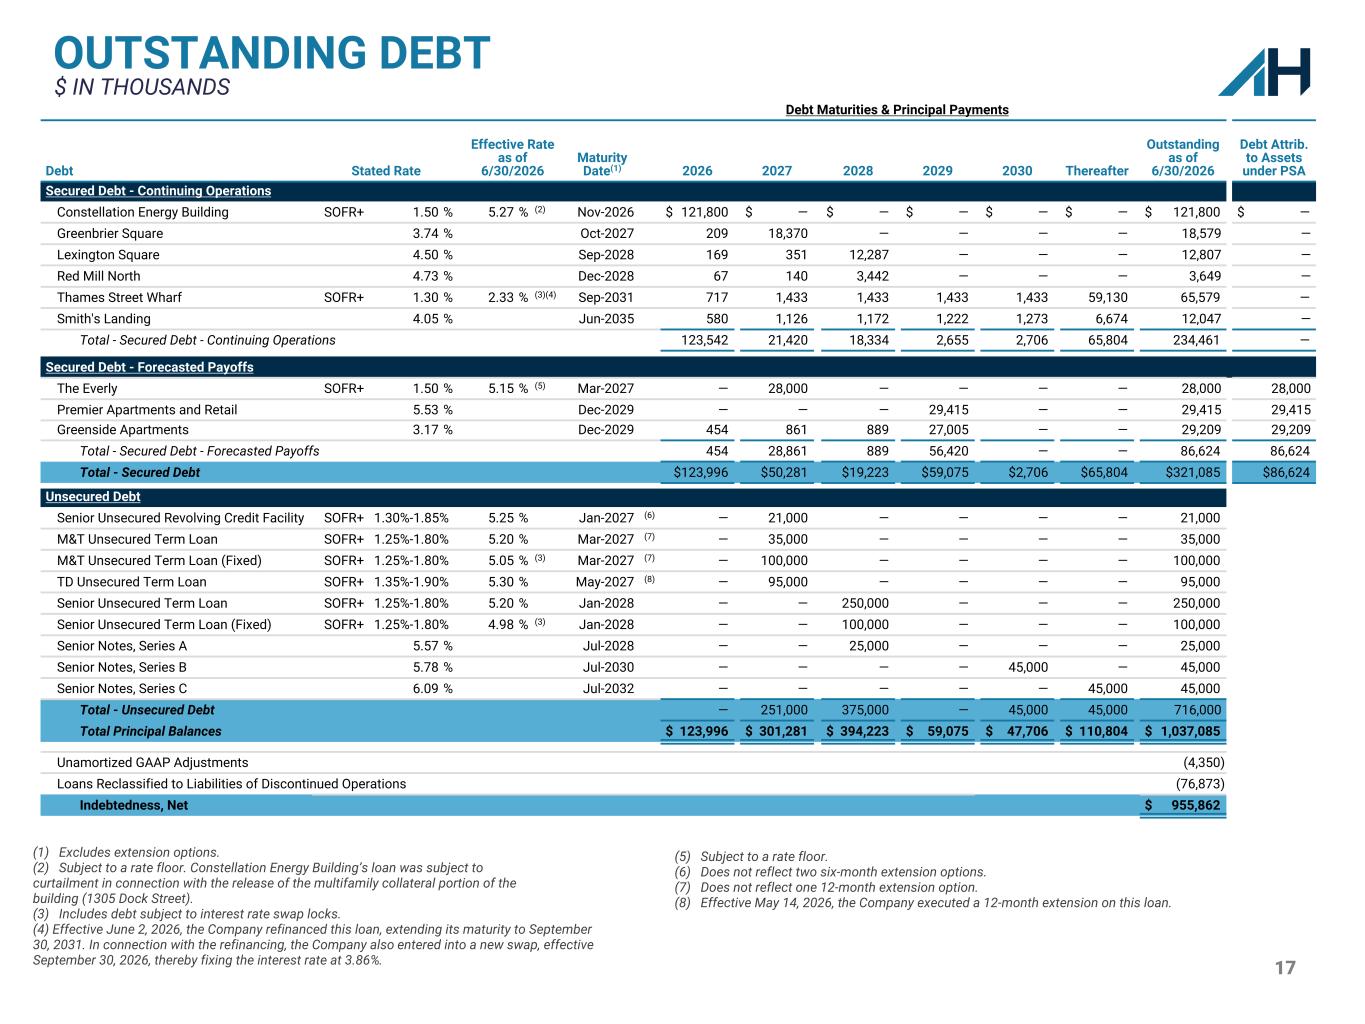
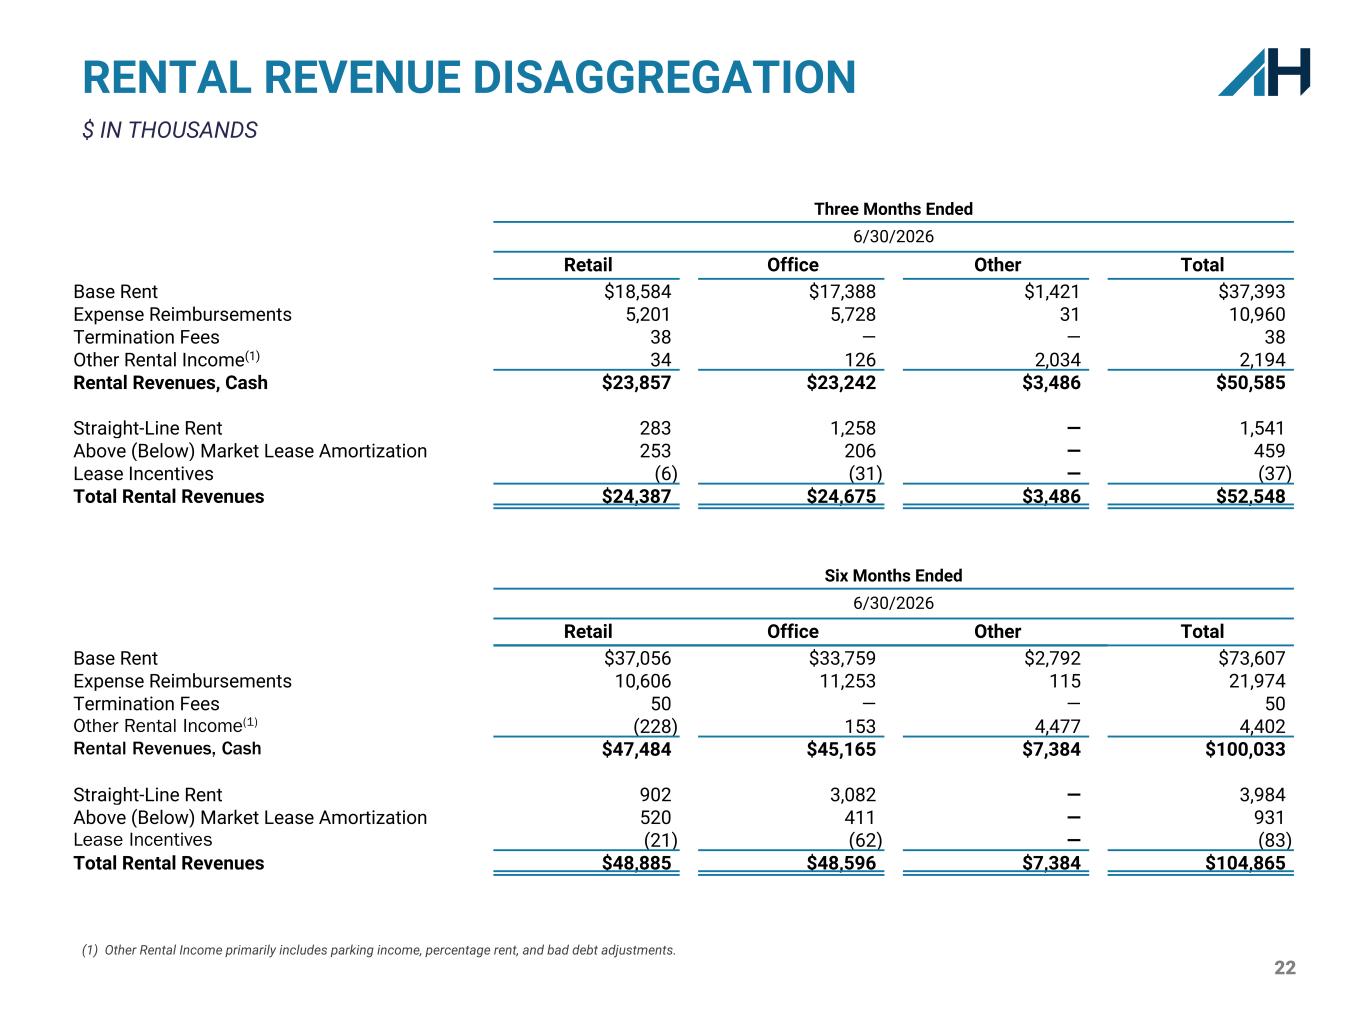
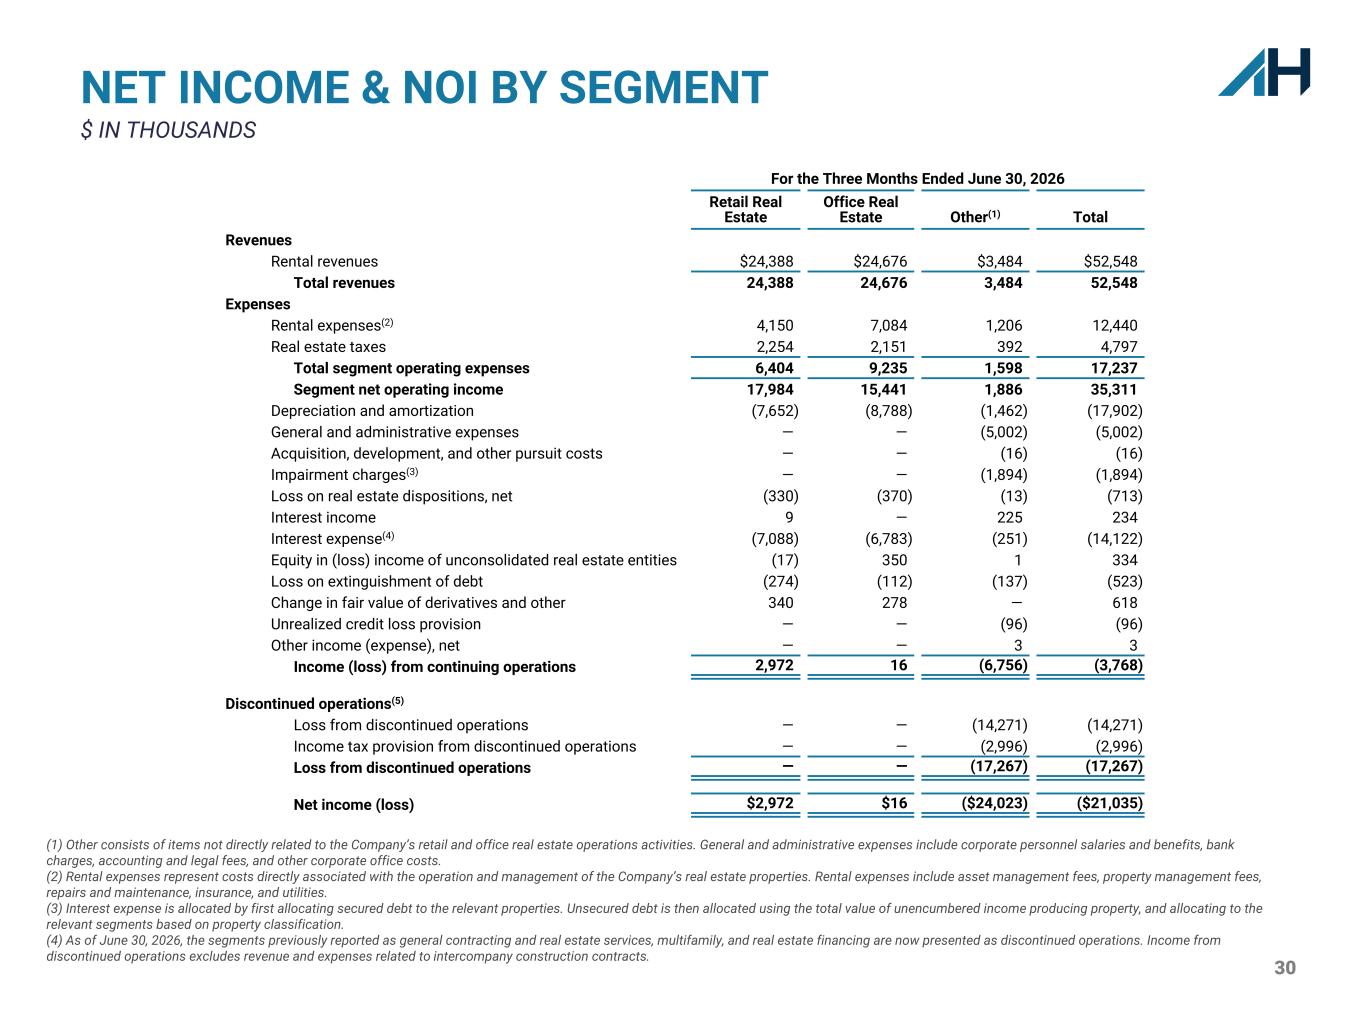
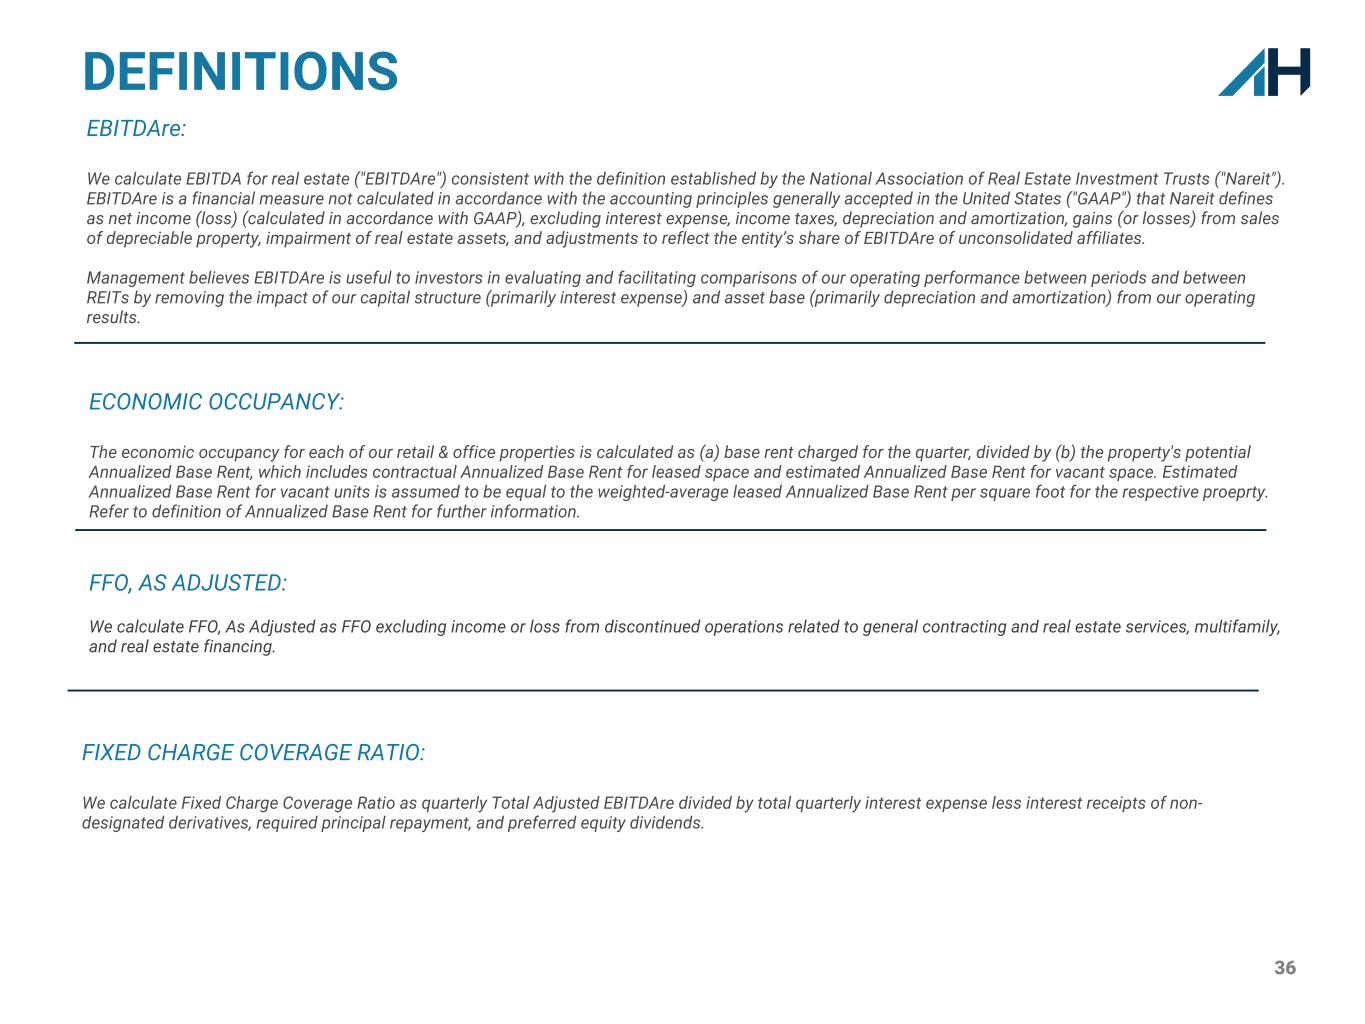
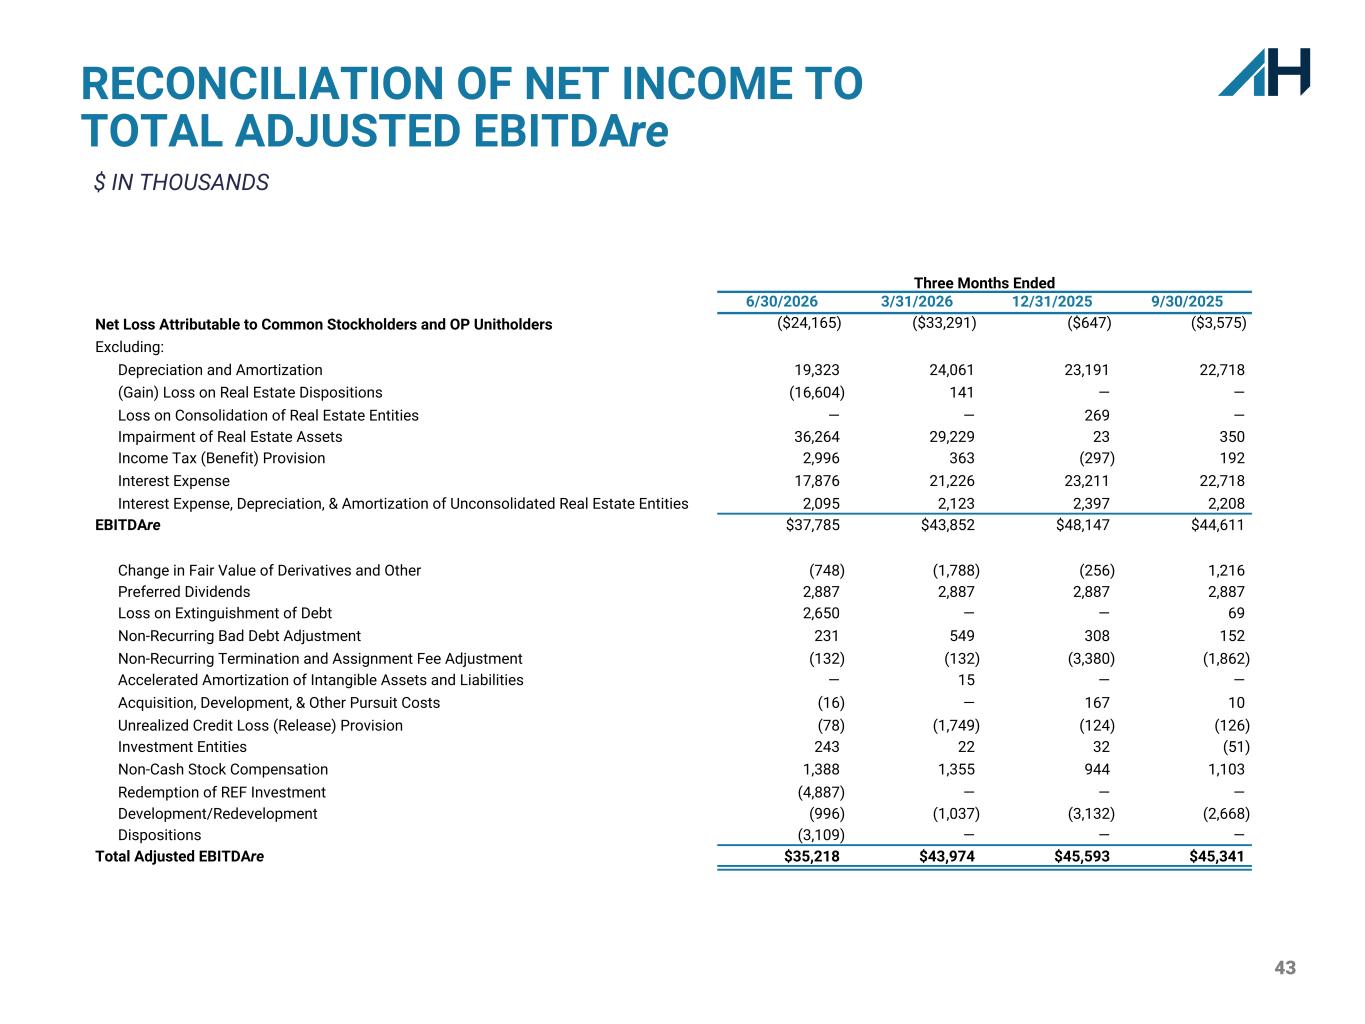
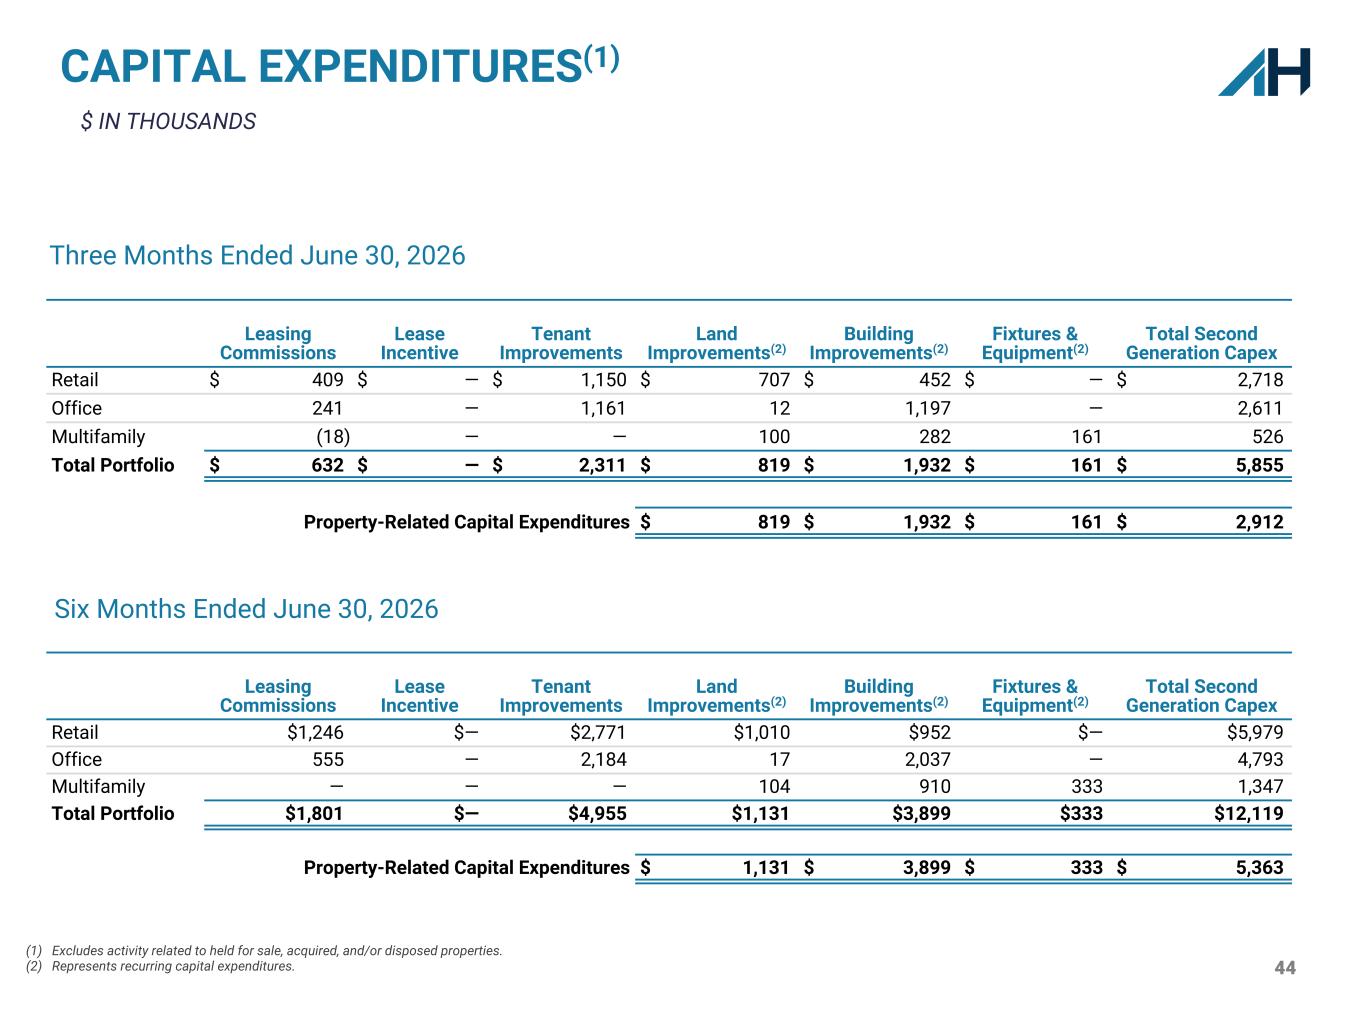
Good morning, and thank you, Craig. AH Realty Trust delivered another quarter of solid execution against our transformation, highlighted by the first closing of our multifamily portfolio sale, a meaningful reduction in leverage, and continued strength across the retail and mixed-use office platform. The results this quarter demonstrate that we are ahead of schedule with our transformations substantially complete and the benefits of a simpler, higher-quality operating platform increasingly evident. For the second quarter, FFO attributable to common shareholders was $15.4 million, or $0.16 per diluted share. FFO, as adjusted, which excludes the results of the segments we have classified as discontinued operations, multifamily, real estate financing, general contracting and real estate services, was $14.1 million, or $0.14 per diluted share. Total property portfolio NOI for the second quarter was $35.3 million, an increase of 2.2% year-over-year, with same-store NOI cash up 5.3% on a blended basis, 2.9% in retail, and 8.3% in office. AFFO totaled $18.1 million, or $0.18 per diluted share, which compares to our current dividend at a payout ratio of approximately 77%. As Craig went over in detail, our retail and mixed-use office portfolios continue to perform Retail renewal leaf spreads on a cash basis were 8.7% for the quarter, and office renewal lease spreads on a cash basis were a strong 21.6 percent reflecting the quality and location of our office assets particularly within our mixed-use ecosystems at harbour point in Baltimore and the interlock in Atlanta the broader flight to quality dynamic that continues to define the office leasing market nationally with well-located amenitized assets capturing a disproportionate share of demand is playing directly to the strength of our mixed-use office portfolio and we believe our office same-store NOI growth this quarter and our broader financial performance is a direct reflection of that trend. As Sean covered, our exit from multifamily, real estate financing and general contracting is largely completed. That progress gives us the flexibility to keep executing our capital allocation priorities, continuing to pay down debt investing selectively in high growth markets and repurchasing shares our balance sheet metrics discussed further on page 14 of the supplemental continue to reflect the underlying quality and embedded value in our retail and mixed use office real estate and remain central to how we evaluate capital allocation including our share of purchase program year to date through June 30th we We repurchased 5.6 million shares for $33.2 million, or an average price of approximately $5.92 per share. Our common stock closed the quarter at $7.08 per share, up from $5.50 per share at the end of the first quarter, and we view repurchases as one of the most attractive uses of capital available to us with our current cost of capital. Continuing with the balance sheet, this was a defining quarter for our deleveraging efforts. The first closing of our multifamily portfolio sale generated $485 million of gross proceeds, which we used to pay down $353 million of net variable rate debt and $456 million of net debt in total during the quarter. As a result, total debt outstanding declined from $1.49 billion at the end of the first quarter to $1.04 billion at quarter end, and net debt to total adjusted EBITDA improved to 7.1 times, down from 8.3 times last quarter. Net debt plus preferred to total adjusted EBITDA improved similarly to 8.3 times from 9.2 times. We are pleased with this progress, though we recognise there is still work to do to reach our target leverage range of five and a half to six and a half times, and we expect to make further progress as we complete the remaining multifamily and real estate financing dispositions over the balance of the year. As of quarter-end, all of our debt was fixed rates or hedged at a weighted average interest rate of 4.3%. Our weighted average years to maturity stands at two years, which is intentionally short as we work through this final stage of the transformation. And we expect that figure to extend as we complete the refinancings I will now discuss. us. On loan maturity specifically, we successfully refinanced Tame Street Wharf in Baltimore during the quarter. Effective June 2nd, 2026, we extended the maturity on this asset level non-recourse loan by five years to September 30th, 2031, and entered into a new interest rate swap effective September 30th, 2026, fixing the all-in rate on this loan at 5.66%. This is consistent with the pricing and structure we discussed on our last call, and it reflects both the quality of this asset and the continued support we are seeing from our relationship lenders, even in a selective financing environment. We are also actively working on our remaining near-term maturities. The Constellation Energy Building Loan, with $121.8 million outstanding, matures in November of this year we continue to progress the refinancing discussions looking further out we are monitoring our 2027 unsecured maturities including the revolving credit facility and our unsecured term lapse and will keep investors updated as those discussions progress separately in may we exercised a 12-month extension on our td unsecured term loan pushing that maturity to may 2027 on its existing terms. Strategically, we will endeavor to consolidate all of these term loans under our primary credit facility that we will look to recast later this year. We would like to note that we are executing this maturity schedule against a broader commercial real estate backdrop in which an estimated 875 billion dollars of mortgage debt is scheduled to mature industry-wide in 2026. Much of it originated at rates of 3% to 4% and now facing refinancing markets in the 6% to 7% range. Against that backdrop, we believe our fully fixed and hedged position at a 4.3% weighted average rate, together with the proactive asset-by-asset approach we have taken to our maturities, position us well relative to the sector, limiting the exposure we have relative it to our pits. We ended the quarter with total liquidity of $267.1 million, including $203.7 million of availability under our credit agreements and $35.5 million of cash on hand. 84% of our properties, representing 71% of our annualised base rents, remain unencumbered, provided us with additional flexibility as we work through the remaining stages of the transformation turning to guidance we are raising our full year 2026 same store noi cash growth ranges to two and a half percent three and a half percent for retail and 2.75 to 3.75 for office and we now expect ffo as adjusted of 53 cents 57 cents per diluted share for the full year This outlook assumes the dispositions of the remaining multifamily portfolio, with the exception of Smith's Landing, the exit of our remaining real estate financing portfolio, approximately $57 million of additional secured debt paydowns funded by the expected dispositions of the Everleigh and Greenside, and approximately $100 million of further net unsecured debt paydowns with no acquisitions currently planned for the 2026 fiscal year. We remain confident that the actions underway simplified our operating model, exiting non-core businesses, strengthening our balance sheet, and executing share repurchases position us to drive long-term value for shareholders. We are committed to unlocking that value, and we will continue to provide the enhanced disclosures that allow investors to track our progress.
With that, I will turn the call back over to Sean. thank you matt before i close i want to step back for a moment because the numbers alone don't capture everything this team accomplished this quarter less than six months ago ah realty trust was a multi-business multi-sector company carrying significant complexity and balance sheet leverage Today, we are a pure-play retail and mixed-use office read with a dramatically simplified business, a materially stronger balance sheet, and a go-forward earnings profile that is clean, predictable, and durable. To repeat the numbers, over $565 million in signed or closed asset sales, $460 million of debt paid down, 5.6 million shares repurchased, and two new independent directors added to the board, all in under two fiscal quarters. That is exceptional execution for any business, and it is a direct reflection of the AH Realty Trust team's talent, discipline, and ownership mentality. There is more work to do. We will execute the pending multifamily sales and continue to invest in our portfolio and our people. This should grow long-term shareholder value and close the NAV gap. The foundation has been built. Now we execute. We remain deeply grateful for the continued support and confidence of our shareholders and look forward to the opportunities ahead. Operator, we are ready for questions.
Operator
At this time, I would like to remind everyone in order to ask a question, press star, then the number one on your telephone keypad. We will pause for just a moment to compile the Q&A roster. Your first question comes from the line of Victor Fedev with Scotiabank. Your line is open.
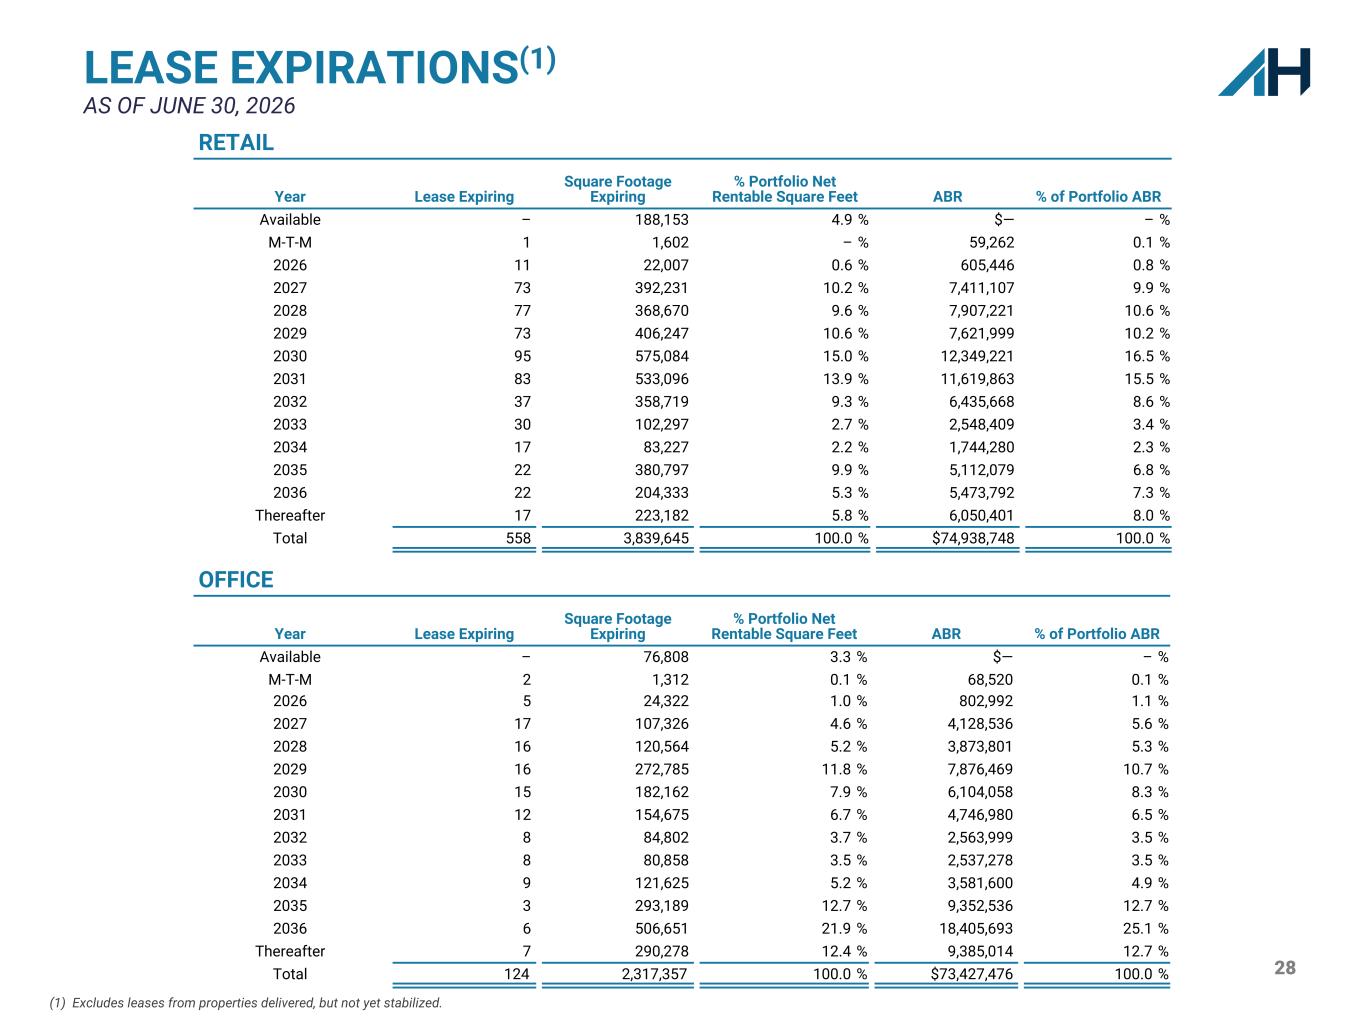
Good morning, everyone, and thank you for taking my question. First of all, congratulations on Solid Quarter and substantial progress on your transformation. Now, looking at the 2027 expirations, have discussions started with any of the larger tenants, and are there any known move-out or challenging renewals to flag, and what are your expectations for renewal spread on that cohort?
Thank you, Victor, and appreciate the kind words. Obviously, we're pushing as hard as possible here with quality and with speed, so I appreciate you recognizing that. In terms of renewals on, you know, kind of looking forward, our team takes a strategy to mitigate those as soon as possible, right? So we're out a year or two years talking about those, and we've been consistent in that regard, and that's how we keep that kind of rollover list minimized because we're proactive and obviously partner with tenants in that regard. As it relates to spreads, Craig, and kind of Victor's question there, you want to take that and give a little insight into what you're seeing?
Yeah, happy to, Sean and Victor. Thank you for your question. You know, as we look at the portfolio, you know, we've got retail and office expirations coming up next year. I feel really, really good about the retail role next year. A lot of that consists of anchor spaces that have been long tenures at our shopping centers. And as Sean mentioned, we're proactive in that regard in terms of getting in front of that. So no real risk that we see in next year's role in the retail side. If anything, there's some opportunity. There are pockets of anchor spaces that are probably below market that present some recapture opportunities to push rents a little bit. So I'm excited about that. On the office side, you know, if you look at the portfolio, Town Center, we're 99% leased, not a ton of roll over there. We continue to push rents even though we're at the top of the market. We see it in our spreads for this quarter. Really, the one thing we have our eye on is at the Interlox, we've got a ton of growth coming from the Interlox this year. We'll see it again next year. But we do have some spaces rolling next year. But given the momentum we have at that asset, we feel really good about our ability to capture market rates there. So all in all, still feel really confident about next year and our ability to manage the minimal rollover that we do have.
Makes sense. And then with retail leased occupancy at 95%, office closer to 97%, does a portfolio stronger occupancy position allow you to reduce free rent and TI? concessions, or should we expect leasing economics to remain kind of similar to rest Obviously, we would prefer pushing, and I think in, let's take the office, let's break this down, let's take the office first.
In the office assets that we have, we do see a supply-demand situation there that leans in our favor, right? So, similar to what I mentioned in my remarks, we have a situation where we're out of space in town center therefore we moved our headquarters out created 1.3 million of abr and we're in a former kind of vacant retail space as we sit here and talk to you today and so i think that's a that's a proxy for or not or an example of our ability to push rents victor because people want to be in these amenitized office locations these mixed use ecosystems and for that reason we're able to have some pricing power and we we expect that to continue to be the case in the short to near term, obviously. And, you know, at some point, I think the market bifurcates and differentiates between suburban office and the type of office that we own, the highly aminatized sitting in these ecosystems. In terms of retail, I think it depends on the retail asset. We have a couple of different types, as Craig, I'm sure we'll discuss with you here in a second. But yeah, we do see, in some cases, market-to-market opportunities. In other cases, we see steady issue goes gross. So I think, you know, it depends on which asset we're talking about. Craig, you want to kind of split that up quickly, if you don't mind?
Yeah, happy to, Sean. Yeah, so in the open-air shopping center portfolio, which comprises roughly 75 percent of our retail NOI, I think we really, we do benefit from the supply-demand dynamic that currently exists. Sean mentioned, you know, there's a lid on new supply in terms of development. And so the spaces that we do have are leasing, and we're able to push rent. I gave a couple of examples in my prepared remarks, specifically at Southgate Square, where we're seeing significant double-digit spreads on both renewals and new leases, so with good traffic year-over-year and kind of pre-COVID. In the mixed-use space, town center, interlock, those are a little bit more capital-intensive, so to attract the right kind of tenants to complete the merchandising mix does generally require a little bit more investment but as with every deal we are thoughtful and judicious and we screen for the right economics and if the economics still makes sense then those are deals that we tackle. So all in all still really really optimistic about our growth prospects here next year and beyond.
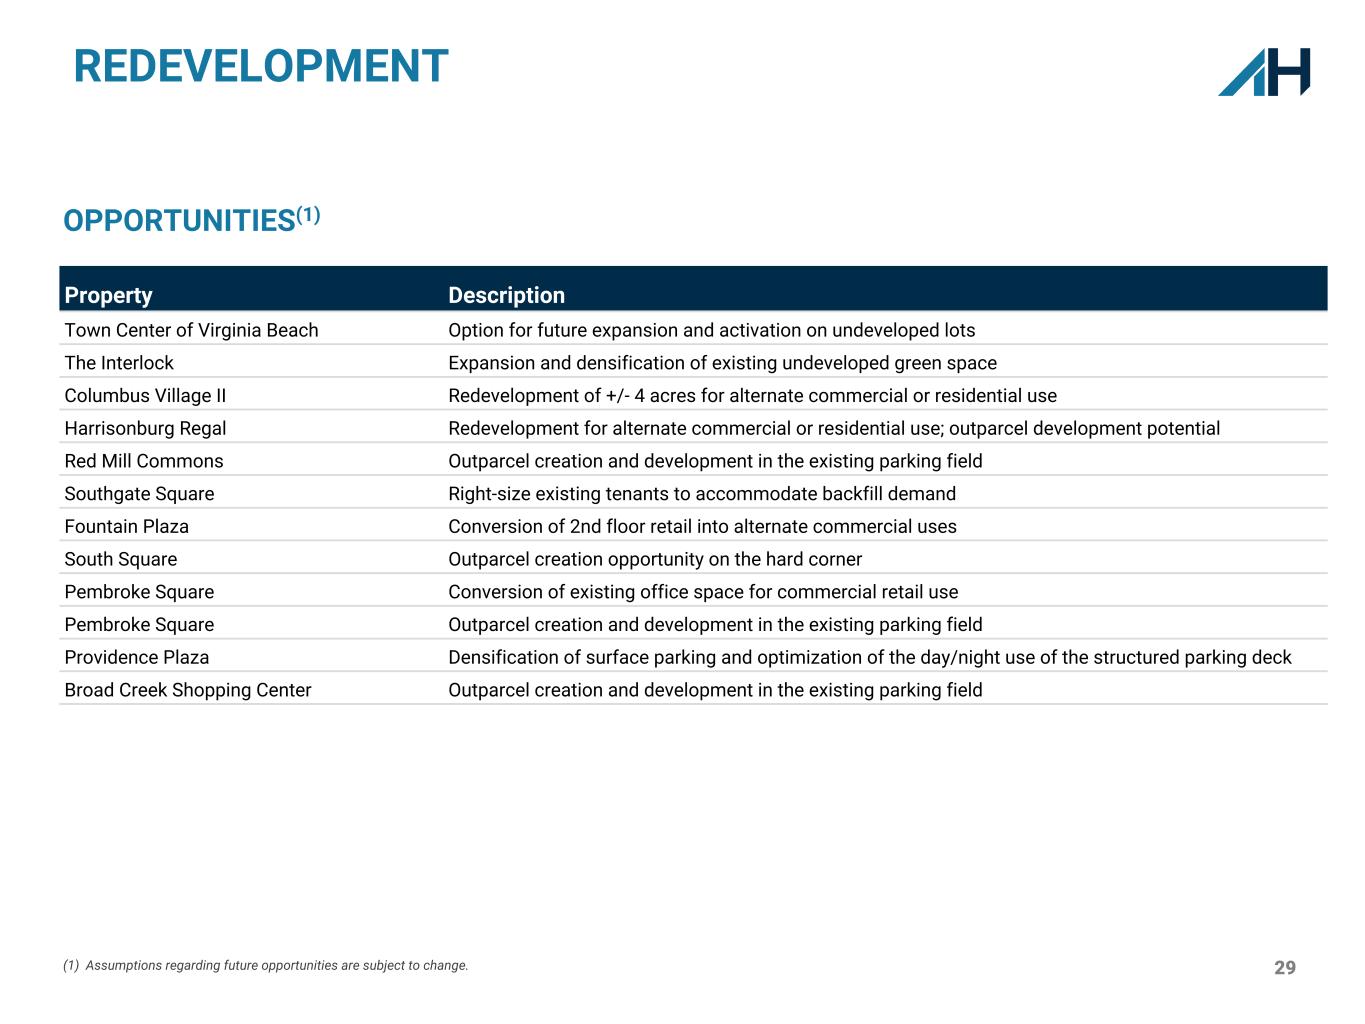
Good and the last quick one for me on your future opportunities I appreciate the beliefs that you have in your disclosures Which one of these projects you are the most excited about and why?
You're saying for our future opportunity set. Yeah, I think it's probably in the out parcel section, as we said here today, right? We're looking at a couple of opportunities. And I think that's probably, in terms of investment, the quickest benefit to shareholder and the least kind of capital intensive, As we think about, you know, things that are additive to the embedded earnings that we know about today, i.e. 2026 into 2027, we think that incremental kind of additive income is most efficiently put on the table in out-parcel leases and these out-parcel redevelopments. there's some potential repositioning. I know Craig and his team are looking at a couple of things there in terms of repositioning boxes, similar to what you've seen us do here in Town Center with the Trader Joe's. Do you want to add any color to that, Craig? Happy to step back for a second.
Yeah, no, I'll expand on exactly what you said, Sean. So a good example of out-parcel development creating something out of literally nothing. Southgate Square, we were able to negotiate a deal with Seven Brew Coffee on an area of the parking field that we thought was undevelopable bowl. It's too small to accommodate a traditional drive-thru user. But as the markets change, concepts change, smaller format concepts, we're able to capitalize on that and create additional NOI and value literally out of nothing. And so we constantly look through the portfolio for opportunities just like that where we can continue to create shareholder value.
Operator
Before going to the next question, again, if you would like to ask a question, press star 1 on your telephone keypad. Your next question comes from the line of Jana Gallen with Bank of America. Your line is open.
Thank you. Good morning, and congrats on the quarter and the progress on the transformation. I believe you touched on a few of these in the opening remarks, but can you walk through the timing of the sign-not-yet-occupied NOI coming online for office? I think the largest pieces are Southern Post and the interlock.
Happy to, Jana. Thank you for your question uh yes so uh in regards to the Sinai occupied pipeline the amounts we quoted uh earlier were specific to the stabilized portfolio so that would exclude southern post but the majority of that 4.6 million dollars of of Sinai occupied pipeline a majority of that we expect to come in some of that will trickle in towards the second half of this year most of it uh next year in 2027 uh primarily at the interlock uh where we have executed leases from from months ago uh starting to to come out of free rent periods as space delivers thank you and then nice retail leasing this quarter i saw a couple new tenants enter the top tenant list um but i
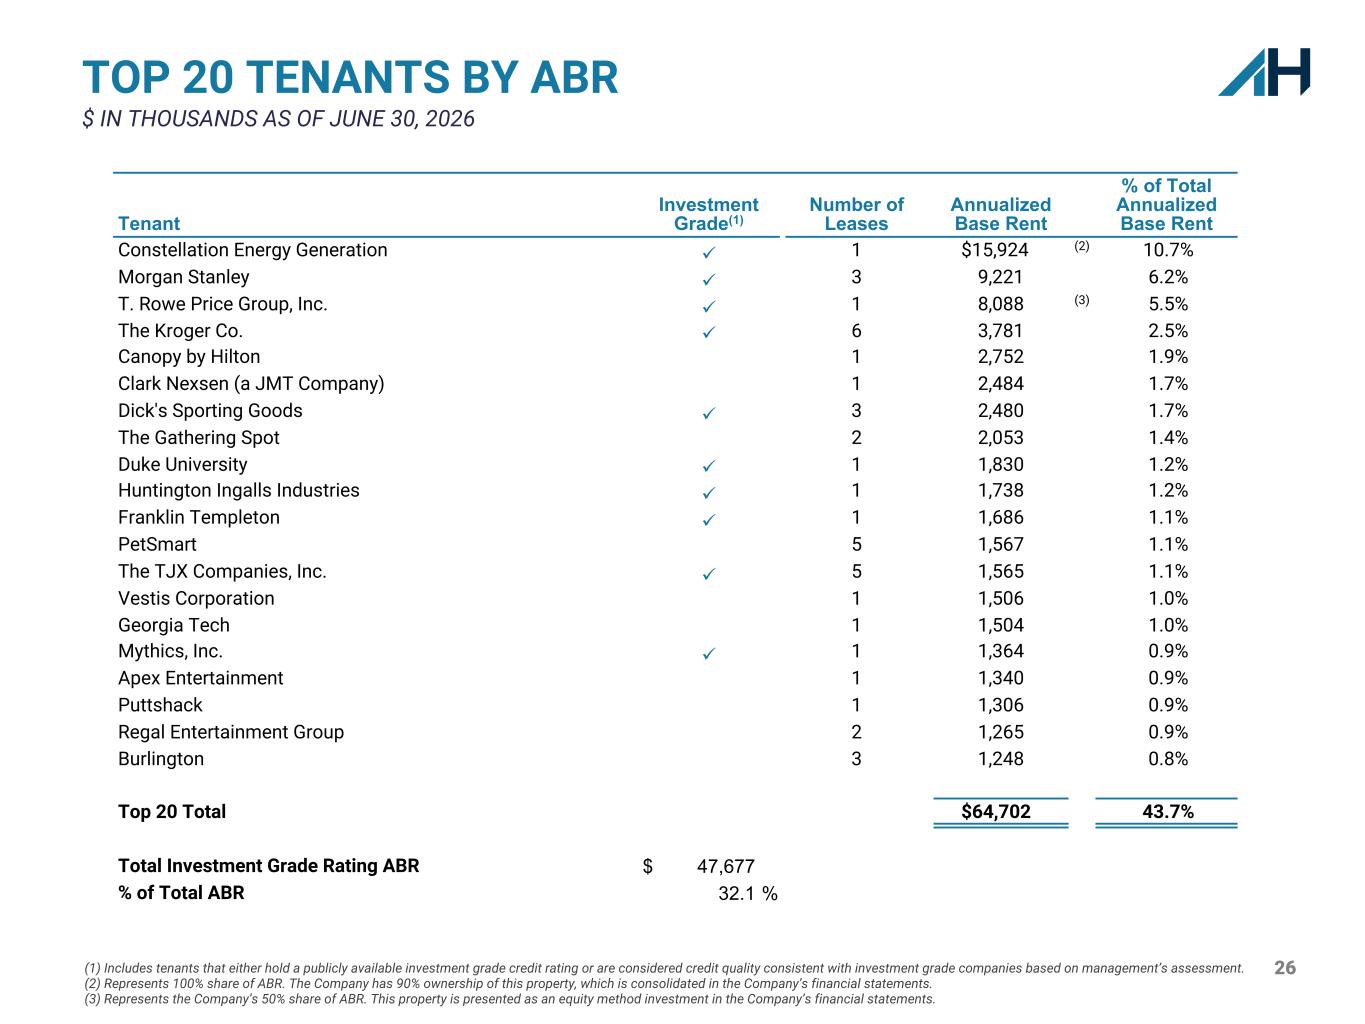
also noticed the lease terms this quarter were a little shorter on both renewals and new leases And I was just curious if there's anything driving that.
No, nothing specific in that regard. Our renewal population is generally pretty small. What you're seeing is a lot of exercise of five-year options from existing tenants. So that's kind of the phenomenon driving the weighted average renewal terms this quarter.
Operator
I will now turn the call back over to Sean Tibbetts for closing remarks.
Thank you very much. I want to say thank you for taking the time to be with us this morning. And most importantly, thank you for your confidence in us. We are excited about the path forward, as I hope you can tell. Obviously, announced a bunch of exciting things today, and we continue to execute. And that's been our commitment to do exactly what we said we would do, when possible, faster, and when possible with a higher degree of quality. So thank you for your time and thank you for your commitment to this company.
Operator
Ladies and gentlemen, that concludes today's call. Thank you for joining. You may not disconnect.