Operator
Thank you for standing by. My name is Jael and I will be your conference operator today. At this time I would like to welcome everyone to the DK fourth quarter 2024 earnings call. All lines have been placed on mute to prevent any background noise. After the speaker's remarks there will be a question and answer session. If you would like to ask a question during this time simply press star followed by the number one on your telephone keypad. If you would like to withdraw your question simply press star one again. I would now like to turn the conference over to Robert Wright, Deputy CFO. You may begin.
Robert Wright Good morning, and welcome to the Delic U.S. Fourth Quarter Earnings Conference Call. Participants joining me on today's call will include Abigail Sorek, President and CEO, Joseph Israel, EVP Operations, Reuben Spiegel, EVP and Chief Financial Officer, and Mark Hobbs, EVP Corporate Development. Today's presentation material can be found on the Investor Relations section of the Delic U.S. website. Slide two contains our safe harbor statement regarding forward-looking comments. Any forward-looking information shared during today's call will involve risks and uncertainties that may cause actual results to differ materially from today's comments. Factors that could cause actual results to differ are included here as well as within our FCC filings. The company assumes no obligation to update any forward-looking statements. I will now turn the call over to Avigal for opening remarks. Thank you, Robert.
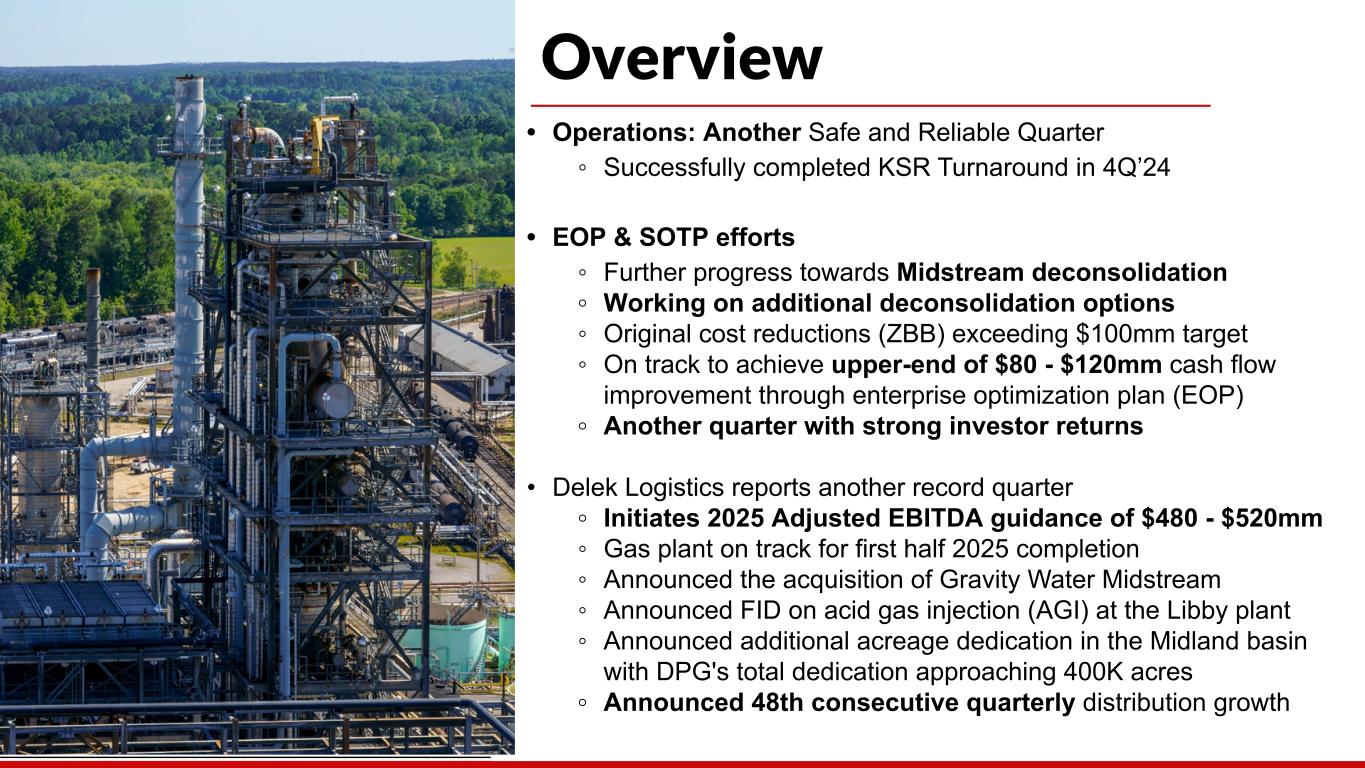
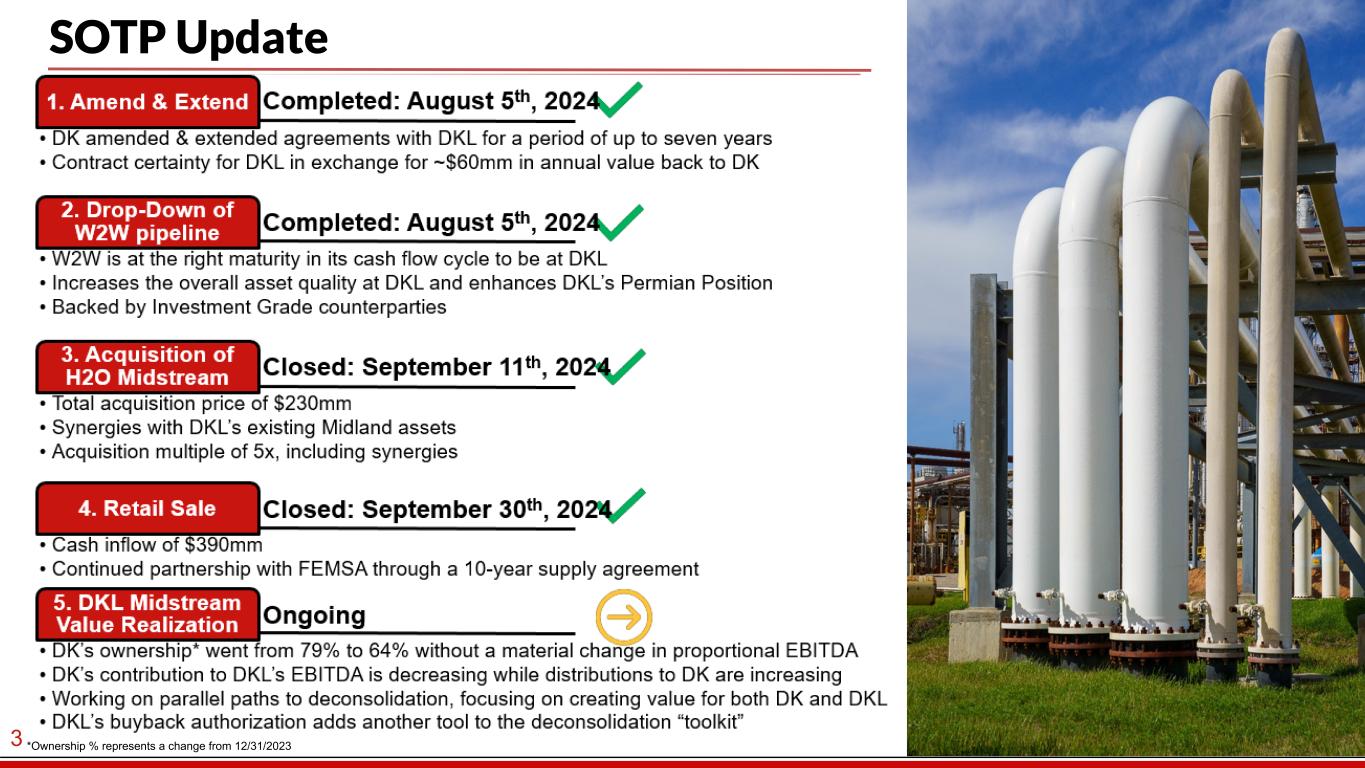
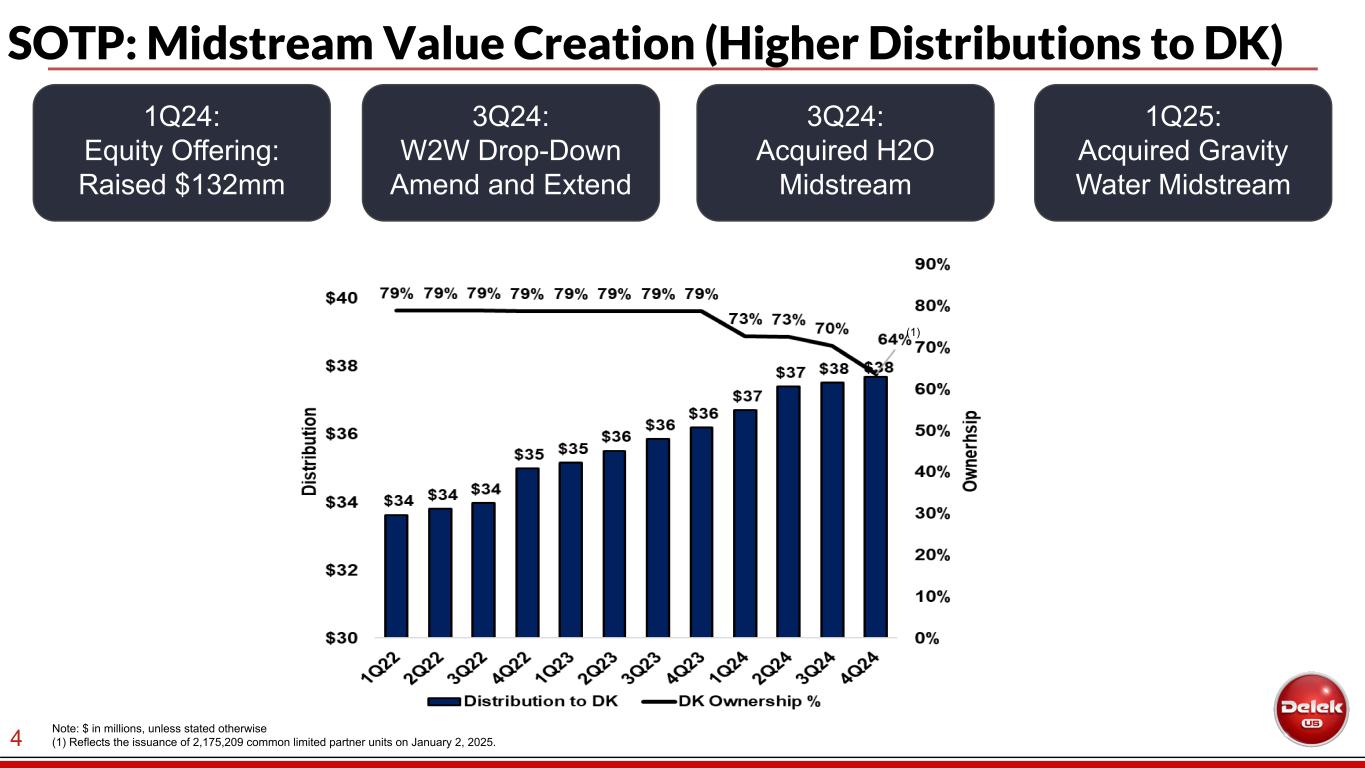
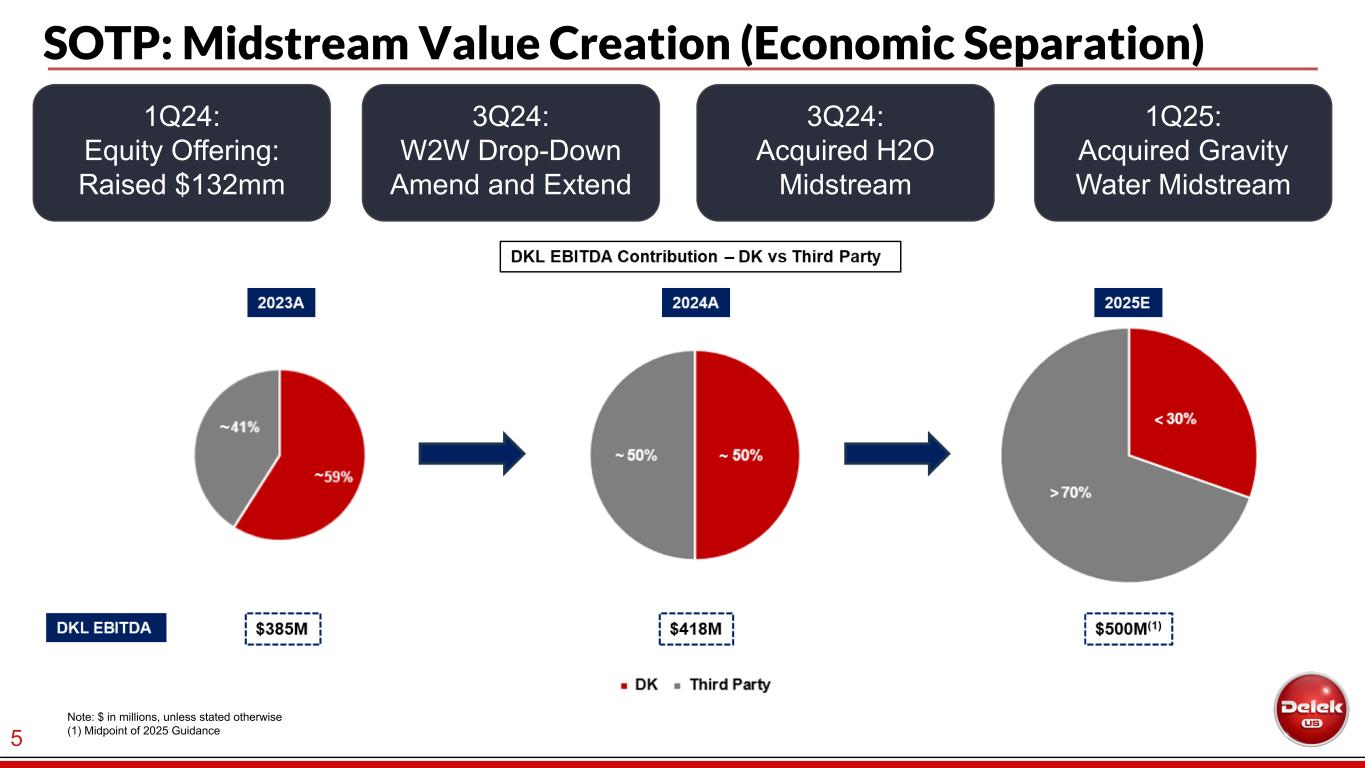
Good morning, and thank you for joining us today. Despite a challenging refining margin environment, which we believe was around $6 below mid-cycle in Q4 of 2024, 2024 was transformational here for us. We have vastly improved our operational performance, made significant progress on our sum-of-the-part efforts, and implemented key plans to increase the overall profitability of our company. I would like to highlight the progress we have made on our key priorities. First, safe and reliable operations. We have made great progress in improving the operations towards our company. We have successfully completed a major turnaround at KSR in the fourth quarter. Coming out of the turnaround, the refinery is showing improved operational performance. the asset is running well and we look forward to a strong contribution from ksr in 2025. moving to big spring in 2024 we have significantly improved its reliability we have consistently been running over 70 000 per day looking forward in 2025 we have no major turnaround planned in our system and we expect to continue our improvement journey now i would like to discuss our sum of the part strategy in 2024 we made great progress in unlocking the sum of the parts value inherent in our assets in september we sold our retail asset for 390 million dollars and we are extremely happy with the timing and the value we received the timely sale has allowed us to continue to progress our initiative in a in a tough refining environment we have also made great progress in making delec logistics a strong independent midstream company levered to the growth in the permanent basin in 2024 we successfully executed economic swap of assets between DK and DKL. The swap will improve the profitability of our refineries going forward. At the same time, the swap brings more certainty to DKL cash flow through the contract extension by up to seven years. Our economic separation from DKL is increasing and at the same time, the distribution DK received from DKL continues to grow. So, DKL also announced two accretive acquisitions to add around $100 million in third-party EBITDA. After DKL acquisition of Gravity Midstream, DK ownership in DKL has come down to 63.6%. DKL is progressing its capacity expansion in the Libby Gas Processing Complex and expects to complete the expansion in the first half of 2025 as previously communicated. Additionally, DKL announced an FID on acid gas injection at the Libby Complex in December. These steps highlight DKL's progress in becoming an attractive, high-growth, mid-sized, mid-stream company, benefitting from the natural gas growth in the Perman Basin. This is reflected in the strong guidance that Dalek Logistics has provided today. Despite this great move, DKL continues to trade at discount versus its peers, and very limited if any of this value is reflected in DK shares. We are in the process of taking additional steps such that the value of greater than $350 million in third-party EBITDA in DKL is fully reflected in DK share price and DKL unit price. We are confident that we'll complete the DKL deconsolidation in methodical manner and create value for both shareholder and unit holder. In 2024, we have made progress in improving overall profitability of the company. We completed our zero-based budget initiative, which allowed us to save around $100 million in cost through our system. We completed this program in the second quarter of 2024 ahead of our regional target of completion by the end of 2024.
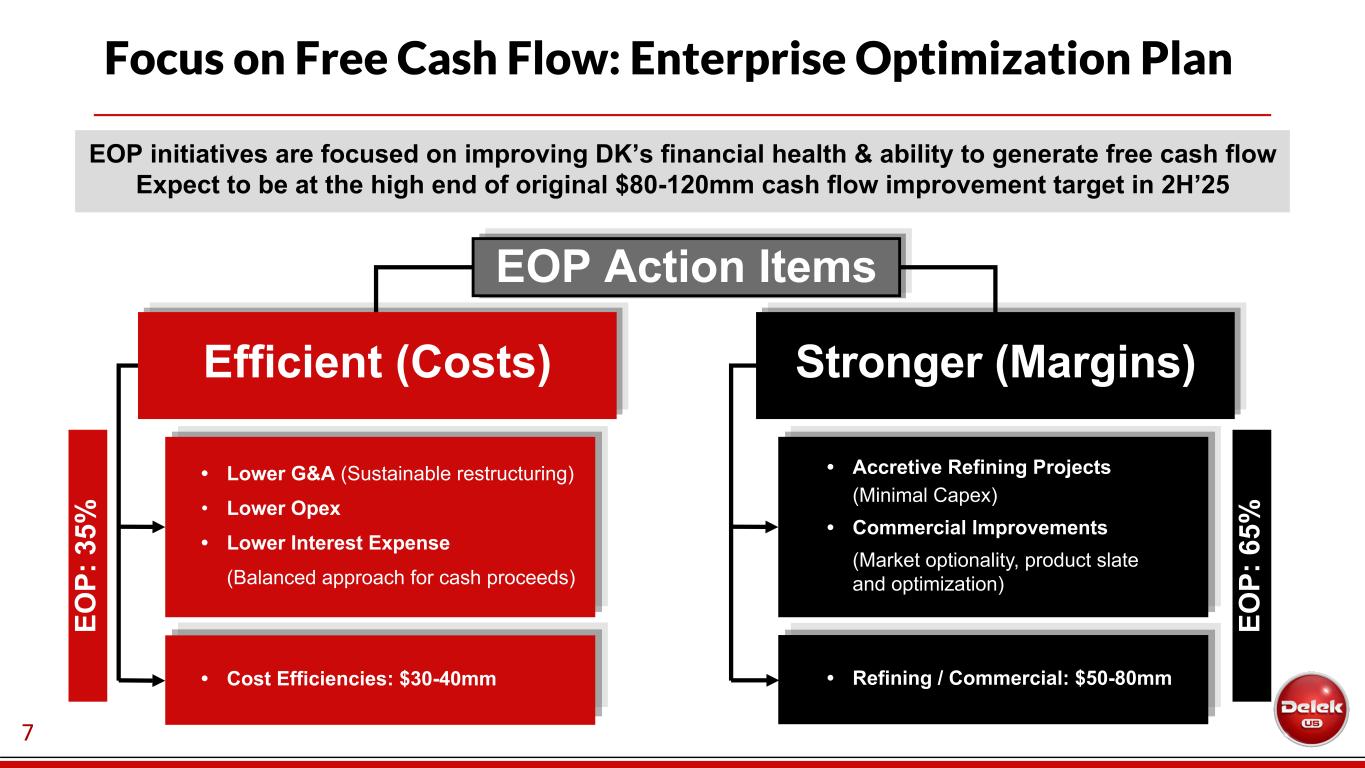
Our VVP effort laid the foundation for our enterprise optimization plan, or EOP.
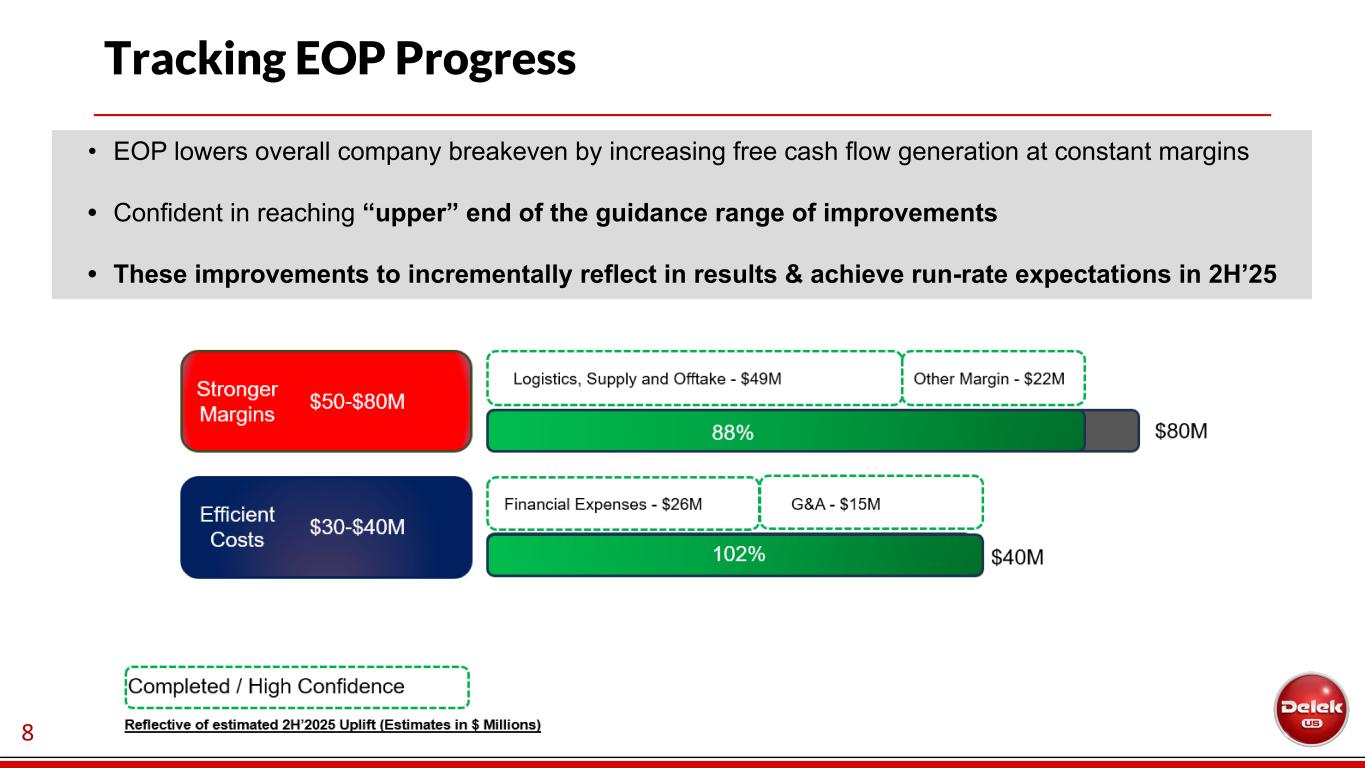
EOP aims to improve DK cash flow by $80 to $120 million per year, starting in the second half of 2025. I'm pleased to announce that we have made great progress with EOP, and now we expect to be closer to the top end of our cash flow improvement guidance. Despite our initial success, we are not standing still and look forward for further improve our cash generation power as we progress through the year. Final piece of our strategy is being a shareholder friendly and having strong balance sheet. During the quarter, we paid $16 million in dividend and bought back $22 million of our shares. We remain committed to a disciplined and balanced approach to capital allocation. Now, I would like to make a comment about small refinery exemptions. As you know, the DC Circuit Court overturned the EPA denial of our small refinery exemption petition under the RFS in July of 2024. Therefore, our petitions were sent back to the EPA for reconsideration. We are optimistic that the EPA will revise its approach following the court ruling and grant us SREs. We hope the recent ruling on SREs along with Supreme Court ruling on Chevron Deferent's case will reduce unneeded bureaucracy and allow for predictable approach to the SRE petition review. in closing i would like to thank our entire team for the hard work and dedication we are excited about the prospects of decay in 2025 and beyond now i will turn the call over to joseph will provide additional color on our operations thank you avigal first i'd like to congratulate our team on another safe, reliable, and environmentally compliant year.
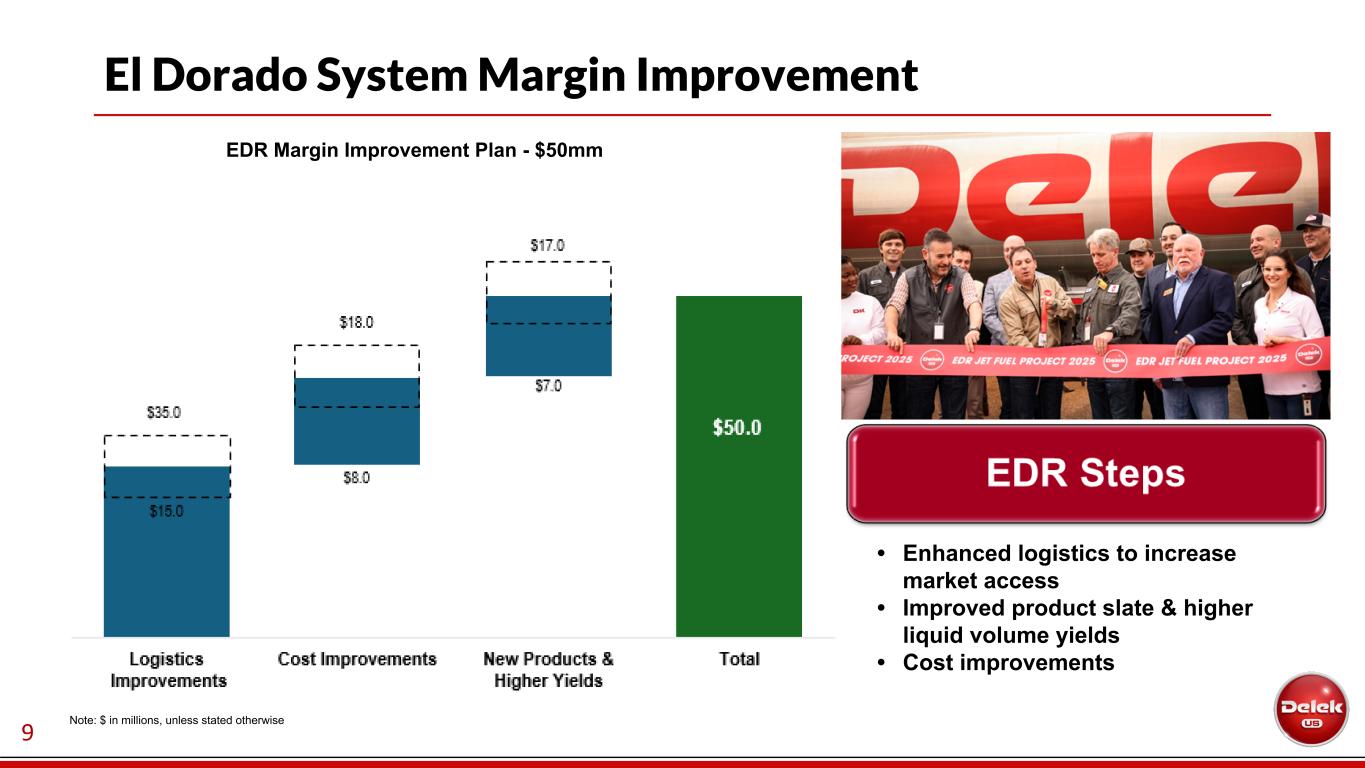
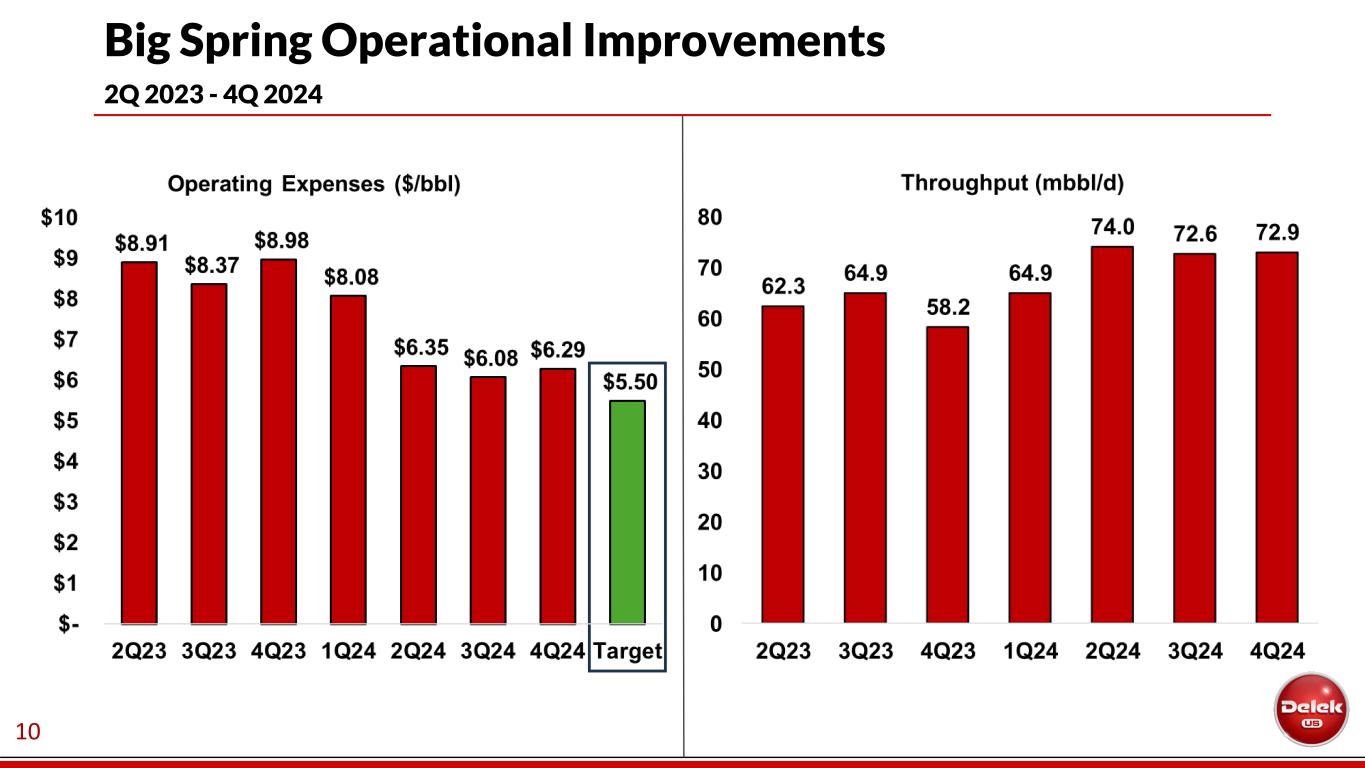
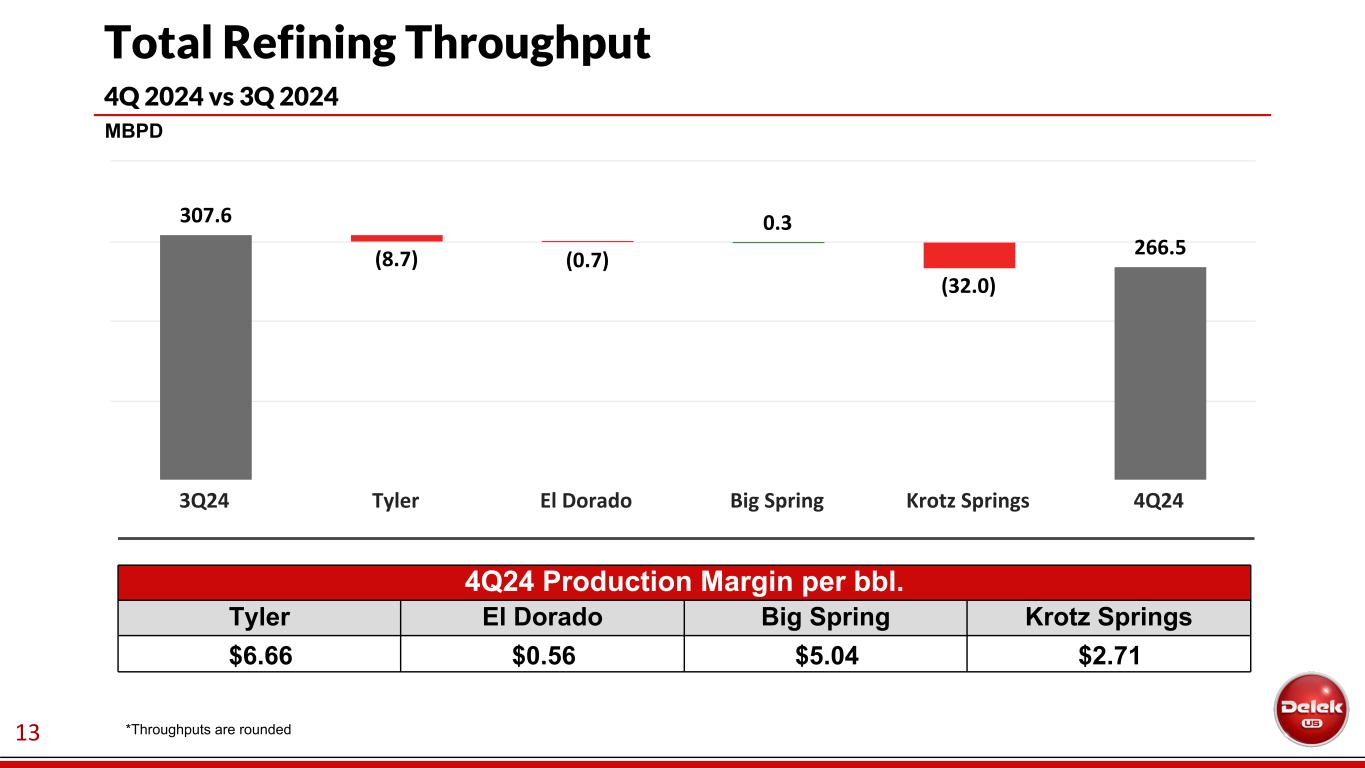
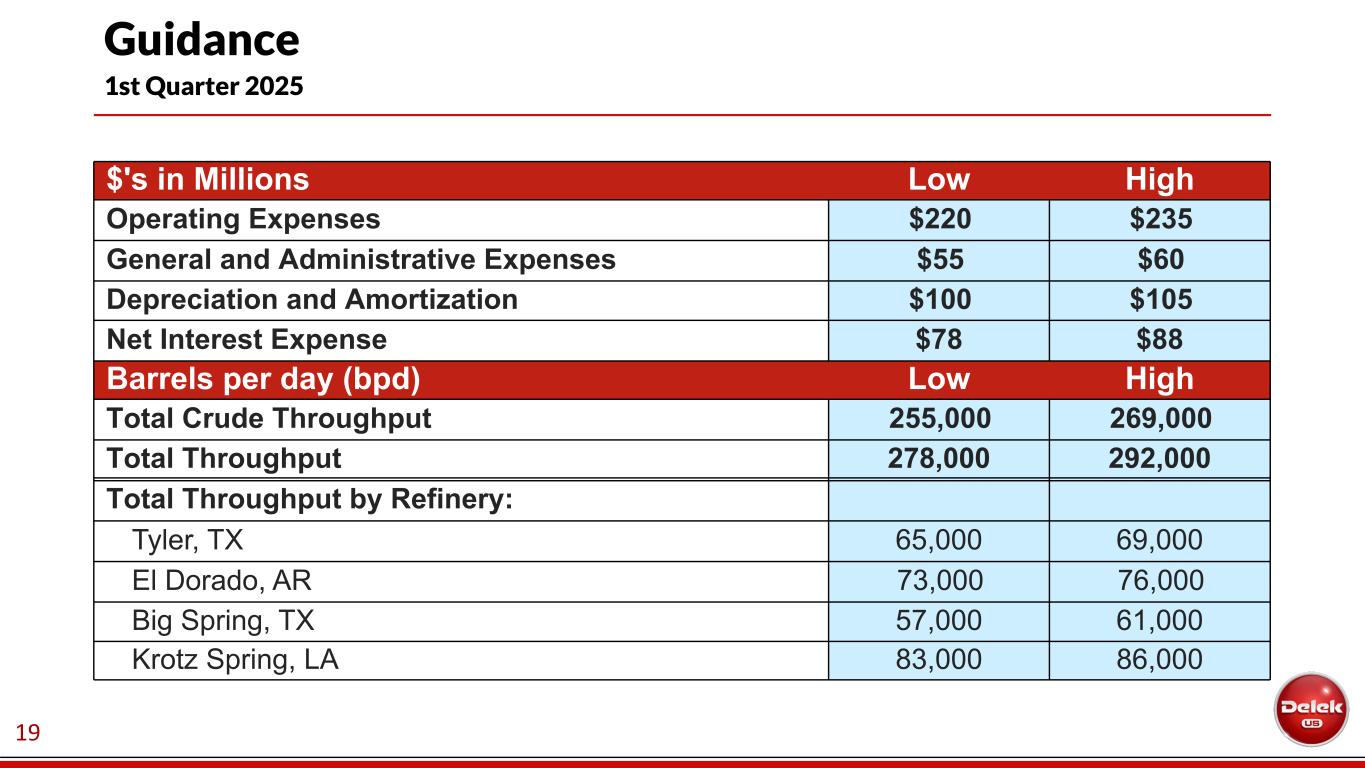
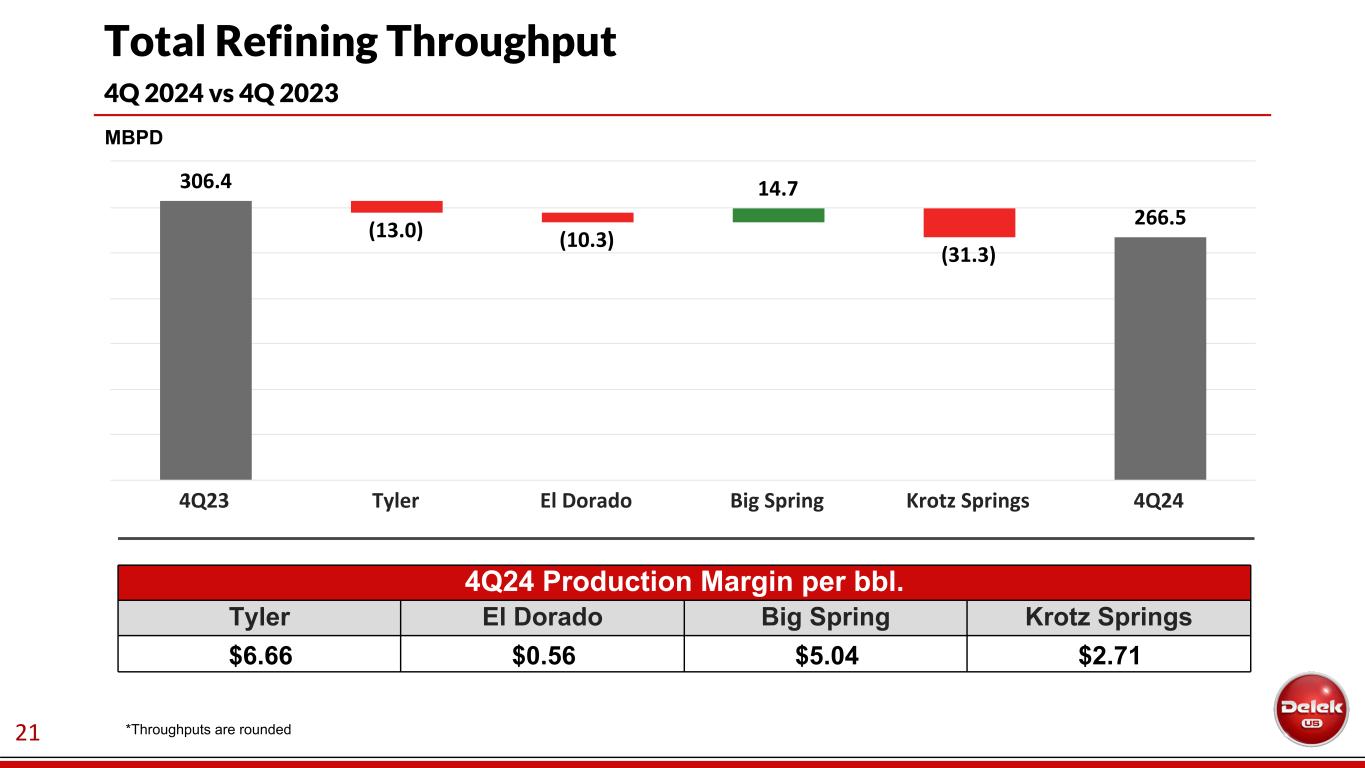
Our progress in hiring the right people, developing good processes, and proactively managing our equipment is well reflected in the field and is giving us a strong foundation to perform, optimize, and grow our business. In Tyler, total throughput in the fourth quarter was approximately 66,000 barrels per day. Production margin in the quarter was $6.66 per barrel and operating expenses were $5.51 per barrel. During the first quarter, we are executing our plant maintenance in the ARC unit. including an upgrade scoop which will allow us to increase production of high-value products by approximately 500 barrels per day. For the first quarter, our estimated total throughput in Tyler is in the 65 to 69 thousand barrels per day range. In El Dorado, total throughput in the fourth quarter was approximately 77 thousand barrels per day. Our production margin was 56 cents per barrel and operating expenses were $4.78 per barrel. Estimated throughput for the first quarter is in the 73 to 76 thousand barrels per day range. On the strategic front, we are making good progress with our EOP initiatives, which are expected to add, by mid-year, $50 million of annual EBITDA run rate in the Eldorado integrated system. The incremental approximately $2 per barrel of net margin will support Eldorado cash flow generation through the cycles. In Big Spring, total throughput for the quarter was approximately 73,000 barrels per day. Our production margin was $5.04 per barrel, and operating expenses were $6.29 per barrel, including approximately 50 cents per barrel of winterization and maintenance special activities. Burgers in Big Spring is well reflected in the numbers. Total throughput in 2024 increased over 10% compared to 2023 due to improved reliability. Cost structure is approaching our target, and as important, it is mostly driven now by routine and proactive agenda rather than reactive. In the first quarter, we are replacing catalysts in our reformer and diesel hydro-treater per plan. As a result, estimated throughput for the first quarter is in the 57 to 61,000 barrels per day range. In Crott Springs, the team successfully completed the planned major turnaround. Since startup, we have demonstrated improved crude capacity, product mix, and liquid yield recovery capabilities consistent with our plans. Total throughput in the fourth quarter was approximately 50,000 barrels per day. Our production margin was $2.71 per barrel and operating expenses in the quarter were $5.27 per barrel. Our planned throughput for the first quarter is in the 83 to 86,000 barrels per day range. Our implied system throughput target for the first quarter is in the 278 to 292,000 barrels per day range. Moving on to the commercial front, in the fourth quarter, supply and marketing contributed a loss of $34.6 million. Of that, approximately a $12 million loss was generated by wholesale marketing, driven by seasonal low demand trends around our system racks. $22 million loss was attributed to supply, and a negative half a million dollars contribution was generated by asphalt. In summary, we continue to execute well on the fundamentals of our business. After successfully addressing reliability gaps, our teams continue to focus on operational excellence and commercial optimization initiatives as we position ourselves for the coming gasoline season and the future cycles. I will now turn the call over to Orbuild for the financial variances.
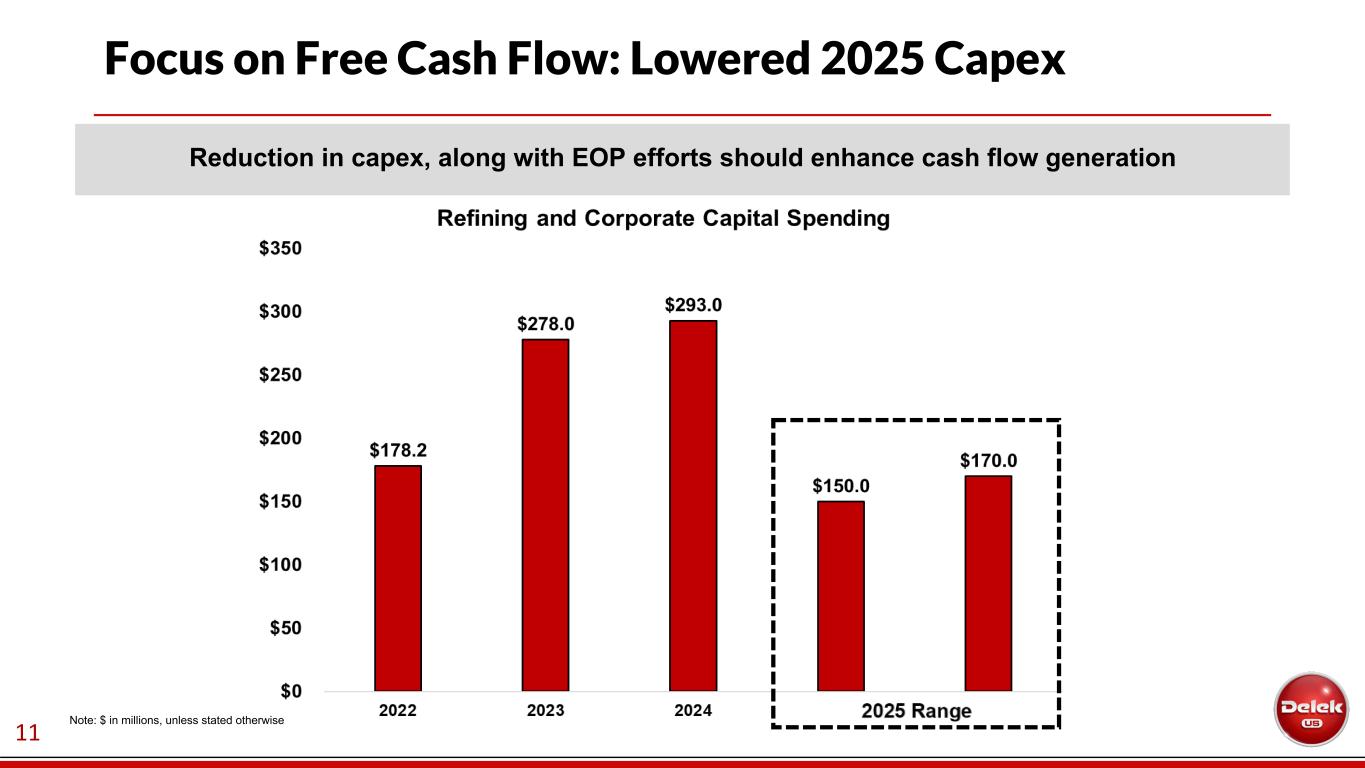
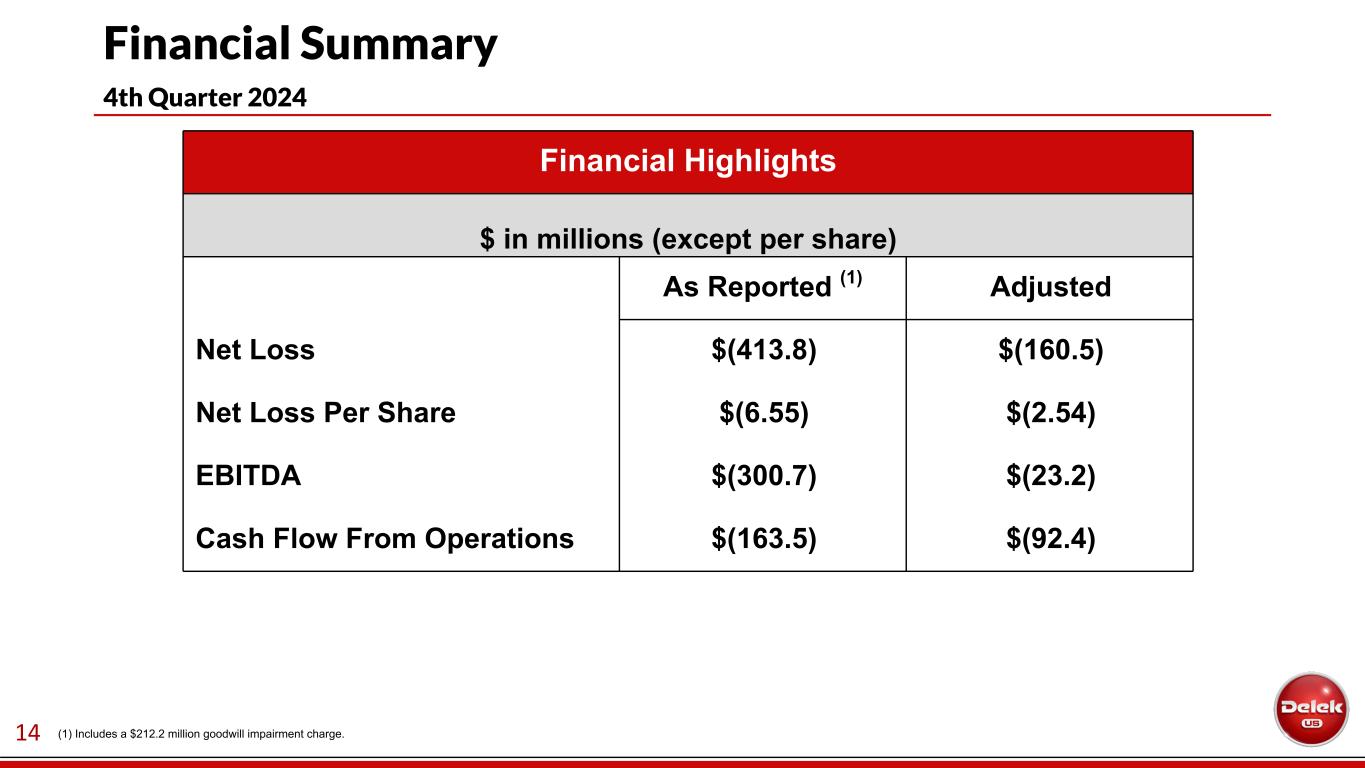
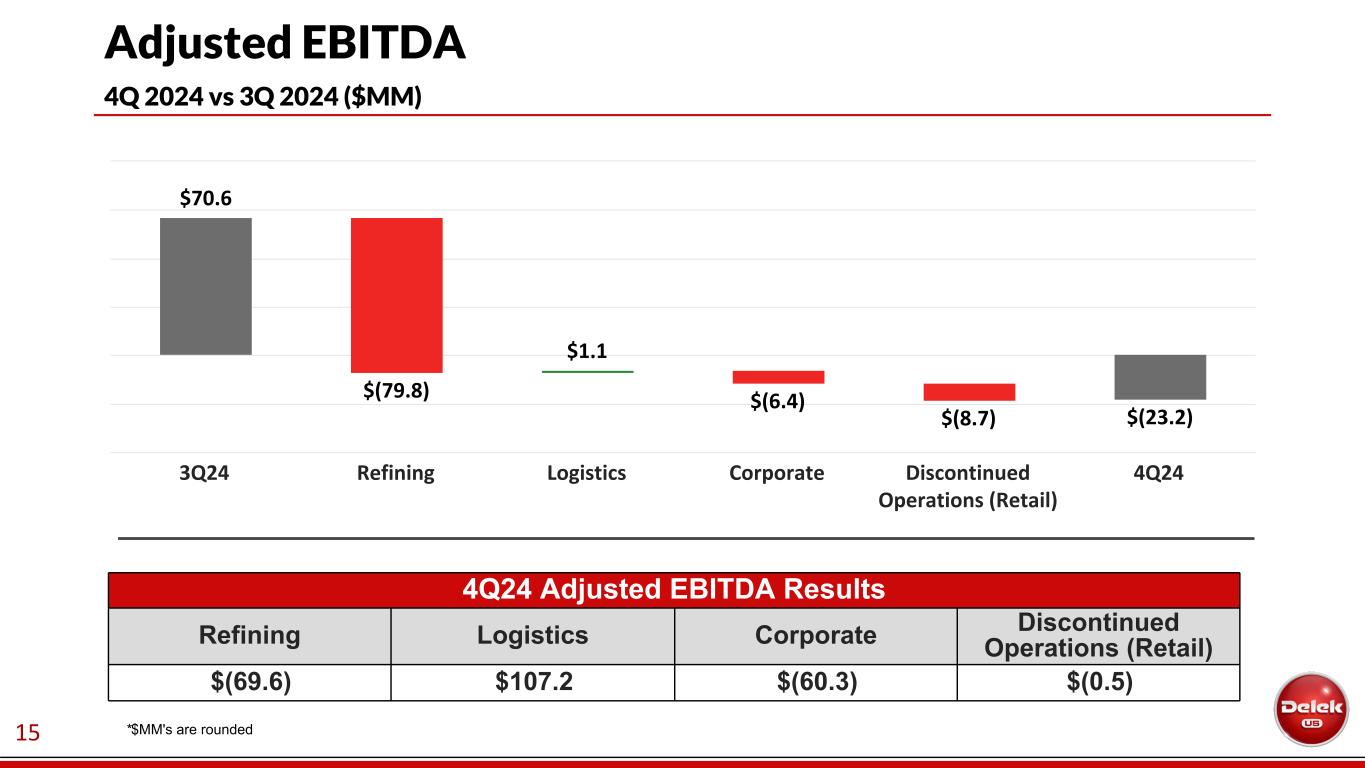
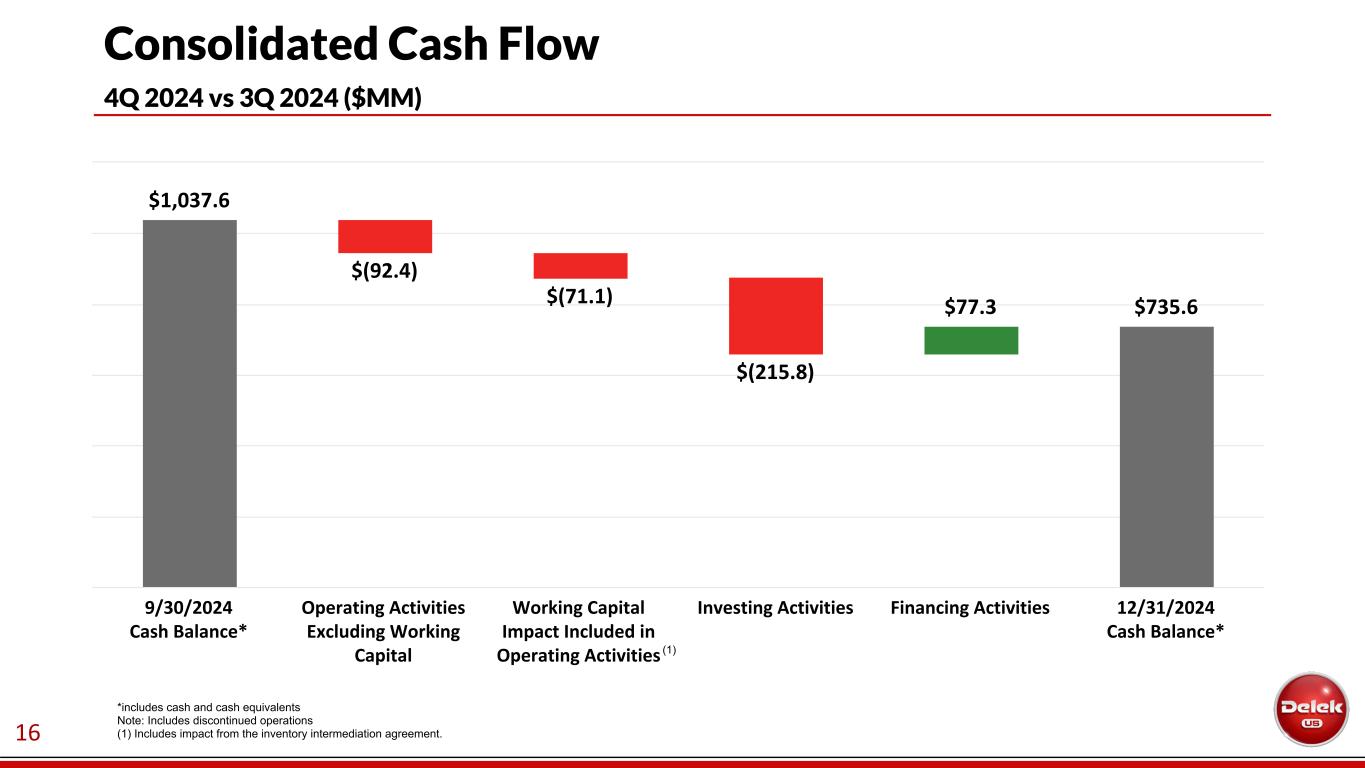
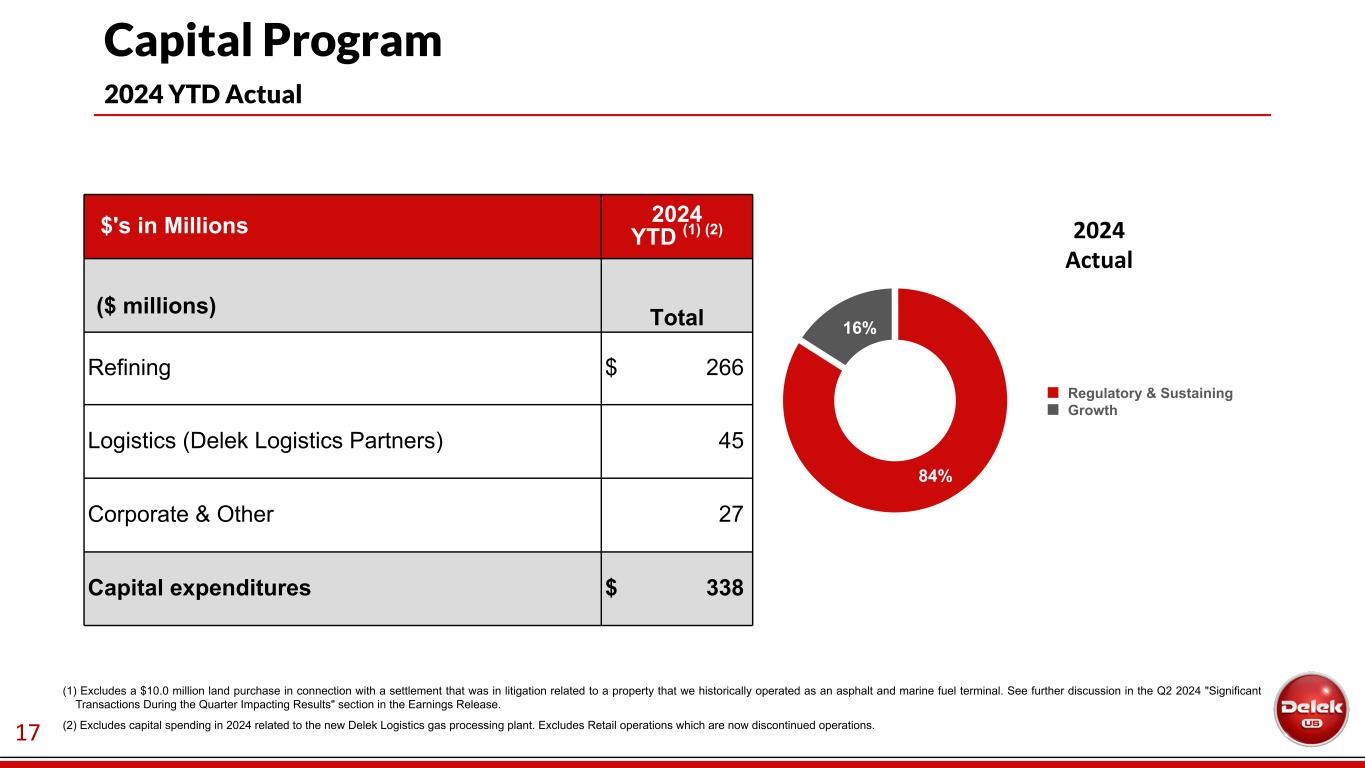
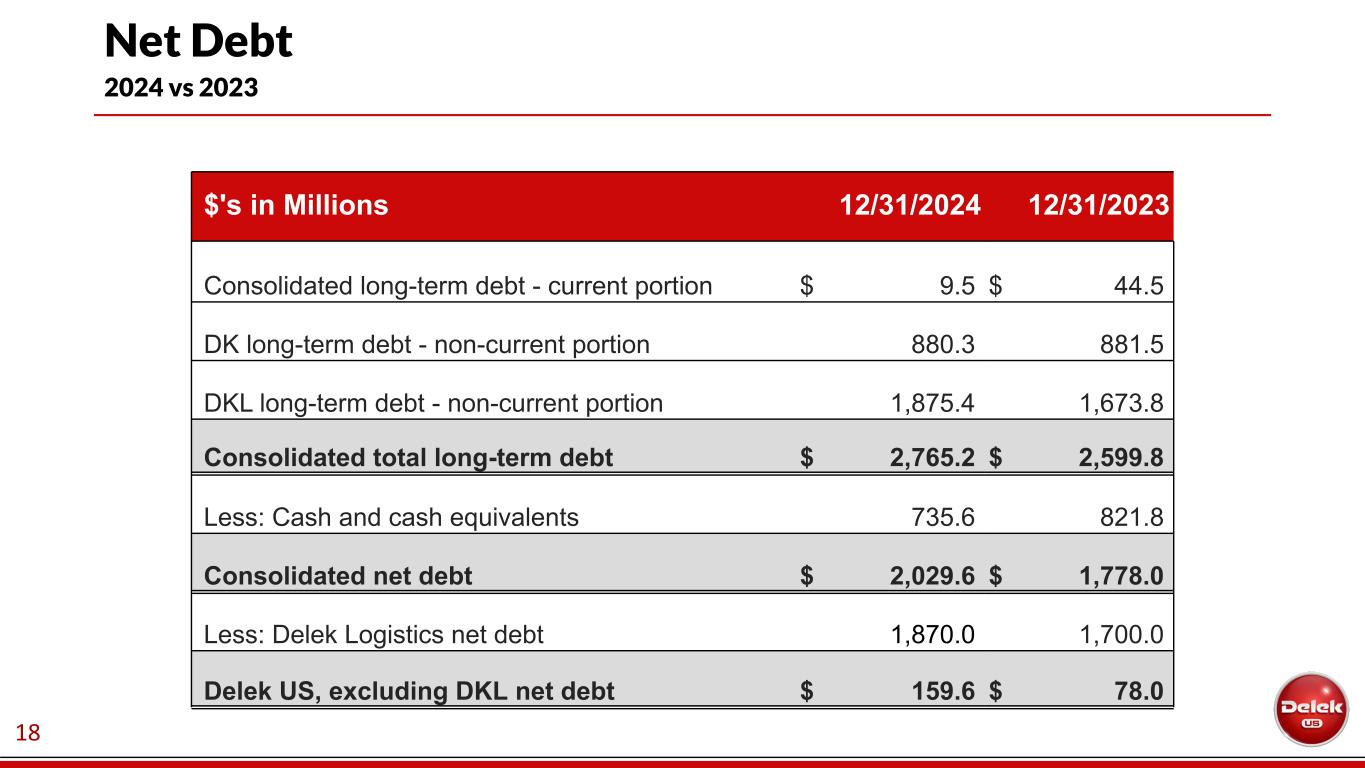
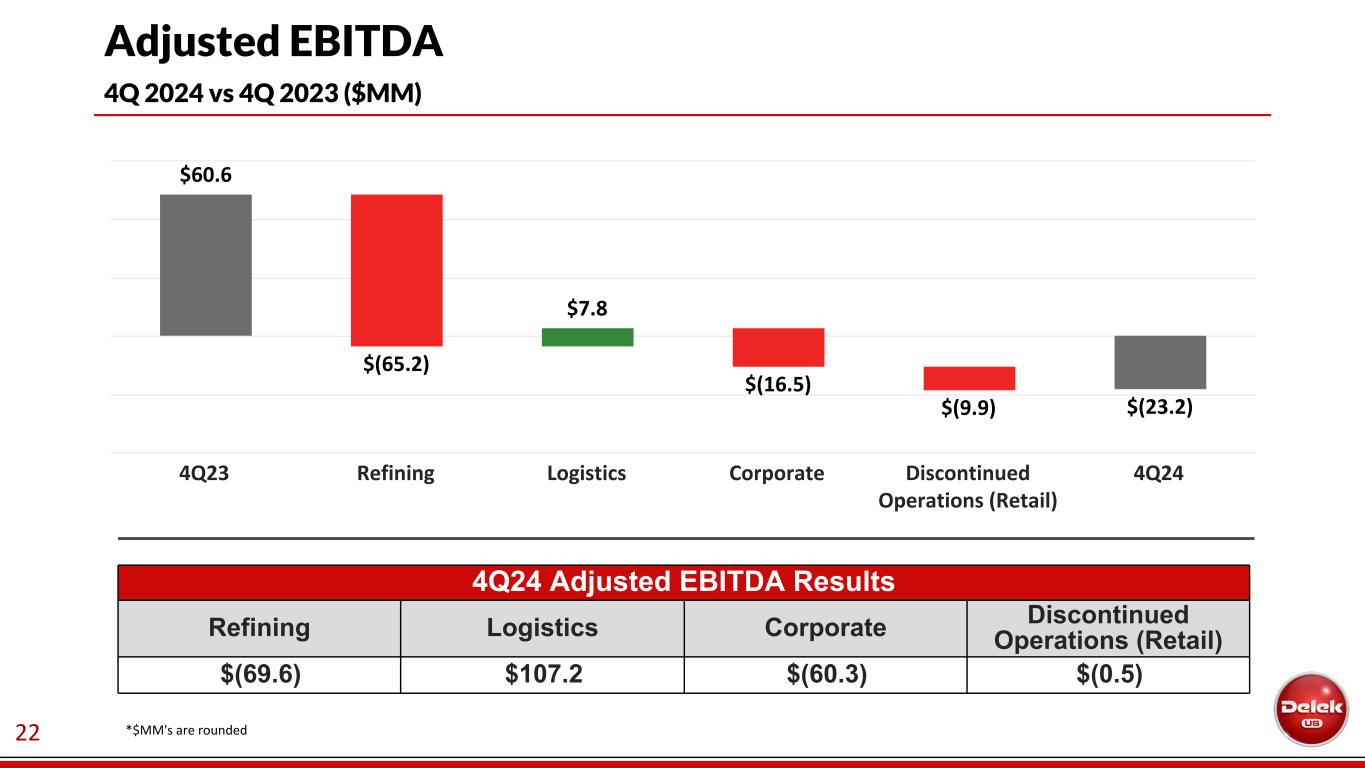
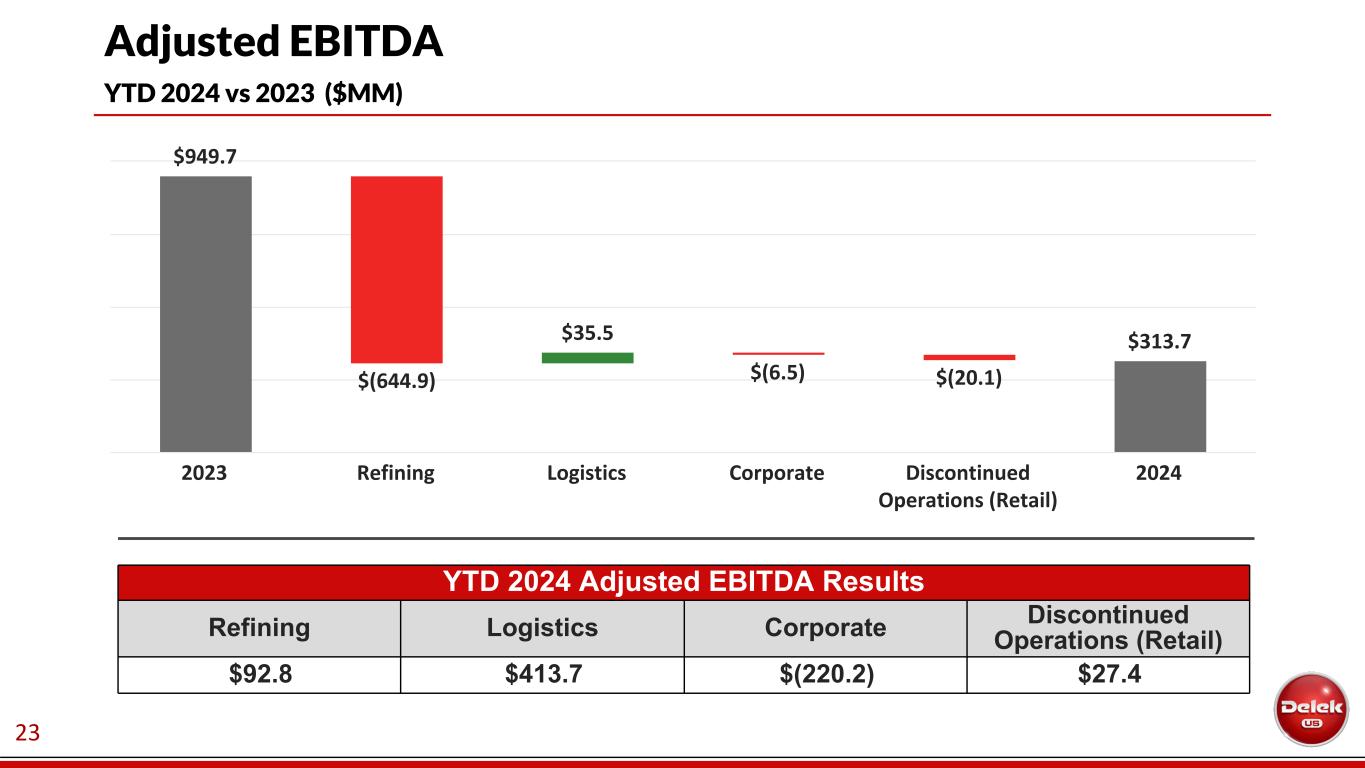
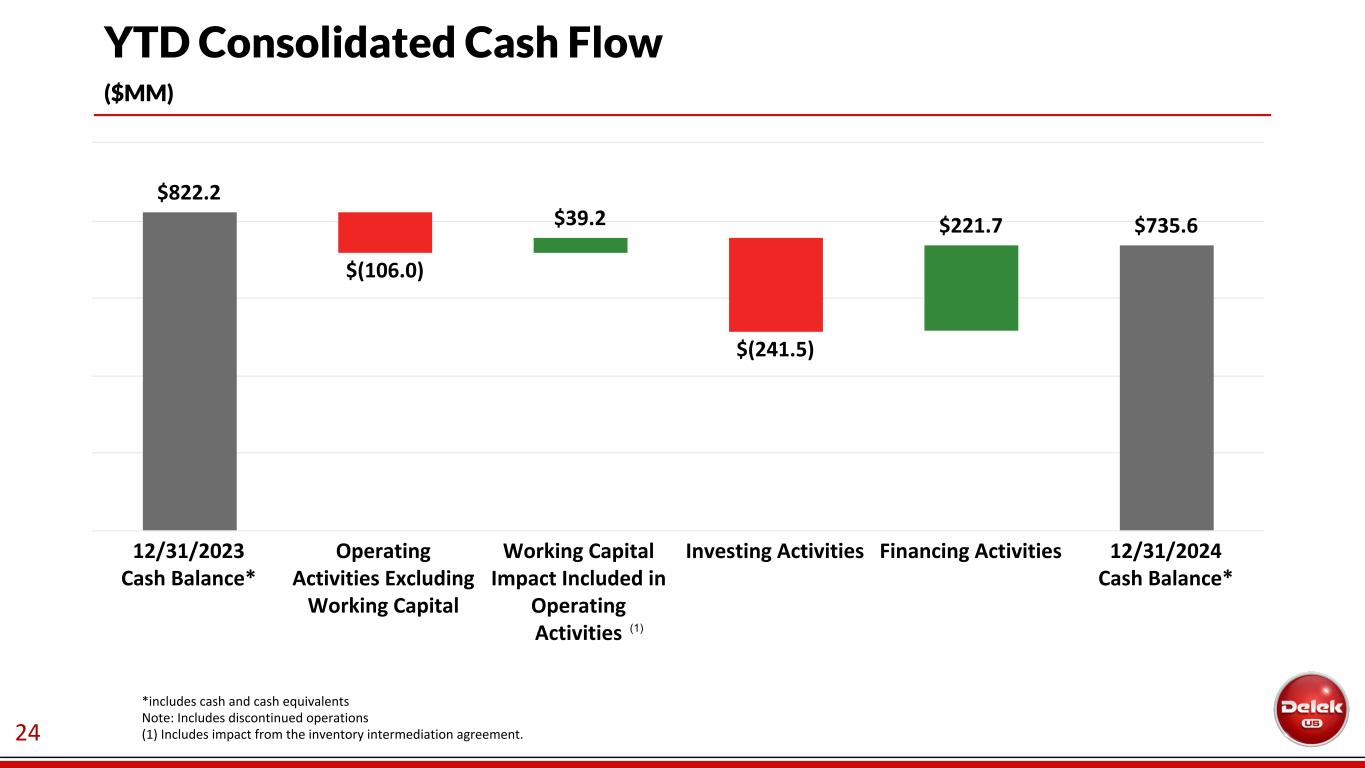
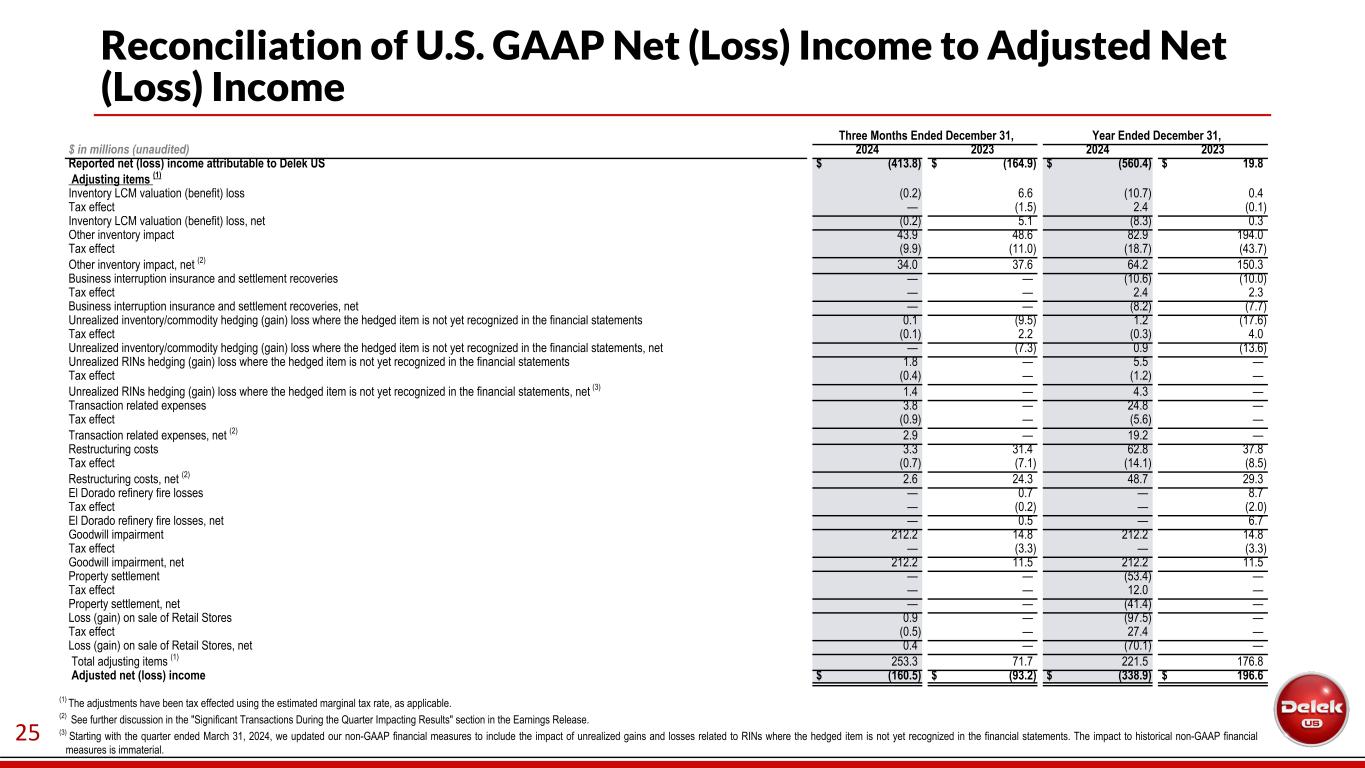
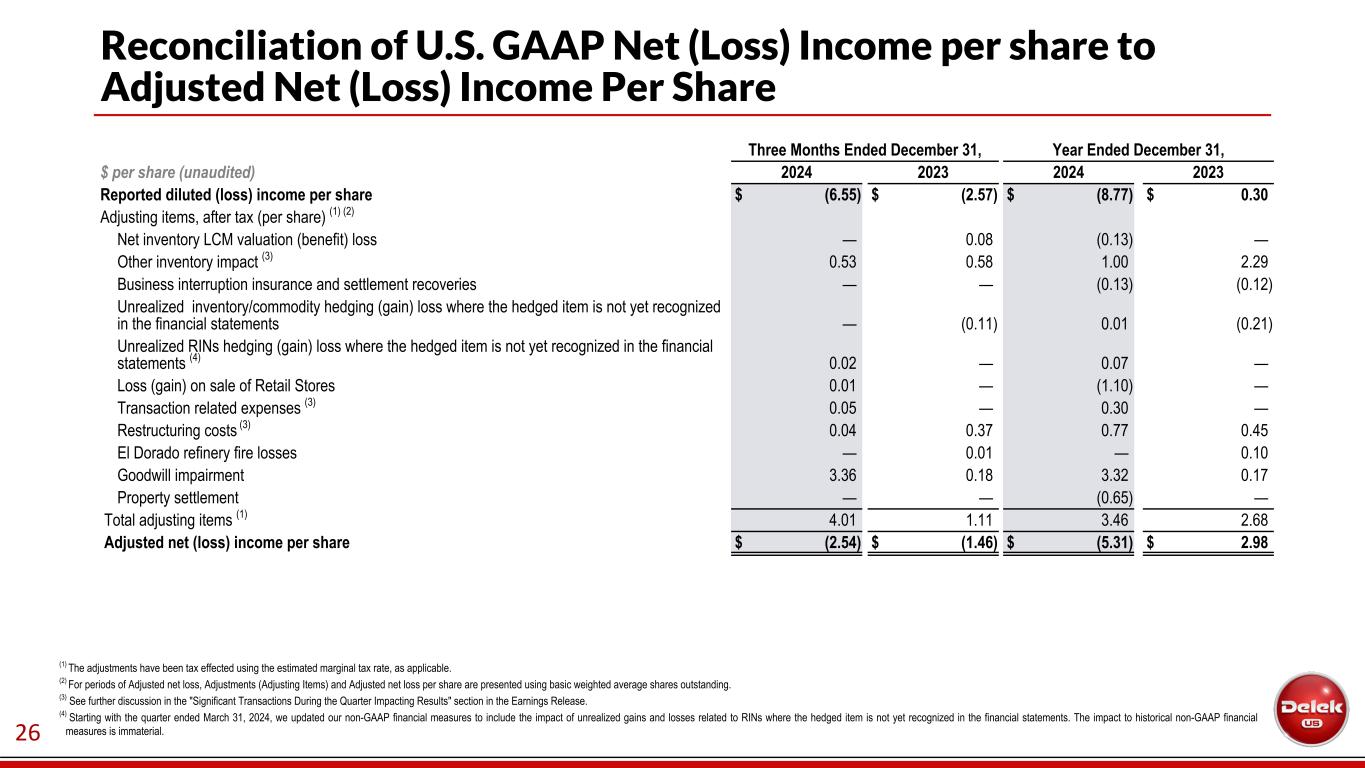
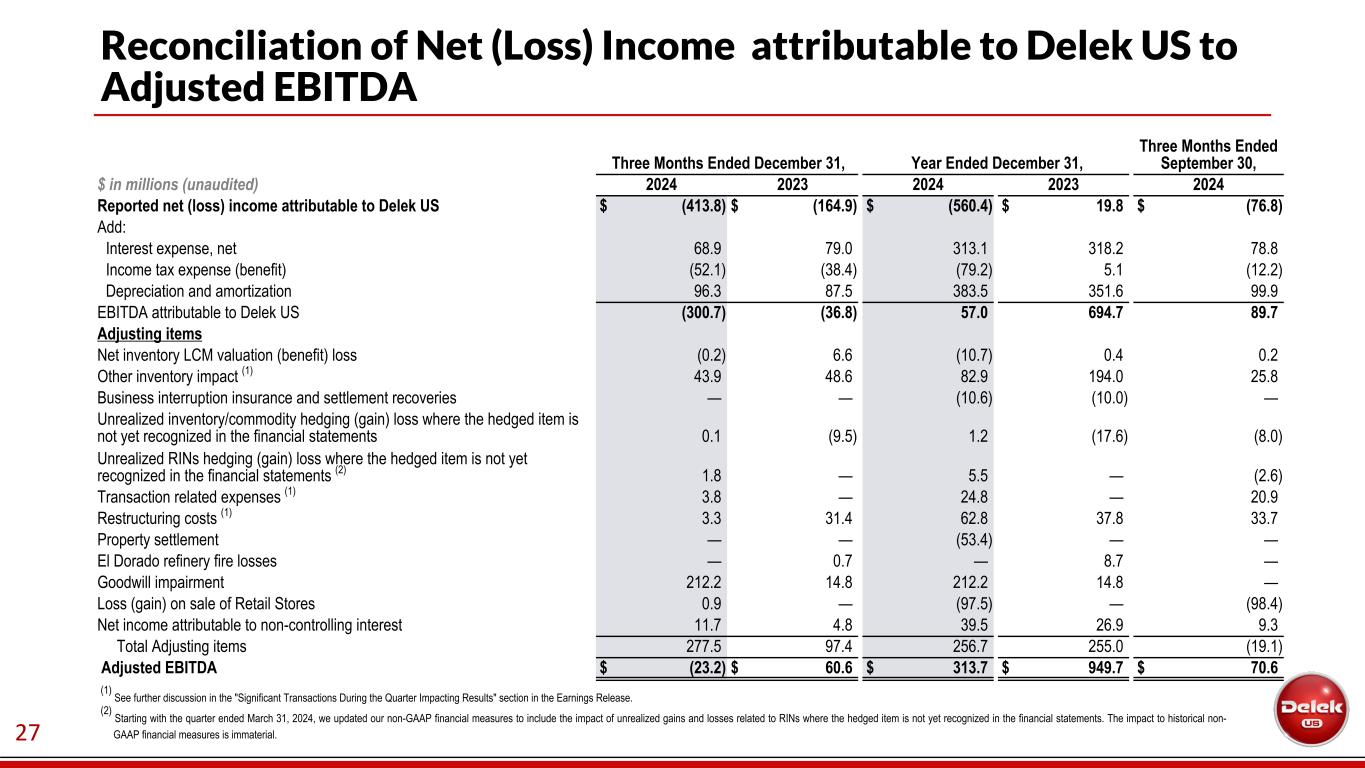
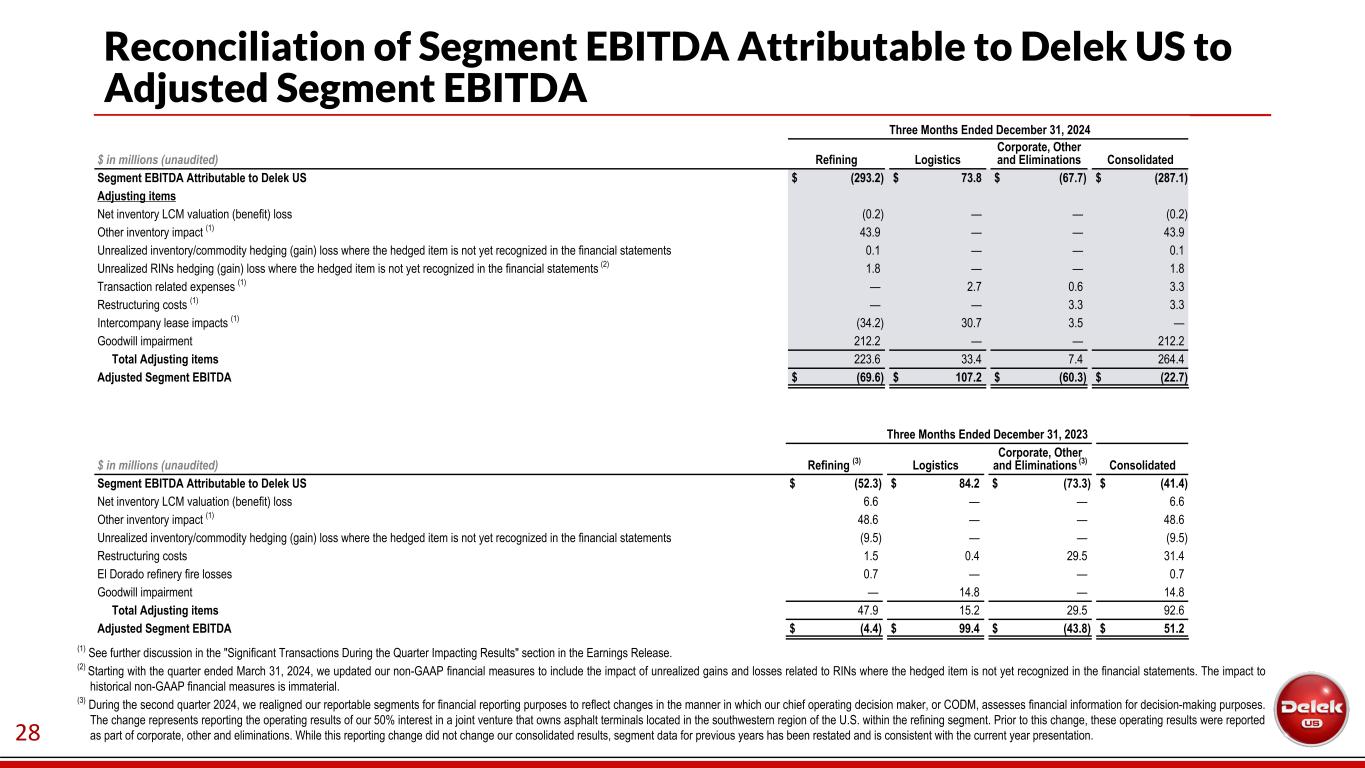
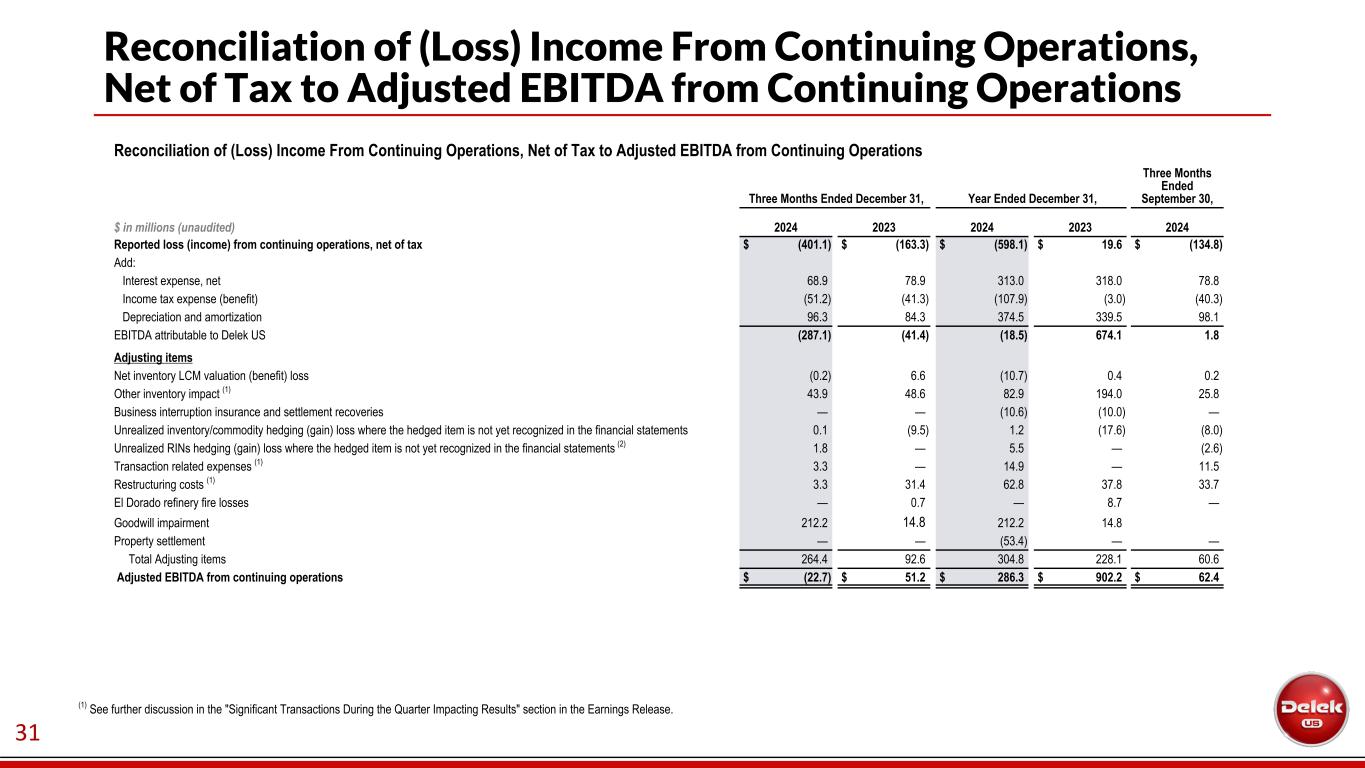
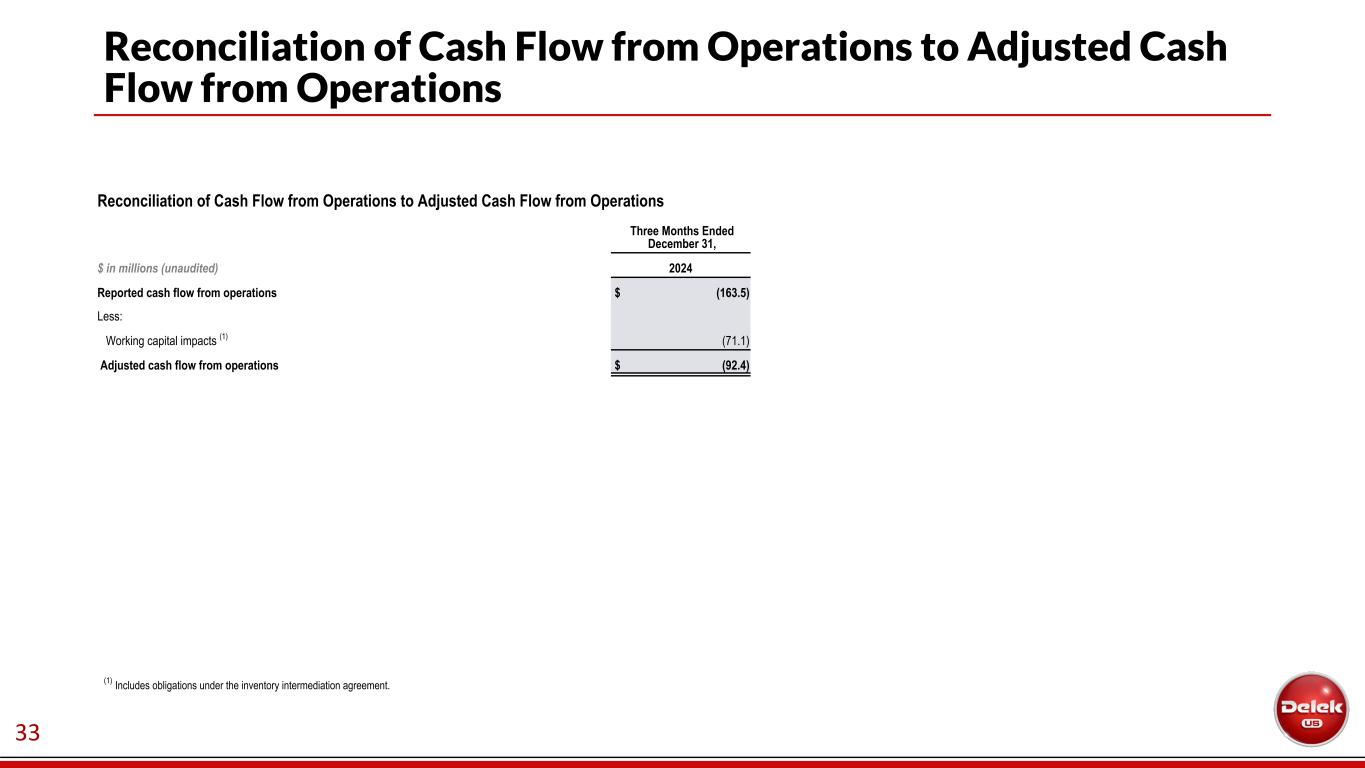
Thank you, Joseph. I will start by referring to slide 14. For the fourth quarter, Delic had a net loss of $414 million, or negative $6.55 per share. Included within this is a partial impairment of Goodwill balance of $212 million. Adjusted net loss was $161 million or negative $2.54 per share and adjusted EBITDA was a loss of $23 million. On slide 15, the waterfall of adjusted EBITDA from the third quarter of 2024 to the fourth quarter of 2024 shows that the decline is primarily because of lower refining contributions. The $80 million decrease in refining is primarily attributable to a lower margin environment in the fourth quarter relative to the third quarter. As to the logistics segment, we continue to have another strong quarter delivering $107 million in adjusted EBITDA. Moving to slide 16 to discuss cash flow. Cash flow from operations was a use of $164 million. Within this amount is our net loss for the period, in addition to an outflow of approximately $71 million of timing-related working capital movements, which include the impacts of the Inventory Intermediation Agreement. Investing activities of $216 million includes capital asset purchases of $191 million and a $23 million deposit paid for the Gravity acquisition which closed on January 2, 2025. Financing activities of $77 million reflects the DKL equity offering and timing of accruals. This also includes $22 million in share repurchases, $16 million in dividend payments, and $19 million in distribution payments. On slide 17, we have the actual results of the 2024 capital program. Fourth quarter capital expenditures were $198 million. $140 million of this spend was in the refining segment, a large portion of which was related to the successful completion of the KSR turnaround. The remaining amount is largely spend associated with the construction of the LV2 gas plant, which remains on track from a timing and cost perspective. As we have previously announced, our standalone DK capital outlook for 2025 is approximately $150 to $170 million. Our net cash position is broken out between Delec and Delec Logistics on Slide 18. During the quarter, we drew approximately $300 million of cash primarily due to anticipated capital expenditures on growth projects and the turnaround at KSR. Additional unfavorable impacts included working capital timing differences and the overall market conditions impacting our recognized EBITDA results for the period. Excluding Dellic Logistics, we finished the year with an increase of $82 million in net We are pleased with the relatively modest increase in net debt for the year, especially considering the broader market conditions and the impact on our peers, many of whom have experienced substantial increases. Moving now to slide 19, where we cover Outlook items. In addition to the guidance Joseph provided, for the first quarter of 2025, we expect operating expenses to be between 220 and 235 million dollars gna to be between 55 and 60 million dollars dna is expected to be between 100 and 105 million dollars and net interest expense to be between 78 and 88 million dollars we will now open the call for questions thank you the floor is now open for questions if you have dialed in and would like to ask a question please press star one on your telephone keypad to raise your hand and join the queue if you would like to withdraw your questions simply press star one again if you're called upon ask a question and are listening
via loudspeaker on your device please pick up your handset and ensure that your phone is not on mute when asking a question we do request for today's session that you please limit yourself to one question and one follow-up your first question comes from the line of manav gupta of ubs your line is open uh morning guys i wanted to focus on a little bit on slide 10 obviously you are making a lot of improvements in El Dorado, help us understand what more can be done to make this a truly competitive asset, something which can be performing in line with probably Tyler here, at least.
Yeah, Manav, good morning. Thank you for your question. El Dorado is a big focus for us. Joseph leading that with a lot of talent, and I will allow Joseph to chime in.
Yeah, the Eldo-Edo is the most significant beneficiary of our EOP focus on the product mix. We started to make and sell jet fuel through the rack. We are looking to convert heavy bottoms to light products. Process efficiency, we are focused on liquid yield recovery, mainly in the reformer, FCC, and asphalt areas. On the logistics front, we put together new logistics, and we are already shipping more products away from the local market to optimize their netbacks. Bottom line, Munaf, considering our strong refinery team out there, the asset flexibility, and the $50 million of low-hanging fruits, we are confident about our ability to translate this progress to numbers sooner than later.
Perfect, guys. Quick follow-up here is, looks like you're growing DKL, EBITDA, although you're divesting it down slowly. It's a strategy here to look for smaller boton deals, whether it's water, crude, gas, and basically continue to grow the company at the DKL level, and at the same time, try and bring down the ownership below 50%.
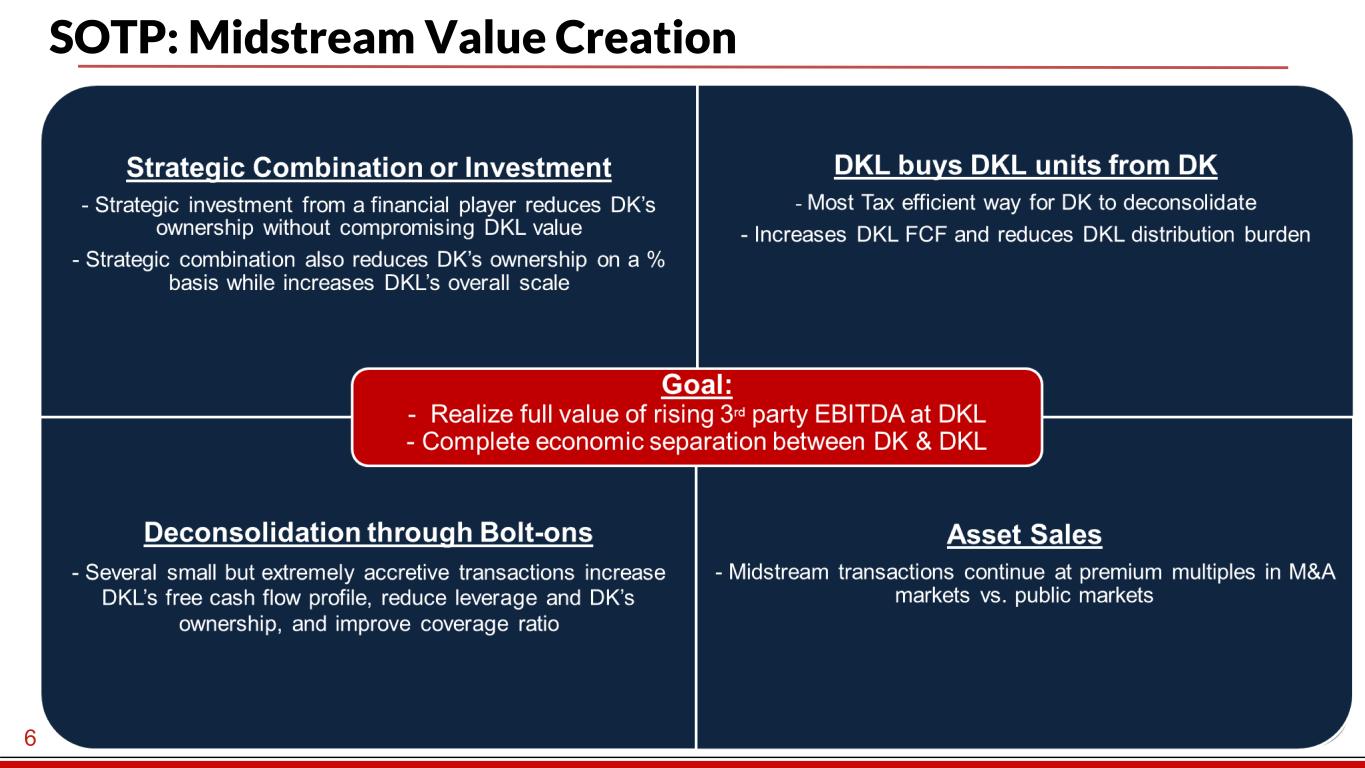
Yeah, so Manav, I will take that question. And I would like to give you a bigger answer than that about some of the part effort we are doing. And some of the parts, together with EOP, are the most strategic initiative we have for this year, right? And deconsolidation, I want to make it crystal clear, is happening and will happen as we speak. So it's very, very clear. And I want to take a moment and reflect on 2024 action that we did around it, right? So in 2024, we sold retail as we wanted. We continue to make progress in the deconsolidation, right? We took the ownership of us from 79 to below 64% today. We grew the EBITDA while we are doing all of that from 385 not very long ago to over 400 this year, the 2024 to 500 guidance for 2025, which is another step. And we increased the third-party EBITDA from 40% to 70%. Manav, while we were doing all of that, we also increased the distribution that DK gets from DKL. So it's many, many, many boxes that we are checking the box on. And today, I don't know if you noticed, we announced another efficient tool in our toolbox to allow basically efficient tax way for DK to sell back their units to DKL. So we announced it today for $150 million, up to $150 million. So the other, and that's benefit for DKL for the efficient way, and it's also benefit for DKL because of free cash flow, right? You're Boeing at 7, you're Boeing at 7, and you're avoiding a cost of 10 or 11. So that's very beneficial for both companies. And the last point I want to make, that the deconcidation is the goal of both companies because it will allow DKL to grow over time and then allow DKL to get the whole value in the asset. With that said, Mark was very busy this year with all the deals we had. And the plan is that he was going to be very busy in 2025 as well. So I'll let Mark chime in.
Yeah, thanks, Abigail. We're very happy with our sum-of-the-parts efforts in 2024, and we're very active in the year in advancing our deconsolidation efforts. Both H2O and Gravity checked all the boxes and what we look at for acquisitions. Highly strategic and highly synergistic with our Midland Basin operations and what we're trying to do out there as a full-service midstream provider. immediately accrued to free cash flow, improved our leverage, and increased our coverage ratio. We also initiated organic growth projects in the Delaware to add to our gas processing capacity and to also add critical sour gas capabilities. And finally, we dropped down Wink to Webster, our 15% interest in Wink to Webster. And when you take all of those combined, we're adding significant third-party EBITDA to DKL, which is driving this economic separation between DK and DECAL that we're talking about. If you layer on top of that, we also continue to see premium valuations paid in the private markets by midstream companies for midstream assets over the past few months. And in particular, those tied to the Permian Basin, which, as you know, is the core of our DECAL operations. And as Avogol said, our focus is that we're going to continue our measured approach to deconsolidation. And the focus is going to continue on enhancing and maximizing value for both DK shareholders and decal unit holders.
Operator
Your next question comes from a line of Matthew Blair of TPH. Your line is open.
Thank you, and good morning. I was hoping you could go into the supply and marketing dynamics a little bit more in the fourth quarter. I understand there's some seasonality with wholesale, but could you help us understand why is that just an outright negative EBITDA contribution, and does there need to be any structural changes there? And then how are are these supply and marketing dynamics trending so far in the first quarter?
Hey, good morning. Thank you for the question. First of all, I'm very happy on the progress that DKTS are doing. If you are comparing that to the fourth quarter of last year, the market condition back then was better versus this quarter. But DKTS achieved $10 million better this quarter versus last quarter. So that's a very good step on the right direction. And I will let Pat Riley, our chief commercial officer, to chime in into that answer and give you some color.
Thank you, Avigol. Fourth quarter DKTS performance was impacted primarily by seasonal inland demand weakness led by the group and a one-time major turnaround across. With that said, DKTS made significant progress on our 2024 initiatives. As Avigol just mentioned, supply and trading market conditions in Q4 was significantly weaker. relative to the same time period in 2023 so as an example group diesel weakened by 14 cents per gallon that's almost six dollars a barrel year on year now despite these headwinds dkts outperformed fourth quarter 2023 by nearly 10 million dollars dkts will play a crucial role in the delivery of the 2025 eop and our strategy is actually simple to intelligently streamline operations thereby reducing costs, further increase our margins on the back of optimization of supply and trading, lean into our partnership with our assets to flex our broader product offering, and further mature to ETS's newfound and expanded market reach. We're excited for the commitment and the challenge.
And then on the RD side, have you made a decision on whether to invest in the bakersfield uh renewable diesel plant yeah that's not on our table these 10 seconds if something changed we'll definitely let you know but it's not and maybe mohi you want to chime in on that yeah matt uh that option is still available to us uh as you and i have discussed in the past um the team over there has to show that they have had healthy operations for around three months and then we have around 90 days to exercise our option and we are obviously going to be looking at it once we are asked to look at that option but as of right now that option is still available to us and we're just hoping for the team to have those operations in order before we start making our decisions sounds good thank you your next question comes from line of john royal of jp morgan your line is open hi good morning thanks for taking my question So my first question is on the OPEX guide for 1Q.
We noticed a step up from where you had guided to 4Q, but it's also in the context of things going well with EOP. So I was hoping you could help us bridge the difference and maybe how should we think about that OPEX number as we progress further into 2025 beyond that 1Q guide.
Absolutely, John. Thank you for the question. Mohit was putting the guidance together, so I will let him chime in. Please, Mohit.
Yeah, John, thanks for the question. So as far as our company is concerned, OPEX and cost reduction, we are taking a lot of pride in it. And you know, you're seeing the results through EOP. You have seen the results through ZBB. As far as your specific question around Q1 guidance is concerned, so there are four factors which are influencing the guidance. The first one is, as you know, that we closed gravity, water, midstream, and you're presenting the guidance on a consolidated basis. So you're seeing some OPEX coming from gravity water midstream. Second, we are running higher throughput quarter over quarter. So that's also influencing our OPEX number. Third piece is natural gas. As you've seen, natural gas prices have gone a little bit higher. So that's also influencing our OPEX numbers. And finally, we have some planned maintenance at Big Spring in 1Q, which is reflected in our throughput guidance. So that is also impacting our overall OPEX. But as I started my answer, OPEX and cost reduction is an extremely positive story for We're very excited about how OPEX reductions are contributing to EOP and our free cash flow And we look forward to updating you guys more on that.
Great. Thanks, Mohit. And then my follow-up is another one on guidance, maybe just on the DKL EBITDA guidance. just trying to bridge from the run rate of about I think it's about 430 million annually in 4q to this guy that's about 50 to 90 million above that if you could just walk us through some of those moving pieces I know obviously there's gravity there's the gas plant coming on mid-year you know maybe some other things on the organic side just a little bit of detail on how you get from the 430 to 480 to 520.
Yeah absolutely so first of all John we need to take a step back and talk about the D.K.L. in a broader context. D.K.L. is a growing story. And obviously, as we speak, we are increasing the economical separation between the companies. And we are doing that very methodically and to benefit both unitholder and shareholder as you see by all the action that we have done in the last 18 months or so. That's very, very important. We decided to allow you guys to have guidance for D.K.L. because we want everyone to model that company right and to be able to understand the value creation that was done here. So we're taking a lot of pride of what we are doing here. We think the guidance we gave you is solid and good. And Mohit, do you want to chime into that as well? If there is more modeling questions, we can take it offline, obviously.
Speaker 0
Yeah, I think, Abigail, you covered most of it, but, John, I can definitely help you walk through the moving pieces you know we can do a one-on-one call after this so maybe we should take that offline thank you thank you your next question comes from the line of Doug Leggett of Wolf Research your line is open hi this is McKinley all for Doug he's traveling at the moment my first question kind of a piggyback saw in some of the commentary that's already been had in addition to the EOP you guys have quite a a few options in terms of being able to release value from DKL. Where are you in the process, for example, with the solid gas permitting? And is there a kind of line of sight on potentially other sellable assets going forward?
Yeah, so you started your question with the EOP. So I will start my answer with the EOP. And I will give you some more broader context around that. So especially on the refinery environment that we are at, EOP is all about free cash flow, period, end of story. That's what we are after, right? We obviously today is a happy day around that because we felt comfortable enough to take our guidance towards the end of the range we gave in the past. So that's a happy moment for us. We have seen a significant progress on the cost side already been signed and we will see them executed and coming to fruition over the next few months. And as Pat mentioned, we see a good progress also on the margin improvement that we see on EOP. But I want to ensure you that we are not stopping here. We are not standing still. We always have more options and more things that we are working on and adding to that very important initiative. And we are very optimistic about that. The last comment I want to make is that it's pretty neutral to market condition, and all the actions that we are doing here are new actions that were not done in the past. So we are very optimistic, and Ruben is very close to that and helped manage that very nicely, and I will let him chime in on that.
Thank you, Avigal. So the EOP plan includes a bank of projects from all areas of the company, and I will address specifically your question about D.K.L. at the end. And each project has to be validated two ways, one, that it's sustainable, and two, that is, for the most part, market agnostic. Once vetted, it goes into execution and added to the projections. You can see on the deck that we're provided, it's reflected in slide nine in the green boxes. Each project has a different timeframe for each, and that is why we're measuring third and fourth quarter run rates. As for DKL, we have the sour gas plant, which our team is executing on time, on budget, and it's expected to flow in the second quarter. And that gives us a whole new dimension and flexibility around gas.
Operator
Thank you. Your next question comes from the line of Jason Gabelman of TD Kellan. Your line is open.
Hey, morning. Thanks for taking my question.
Hey, Jason. Thanks for joining us today. i wanted to ask about the dkl repurchase program of dk units i'm wondering one what the what the timeline is to deploy that uh buyback cash and two once once dk gets that cash what what it's going to use that cash for yeah thank you for the question um the timeline that we put that program in is all the way until 2026 obviously it's a dkl option but we are very close to that so we do that when time is right, but you probably can appreciate that that's another tool in our toolbox that benefits the deconsolidation for both companies and helps free cash flow of both companies. So that checks many, many boxes. And it's very tax efficient. I think you can be proud of a very creative way how to create deconsolidation with no tax impact, basically. But I want to take the other part and to talk about the capital allocation program we have. and I want to give a broader discussion around that. So we said many times and we are saying that today that we are maintaining dividends toward the cycle. We are doing that, we've done that and we will do it in the future. And then we have a balanced approach between taking care of the balance sheet and buyback. We did buyback in Q3, we did buyback in Q4 and we are doing buyback at Q1 of 2025. At the current valuation of our share price, we see a huge value in our share price, and we are acting on that, just to make it very clear. So that's kind of where we are.
Great. Yeah, I appreciate the color on the capital allocation. The other question is just back to Group 3 dynamics. And it sounds like in a weaker inland margin environment, you see some weakness in that supply line item. And I wonder, you know, kind of post COVID, we've seen inland markets become more seasonal, where they're weaker in the winter. So should we expect that that supply line is weaker in 4Q and 1Q kind of in line where it was this past quarter, or maybe I guess a little better based on what's going on in the EOP program?
Or I guess, how should we think about the seasonality of that supply line? thanks yeah so listen there are two different questions here market observation there is some truth that there is a weakness in the winter and strength in the summer but i'm not going to provide we are not going to provide the guidance for dkts we didn't do that in the past and i don't think it's a it's best practice in the market we are not going to deviate from that today but i'm going to tell you and jason you need to know that very well that we are moving very well with the things that we are controlling like different products that we are start moving and different market that we are moving towards and I can be only very pleased with the progress we are doing about what we can control so and I will leave it to that okay understood thanks for the answers but that concludes our Q&A session I will now turn the conference back over to Avigal Sorek for closing remarks yeah so i would like to thank my colleagues around the table um for a great uh safe and reliable here i want to thank the entire delic employees for a great execution and a great commitment for the company and i'm very pleased with that to thank our board of directors and to thank you investors for believing in our story and our journey with that i would conclude the call and we'll see you next in the next quarter.
Operator
This concludes today's conference call. You may now disconnect.